
 Sub-Micrometer Computed Tomography Market | 2026-2036
Sub-Micrometer Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Sub-Micrometer Computed Tomography Market Insights
Direct sales and OEM partnerships for sub-micrometer CT systems is fragmenting as specialized distributors and digital procurement platforms gain ground in Asia-Pacific and European markets. Bruker Corporation leverages its installed base in materials science to sustain recurring service revenue across university laboratories. Thermo Fisher Scientific anchors its position through integrated workflows that bundle imaging with analytical chemistry instruments. Carl Zeiss AG competes on optical heritage and tight tolerances in semiconductor metrology applications.
Sub-micrometer computed tomography captures three-dimensional internal structures at resolutions below one micron using X-ray or synchrotron sources, enabling non-destructive analysis of pore networks, fiber orientations, and micro-crack propagation in engineered materials. Laboratory systems dominate current installations due to their controlled environments and higher throughput for academic research, while industrial systems gain traction in automated inline quality control where manufacturers demand cycle-time reduction. Synchrotron radiation technology leads in resolution performance but occupies niche facilities, whereas cone beam computed tomography extends accessibility to mid-tier manufacturing plants.
FDA oversight shapes biomedical imaging deployments through 21 CFR Part 820 quality system requirements, while ISO 17025 accreditation dictates calibration protocols for laboratories serving regulated industries. The EU AI Act and MDR framework increasingly govern automated defect-classification algorithms embedded in industrial CT software. REACH compliance affects X-ray target materials and detector scintillator chemistries, forcing suppliers to reformulate components. Stakeholders must weigh capital intensity against the operational shift from destructive testing to fully non-destructive validation protocols.
Market Dynamics
Semiconductor packaging inspection requirements are compressing measurement tolerances below 500 nanometers, forcing equipment suppliers to synchronize X-ray source stability with detector pixel pitch advances.
Growth Catalysts
- EU AI Act compliance:Automated defect-classification algorithms in industrial CT software now require conformity assessment, creating upgrade cycles for installed base systems.
- Fraunhofer institute networks:Germany's applied research infrastructure concentrates validation demand for sub-micrometer CT in precision manufacturing clusters.
- Synchrotron radiation facilities:Third-generation light sources in France and Switzerland extend resolution frontiers for academic materials science, pulling laboratory system specifications upward.
Market Restraints
- Tungsten target supply:REACH restrictions on heavy metal chemistries constrain X-ray source component sourcing from Chinese refiners.
- Detector scintillator concentration:Cesium iodide and gadolinium oxysulfide production clusters in Japan create single-source vulnerability for high-resolution flat panels.
- Calibration infrastructure:ISO 17025-accredited laboratories remain geographically sparse outside Germany, the United Kingdom, and the United States.
Strategic Opportunities
- Battery electrode inspection:Solid-state lithium-metal anode development in South Korea requires non-destructive porosity mapping at sub-micron resolution.
- Additive manufacturing certification:FAA and EASA qualification pathways for flight-critical printed parts mandate CT-based pore network validation.
- Digital procurement platforms:Specialized distributors in Singapore and the Netherlands are consolidating mid-tier manufacturing demand through configuration-as-a-service models.
Industry Challenges
- Metrology technician scarcity:Cross-disciplinary expertise combining X-ray physics, reconstruction algorithms, and materials science outpaces university pipeline output.
- Legacy system integration:MES and QMS software from 1990s-era semiconductor fabs lacks API compatibility with modern CT automation protocols.
- Patent thickets:Iterative reconstruction algorithm licensing from university technology transfer offices fragments software development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sub-Micrometer Computed Tomography Market |
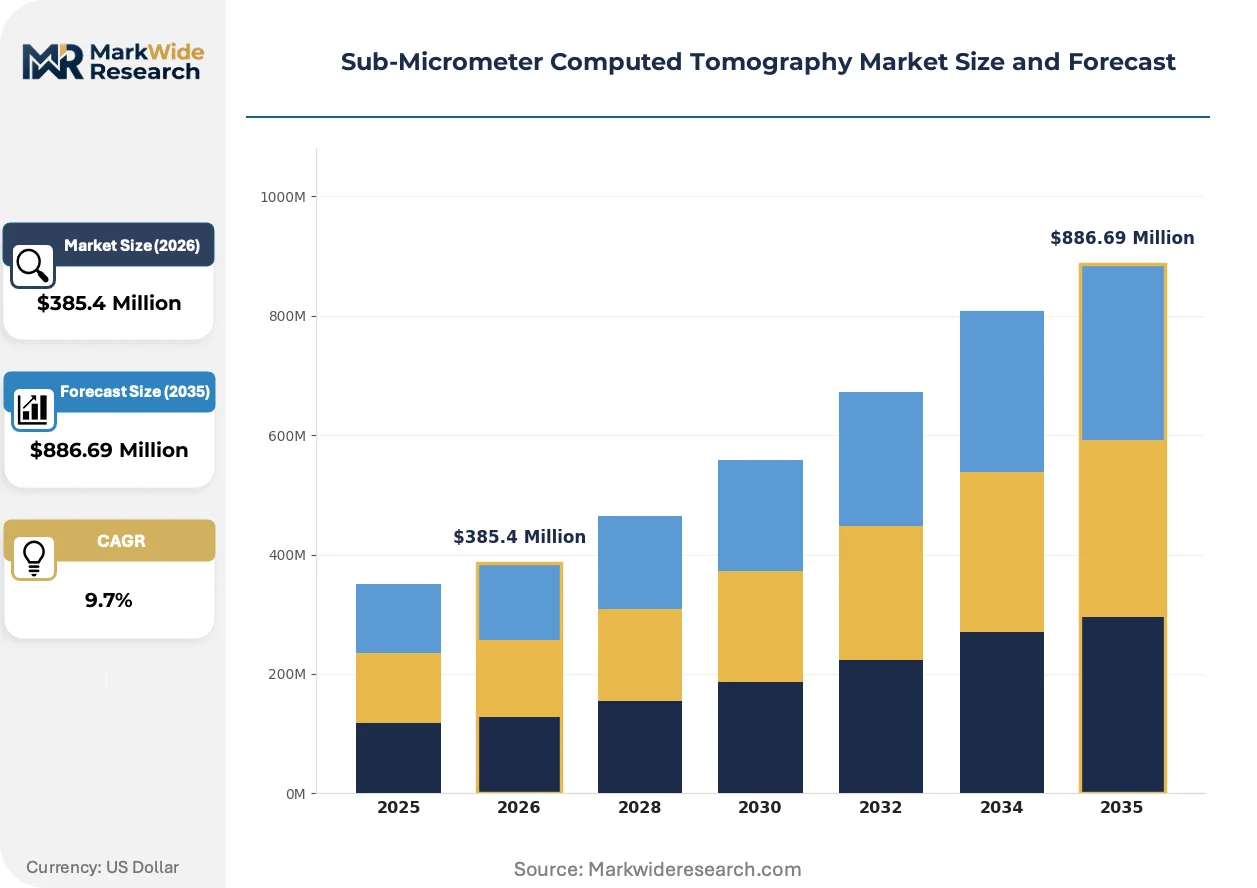
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Systems, Industrial Systems, Portable Systems, Customized Solutions Application: Material Science, Biomedical Imaging, Quality Control, Reverse Engineering Technology: X-ray Tomography, Cone Beam Computed Tomography, Synchrotron Radiation, Optical Coherence Tomography End User: Research Institutions, Manufacturing Plants, Healthcare Providers, Academic Laboratories |
| Companies Covered | Bruker Corporation, PerkinElmer Inc., Thermo Fisher Scientific, Carl Zeiss AG, SCANCO Medical AG, RX Solutions, Nanoscribe, North Star Imaging Inc., Sanying Precision Instruments Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sub-Micrometer Computed Tomography Market Trends and Innovations
Phase-contrast imaging techniques are penetrating industrial applications previously reserved for synchrotron facilities, compressing the resolution-accessibility frontier for mid-tier manufacturers.
Grating-based phase-contrast CT is digitizing soft-tissue visualization in biomedical implants without staining protocols. Medical device manufacturers in Switzerland and Massachusetts are piloting inline systems for hydrogel scaffold inspection. The technology is digitizing quality control workflows that previously required destructive histology, collapsing analysis cycles from weeks to hours.
REACH authorization timelines for cadmium-based scintillator alternatives are forcing detector suppliers to reformulate europium-doped compositions. ECHA's 2024 substance evaluation wave specifically targets heavy metal persistence in imaging equipment. German and Dutch component manufacturers are accelerating ceramic scintillator development to preempt supply discontinuities.
Buyers in automotive and aerospace verticals are unbundling service contracts from hardware procurement, demanding à-la-carte calibration and reconstruction software subscriptions. Specialized distributors in the Asia-Pacific region are capturing this demand through usage-based pricing models. South Korean battery manufacturers represent the most aggressive adopters of this procurement pattern, separating capital expenditure from operational technology budgets.
Sub-Micrometer Computed Tomography Market Segmentation
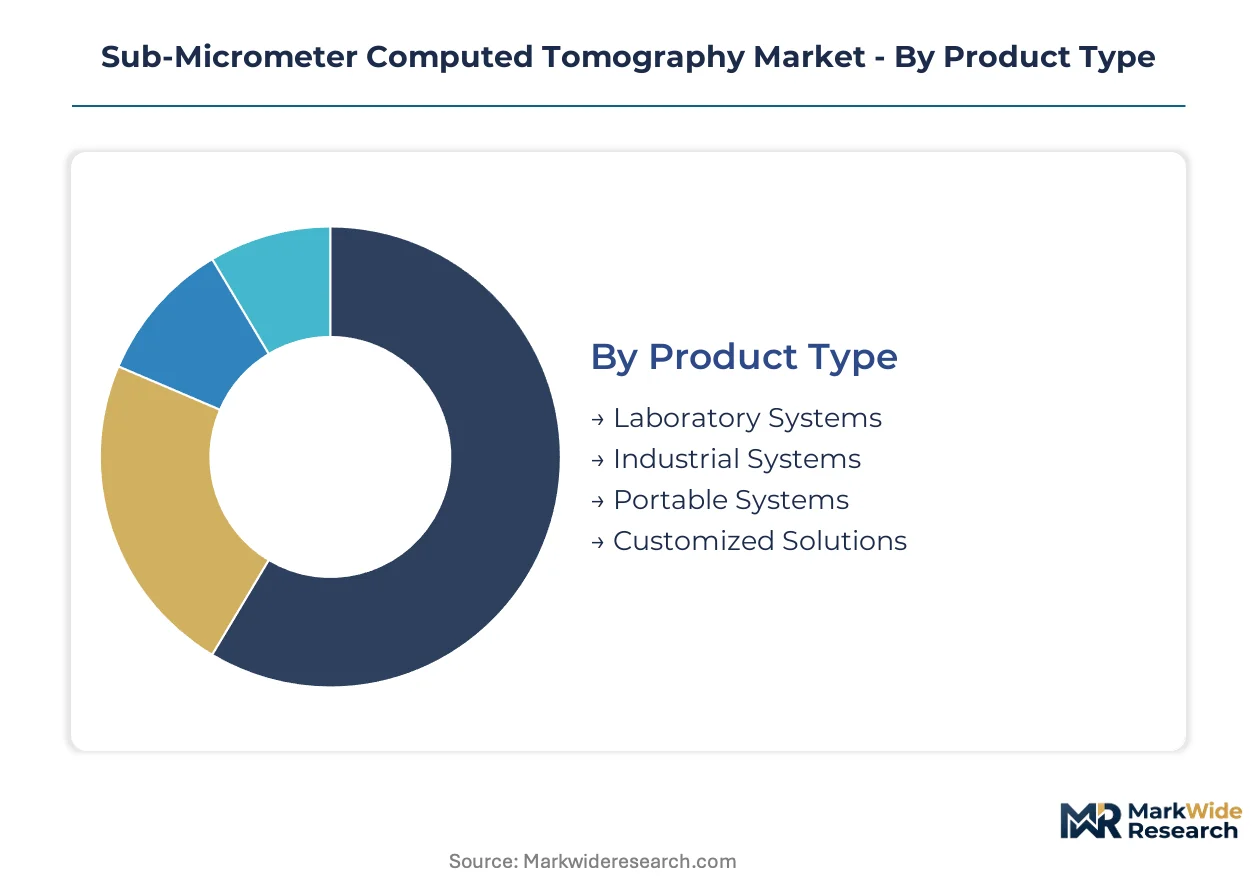
Sub-micrometer CT equipment fragments across deployment contexts, resolution requirements, and operational environments. Each segmentation axis reveals distinct procurement patterns, calibration protocols, and service attachment rates that shape vendor strategy and distributor economics.
Product Type:
Mature installations cluster in controlled laboratory settings, while emerging formats target mobility and application-specific customization.
- Laboratory Systems:Fixed installations with environmental isolation chambers deliver sub-500 nanometer resolution for academic materials science. Demand concentrates in Fraunhofer institute networks and Swiss federal technology institutes where ISO 17025 accreditation mandates traceable measurement chains.
- Industrial Systems:Automated inline configurations integrate with semiconductor fab MES layers for wafer-level packaging inspection. South Korean battery electrode manufacturers and German automotive suppliers drive specification tightening for cycle-time reduction below 90 seconds per scan.
- Portable Systems:Compact gantry designs with battery-powered X-ray sources serve field archaeology and pipeline integrity assessment.
- Customized Solutions:Bespoke detector arrays and source configurations address synchrotron beamline integration and specialized biomedical scaffold inspection.
Laboratory Systems retain volume leadership; Industrial Systems hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive research workflows from operational quality control budgets.
- Material Science:Pore network characterization in additive manufacturing feedstocks and fiber orientation mapping in composites dominate academic procurement. Oak Ridge National Laboratory and ETH Zurich operate multiple systems for multiscale mechanical behavior studies.
- Biomedical Imaging:Phase-contrast techniques visualize soft-tissue scaffolds without staining. Swiss medical device manufacturers pilot inline hydrogel inspection to replace destructive histology protocols.
- Quality Control:Automated defect classification in semiconductor packaging compresses measurement tolerances below 500 nanometers.
- Reverse Engineering:Legacy component digitization for aerospace spares reproduction leverages archival scan data repositories.
Material Science commands the highest average selling prices; Quality Control is expanding most quickly.
Technology:
Resolution performance and facility infrastructure requirements create distinct customer access tiers.
- X-ray Tomography:Sealed microfocus tubes with tungsten targets serve routine laboratory inspection. REACH authorization pressures on heavy metal chemistries force supplier reformulation of target materials.
- Cone Beam Computed Tomography:Flat-panel detector architectures extend sub-micron accessibility to mid-tier manufacturing plants. Japanese cesium iodide scintillator supply concentration creates single-source vulnerability.
- Synchrotron Radiation:Third-generation light sources at ESRF in France and PSI in Switzerland deliver coherent illumination for phase-contrast frontiers.
- Optical Coherence Tomography:Near-infrared interferometry addresses transparent material inspection without ionizing radiation.
Cone Beam Computed Tomography retains volume leadership; Synchrotron Radiation holds the steepest expansion curve.
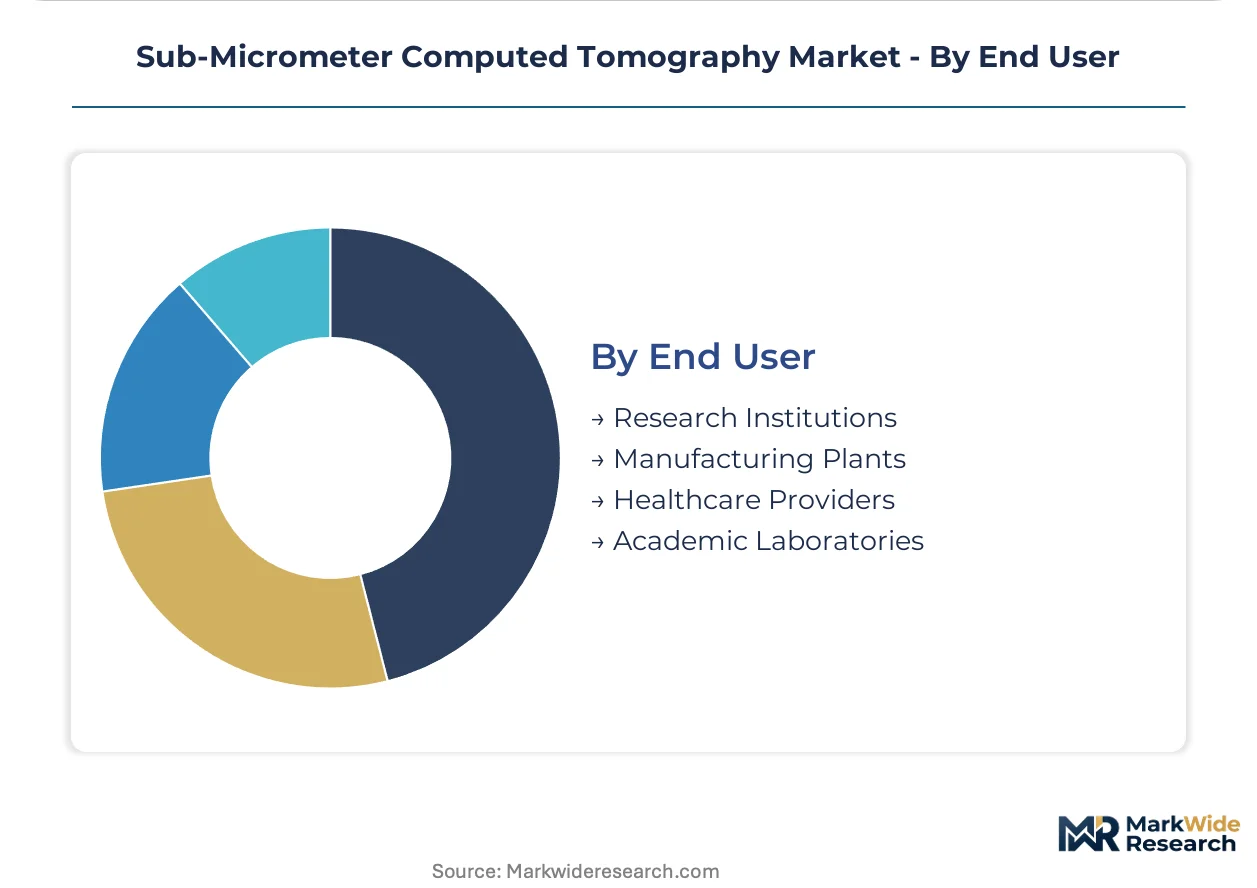
End User:
Customer type determines procurement authority, service contract structure, and software customization depth.
- Research Institutions:National laboratories and federal technology institutes prioritize resolution specifications and reconstruction algorithm access. Grant-funded acquisitions favor vendors with university technology transfer partnerships.
- Manufacturing Plants:Semiconductor fabs and battery cell producers demand API-compatible automation and predictive maintenance integration. South Korean manufacturers aggressively unbundle service contracts from hardware.
- Healthcare Providers:Hospital radiology departments and medical device manufacturers navigate FDA 21 CFR Part 820 and EU MDR quality system requirements.
- Academic Laboratories:University materials science departments balance capital constraints against publication-grade imaging requirements.
Research Institutions retain volume leadership; Manufacturing Plants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Diamond Light Source synchrotron facility near Oxford anchors the United Kingdom's position in high-resolution materials characterization, while the country's dense concentration of ISO 17025-accredited calibration laboratories supports metrology-intensive manufacturing sectors.
Germany
Fraunhofer institute networks concentrate validation demand for sub-micrometer CT systems across precision manufacturing clusters in Bavaria and Baden-Württemberg. The EU AI Act's conformity assessment requirements for automated defect-classification algorithms are accelerating upgrade cycles for installed industrial systems. Stuttgart and Munich host the densest concentrations of semiconductor packaging inspection facilities demanding sub-500 nanometer measurement tolerances.
United States
Oak Ridge National Laboratory's multiple system installations for multiscale mechanical behavior studies anchor academic materials science demand. FDA 21 CFR Part 820 quality system requirements shape biomedical imaging deployments through rigorous calibration protocols. Massachusetts medical device manufacturers pilot inline phase-contrast systems for hydrogel scaffold inspection to replace destructive histology workflows.
South Korea
Solid-state lithium-metal anode development programs are driving non-destructive porosity mapping requirements at sub-micron resolution for battery electrode inspection. MFDS regulatory frameworks govern medical device qualification pathways incorporating CT-based validation. Seoul-based battery manufacturers aggressively unbundle service contracts from hardware procurement through usage-based pricing models.
Switzerland
Third-generation light sources at PSI deliver coherent illumination for phase-contrast imaging frontiers that pull laboratory system specifications upward. Swissmedic oversight governs medical device software validation for automated classification algorithms. Swiss federal technology institutes in Zurich and Lausanne operate multiple systems under ISO 17025-accredited measurement chains.
Japan
Cesium iodide and gadolinium oxysulfide production clusters create single-source vulnerability for high-resolution flat panel detectors serving cone beam CT architectures. METI industrial policy supports domestic scintillator material development to preempt supply discontinuities. Tokyo and Osaka metropolitan areas concentrate semiconductor fab installations demanding automated inline quality control integration.
Sub-Micrometer Computed Tomography Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: precision optics heritage, integrated analytical workflows, and specialized detector architectures. Equipment vendors fragment across laboratory system providers, industrial automation specialists, and synchrotron beamline integrators. Dominant competitive moves include strategic partnerships with university technology transfer offices for algorithm licensing and geographic expansion through specialized distribution platforms in Asia-Pacific markets.
Among precision instrumentation specialists, Bruker Corporation and Carl Zeiss AG exemplify archetypes rooted in materials science heritage and optical metrology respectively, while Thermo Fisher Scientific occupies a position representing integrated workflow bundling across imaging and analytical chemistry domains. These three anchors illustrate divergent strategic postures: recurring service revenue cultivation, tolerance-driven semiconductor applications, and cross-instrument software integration. Their collective presence shapes procurement patterns across research institutions and manufacturing plants, with each representing a distinct value proposition in calibration infrastructure, reconstruction algorithm access, or predictive maintenance integration.
| Leading Market Players |
|---|
| Bruker Corporation |
| PerkinElmer Inc. |
| Thermo Fisher Scientific |
| Carl Zeiss AG |
| SCANCO Medical AG |
| RX Solutions |
| Nanoscribe |
| North Star Imaging Inc. |
| Sanying Precision Instruments Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Japanese cesium iodide and gadolinium oxysulfide production clusters concentrate scintillator supply for high-resolution flat panel detectors, anchoring margin pools with detector manufacturers and specialized component distributors rather than system integrators or end-user facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates synchrotron-grade laboratory systems from mid-tier cone beam configurations and portable field units. Price differentiation rests on ISO 17025 certification status and detector pixel pitch specifications, with academic laboratories showing lowest sensitivity and South Korean battery manufacturers driving hardest bargains through unbundled procurement. Cost compression in industrial system tiers is intensifying because buyers separate capital expenditure from operational technology budgets.
Supply Chain Analysis
Tungsten target feedstock draws from Chinese refiners facing REACH authorization pressures, while cesium iodide scintillator crystals source from Japanese chemical manufacturers and precision motion stages originate from German and Swiss machine tool builders. Single-source vulnerability in detector scintillator supply creates structural risk for cone beam CT architectures. Distribution runs through specialized distributors in Singapore and the Netherlands consolidating mid-tier manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across detector architectures, reconstruction algorithm licensing, and calibration infrastructure creates niche entry points as semiconductor packaging inspection and battery electrode qualification pull specifications in divergent directions.
For Market Incumbents: Insulate service revenue streams by deepening captive calibration infrastructure and ISO 17025-accredited laboratory networks against emerging distributors offering usage-based pricing. Lock in university technology transfer partnerships for iterative reconstruction algorithm licensing to preempt patent thicket fragmentation. For New Entrants and Emerging Players: Establish a beachhead in portable and customized system configurations where Bruker and Carl Zeiss installed bases offer less coverage, particularly field archaeology and pipeline integrity assessment applications. Pursue configuration-as-a-service models through digital procurement platforms rather than direct sales force builds. For Investors and Strategic Acquirers: Capital is best deployed toward specialized detector architecture firms and ceramic scintillator developers ahead of REACH-driven supply discontinuities. The signal to watch is ECHA substance evaluation waves targeting heavy metal persistence in imaging equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scintillator Manufacturing | Preempts REACH authorization disruptions for Japanese cesium iodide supply. |
| University Technology Transfer Partnership | Secures iterative reconstruction algorithm licensing from ETH Zurich and Oak Ridge. |
| ISO 17025 Accreditation Expansion | Captures calibration service revenue as Fraunhofer networks tighten traceability mandates. |
| Configuration-as-a-Service Platform Launch | Consolidates mid-tier manufacturing demand through Singapore and Netherlands distributors. |
| Phase-Contrast Imaging Product Line Extension | Penetrates biomedical scaffold inspection replacing destructive histology at Swiss medical device manufacturers. |
Research Methodology
A spread of perspectives from CT system procurement managers at semiconductor fabs, metrology technicians at Fraunhofer institutes, biomedical engineers at Swiss medical device manufacturers, and aftermarket service heads at university laboratories converged on the working assumptions. These primary insights combined with secondary validation from FDA 21 CFR Part 820 quality system filings, ECHA REACH authorization timelines, SEC 10-K disclosures from precision instrumentation firms, and ISO 17025 accreditation registries. Bottom-up equipment shipment tallies and top-down analytical chemistry instrumentation market sizing provided triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, technology, and end user, with additional granularity on calibration infrastructure density and reconstruction algorithm licensing status. CAGRs derived from curve-fitting historical shipment data against semiconductor packaging inspection and battery electrode qualification demand curves. Industry-specific forecast inputs incorporated synchrotron facility beamtime allocation trends and EU AI Act conformity assessment timelines.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and battery cell production capacity buildouts would shift the trajectory. Forecasts reflect documented assumptions on detector pixel pitch advancement rates and tungsten target supply continuity. Cross-checking against Fraunhofer institute equipment procurement budgets and South Korean battery manufacturer capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Digital Imaging Market
Imaging
Weatherproof Camera Market
Imaging
Photoconductor Drums Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Medical X-Ray Detectors Market
Imaging
Micro Computed Tomography Market
Imaging
Virtual Reality Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Global Microbolometer Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Handheld Imager Market
Imaging
Europe IP Camera Market