
 United States Smart Sensors Market | 2026-2036
United States Smart Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Sensors Market Analytics
Aftermarket sensor calibration and predictive maintenance services is reconfiguring margin pools away from one-time hardware sales toward recurring revenue streams. Honeywell International leverages its aerospace heritage to dominate high-reliability pressure and temperature sensing for aviation and industrial clients. Texas Instruments sustains broad analog and signal-conditioning portfolios that anchor its position across multiple end-user verticals. Infineon Technologies specializes in magnetic and current sensors for electrified powertrains, competing directly with NXP Semiconductors in automotive-grade MEMS.
Smart sensors integrate microelectromechanical systems, signal-processing circuitry, and wireless communication protocols to transduce physical phenomena into actionable digital data with millisecond latency. These devices typically operate across temperature ranges from -40°C to 125°C and communicate via SPI, I2C, or low-power wide-area networks for real-time industrial control and consumer applications. Industrial Automation applications lead current revenue contribution due to mature factory digitization investments, while Healthcare Monitoring represents the fastest-expanding segment as remote patient diagnostics shift from hospital to home settings. MEMS technology occupies the dominant share of unit volume given its silicon-compatible batch fabrication, though IoT-enabled networked form factors are capturing disproportionate margin expansion as edge-computing architectures proliferate.
The EPA enforces emissions monitoring standards that mandate precise gas and particulate sensors in automotive and industrial installations, while NHTSA's automated vehicle safety assessments require redundant environmental perception systems. OSHA workplace exposure limits further drive demand for wearable and standalone environmental sensors in manufacturing facilities. Stakeholders must monitor how FAA unmanned aircraft regulations and evolving FCC spectrum allocations for sensor networks reshape product certification requirements and channel access priorities.
Market Dynamics
EPA tailpipe standards and NHTSA automated vehicle guidance are forcing sensor specification upgrades across automotive OEM supply chains, while Michigan and Ohio procurement expansion for electric powertrains concentrates demand in the Midwest manufacturing belt.
Growth Catalysts
- EPA Emissions Mandates:Gas and particulate monitoring requirements in automotive and industrial installations drive precision sensor procurement for compliance verification.
- Electrified Powertrains:Michigan and Ohio automotive OEMs are expanding sensor procurement for battery management and motor control systems.
- MEMS Batch Fabrication:Silicon-compatible manufacturing enables cost-effective unit scaling for consumer and industrial applications.
Market Restraints
- Raw Material Concentration:Rare earth element supply dependence creates input cost volatility for magnetic and current sensor production.
- Technical Limitation:Operating temperature ranges of -40°C to 125°C constrain deployment in extreme aerospace and deep-well applications.
- Regulatory Friction:FCC spectrum allocation delays for low-power wide-area networks slow IoT sensor network deployment timelines.
Strategic Opportunities
- Healthcare Home Diagnostics:Remote patient monitoring shifts from hospital to home settings, expanding wearable sensor demand.
- Edge-Computing Convergence:IoT-enabled networked sensors with on-device processing capture margin expansion as distributed architectures proliferate.
- Aftermarket Services:Predictive maintenance and calibration subscriptions reconfigure revenue from one-time hardware sales to recurring streams.
Industry Challenges
- Multi-Protocol Integration:SPI, I2C, and LPWAN communication standards create firmware complexity for cross-platform sensor deployment.
- Certification Timeline Compression:FAA unmanned aircraft regulations and evolving FCC requirements extend product validation cycles.
- Signal-Conditioning Talent Scarcity:Analog circuit design expertise shortages constrain development of high-reliability industrial sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Sensors Market |
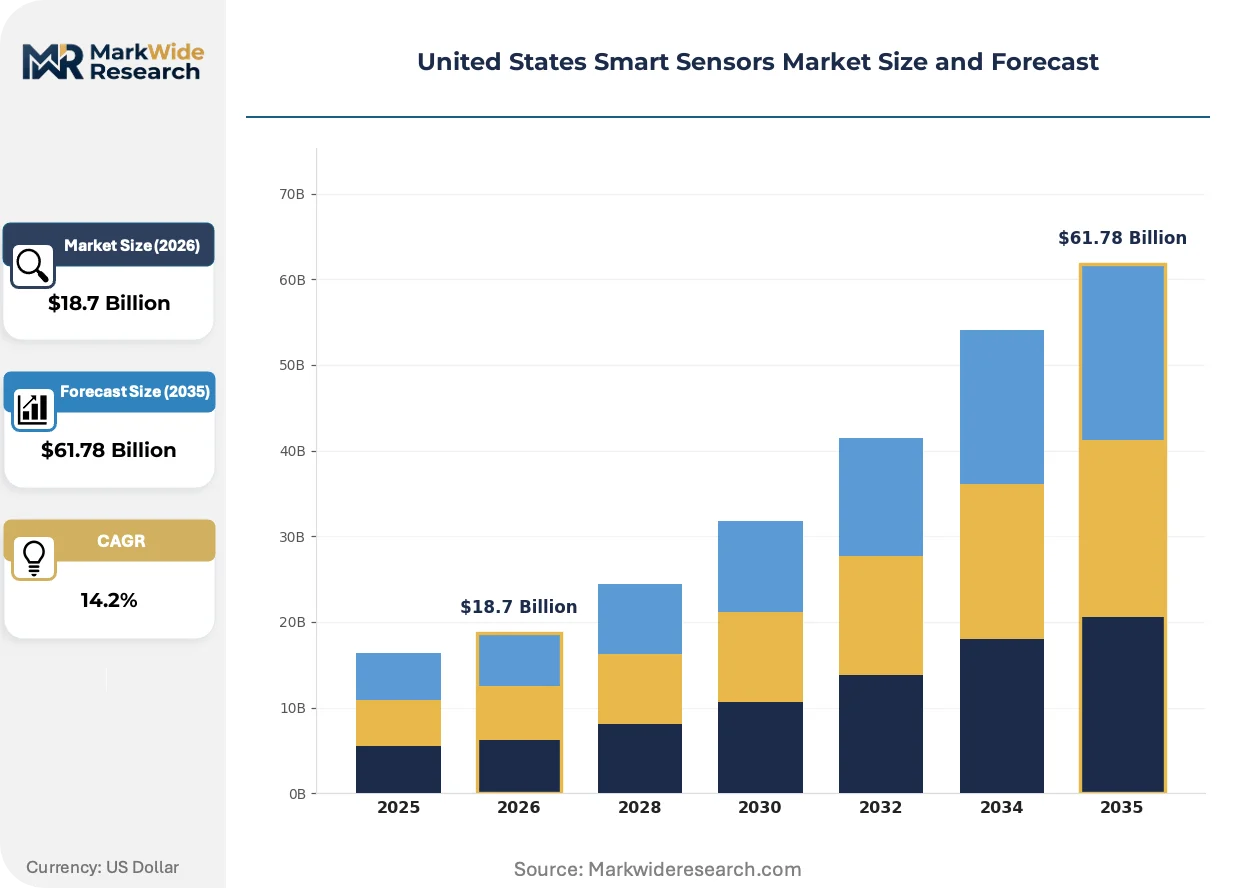
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Automation, Smart Home Systems, Healthcare Monitoring, Environmental Monitoring Technology: MEMS, IoT, Infrared, Ultrasonic End User: Manufacturing, Automotive, Consumer Electronics, Aerospace Form Factor: Wearable, Standalone, Embedded, Networked |
| Companies Covered | Analog Devices, Honeywell International, Infineon Technologies, TE Connectivity, Texas Instruments, STMicroelectronics, Eaton Corporation, ABB, NXP Semiconductors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Sensors Market Evolving Landscape
Wireless communication protocols and on-device processing architectures are compressing latency requirements and enabling real-time industrial control applications previously dependent on wired infrastructure.
MEMS technology is digitizing physical phenomena detection through microelectromechanical systems that integrate transduction, signal processing, and wireless transmission in single-package formats. Automotive OEMs in Michigan and Ohio are adopting these sensors at accelerated rates for electric powertrain monitoring. This convergence is digitizing factory control architectures by replacing discrete wired sensors with networked, self-calibrating devices.
NHTSA automated vehicle safety assessments mandate redundant environmental perception systems that combine LiDAR, radar, and camera inputs for failsafe operation. These requirements force tier-one suppliers to source multi-modal sensor suites with cross-validation capabilities. The commercial vehicle segment faces the steepest compliance burden as autonomous trucking pilots expand across Arizona and Texas corridors.
Buyers are consolidating sensor procurement around suppliers offering bundled calibration and predictive maintenance services rather than discrete hardware transactions. Industrial automation OEMs in the Midwest are shifting toward subscription-based sensor health monitoring. This pattern is most visible in Ohio manufacturing facilities where OSHA workplace exposure monitoring requirements drive recurring environmental sensor service contracts.
United States Smart Sensors Market Segmentation
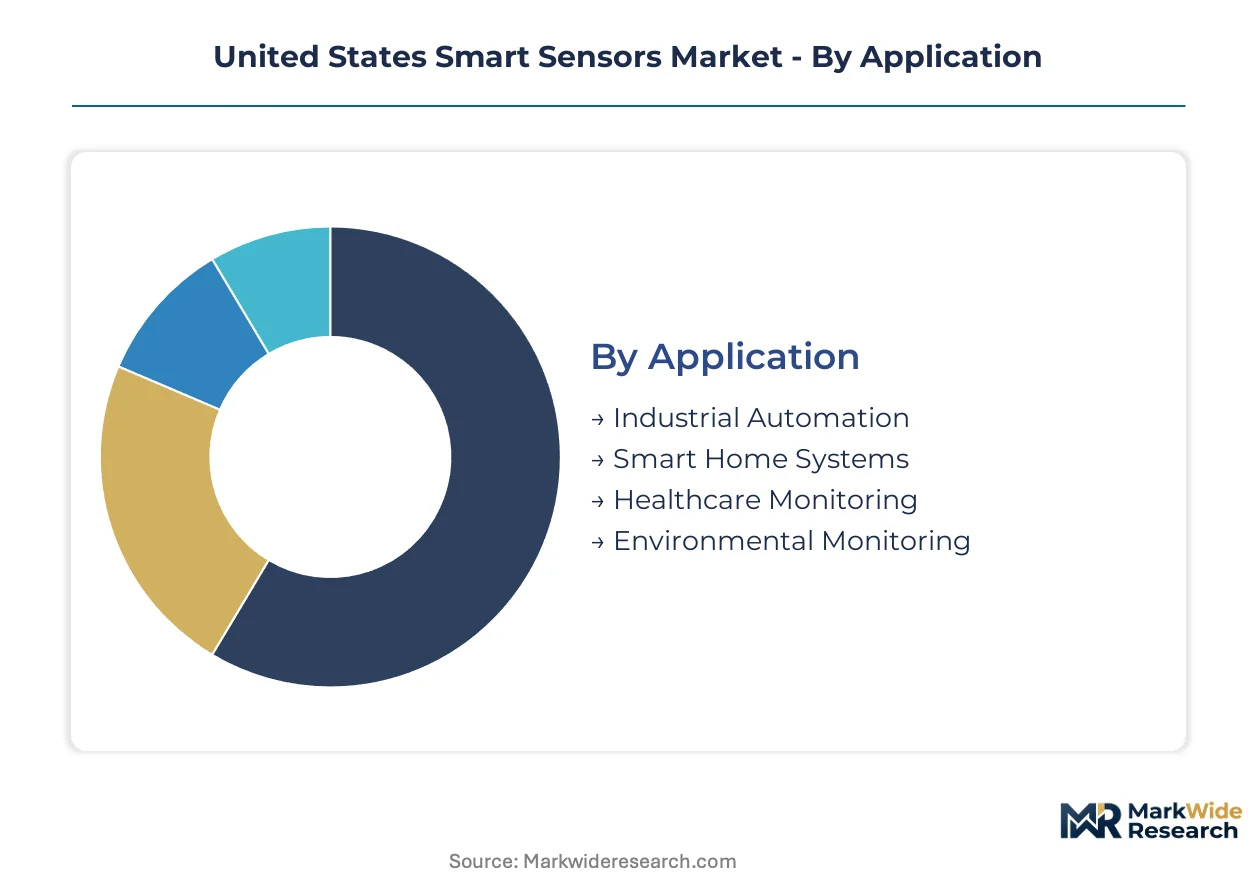
Smart sensor deployment patterns diverge sharply across application contexts, with industrial buyers prioritizing reliability metrics while consumer segments optimize for miniaturization and power efficiency. Technology selection and form factor tradeoffs further fragment procurement specifications across end-user verticals.
Application:
End-use context determines performance thresholds, communication protocols, and service contract structures across deployment scenarios.
- Industrial Automation:Ruggedized pressure, temperature, and vibration sensors with IP67+ enclosures communicate via industrial Ethernet and fieldbus protocols for real-time process control. Michigan and Ohio automotive OEMs anchor procurement volume for predictive maintenance and quality assurance systems.
- Healthcare Monitoring:Biometric sensors with FDA Class II clearance track vital signs through photoplethysmography and impedance spectroscopy for remote patient diagnostics. Home-based deployments are climbing the fastest as reimbursement codes shift from facility to ambulatory settings.
- Smart Home Systems:Low-power motion, humidity, and air quality sensors integrate with Z-Wave and Matter protocols for residential automation hubs.
- Environmental Monitoring:EPA-compliant gas and particulate sensors enable stationary and mobile emissions verification for regulatory reporting.
Industrial Automation holds installed capacity. Healthcare Monitoring is rotating up the share rankings.
Technology:
Underlying transduction mechanisms determine unit economics, calibration requirements, and supply chain exposure to semiconductor fabrication constraints.
- MEMS:Silicon-microfabricated mechanical structures transduce acceleration, pressure, and gyroscopic motion through capacitive or piezoelectric effects with batch-scale cost efficiency. Texas Instruments and Infineon sustain dominant positions through captive foundry access and automotive qualification pipelines.
- IoT:Networked sensor nodes embed microcontrollers, wireless radios, and edge-processing capability for distributed data collection. LPWAN protocol fragmentation and FCC certification delays constrain deployment velocity despite margin expansion potential.
- Infrared:Thermal imaging arrays and non-contact temperature sensors leverage bolometer or thermopile architectures for industrial and medical applications.
- Ultrasonic:Time-of-flight and Doppler-effect sensors enable level sensing, proximity detection, and flow measurement in harsh media environments.
MEMS dominates unit shipment volume. IoT is expanding most quickly as edge-computing architectures proliferate.
End User:
Customer archetype dictates procurement scale, specification rigor, and aftermarket service attachment rates.
- Automotive:NHTSA-mandated redundant perception systems and EPA emissions verification drive multi-sensor fusion requirements across powertrain, chassis, and cabin domains. Electric vehicle battery management systems concentrate magnetic and current sensor demand in Midwest manufacturing corridors.
- Manufacturing:OSHA workplace exposure limits and predictive maintenance ROI targets sustain environmental and condition-monitoring sensor procurement.
- Consumer Electronics:Wearable and smartphone-integrated sensors prioritize die-size reduction and sub-milliwatt power budgets.
- Aerospace:DO-160G and MIL-STD-810 qualification requirements limit supplier base to Honeywell and established avionics specialists with aerospace heritage.
Manufacturing holds installed capacity. Automotive is rotating up the share rankings.
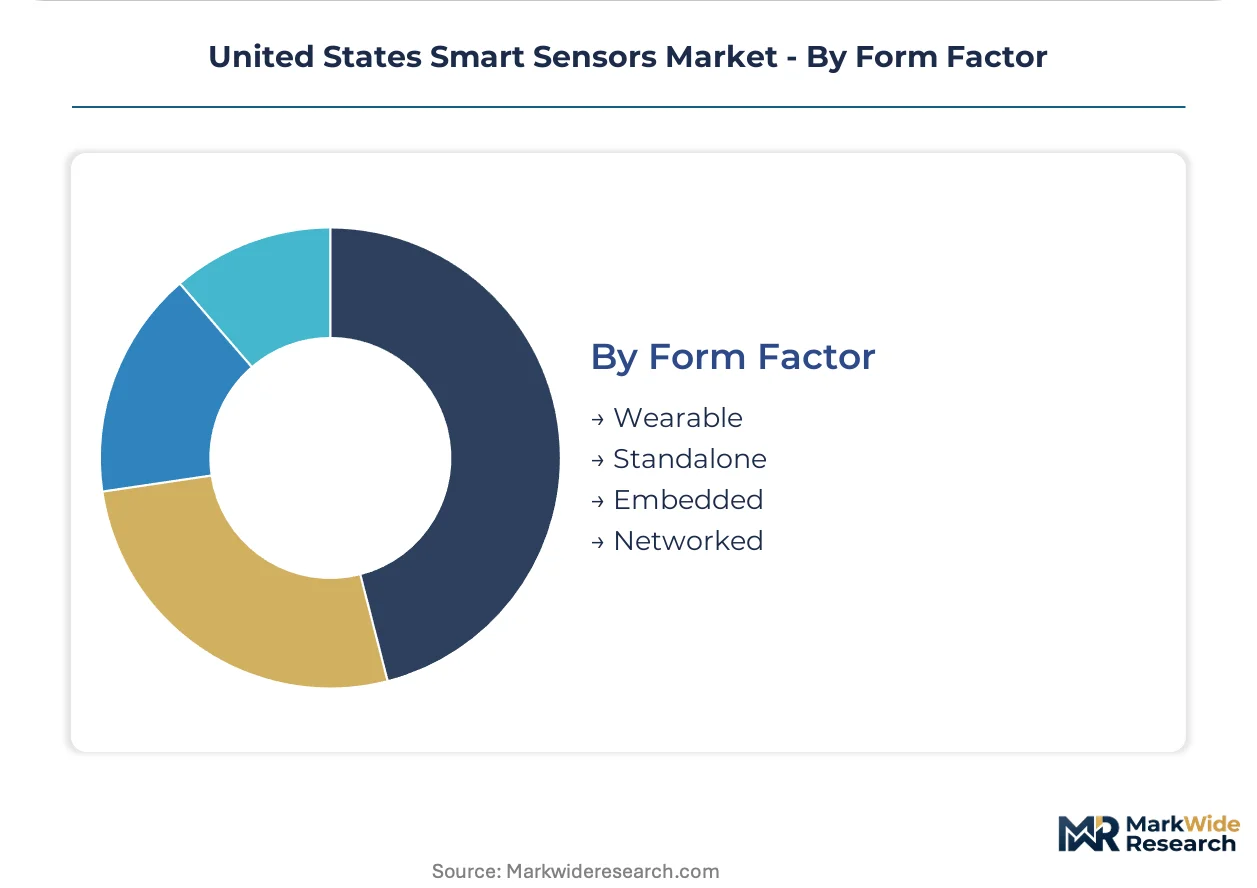
Form Factor:
Physical integration approach determines power architecture, thermal management, and upgrade pathway flexibility.
- Embedded:Die-level or package-level integration within host systems (motor controllers, medical devices, vehicle ECUs) minimizes interconnect complexity and latency. Automotive powertrain controllers in Ohio and Michigan anchor procurement concentration.
- Networked:Self-contained sensor nodes with local processing and wireless backhaul enable retrofit deployment without control system modification.
- Wearable:Skin-contact or body-worn configurations optimize for biocompatibility, flex circuit integration, and extended battery life.
- Standalone:Enclosed instruments with local display and data logging serve calibration reference and portable inspection applications.
Embedded holds installed capacity. Networked is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan and Ohio automotive OEMs deploy smart sensors primarily for powertrain electrification and autonomous vehicle validation, while California's Silicon Valley corridor concentrates IoT-enabled environmental and wearable sensor development for consumer and healthcare applications.
Michigan
Detroit-area automotive OEMs anchor procurement volume for electric vehicle battery management systems and motor control sensors. NHTSA automated vehicle safety assessments mandate redundant environmental perception systems across tier-one supplier networks. The Ann Arbor-Detroit corridor concentrates validation facilities for autonomous trucking pilots and ADAS sensor fusion testing.
Ohio
Cleveland and Cincinnati manufacturing hubs drive demand for OSHA-compliant workplace exposure sensors and predictive maintenance systems. EPA emissions monitoring standards require precise gas and particulate sensors for industrial compliance verification. The state's automotive supply chain is expanding sensor procurement for electrified powertrain production alongside legacy internal combustion platforms.
California
Silicon Valley and San Diego clusters concentrate venture-backed IoT sensor startups and FDA-cleared wearable device manufacturers. FCC spectrum allocation proceedings for low-power wide-area networks directly impact deployment timelines for networked environmental sensors. Los Angeles aerospace contractors source high-reliability pressure and temperature sensors for satellite and unmanned aircraft applications under FAA regulations.
Texas
Houston's energy sector deploys harsh-environment sensors for petrochemical process control and emissions monitoring. FERC grid modernization initiatives accelerate demand for current and magnetic sensors in utility-scale battery storage installations. Austin's semiconductor fabrication ecosystem supports MEMS foundry services for automotive and industrial sensor producers.
Arizona
Phoenix-area autonomous vehicle testing corridors consume multi-modal sensor suites combining LiDAR, radar, and camera inputs. NHTSA commercial vehicle safety mandates concentrate validation programs for autonomous trucking routes spanning Arizona-Texas corridors. Tucson's mining equipment manufacturers source ruggedized vibration and temperature sensors for predictive maintenance in open-pit operations.
United States Smart Sensors Market Competitive Landscape
Capability concentration sits with aerospace-qualified specialists; scale advantage sits with diversified semiconductor conglomerates. The market structure reflects a tiered hierarchy where high-reliability applications limit supplier pools through DO-160G and MIL-STD-810 qualification barriers, while consumer and industrial segments permit broader participation from analog and mixed-signal specialists. Strategic archetypes include captive foundry operators with automotive qualification pipelines, fabless designers leveraging contract manufacturing, and vertically integrated industrial conglomerates with aftermarket service networks. Competitive moves center on portfolio diversification into edge-computing sensor nodes and backward integration into MEMS fabrication capacity.
Within the diversified semiconductor tier, Texas Instruments and Infineon Technologies occupy positions anchored by broad analog portfolios and captive foundry access. Honeywell International exemplifies the aerospace-specialist archetype with qualification heritage limiting competitive entry. NXP Semiconductors sits within the automotive-focused tier competing directly in magnetic and current sensing for electrified powertrains.
| Leading Market Players |
|---|
| Analog Devices |
| Honeywell International |
| Infineon Technologies |
| TE Connectivity |
| Texas Instruments |
| STMicroelectronics |
| Eaton Corporation |
| ABB |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
Rare earth element supply dependence on Chinese and Australian mining operations determines both tiered pricing spreads across automotive-grade MEMS and the geographic shape of North American sensor supply chains. EPA emissions compliance mandates and NHTSA automated vehicle specifications further stratify procurement costs between certified and uncertified supplier tiers.
Pricing Analysis
Long-term offtake agreements dominate automotive OEM procurement in Michigan and Ohio, locking in volume commitments for magnetic and current sensors across electrified powertrain programs. Pricing stratifies across premium, standard, and economy tiers based on DO-160G aerospace qualification status and automotive AEC-Q100 certification grade. Cost compression in standard-tier MEMS is intensifying because Taiwanese foundry capacity expansion outpaces Midwest demand growth. Tier-one automotive suppliers exhibit lowest price sensitivity due to liability exposure from sensor failures, while consumer electronics integrators negotiate aggressively on die-size margins.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for rare earth magnet inputs and silicon wafer substrates. Taiwan, South Korea, and Germany anchor global MEMS fabrication capacity, with Austin's semiconductor ecosystem providing domestic foundry alternatives for automotive qualification pipelines. Magnetic core materials and specialized packaging substrates draw from concentrated Asian suppliers. Single-source vulnerability persists for aerospace-grade pressure sensor diaphragm alloys. Distribution runs through authorized distributor networks serving tier-one automotive and industrial OEMs with consignment inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
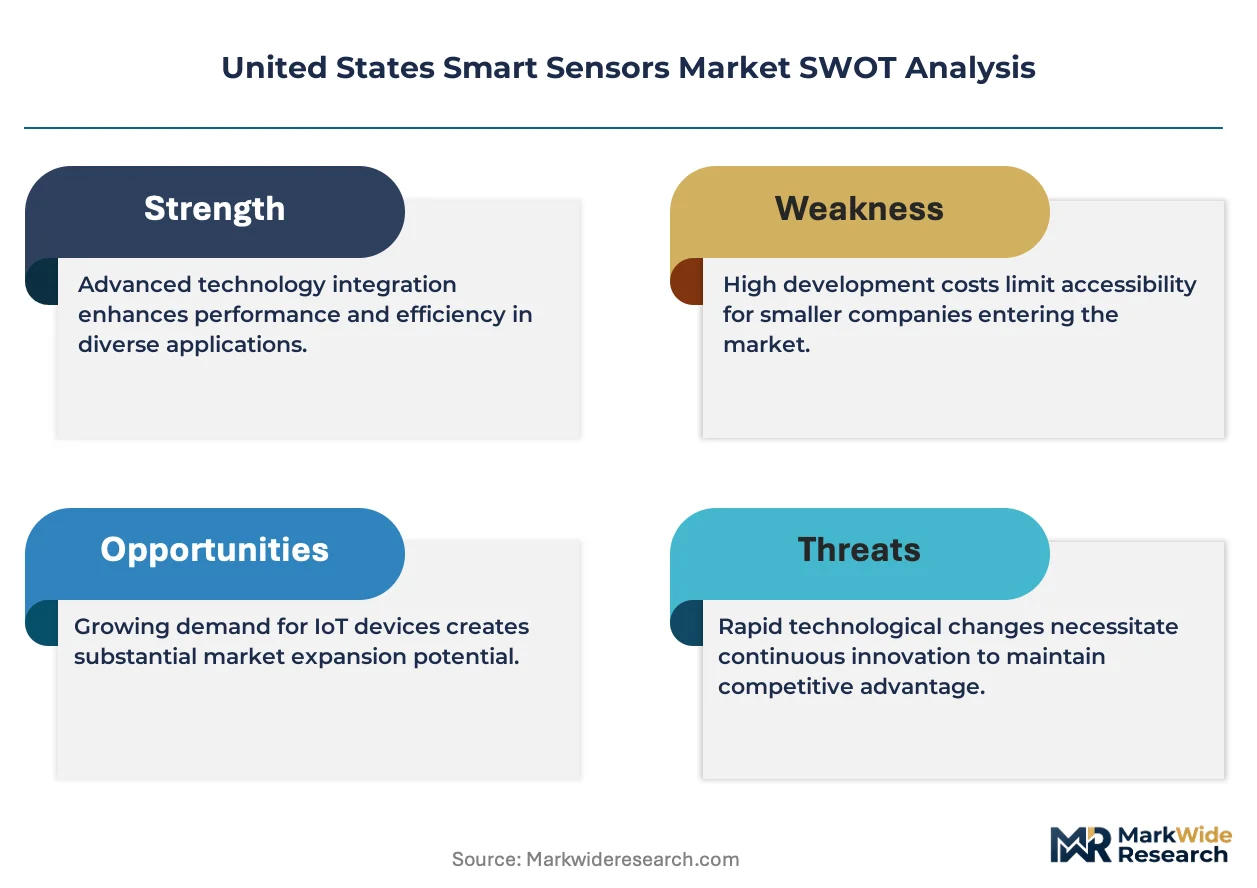
Signal-conditioning analog expertise scarcity constrains development velocity for high-reliability industrial sensors, compressing competitive margins for firms without captive design talent. This capability gap rewards early investments in specialized workforce pipelines and university partnership programs.
For Market Incumbents: Pre-empt emerging fabless competitors by securing captive MEMS foundry access in Austin and Phoenix manufacturing corridors. Accelerate DO-160G qualification pipelines for aerospace sensor portfolios before FAA unmanned aircraft regulations harden certification barriers. Defensive consolidation around aftermarket calibration service networks locks in recurring revenue streams that offset hardware margin erosion. For New Entrants and Emerging Players: OSHA-compliant workplace exposure monitoring in Ohio manufacturing facilities represents the most penetrable entry point for networked environmental sensor platforms. Healthcare home diagnostics reimbursement code expansion creates white-space for FDA Class II wearable device startups targeting remote patient monitoring. Direct sales to Midwest predictive maintenance programs bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors aerospace-qualified specialists with aftermarket service networks. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment growth. Acquisition target archetypes include fabless designers with automotive AEC-Q100 qualification pipelines and captive analog design teams. The signal to watch is FCC spectrum allocation finalization for low-power wide-area networks as inflection indicator for IoT sensor deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Austin semiconductor fabrication investments reduce tariff exposure for automotive OEMs in Michigan and Ohio. |
| Aftermarket Service Network Buildout | Predictive maintenance subscriptions reconfigure Honeywell and TE Connectivity revenue toward recurring streams. |
| Aerospace Qualification Pipeline | DO-160G certification investments limit competitive entry for high-reliability pressure and temperature sensors. |
| Edge-Computing Sensor Integration | On-device processing architectures capture margin expansion as distributed industrial control systems proliferate. |
| Healthcare Regulatory Pathway | FDA Class II clearance for photoplethysmography wearables unlocks home diagnostics reimbursement codes. |
Research Methodology
The analysis maps MEMS fabrication, IoT networked sensors, infrared thermal arrays, and ultrasonic detection technologies, each validated through tier-one automotive procurement directors, industrial automation plant engineers, and FAA certification specialists. Primary interviews with biomedical device regulatory affairs leads and semiconductor foundry operations managers combined with secondary triangulation against SEC 10-K filings, EPA emissions compliance databases, and NHTSA automated vehicle safety assessment records. Bottom-up unit shipment estimates and top-down value aggregation cross-validate segment-level projections.
Assumption sets held semiconductor fabrication capacity expansion and EPA tailpipe standard enforcement trajectories fixed while varying electric vehicle adoption curves and FCC spectrum allocation timelines across modeling scenarios. Segmentation dimensions include transduction technology, application context, end-user vertical, and form factor integration approach. CAGRs derive from installed base growth rates and content-per-vehicle expansion in electrified powertrains. Industry-specific inputs encompass OSHA workplace exposure monitoring mandate implementation schedules and FAA unmanned aircraft regulatory evolution.
Practitioners should monitor rare earth export restriction announcements and foundry utilization rate shifts for early signals of supply constraint. Forecasts reflect documented assumptions about automotive electrification penetration and healthcare reimbursement policy trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Global Actuator Sensor Interface Market