
 Global Single Loop Controller Market | 2026-2036
Global Single Loop Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single Loop Controller Market Intelligence
The integration of Ethernet connectivity and OPC UA communication protocols is reshaping how single loop controllers are deployed within distributed control systems. This shift enables greater data accessibility and interoperability between devices. Siemens leverages its extensive automation portfolio to offer integrated solutions for complex processes. Meanwhile, Yokogawa specializes in high-reliability controllers for critical applications in the chemical and power generation sectors.
A single loop controller is a dedicated instrument designed to manage one specific process variable, such as temperature, pressure, or flow. It functions by comparing a sensor's real-time measurement to a desired setpoint and adjusting an output to minimize the deviation. Digital electronic controllers represent the largest product segment, offering superior accuracy and networking features. PID control remains the foundational technology, essential for maintaining stability in applications from water treatment to food processing.
Product design and market access are governed by international standards like IEC 61508 for functional safety in critical systems. In Europe, CE marking is mandatory, while FDA regulations in the United States influence data logging features for pharmaceutical applications. Stakeholder decisions will increasingly weigh the benefits of standalone, dedicated control against integration into larger PLC or DCS architectures.
Market Dynamics
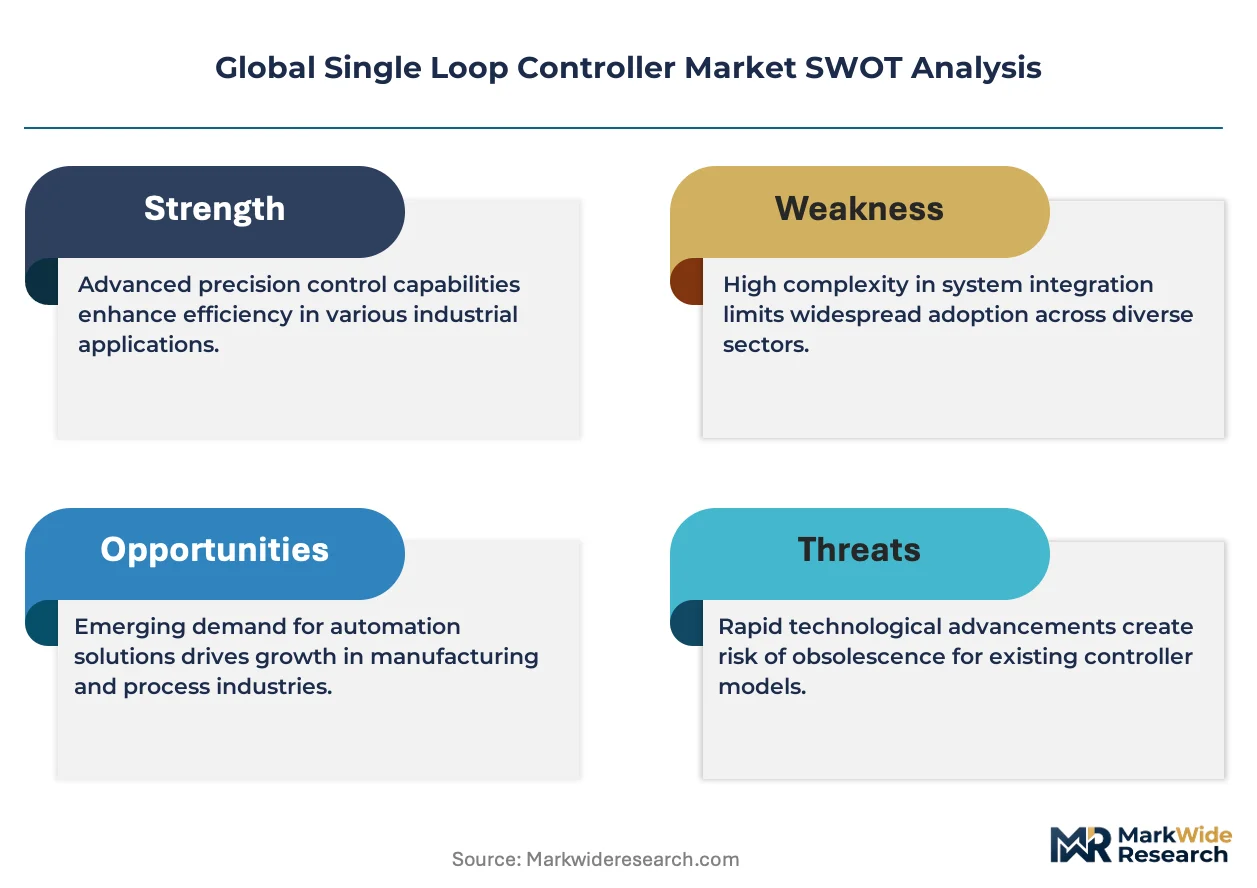
The central force shaping the market is the architectural tension between standalone, dedicated control and full integration into larger Distributed Control Systems (DCS). This is amplified by the adoption of IIoT protocols for remote asset management and diagnostics.
Growth Catalysts
- Advanced Process Control (APC) Integration:The implementation of APC strategies in refining and chemical processing requires highly reliable and responsive underlying loop control, driving upgrades to more capable digital controllers.
- Semiconductor Fabrication Expansion:Unprecedented investment in new semiconductor fabs, particularly in South Korea and Taiwan, creates substantial demand for controllers ensuring ultra-precise temperature, pressure, and gas flow management.
- Water Treatment Standards:Stricter regulations for municipal and industrial water treatment, such as those from the EPA in the US, mandate precise, documented control over variables like pH and turbidity, boosting controller deployment.
Market Restraints
- PLC and DCS Functional Encroachment:Modern Programmable Logic Controllers (PLCs) and DCS platforms increasingly incorporate single-loop control functions, reducing the need for dedicated hardware in new, highly integrated plant designs.
- High-Cost Specialized Sensors:The total cost of a control loop is often dictated by the sensor. The expense of high-accuracy sensors for corrosive or extreme-temperature environments can constrain the budget for controller upgrades.
- Inherent I/O Limitations:By design, a single loop controller has limited input and output capacity. This structural limitation makes it unsuitable for complex, multi-variable processes, confining its use to specific, isolated applications.
Strategic Opportunities
- Edge Computing Capabilities:Embedding edge processing directly within controllers presents an opportunity to perform local analytics, run optimization algorithms, and reduce latency without constant communication with a central host.
- Renewable Energy Systems:Applications in renewable energy, such as solar thermal fluid management and battery storage temperature regulation, represent an underpenetrated market for rugged, reliable standalone controllers.
- Functional Safety Mandates:The stringent enforcement of IEC 61508 for safety-instrumented systems creates a premium market for certified, high-reliability controllers in critical applications across the European power and chemical sectors.
Industry Challenges
- Legacy System Integration:A primary operational hurdle for system integrators is the complexity of interfacing modern, Ethernet-based controllers with older plant equipment that relies on proprietary or serial communication protocols.
- PID Tuning Expertise Scarcity:A persistent shortage of process control engineers and technicians with the deep practical experience needed to properly tune PID loops for optimal stability and performance is a widespread challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single Loop Controller Market |
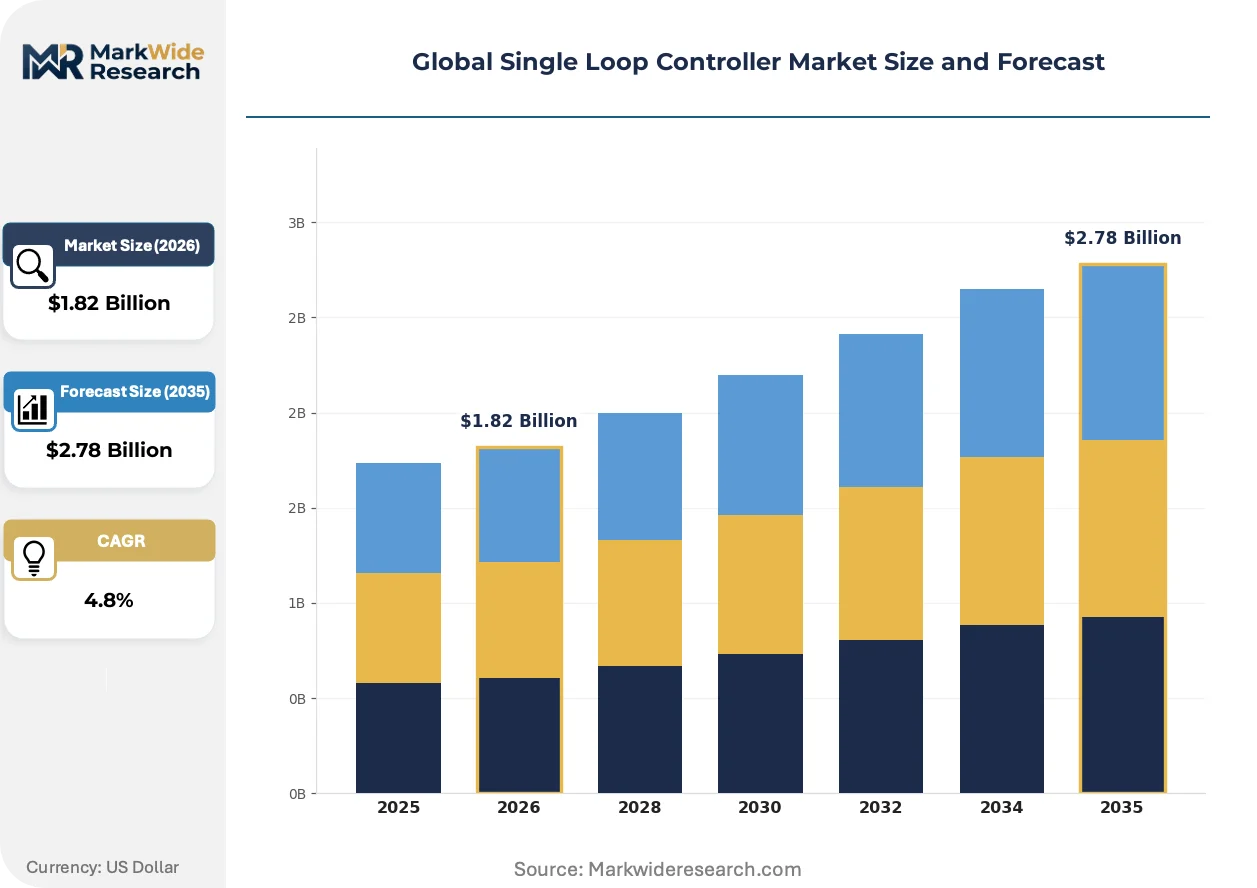
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Controllers, Analog Electronic Controllers, Digital Electronic Controllers, Hybrid Controllers Technology: PID Control, On-Off Control, Feedforward Control, Adaptive Control, Ratio Control Application: Chemical Manufacturing, Power Generation, Water Treatment, Food Processing, Semiconductor Fabrication End User Industry: Process Manufacturing, Utilities, Electronics Production, Food & Beverage Plants |
| Companies Covered | ABB, Honeywell, Siemens, Yokogawa, Schneider Electric, Emerson Electric, OMRON, Eurotherm, Mitsubishi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single Loop Controller Market Strategic Shifts & Innovations
The functional evolution of single loop controllers is defined by their transformation from isolated instruments into networked data nodes. This shift prioritizes interoperability and remote accessibility within modern industrial automation architectures, enhancing data value across the enterprise.
Standardized communication protocols like OPC UA and MQTT are foundational to modern controller design, enabling secure, platform-independent data exchange. Process industries, particularly pharmaceuticals and food processing, are rapidly adopting these for enhanced data integrity and system-wide visibility. The market is migrating from proprietary, closed-loop networks toward open, Ethernet-based architectures that simplify integration with MES and cloud platforms.
Regulations such as the FDA's 21 CFR Part 11 in the United States and similar EMA guidelines in Europe impose strict requirements for electronic records and signatures. This directly impacts controller design, mandating features like secure data logging, audit trails, and user access controls to ensure compliance. Pharmaceutical and biotech manufacturing are most affected, driving demand for controllers with built-in data integrity and validation support.
End-users are increasingly purchasing controllers as part of a broader solution that includes remote monitoring, diagnostics, and loop tuning services. This unbundles traditional hardware sales and disrupts the model for distributors, who must now build service capabilities or partner with system integrators. The shift is most visible in the water and building automation sectors, where remote asset management is critical for operational efficiency.
Global Single Loop Controller Market Segmentation
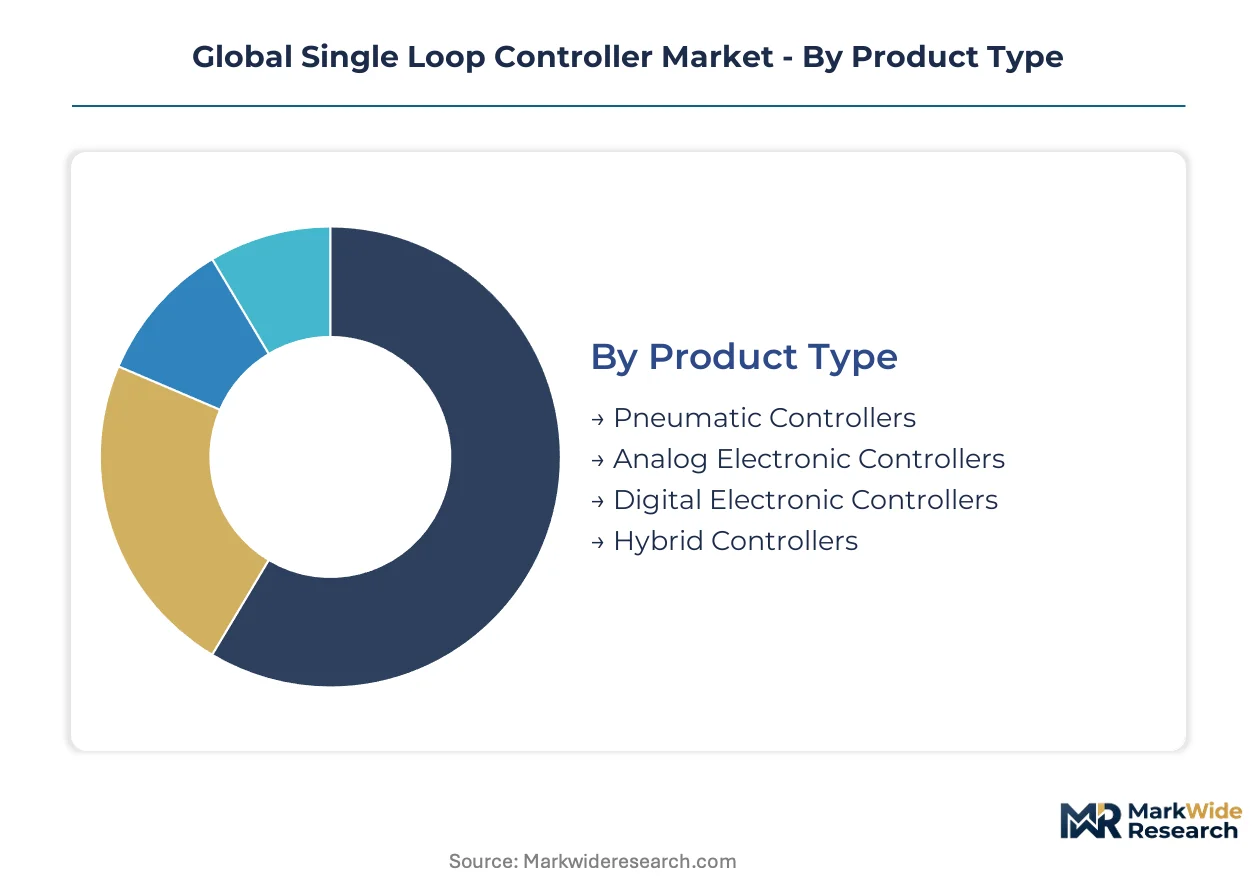
Understanding the segmentation of the global single loop controller market reveals the diverse demands shaping product development and strategic investments. These classifications highlight varying needs for precision, integration, and regulatory adherence across different industrial contexts.
Product Type:
The turnover rate for single loop controller product types varies significantly, driven by technological advancements and legacy system lifecycles.
- Digital Electronic Controllers:These controllers utilize microprocessors for precise control algorithms and offer advanced networking capabilities. Demand is highest in semiconductor fabrication facilities in South Korea, where ultra-high accuracy and data logging are critical.
- Analog Electronic Controllers:These traditional controllers employ analog circuits to manage process variables with continuous signals. Demand remains stable in older industrial plants in Germany, where cost-effective replacement of existing infrastructure is preferred.
- Pneumatic Controllers:These controllers operate using air pressure for control actions, often found in hazardous environments requiring intrinsic safety.
- Hybrid Controllers:Combining analog and digital elements, these offer a balance of robust, continuous control with some digital interface features.
Analog Electronic Controllers dominate the installed base across various industries. Digital Electronic Controllers see significant expansion for new projects.
Technology:
The choice of control technology for single loop controllers directly correlates with the required process stability and dynamic response characteristics.
- PID Control:Proportional-Integral-Derivative control is the most widely adopted algorithm, continuously calculating an error value and adjusting output to minimize deviation. It is essential for maintaining stable temperatures in food processing plants across the United States, adhering to FDA guidelines.
- Adaptive Control:This advanced method automatically adjusts controller parameters in real-time to compensate for changes in process dynamics or external disturbances. Its application is growing in complex chemical manufacturing in Japan, where process variability is high.
- On-Off Control:This basic control strategy simply switches an output fully on or off when a setpoint is crossed, suitable for simple temperature regulation.
- Feedforward Control:This method anticipates disturbances and takes corrective action before the process variable deviates significantly, enhancing response times.
- Ratio Control:This technology maintains a precise ratio between two or more flow rates, critical in blending operations within the oil and gas sector.
PID Control offers the broadest applicability across diverse industrial processes. Adaptive Control is increasingly selected for highly dynamic or non-linear systems.
Application:
The specific application dictates the required precision, reliability, and regulatory compliance of single loop controllers.
- Semiconductor Fabrication:This sector demands ultra-precise control over temperature, pressure, and gas flow in highly sensitive environments to ensure chip quality. New fabrication plants in Taiwan are driving significant demand for advanced digital controllers that meet stringent process windows.
- Chemical Manufacturing:Critical processes in this industry require robust and reliable controllers for managing exothermic reactions and maintaining precise ingredient ratios. IEC 61508 certified controllers are mandated for safety-instrumented systems in European chemical plants.
- Power Generation:Controllers manage variables like boiler feedwater flow and turbine bearing temperatures to ensure efficient and safe operation of power plants.
- Water Treatment:Municipal and industrial water treatment facilities use single loop controllers for pH balancing, chlorine dosing, and turbidity management, often under EPA regulations.
- Food Processing:These controllers maintain pasteurization temperatures and fermentation conditions, ensuring product quality and compliance with FDA food safety standards.
Semiconductor Fabrication places the highest demands on controller precision and data integrity. Water Treatment applications represent a widespread and growing area for deployment.
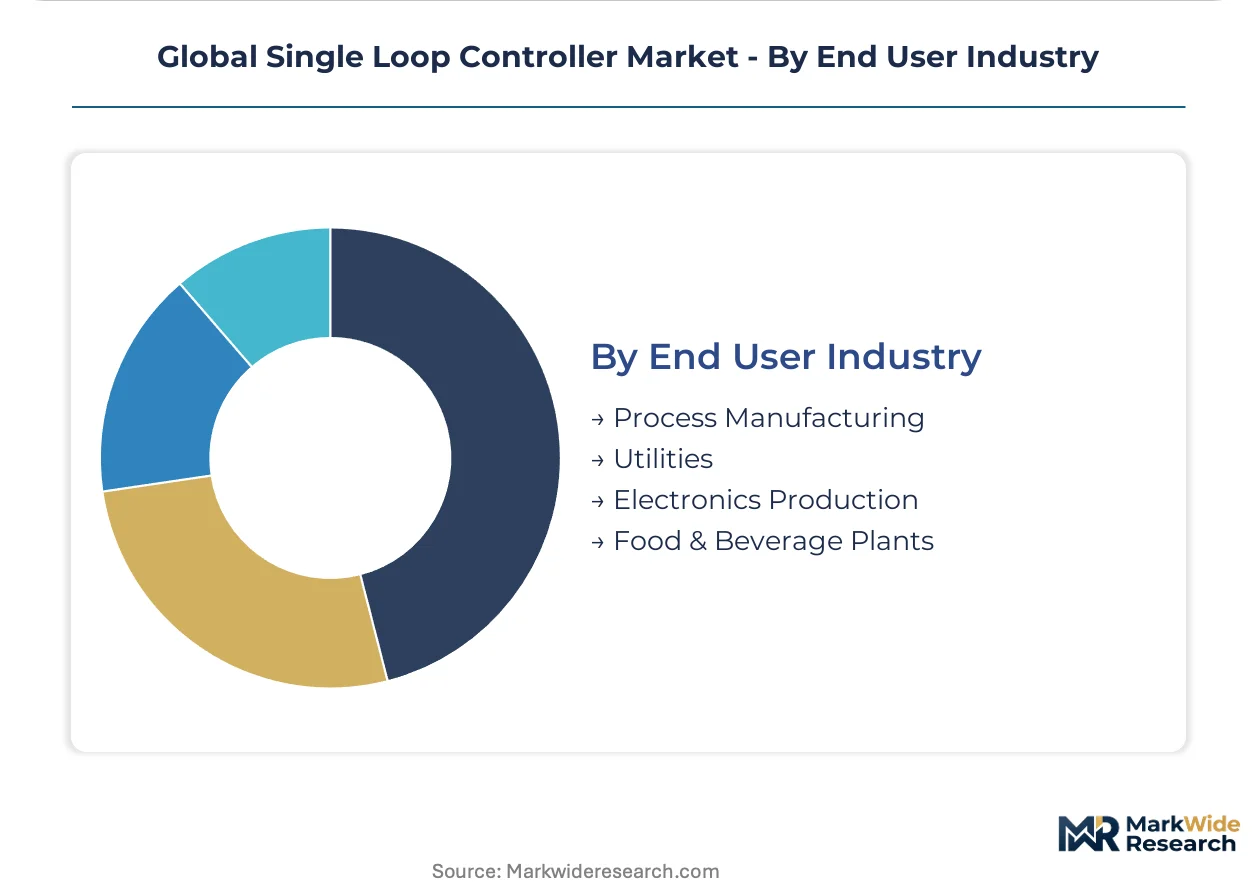
End User Industry:
End-user industries vary significantly in their operational scale and the complexity of integrating single loop controllers into broader automation architectures.
- Process Manufacturing:This broad category encompasses industries like oil and gas, petrochemicals, and pulp and paper, where continuous production relies on stable control of numerous variables. Large-scale refineries in Saudi Arabia utilize these controllers for critical flow and level regulation.
- Electronics Production:Beyond semiconductor fabrication, this segment includes assembly and component manufacturing, requiring precise temperature and humidity control for quality assurance. Facilities in China are integrating advanced controllers with IIoT protocols for enhanced monitoring.
- Utilities:This sector includes water, wastewater, and power distribution, where controllers manage infrastructure for public services and regulatory compliance.
- Food & Beverage Plants:Controllers ensure consistent product quality and safety by managing parameters such as temperature, pressure, and flow in production lines.
Process Manufacturing represents the largest segment for single loop controller deployment. Electronics Production exhibits a steep expansion trajectory driven by new investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of advanced digital single loop controllers from specialized manufacturing hubs in East Asia to global industrial consumers shapes regional market dynamics. Demand for these precision instruments is particularly intense in sectors requiring stringent process control. International trade agreements and local investment policies significantly influence market access and growth trajectories.
South Korea
South Korea's semiconductor fabrication expansion creates substantial demand for ultra-precise temperature, pressure, and gas flow management. The country's national industrial safety standards (KOSHA regulations) influence controller deployment in critical facilities. New semiconductor fabs around Seoul and Gyeonggi Province require advanced digital controllers for production.
Taiwan
Taiwan's new fabrication plants drive significant demand for advanced digital controllers that meet stringent process windows for chip quality. Taiwan's Industrial Technology Research Institute (ITRI) guidelines promote high-tech manufacturing standards. Hsinchu Science Park and Tainan's Southern Taiwan Science Park particularly drive demand for these advanced instruments.
Germany
German industrial plants, especially in the chemical sector, require robust and reliable controllers for managing complex processes. CE marking is mandatory for market access, and IEC 61508 applies to safety-instrumented systems. Chemical parks in Ludwigshafen and Leverkusen frequently upgrade controllers for critical process variables.
United States
United States food processing and water treatment sectors require precise control for quality assurance and regulatory compliance. FDA guidelines impact data logging features for pharmaceutical applications; EPA regulations mandate precise control in water treatment. Food processing facilities across the Midwest and water treatment plants in California utilize PID controllers for stability.
Japan
Japanese complex chemical manufacturing and power generation applications require high-reliability controllers for process variability. METI industrial standards and JIS standards guide controller specifications for domestic industries. Chemical and power generation facilities in the Kansai region adopt adaptive control for dynamic systems.
Global Single Loop Controller Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large, diversified industrial automation conglomerates and specialized control system providers. These entities often compete across various product segments and end-user industries. Strategic archetypes include integrated solution providers, niche technology specialists, and regional market leaders. Companies pursue portfolio diversification and strategic partnerships to enhance their market presence.
Among the integrated solution providers, Siemens AG and Emerson Electric Co. represent established players offering extensive automation portfolios. These firms leverage their broad engineering capabilities to deliver solutions across multiple industrial sectors. Yokogawa Electric Corporation, a Japanese multinational, exemplifies a specialist in high-reliability controllers, particularly for critical applications in process industries. These companies occupy positions across the globe, serving complex industrial control needs.
| Leading Market Players |
|---|
| ABB |
| Honeywell |
| Siemens |
| Yokogawa |
| Schneider Electric |
| Emerson Electric |
| OMRON |
| Eurotherm |
| Mitsubishi |
| Others |
Cost & Logistics Intelligence
Hsinchu Science Park's advanced manufacturing capacity for critical electronic components significantly influences downstream pricing power for digital single loop controllers. This concentration in East Asia shapes global market dynamics and product availability.
Pricing Analysis
The clear pricing gap exists between advanced digital controllers and legacy analog units. Premium-mid-economy pricing differentiation stratifies offerings, with high-accuracy digital controllers commanding higher prices. Certification levels, such as IEC 61508 for functional safety, drive price differentiation for specialized products. Pricing softness affects analog electronic controllers due to their widespread installed base and lower performance. Semiconductor fabrication facilities in Taiwan exhibit low price sensitivity for ultra-precise digital controllers, while older industrial plants in Germany prioritize cost-effective replacements.
Supply Chain Analysis
Geopolitical tensions impacting trade routes between East Asia and Europe represent a structural supply chain risk. Supply concentrates in South Korea, Taiwan, and Japan for advanced microprocessors and specialized sensors. Critical components like high-precision analog-to-digital converters and communication modules are sourced from a limited number of specialized manufacturers. The distribution model combines direct sales from large automation conglomerates with specialized distributors and system integrators providing localized support and integration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The single loop controller market is undergoing an early-cycle expansion, driven by unprecedented investment in semiconductor fabrication and the widespread integration of IIoT protocols for remote monitoring.
For Market Incumbents: Harden core product offerings by investing in functional safety certifications, particularly IEC 61508, to address critical application requirements. Expand IIoT integration capabilities to counter PLC and DCS functional encroachment. Control distribution channels through enhanced service offerings, including remote diagnostics and loop tuning services. Invest in R&D for edge computing capabilities to reduce latency and provide local analytics.
For New Entrants and Emerging Players: Renewable energy systems, such as solar thermal fluid management and battery storage temperature regulation, represent the most penetrable entry point. Niche applications in water treatment, requiring specialized pH balancing or chlorine dosing, also offer white space. Partner with regional system integrators to offer bundled solutions that include installation and ongoing maintenance services, focusing on retrofit markets in Europe for legacy system upgrades.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because modern industrial processes depend on precise, reliable control. Target niche technology specialists with strong intellectual property in adaptive control algorithms or embedded edge processing capabilities. The increased adoption of OPC UA and MQTT communication protocols in new plant designs indicates an inflection point for interoperable solutions, signaling market readiness for advanced connectivity.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IIoT Protocol Integration | Enhances remote monitoring and diagnostics, increasing data accessibility for operational efficiency. |
| Invest in Functional Safety Certifications | Addresses stringent regulatory requirements like IEC 61508 for critical applications in chemical plants. |
| Develop Edge Computing Capabilities | Enables local analytics and optimization algorithms, reducing latency in distributed control systems. |
| Target Renewable Energy Applications | Penetrates an under-served market for rugged, reliable standalone controllers in solar and battery systems. |
| Form Strategic Partnerships with System Integrators | Expands market access and provides comprehensive service offerings for complex legacy system integration. |
Research Approach
Desk research of industry association reports, patent databases, and regulatory filings preceded structured interviews with process engineers, automation managers, system integrators, and regulatory compliance officers. This approach combined primary insights with secondary validation. The methodology incorporated both bottom-up and top-down triangulation to ensure data consistency and accuracy across various market segments.
The analytical framework assumed stable geopolitical conditions and consistent regulatory enforcement across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional economic growth. Compound Annual Growth Rates (CAGRs) were derived through regression analysis and validated against expert consensus. Semiconductor fab investment cycles and IIoT protocol adoption rates served as key industry-specific forecast inputs.
Practitioners should monitor shifts in global trade policies and rapid technological obsolescence for early signals of market revision. Forecasts reflect a specific set of assumptions and are subject to change based on unforeseen macroeconomic or regulatory developments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market