
 Wind Speed Sensor Market | 2026-2036
Wind Speed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Speed Sensor Market Analytics
The capital-intensity divergence between precision calibration laboratories and commodity assembly lines is unwinding competitive stability across the wind speed sensor supply base. Vaisala leverages in-house meteorological research stations to sustain premium positioning in polar and maritime environments. Campbell Scientific anchors its North American footprint through ruggedized datalogger integration. Thies Clima competes on German-engineered cup anemometer heritage across European wind farm certification workflows.
Wind speed sensors measure air velocity through mechanical rotation, ultrasonic time-of-flight, or optical Doppler principles, with typical operating ranges from 0 to 75 meters per second and accuracy thresholds of ±0.1 meters per second for turbine control applications. These instruments feed real-time data into turbine yaw systems, meteorological networks, and aviation hazard detection infrastructure. Ultrasonic anemometers command the fastest expansion trajectory as blade pitch control systems abandon mechanical cups for ice-resistant solid-state measurement. Fixed installations dominate value capture given twenty-year service life expectations atop offshore platforms and airport runways. The renewable energy end-user segment concentrates margin pools where IEC-compliant certification commands price premiums over general meteorological hardware.
FAA obstruction lighting standards and IEC 61400-12-1 power performance measurement protocols jointly elevate sensor calibration rigor across aviation and wind energy procurement channels. EPA regional haze monitoring programs and EU Green Deal offshore expansion targets amplify demand for coastal measurement networks. Stakeholders must weigh ultrasonic migration capex against extended maintenance intervals when specifying next-generation turbine sensor packages.
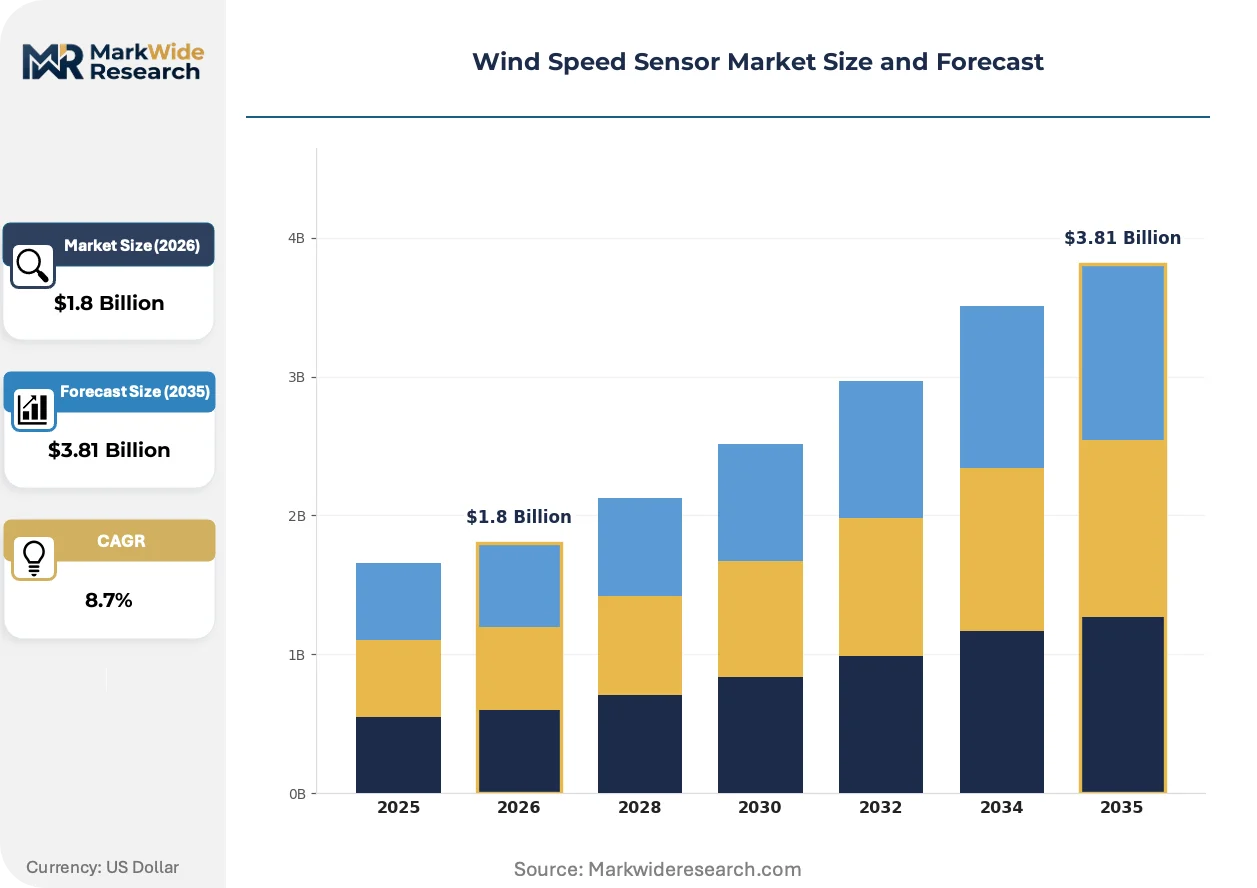
Market Dynamics
Ultrasonic time-of-flight technology is decomposing the mechanical cup anemometer installed base across offshore wind farms, forcing incumbent suppliers to reconfigure calibration laboratories and field service networks around solid-state architectures.
Growth Catalysts
- EU Green Deal offshore expansion:The European Commission's binding renewable targets mandate floating wind capacity additions in the North Sea and Baltic Sea, driving procurement of ice-resistant ultrasonic units for turbine nacelles.
- FAA obstruction lighting standards:Revised aviation hazard protocols require redundant wind measurement at commercial airports, expanding the addressable market for dual-path ultrasonic sensors on runway approach systems.
- Blade pitch control digitization:Original equipment manufacturers are abandoning mechanical transmission linkages in favor of direct-drive electromechanical systems that demand higher-frequency wind data inputs.
Market Restraints
- Precision calibration bottleneck:IEC 61400-12-1 certification requires wind tunnel traceability to national metrology institutes, limiting qualified laboratory capacity in Brazil and India.
- Rare earth magnet dependency:Neodymium price volatility affects ultrasonic transducer actuator assemblies, concentrating supply risk on Chinese processing facilities.
- Mechanical cup residual demand:Budget-constrained meteorological networks in sub-Saharan Africa and Central Asia continue specifying heritage cup anemometers, fragmenting procurement volumes.
Strategic Opportunities
- US Inflation Reduction Act offshore leasing:Bureau of Ocean Energy Management lease rounds in the Gulf of Maine and Pacific Northwest create first-mover positioning for turbine-integrated sensor packages.
- Digital twin convergence:LiDAR wake characterization combined with nacelle-mounted point measurements enables predictive maintenance algorithms that extend sensor replacement cycles.
- Aviation hazard detection retrofit:Secondary airports in Indonesia and Vietnam face ICAO compliance deadlines, opening channel partnerships with regional systems integrators.
Industry Challenges
- Meteorological calibration technician scarcity:Wind tunnel operation and uncertainty quantification expertise concentrates in Northern European and North American research institutions, constraining field service expansion.
- Legacy datalogger integration:Campbell Scientific and Vaisala proprietary protocols create friction when retrofitting ultrasonic units onto existing SCADA architectures at aging onshore wind farms.
- IEC 61400-12-1 revision timeline:Pending updates to power performance measurement standards delay procurement decisions as developers await finalized accuracy requirements for floating platform applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Speed Sensor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Anemometers, Fixed Anemometers, Ultrasonic Anemometers, Cup Anemometers End User: Aerospace, Meteorology, Renewable Energy, Marine Technology: Mechanical, Digital, Laser, Optical Application: Weather Monitoring, Wind Energy Production, Aviation Safety, Research |
| Companies Covered | Vaisala, Campbell Scientific, Met One Instruments, Thies Clima, Columbia Weather Systems, Optical Scientific, R. M. Young, Dyacon, Lufft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Speed Sensor Market Evolving Landscape
Measurement modality substitution is compressing maintenance schedules and recalibration intervals across wind energy and meteorological infrastructure. Three distinct vectors are reshaping competitive positioning and buyer specification behavior.
Ultrasonic time-of-flight sensing is decomposing the mechanical cup anemometer's dominance in turbine nacelle applications. Offshore wind farm operators in the North Sea and Baltic Sea are specifying solid-state units at replacement cycles, eliminating bearing wear and ice accumulation failure modes. This technology shift is compressing the addressable market for precision-machined cup assemblies while expanding demand for MEMS-grade transducer fabrication capacity.
REACH substance restrictions and RoHS compliance deadlines are forcing sensor manufacturers to reformulate potting compounds and PCB substrates. The European Chemicals Agency's candidate list expansion affects conformal coating chemistry for maritime-rated enclosures, pushing suppliers toward silicone-alternative formulations. Wind farm certification bodies in Germany and Denmark are now requiring material declaration documentation as a standard procurement gate.
Buyer specification behavior is hardening around twenty-year service life guarantees with fixed-price maintenance clauses. Independent power producers are unbundling sensor procurement from turbine OEM supply agreements, creating direct purchasing relationships with Vaisala and Thies Clima. This channel disintermediation is most visible in the UK and Dutch offshore sectors, where project finance covenants mandate equipment traceability outside original turbine supply chains.
Wind Speed Sensor Market Segmentation
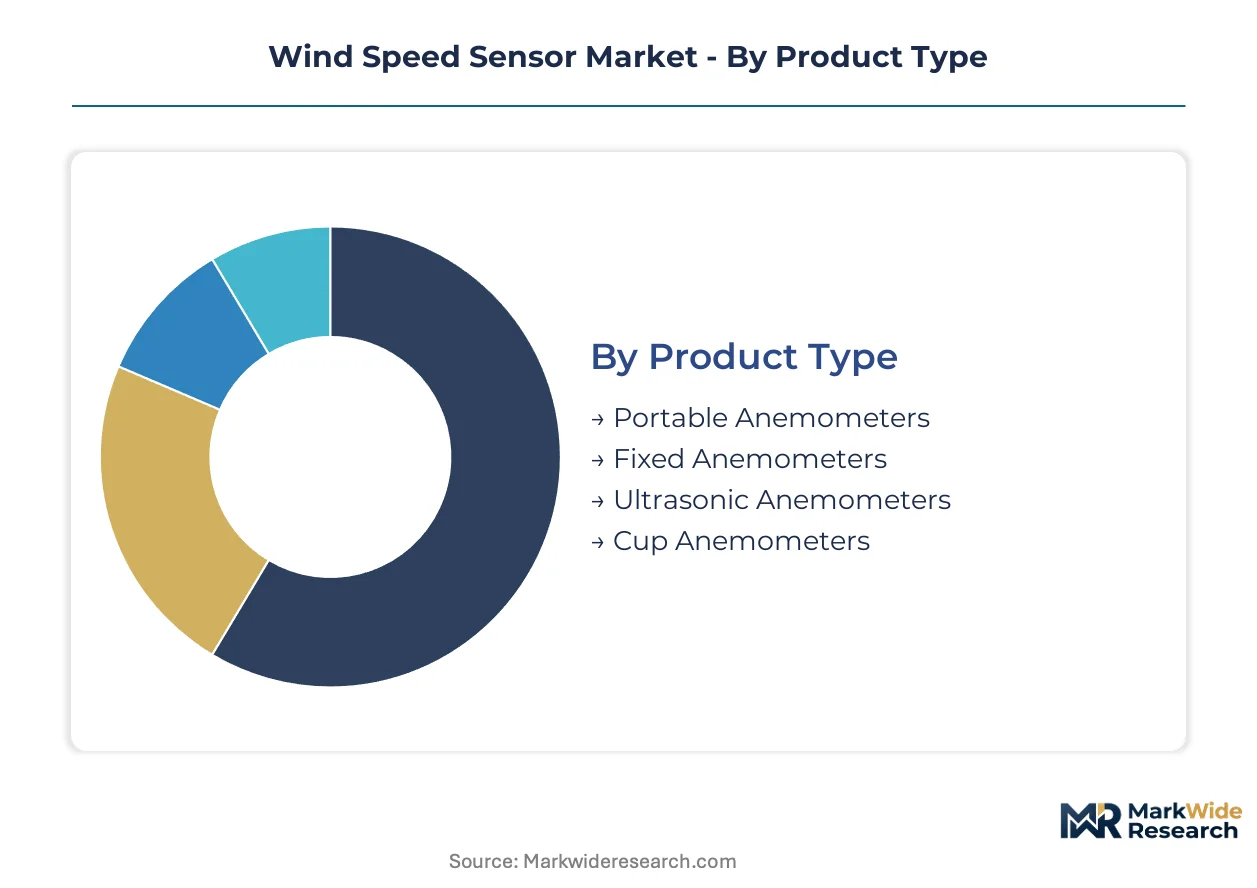
Wind speed sensor procurement patterns diverge sharply across installation permanence, end-use certification requirements, and measurement modality. Buyers in offshore wind and commercial aviation demand IEC-compliant fixed installations with traceable calibration chains, while meteorological networks in emerging economies prioritize portable units for rapid deployment flexibility.
Product Type:
Domestic assembly capacity for cup anemometers concentrates in Germany and China, whereas ultrasonic unit fabrication depends on Taiwanese MEMS foundries and Finnish transducer specialists serving export markets.
- Portable Anemometers:Battery-powered handheld units deploy magnetically-mounted cup assemblies or compact ultrasonic arrays for field meteorologists and construction site managers. Demand clusters with national weather services in India and Brazil funding mobile observation networks, constrained by budget cycles that favor lowest-acquisition-cost specifications over calibration rigor.
- Fixed Anemometers:Permanent installations atop turbine nacelles, airport control towers, and offshore platforms integrate heated enclosures and redundant sensing paths. Northern European wind farm developers drive procurement volumes through direct purchasing agreements that bypass turbine OEM markups.
- Ultrasonic Anemometers:Solid-state time-of-flight measurement eliminates moving parts for ice-prone maritime environments.
- Cup Anemometers:Precision-machined three-cup rotors persist in budget meteorological networks and heritage SCADA architectures.
Fixed anemometers command the established base. The steepest expansion runs through ultrasonic anemometers.
End User:
Margin capture stratifies across certification intensity, with aviation and offshore wind applications demanding laboratory-traceable uncertainty budgets that general meteorological deployments bypass.
- Renewable Energy:Turbine nacelle and meteorological mast installations feed yaw control, blade pitch, and power curve verification workflows. Procurement concentrates with independent power producers in the United Kingdom, Germany, and Denmark who unbundle sensor specification from turbine supply agreements to satisfy project finance covenants.
- Aerospace:Runway approach systems and obstruction lighting infrastructure require FAA-certified redundant wind measurement with dual-path ultrasonic validation. Secondary airports in Indonesia and Vietnam face ICAO compliance deadlines that accelerate retrofit demand.
- Meteorology:National observation networks and research institutions deploy mixed sensor portfolios.
- Marine:Offshore platform helidecks and port operations specify corrosion-resistant enclosures.
Renewable energy anchors revenue concentration. Aerospace applications are climbing the fastest.
Technology:
Production cost structures separate mechanical heritage architectures from solid-state digital platforms requiring semiconductor-grade cleanroom fabrication.
- Digital:Solid-state ultrasonic and thermal anemometry platforms process time-of-flight or temperature differential signals through embedded firmware. Demand accelerates in Baltic Sea and North Sea floating wind projects where ice accumulation disables mechanical alternatives.
- Mechanical:Rotating cup and vane assemblies with magnetic or optical encoding persist in cost-constrained deployments. Sub-Saharan African meteorological networks and Central Asian climate stations specify these units despite higher maintenance burdens.
- Laser:Coherent Doppler LiDAR systems characterize wind fields across rotor diameters.
- Optical:Particle image velocimetry and laser Doppler anemometry serve research applications.
Mechanical technology retains the installed base. Digital platforms are gaining share fastest.
Application:
Specification complexity escalates with regulatory exposure, from research-grade uncertainty quantification to operational safety mandates in commercial aviation.
- Wind Energy Production:IEC 61400-12-1 power performance measurement and turbine control systems demand ±0.1 m/s accuracy with documented wind tunnel traceability. Offshore developers in Germany and the Netherlands specify twenty-year service life guarantees with fixed-price maintenance clauses.
- Aviation Safety:Runway wind shear detection and obstruction lighting control require redundant sensing with automatic failover protocols. FAA standards revision cycles drive replacement demand at US commercial airports.
- Weather Monitoring:Synoptic observation networks and agrometeorological stations prioritize deployment density over individual sensor precision.
- Research:Boundary layer meteorology and atmospheric physics applications demand multi-axis turbulence measurement.
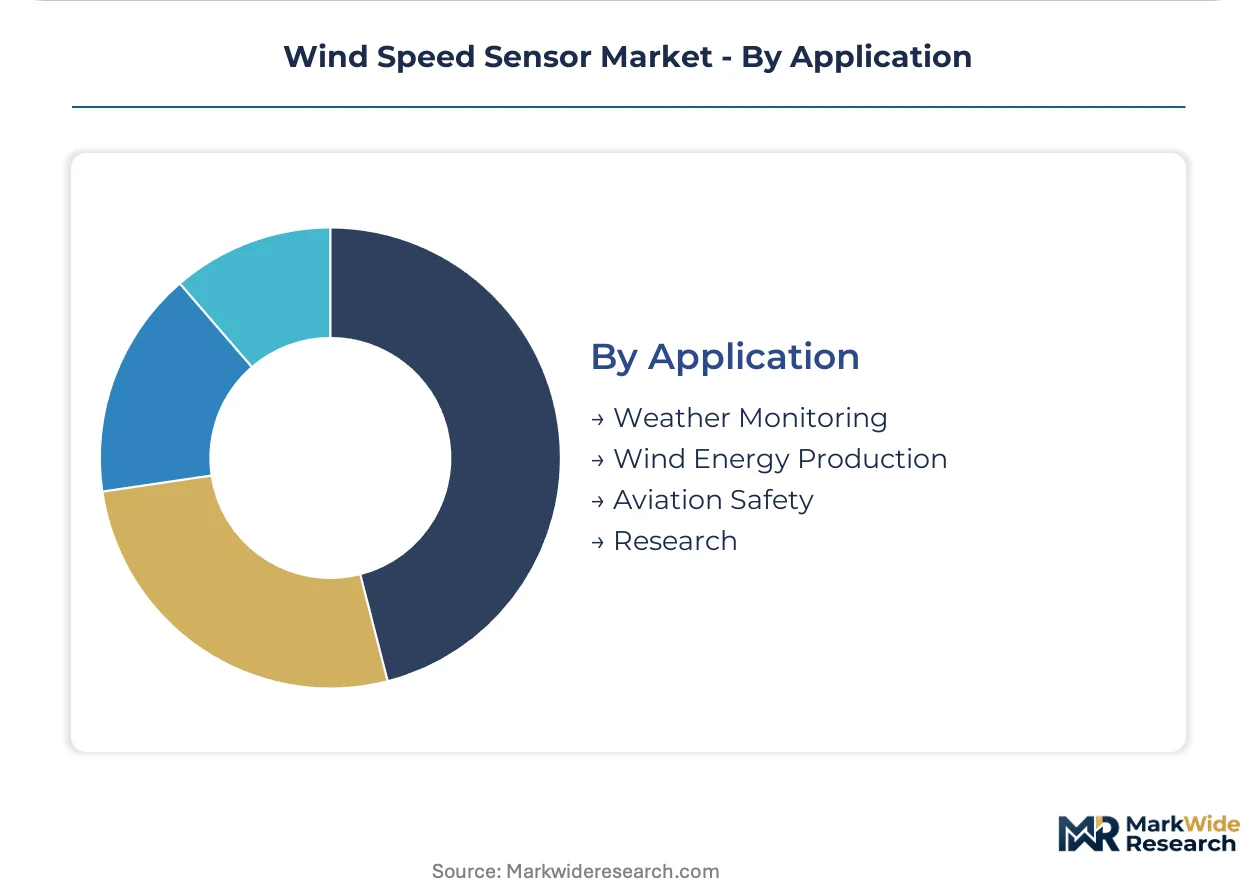
Weather monitoring holds volume leadership. Wind energy production is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Danish calibration laboratories while procurement volumes surge through Chinese manufacturing corridors. Northern European offshore developers command premium certification workflows. Asian assembly lines absorb commodity sensor demand.
United States
Bureau of Ocean Energy Management lease rounds in the Gulf of Maine and Pacific Northwest accelerate turbine-integrated sensor procurement. FAA obstruction lighting standards mandate redundant wind measurement at commercial airports. Massachusetts and California anchor demand for dual-path ultrasonic validation systems.
Germany
Offshore wind farm developers in the North Sea specify twenty-year service life guarantees with fixed-price maintenance clauses. EU Green Deal binding renewable targets mandate floating wind capacity additions. Hamburg and Bremerhaven concentrate calibration laboratory capacity for IEC 61400-12-1 certification.
China
Domestic wind turbine OEMs scale nacelle-mounted sensor procurement across coastal manufacturing corridors. National offshore wind expansion targets under dual carbon goals drive solid-state unit demand. Jiangsu and Guangdong provinces host MEMS foundry capacity for ultrasonic transducer fabrication.
United Kingdom
Independent power producers unbundle sensor procurement from turbine supply agreements to satisfy project finance covenants. Crown Estate leasing rounds for floating wind create first-mover positioning for ice-resistant units. Scottish and East Anglian offshore clusters dominate installation volumes.
India
National weather services fund mobile observation networks with budget-constrained portable unit specifications. CEA renewable purchase obligations expand meteorological mast deployments across Gujarat and Tamil Nadu wind corridors. Sub-Saharan African export markets absorb heritage cup anemometer production from Indian assembly lines.
Wind Speed Sensor Market Competitive Landscape
Concentration sits with meteorological instrumentation specialists possessing captive calibration infrastructure. Three to five established players control premium-tier certification workflows while Asian fabricators absorb volume-driven commodity demand. Strategic archetypes separate precision laboratory operators from MEMS-scale transducer specialists and ruggedized field equipment providers. Competitive moves center on backward integration into transducer fabrication and channel disintermediation toward direct independent power producer relationships.
Among Finnish and German precision instrumentation specialists, Vaisala Oyj and Thies Clima GmbH exemplify the calibration-anchored archetype with meteorological research station networks sustaining premium positioning. Campbell Scientific Inc. occupies a position within the North American ruggedized datalogger integration tier. These three entities represent distinct competitive vectors: polar and maritime environment specialization, German-engineered heritage workflows, and datalogger protocol ecosystem control.
| Leading Market Players |
|---|
| Vaisala |
| Campbell Scientific |
| Met One Instruments |
| Thies Clima |
| Columbia Weather Systems |
| Optical Scientific |
| R. M. Young |
| Dyacon |
| Lufft |
| Others |
Value Network & Pricing Analysis
IEC 61400-12-1 certification gates both supply qualification and price differentiation simultaneously, bifurcating the market between traceable laboratory-grade units and commodity assemblies. Calibration infrastructure scarcity in Northern Europe and North America concentrates premium pricing power with established metrology specialists, while Asian fabrication corridors absorb volume-driven demand for lower-tier specifications.
Pricing Analysis
Configured-to-order pricing for IEC-certified units commands spreads of 40-60% above standard catalog specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and wind tunnel traceability depth. Cost compression in the economy tier is intensifying because Indian and Chinese assembly lines are scaling cup anemometer output for budget meteorological networks. Independent power producers in Northern Europe exhibit the lowest price sensitivity, prioritizing twenty-year service life guarantees over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of neodymium magnets and MEMS-grade transducers characterizes procurement behavior among ultrasonic anemometer specialists facing rare earth price volatility. Component fabrication concentrates in Taiwan, Finland, and Germany, with final assembly distributed across Chinese coastal provinces and Indian industrial corridors. Supply chain risk rests on single-source vulnerability for precision-machined cup assemblies sourced from German heritage suppliers. Distribution runs through turbine OEM channel partnerships and direct procurement relationships with offshore wind developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind tunnel operation expertise and IEC certification accreditation represent scarce, non-replicable assets that concentrate competitive advantage among a handful of Northern European and North American institutions. This capability gap constrains field service expansion and limits qualified laboratory capacity in high-growth procurement corridors.
For Market Incumbents: Consolidate calibration infrastructure through captive laboratory investments in Hamburg and Bremerhaven to defend against ultrasonic technology substitution eroding mechanical cup maintenance revenue. Deepen backward integration into MEMS transducer fabrication through partnerships with Taiwanese foundries, securing supply continuity for solid-state product lines. For New Entrants and Emerging Players: Anchor in secondary airport retrofit opportunities across Indonesia and Vietnam where ICAO compliance deadlines outpace incumbent service capacity. Target portable anemometer specifications for Indian and Brazilian national weather services, leveraging lowest-acquisition-cost procurement preferences to establish volume footholds before premium-tier migration. For Investors and Strategic Acquirers: IEC 61400-12-1 revision timelines reshape the acquisition landscape by delaying procurement decisions and concentrating developer attention on certification-ready suppliers. Long-term viability favors precision instrumentation specialists with captive metrology infrastructure over commodity assemblers. Watch floating wind platform certification requirements as the inflection signal indicating premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | Captive wind tunnel capacity in Hamburg secures IEC 61400-12-1 certification workflows for North Sea offshore developers. |
| MEMS Transducer Backward Integration | In-house fabrication of ultrasonic arrays reduces dependency on Taiwanese foundry allocation cycles. |
| Direct IPP Channel Development | Bypassing turbine OEM markups captures margin pools in UK and Dutch offshore procurement. |
| Aviation Systems Integrator Partnership | ICAO compliance deadlines in Southeast Asia create retrofit demand for dual-path ultrasonic validation. |
| Twenty-Year Service Life Guarantee Programs | Fixed-price maintenance clauses align with project finance covenants in floating wind sectors. |
Research Methodology
Operator-level perspectives from turbine control engineers, offshore project developers, calibration laboratory technicians, and airport systems integrators anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from IEC standards documentation, FAA certification records, BOEM lease round filings, and EU Green Deal implementation reports. Bottom-up sensor shipment tracking and top-down renewable energy capacity projections enabled triangulation across independent analytical paths.
Sensitivity analysis tested forecast robustness against neodymium price volatility, floating wind deployment acceleration, and calibration laboratory capacity constraints. Segmentation modeling spanned product type, measurement technology, end-user industry, installation permanence, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new capacity addition trajectories, incorporating blade pitch control digitization adoption curves and ultrasonic substitution rates across the analysis window.
Material uncertainties — IEC 61400-12-1 revision content, rare earth supply disruptions, and floating wind platform certification timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology substitution velocity and procurement channel evolution. Revision becomes warranted when ultrasonic anemometer cost parity crosses mechanical cup thresholds in budget meteorological segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market