
 Global Rotation Laser Market | 2026-2036
Global Rotation Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rotation Laser Market Outlook
Market Context with Strategic Players
Commercial construction is broadening its share of rotation laser procurement as infrastructure budgets expand across developed and developing economies. Leica Geosystems leverages its Swiss engineering heritage to dominate high-precision surveying applications, while Trimble sustains technology leadership through integrated GNSS-laser fusion systems. Hilti Corporation anchors the professional trades segment with battery-powered jobsite tools that reduce setup time.
Technical Definition and Structural Segments
Rotation lasers are electro-optical instruments that project a continuously rotating beam of visible or infrared light to establish precise horizontal or vertical reference planes, typically operating at rotational speeds of 600–1,100 RPM with accuracy grades from ±1.5 mm to ±10 mm per 30 meters. The 360-degree product category captures the largest revenue pool due to its versatility in interior fit-out and exterior grading, while multi-line units represent the fastest-expanding segment as contractors seek simultaneous horizontal and vertical layout capability. Fiber laser technology occupies the premium tier with superior beam coherence and temperature stability, whereas laser diode systems compete on cost and portability for general construction use.
Regulatory Frame and Forward-Looking Close
The US OSHA regulates laser exposure limits on construction sites under 29 CFR 1926, while the EU Machinery Directive and CE marking framework mandate eye safety interlocks and emission classification labeling. Japan's METI enforces JIS standards for measurement instrument precision that effectively gate market access for imported equipment. Stakeholders must monitor evolving IEC 60825 laser safety classifications and anticipate which national regulators will next mandate connected calibration logging for audit trails.
Market Dynamics
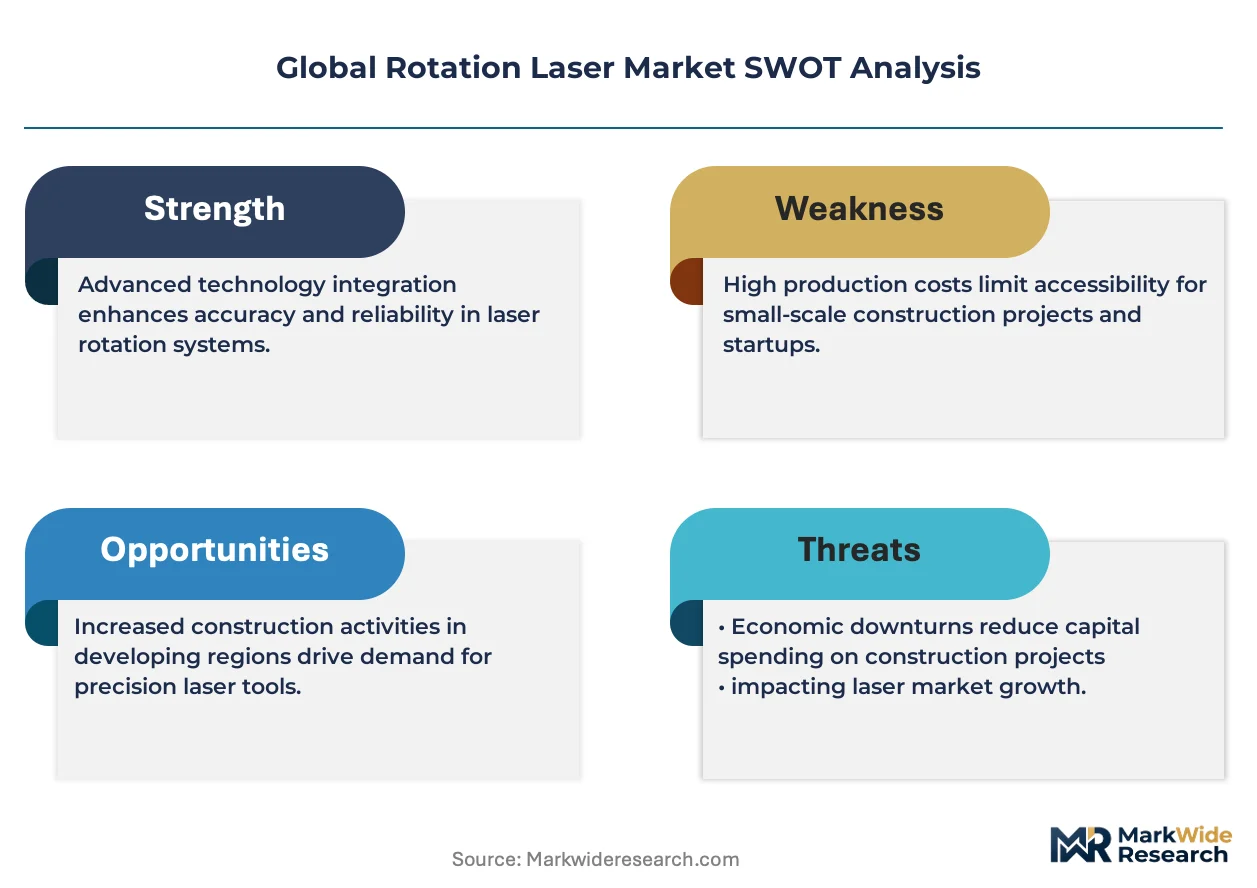
The rotation laser market is experiencing a structural compression as precision requirements from infrastructure digitization collide with supply chain reconfiguration for electro-optical components. Self-leveling algorithms and solid-state beam generation are displacing mechanical gyroscope systems in mid-tier equipment.
Growth Catalysts
- EU Machinery Directive updates:Mandated eye-safety interlocks and emission classification labeling are accelerating replacement cycles for non-compliant legacy equipment across German and French construction fleets.
- Fiber laser temperature stability:Superior beam coherence under thermal stress is capturing specification share in high-precision surveying applications where ±1.5 mm accuracy grades are mandatory.
- China's high-speed rail zones:Linear infrastructure corridors are concentrating demand for 360-degree rotation lasers in trackbed grading and tunnel alignment workflows.
Market Restraints
- Laser diode supply concentration:German and Japanese component manufacturers control critical semiconductor laser sources, creating input vulnerability for price-competitive portable systems.
- OSHA 29 CFR 1926 compliance costs:Exposure limit monitoring and worker certification requirements add operational friction for US commercial contractors deploying multiple units per site.
- Total station substitution:Integrated GNSS-reflectorless measurement systems are capturing layout workflows that previously required dedicated rotation laser setups.
Strategic Opportunities
- India's infrastructure corridors:National highway and metro expansion projects remain underpenetrated by automated grade-control systems, creating first-mover positioning for precision instrument suppliers.
- GNSS-laser convergence:Fusion systems combining satellite positioning with rotating reference planes are opening specification channels in machine control for autonomous earthmoving equipment.
- Japan METI calibration mandates:Emerging requirements for connected calibration logging and audit trail documentation favor vendors with cloud-integrated instrument management platforms.
Industry Challenges
- IEC 60825-1 classification complexity:Multi-jurisdiction laser safety certification timelines delay product launches by 8-14 months as emission testing protocols diverge across notified bodies.
- Field technician skill stratification:Advanced self-leveling and remote diagnostic features require training investment that smaller commercial contractors resist, limiting penetration in the trades segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rotation Laser Market |
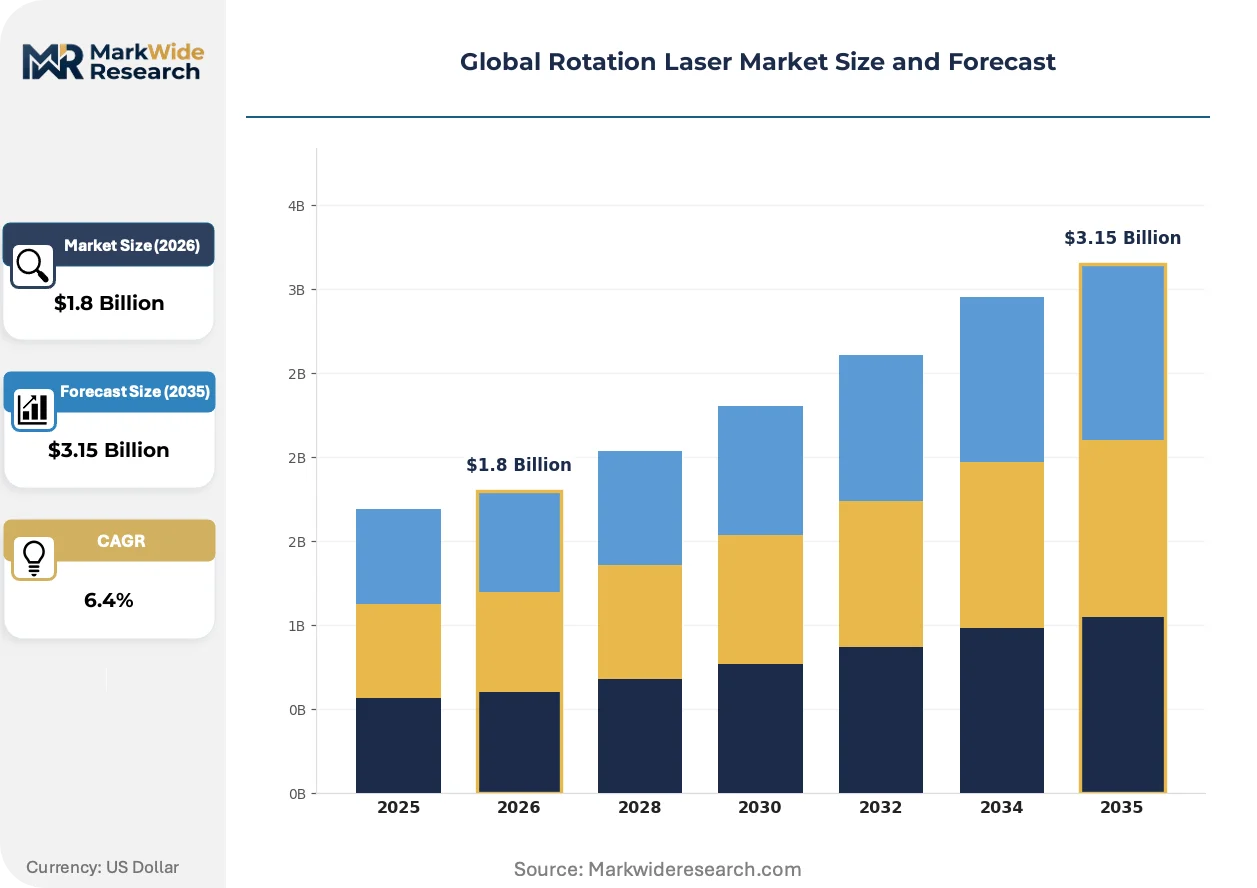
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, 360-Degree, Multi-Line End User: Construction, Surveying, Mining, Agriculture Technology: Laser Diode, Fiber Laser, Solid-State, CO2 Laser Application: Leveling, Aligning, Layout, Scanning |
| Companies Covered | Leica Geosystems, Trimble, Topcon, Hilti Corporation, DEWALT, Bosch, Milwaukee Tool, Johnson Level & Tool, Kapro Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rotation Laser Market Strategic Shifts
Digital integration is rewriting competitive differentiation as hardware margins compress and software-enabled workflow automation becomes the primary value capture mechanism. Vendors are racing to embed connectivity and machine-readable data outputs into field instruments.
Green laser diode technology is expanding into interior fit-out and underground construction applications where beam visibility in high-ambient-light conditions determines productivity. German and Japanese commercial contractors are specifying 515-532 nm wavelength instruments for concrete forming and ceiling grid layout. This visibility advantage is compressing demand for traditional red-beam units in enclosed environments where dust and lighting degrade red-wavelength performance.
OSHA's emphasis on precision excavation safety under 29 CFR 1926 Subpart P is mandating documented grade reference for trenching and shoring operations. US commercial construction fleets are retrofitting rotation lasers with data-logging capabilities to satisfy incident investigation protocols. The underground utility segment is most affected, with contractors upgrading to interlock-equipped units that disable emission when tilt sensors detect level deviation beyond calibrated thresholds.
Equipment-as-a-service models are displacing capital purchase patterns among mid-tier US commercial contractors facing compressed project margins. Hilti Fleet Management and similar programs bundle calibration, repair, and upgrade rights into monthly per-unit fees. This preference shift is most visible in the professional trades segment, where tool crib managers prioritize uptime guarantees over asset ownership and residual value recovery.
Global Rotation Laser Market Segmentation
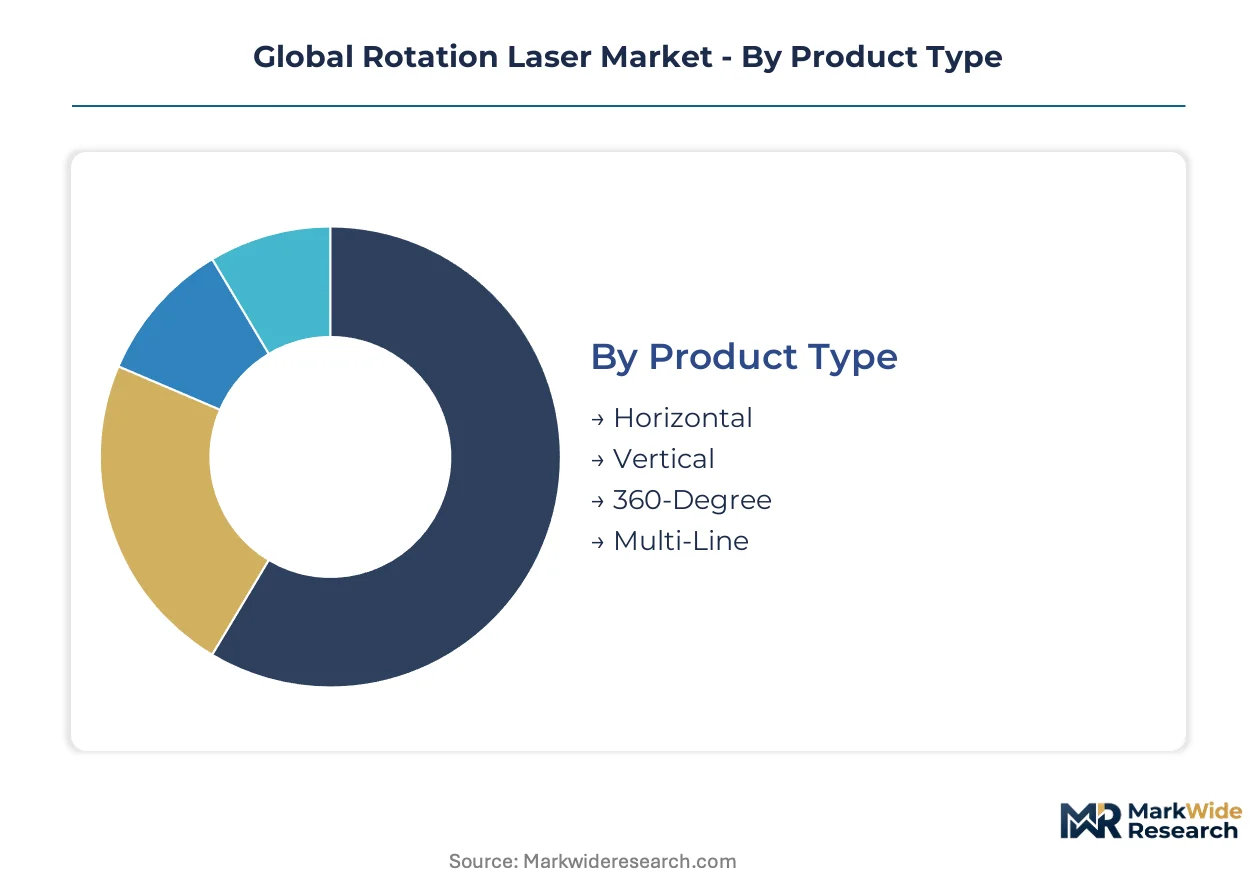
Rotation laser procurement patterns diverge sharply across technical specifications and deployment contexts. Specification-grade instruments command premium positioning in precision surveying, while portable units serve high-volume commercial construction workflows.
Product Type:
Beam projection geometry determines instrument versatility and price positioning across construction workflows.
- 360-Degree:Continuous rotating beam establishes complete horizontal reference planes without receiver repositioning. Demand concentrates in German infrastructure renewal corridors and China's high-speed rail expansion zones where site efficiency drives specification.
- Multi-Line:Simultaneous horizontal and vertical plane projection eliminates sequential setup operations. Contractors in interior fit-out and complex structural forming are specifying these units fastest as labor costs rise.
- Horizontal:Single-plane reference systems dominate legacy fleet composition and basic grading applications.
- Vertical:Dedicated plumb and alignment instruments serve structural steel and elevator shaft workflows.
Mature deployment sits with Horizontal. Newer deployment is concentrated in Multi-Line.
End User:
Customer sophistication and accuracy requirements stratify purchasing behavior and service expectations.
- Construction:Commercial contractors drive volume procurement across site preparation, concrete forming, and interior finishing. US OSHA trenching safety mandates under 29 CFR 1926 Subpart P are accelerating fleet upgrades with data-logging and interlock capabilities.
- Surveying:Geodetic and engineering surveyors specify ±1.5 mm accuracy grades with temperature-stable fiber laser sources. German and Swiss precision engineering traditions sustain specification dominance in this tier.
- Mining:Underground operations demand explosion-proof housings and dust-sealed optics for tunnel alignment and ventilation shaft plumb.
- Agriculture:Land leveling for irrigation efficiency employs cost-optimized diode systems with broad working ranges.
Established penetration sits with Surveying. Volume expansion is accelerating in Construction.
Technology:
Beam generation physics determines thermal stability, power consumption, and regulatory classification complexity.
- Fiber Laser:Doped silica gain medium delivers superior beam coherence and minimal wavelength drift across temperature extremes. German and Japanese component manufacturers control critical supply, creating input concentration for premium instrument assembly.
- Laser Diode:Semiconductor emission enables compact portable designs with battery operation. Green wavelength variants at 515-532 nm are displacing red-beam units in high-ambient-light interior applications.
- Solid-State:Crystal-based generation occupies mid-tier positioning between fiber performance and diode economy.
- CO2 Laser:Gas discharge systems persist in specialized industrial alignment with high-power requirements.
Technology leadership resides with Fiber Laser. Adoption momentum is strongest in Laser Diode.
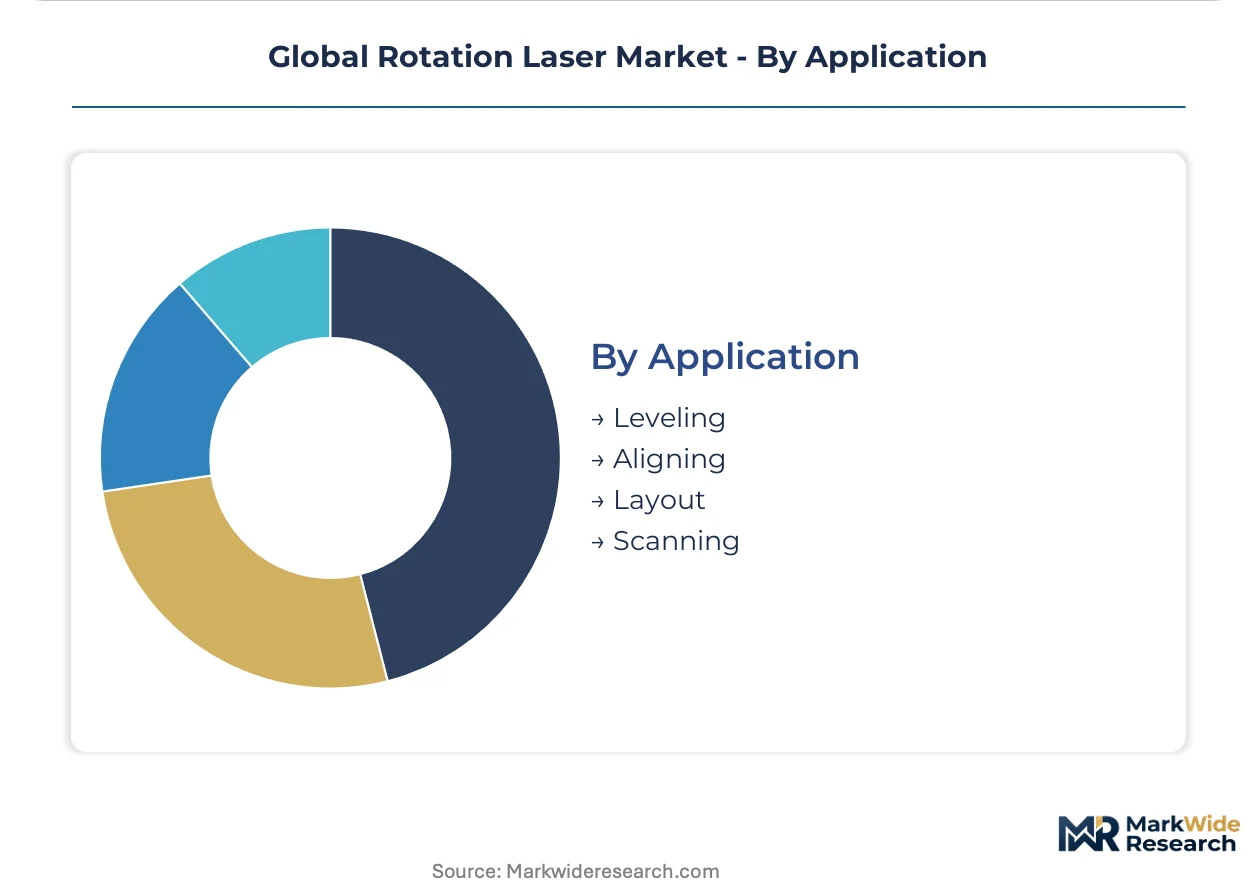
Application:
Workflow integration determines instrument feature prioritization and software connectivity requirements.
- Leveling:Grade control for excavation, foundations, and agricultural land forming represents the foundational use case with established operator training protocols.
- Aligning:Structural steel, machinery installation, and tunnel boring machine guidance demand highest precision with continuous verification.
- Layout:Point projection and reference line establishment for interior construction is gaining connected calibration logging capabilities under emerging Japan METI audit trail requirements.
- Scanning:Rotating beam integration with photogrammetric and LiDAR systems is opening machine-readable data output specifications for autonomous earthmoving equipment.
Conventional dominance rests with Leveling. Functional expansion is advancing fastest in Scanning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Chinese special economic zones for precision manufacturing are concentrating rotation laser demand through infrastructure tax incentives and bonded logistics parks serving construction equipment distribution.
United States
Commercial construction contractors in Texas and Florida are expanding fleet procurement of interlock-equipped rotation lasers to satisfy OSHA 29 CFR 1926 Subpart P documentation requirements for trenching safety. Federal infrastructure spending through the IIJA is channeling equipment budgets toward precision grade-control systems. The Southeast construction corridor from Atlanta to Houston is experiencing concentrated demand from underground utility contractors upgrading legacy equipment.
Germany
Infrastructure renewal corridors in Bavaria and North Rhine-Westphalia are driving specification-grade fiber laser procurement for high-speed rail and highway reconstruction. The EU Machinery Directive's updated laser classification standards are accelerating replacement cycles for non-compliant equipment in commercial construction fleets. Stuttgart and Munich industrial clusters are concentrating surveying instrument manufacturing and precision engineering expertise.
China
High-speed rail expansion zones in the Yangtze River Delta and Pearl River Delta are concentrating demand for 360-degree rotation lasers in trackbed grading and tunnel alignment workflows. GB standards for measurement instrument precision are tightening market access requirements for imported equipment. Chengdu and Xi'an inland logistics hubs are emerging as distribution nodes for western infrastructure corridors.
Japan
METI calibration mandates and emerging connected audit trail requirements are favoring vendors with cloud-integrated instrument management platforms in the Kanto and Kansai construction markets. JIS standards for measurement precision effectively gate market access for non-compliant imported rotation lasers. The Nagoya-Chubu industrial zone maintains concentration in precision electro-optical component manufacturing.
India
National highway and metro expansion projects in Maharashtra and Gujarat remain underpenetrated by automated grade-control systems, creating first-mover positioning opportunities for precision instrument suppliers. The Ministry of Road Transport and Highways is mandating documented grade reference for large-scale earthmoving contracts. The Delhi-Mumbai Industrial Corridor is concentrating demand for cost-optimized diode laser systems in land leveling applications.
Global Rotation Laser Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium surveying equipment consolidating around heritage engineering brands while portable construction tools fragment across power-tool conglomerates and regional fabricators. The market exhibits tiered concentration: fiber-laser precision instruments cluster under established European and Japanese specialists, mid-tier self-leveling systems compete across diversified industrial technology portfolios, and economy portable units fragment across Chinese and Taiwanese contract manufacturers. Dominant competitive moves include strategic partnerships between instrument makers and machine control software platforms, plus geographic expansion through localized calibration service networks.
Within the heritage precision tier, Leica Geosystems and Topcon exemplify Swiss and Japanese engineering traditions that sustain specification dominance in geodetic surveying applications. Trimble occupies a position bridging precision instrumentation with integrated positioning systems. Hilti Corporation anchors the professional trades segment through equipment-as-a-service models that bundle calibration and uptime guarantees into operational expenditure structures.
| Leading Market Players |
|---|
| Leica Geosystems |
| Trimble |
| Topcon |
| Hilti Corporation |
| DEWALT |
| Bosch |
| Milwaukee Tool |
| Johnson Level & Tool |
| Kapro Industries |
| Others |
Value Chain & Pricing Dynamics
EU Machinery Directive eye-safety mandates gate qualified supply for premium-tier rotation laser procurement, compressing vendor pools and amplifying pricing power for compliant manufacturers while spot-market diode sources face margin erosion from certification overhead.
Pricing Analysis
Lead-time-driven pricing stratification rewards premium positioning for IEC 60825-certified units with sub-90-day delivery windows, while spot inventory of legacy red-beam systems trades at discount. Three-tier pricing structure across fiber-laser precision, solid-state mid-tier, and diode-based portable levels separates surveying-grade accuracy from construction-grade portability. Cost compression in the economy tier intensifies because Chinese contract manufacturers are flooding distribution channels with uncalibrated units. Commercial contractors in the professional trades segment exhibit highest price sensitivity, whereas geodetic surveyors absorb premiums for temperature-stable beam coherence.
Supply Chain Analysis
Domestic-content mandates in China's high-speed rail zones and India's Delhi-Mumbai Industrial Corridor are reshaping sourcing patterns, forcing vendors to establish local assembly partnerships or forfeit specification eligibility. German and Japanese component manufacturers anchor critical semiconductor laser source supply, with doped silica gain media for fiber lasers and green-wavelength diodes for interior applications drawing from concentrated precision electro-optical clusters. Single-source vulnerability in laser diode supply creates exposure to export licensing disruptions. Distribution runs through construction equipment dealers and equipment-as-a-service fleet managers serving commercial contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotation laser market is consolidating around compliance-capable vendors as IEC 60825 certification timelines and METI audit-trail mandates force capital-constrained regional fabricators toward exit or acquisition.
For Market Incumbents: Deploy cloud-integrated calibration logging platforms to capture Japan METI compliance premiums and defend against total station substitution in machine control workflows. Deepen upstream control over fiber laser gain media supply through captive partnerships with Stuttgart and Nagoya-Chubu electro-optical clusters. Acquire regional service networks in India's Maharashtra and Gujarat corridors to anchor first-mover positioning before domestic-content rules harden. For New Entrants and Emerging Players: Launch via equipment-as-a-service fleet management models targeting US Southeast underground utility contractors facing OSHA 29 CFR 1926 Subpart P documentation mandates. Target India's national highway and metro expansion projects with cost-optimized green-diode systems specified for high-ambient-light concrete forming. Pursue white-label partnerships with Chinese bonded logistics parks serving Yangtze River Delta infrastructure zones. For Investors and Strategic Acquirers: Leica Geosystems and Trimble patent filings for GNSS-laser fusion architectures are the leading indicator that specification-grade surveying instrumentation is tilting toward integrated positioning ecosystems. Five-to-ten-year viability favors vendors with backward integration into fiber laser component supply and software-defined workflow automation capabilities. Target acquisition archetypes are mid-tier self-leveling specialists with established calibration service footprints in German infrastructure renewal corridors.| Strategic Initiative | Industry Significance |
|---|---|
| GNSS-Laser Fusion System Development | Trimble and Topcon are anchoring machine control specifications for autonomous earthmoving equipment. |
| Cloud-Integrated Calibration Platforms | Japan METI audit-trail mandates favor vendors with connected instrument management capabilities. |
| Green Laser Diode Product Line Expansion | 515-532 nm wavelength instruments capture interior fit-out share from red-beam legacy units. |
| Equipment-as-a-Service Fleet Programs | Hilti Fleet Management models displace capital purchase patterns among US commercial contractors. |
| Localized Assembly Partnerships | China GB standards and India domestic-content rules require regional manufacturing presence. |
Study Parameters
Multi-period observation of fiber laser component pricing, IEC 60825 certification timelines, and equipment-as-a-service adoption rates anchored the trend analysis, supplemented by interviews with construction fleet managers, surveying instrument distributors, precision electro-optical component procurement leads, and aftermarket calibration service heads. Secondary validation drew from customs trade data for laser diode imports, SEC filings of diversified industrial technology portfolios, EU Machinery Directive implementation notices, and Japan METI measurement instrument regulatory updates. Bottom-up channel checks across German, Chinese, and US distribution networks were triangulated against top-down infrastructure spending flow analysis.
Input-output matrices mapped beam generation technology costs to end-use price elasticities across surveying, construction, mining, and agriculture segments, with volume and value outputs derived through iterative reconciliation across the projection horizon. Segmentation dimensions modeled include beam projection geometry, accuracy grade tier, application workflow, and regional regulatory cluster. CAGRs were computed from fitted growth curves incorporating infrastructure budget trajectories, replacement cycle dynamics for non-compliant legacy equipment, and penetration rates for self-leveling algorithms displacing mechanical gyroscope systems.
Supply chain disruptions in German and Japanese laser diode manufacturing, acceleration of total station substitution in layout workflows, and divergence in national laser safety classification protocols are the dominant revision risks to the forecast framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Europe Gas Sensors Market