
 Global Sonar Systems and Technology Market | 2026-2036
Global Sonar Systems and Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sonar Systems and Technology Market Foresight
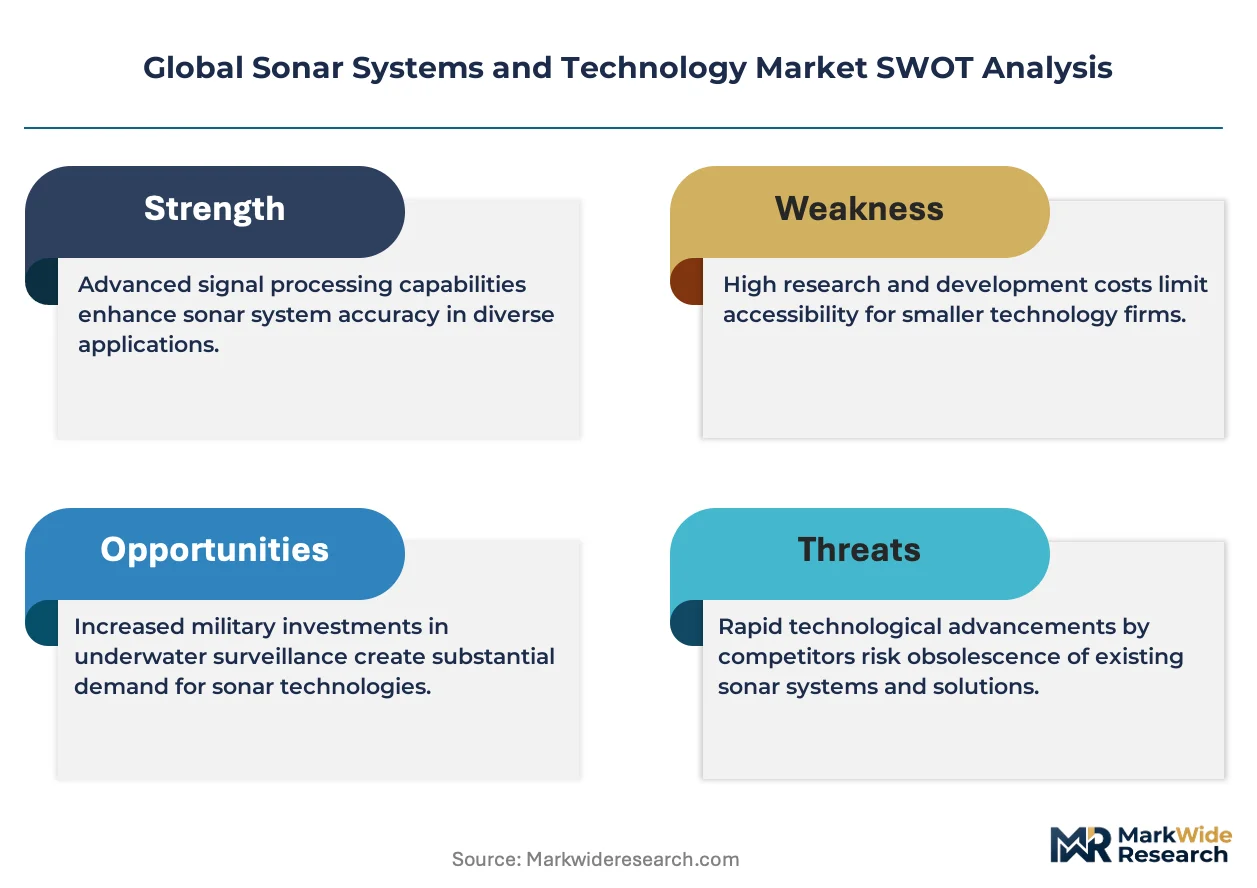
Acoustic engineer shortages across NATO defense industrial bases is rotating procurement timelines toward longer-term sole-source contracts. Thales Group leverages its Franco-British supply chain to sustain transatlantic program continuity. Lockheed Martin anchors US Navy sonar modernization through integrated combat system architectures. L3Harris Technologies competes aggressively in the towed array segment with modular open-system designs.
Sonar systems and technology encompass active and passive acoustic detection platforms operating across frequencies from infrasonic to ultrasonic bands, transmitting or receiving sound pulses to map, track, or classify submerged objects and seafloor topography. These systems serve military undersea warfare, commercial fishery location, and hydrographic survey missions through pulse-compression algorithms and beamforming arrays. Multibeam sonar leads commercial offshore exploration with wide-swath bathymetric coverage, while synthetic aperture sonar dominates mine countermeasures with centimetric resolution. Hull-mounted systems remain the mature revenue base for naval surface combatants, though portable sonar units represent the fastest-growing product category as expeditionary forces prioritize rapid deployment.
US Navy program offices coordinate with the FAA for spectrum management of airborne dipping sonar, while EDA member states align procurement through NATO's Maritime Unmanned Systems initiative and the EU's Permanent Structured Cooperation framework. The International Maritime Organization's underwater noise guidelines increasingly shape transducer design specifications for commercial systems. Stakeholders must monitor convergence between national security classification protocols and commercial dual-use export control regimes as acoustic sensing becomes embedded in autonomous underwater vehicle swarms.
Market Dynamics
Naval modernization programs are compressing procurement cycles while acoustic engineer shortages across NATO defense industrial bases force program offices toward longer-term sole-source contracting arrangements.
Growth Catalysts
- NATO Maritime Unmanned Systems initiative:EDA member states coordinate pooled procurement of autonomous underwater vehicle sonar payloads, standardizing transducer interfaces across national fleets.
- Synthetic aperture processing:Centimetric resolution capabilities in mine countermeasures are displacing conventional side-scan systems in naval survey tenders.
- Norwegian undersea domain awareness expansion:Arctic surveillance priorities drive hull-mounted and towed array installations along the Barents Sea littoral.
Market Restraints
- Rare earth magnetostrictive materials:Terbium and dysprosium supply concentration in Chinese processing facilities creates transducer manufacturing vulnerability.
- ITAR classification protocols:US export controls on acoustic signal processing algorithms fragment supplier access to allied naval programs.
- Passive sonar performance ceilings:Biological noise in littoral zones limits detection ranges against quiet diesel-electric submarines.
Strategic Opportunities
- EU Permanent Structured Cooperation framework:PESCO-funded joint capability programs pool R&D for next-generation variable-depth sonar arrays.
- Commercial fishery AI integration:Machine learning-enhanced fish school classification creates dual-use technology transfer pathways.
- Portable expeditionary units:Rapid deployment requirements from amphibious forces open modular open-system architectures for non-traditional suppliers.
Industry Challenges
- Acoustic engineer pipeline collapse:University oceanography program closures in the United Kingdom and France constrain specialist hiring for transducer design.
- Legacy combat system integration:AN/SQQ-89 and comparable integrated undersea warfare suites require backward-compatible signal processing upgrades.
- ISO/IEC 60565 calibration certification:Extended timeline for hydrophone standardization approval delays product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sonar Systems and Technology Market |
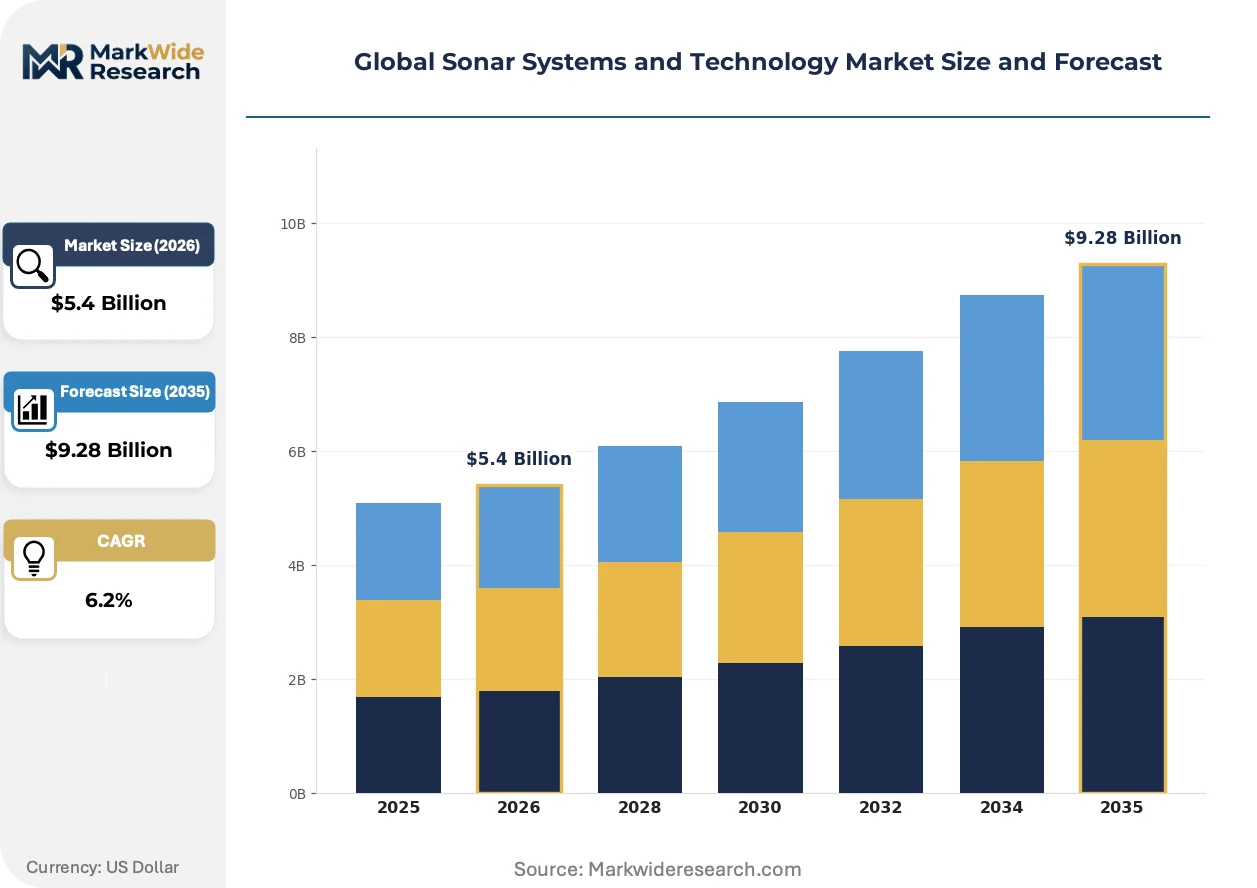
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Sonar, Passive Sonar, Synthetic Aperture Sonar, Side-Scan Sonar, Multibeam Sonar Application: Submarine Navigation, Underwater Mapping, Fisheries Management, Ocean Research, Security Surveillance Product Type: Hull-Mounted Systems, Towed Array Sonar, Diver-Borne Systems, Fixed Underwater Sonar, Portable Sonar Units End User: Navy Forces, Marine Research Institutes, Offshore Exploration Firms, Commercial Fishermen, Port Authorities |
| Companies Covered | Thales Group, Lockheed Martin Corporation, L3Harris Technologies, Raytheon Technologies, Teledyne Technologies Incorporated, General Dynamics Corporation, Atlas Elektronik, Kongsberg Maritime, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sonar Systems and Technology Market Shifts & Advancements
Signal processing architectures are fragmenting platform requirements as artificial intelligence reshapes detection workflows and spectrum management protocols force coordination between maritime and aviation authorities.
Synthetic aperture sonar is decomposing traditional bathymetric survey value chains. Naval mine countermeasures commands in the United States and United Kingdom are fielding SAS-equipped autonomous underwater vehicles for centimetric-resolution bottom mapping. This capability compression eliminates the need for separate high-frequency identification sonars, collapsing procurement categories.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing transducer encapsulant reformulation. Manufacturers serving European commercial offshore markets must qualify alternative polyurethane and epoxy compounds for deep-pressure hull penetration. The International Maritime Organization's underwater noise guidelines amplify this pressure, tightening acoustic source level specifications for multibeam systems operating in marine protected areas.
Defense procurement offices are consolidating sonar subsystem awards into platform-level combat system contracts. The US Navy's integrated undersea warfare program office now specifies open-architecture interfaces rather than standalone sensor procurements. This bundling concentrates supplier relationships with systems integrators while squeezing standalone transducer vendors into tier-2 subcontractor roles, with effects most visible in hull-mounted array competitions.
Global Sonar Systems and Technology Market Segmentation
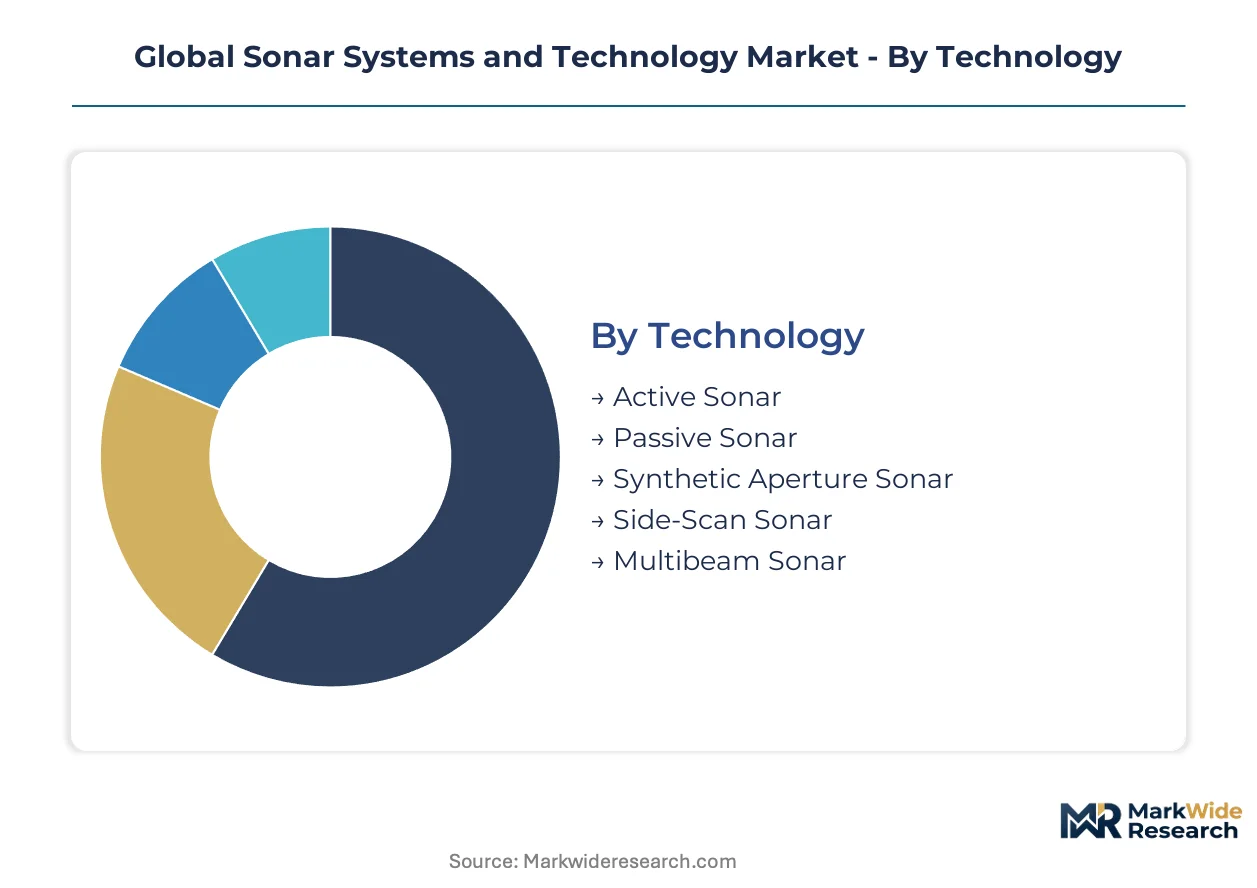
Segmentation reveals how acoustic detection requirements fragment across mission profiles, from naval combat systems demanding classified signal processing to commercial operators prioritizing portable deployment speed. Understanding these divides exposes where technology substitution pressures concentrate and where incumbent architectures retain defensive moats.
Technology:
Passive sonar architectures face intensifying substitution pressure from AI-enhanced active systems that reduce operator dependency and compress detection timelines.
- Active Sonar:Systems transmit acoustic pulses and analyze return echoes to determine target range, bearing, and velocity through Doppler processing. Demand concentrates in US Navy integrated combat system upgrades where open-architecture mandates favor modular pulse-compression implementations.
- Passive Sonar:Arrays detect radiated noise from submerged targets without emitting detectable signals, preserving platform stealth. Norwegian Barents Sea surveillance programs and Royal Navy Astute-class upgrades sustain procurement despite performance ceilings against quiet diesel-electric submarines in littoral biological noise.
- Synthetic Aperture Sonar:Motion-compensated beamforming achieves centimetric resolution for mine countermeasures.
- Side-Scan Sonar:Towed near-bottom platforms produce acoustic imagery for seabed classification.
- Multibeam Sonar:Wide-swath bathymetric coverage dominates commercial offshore survey.
Active sonar retains volume leadership; synthetic aperture sonar holds the steepest expansion curve.
Application:
Cost tier stratification separates sovereign defense budgets from constrained research and commercial fishing allocations, compressing procurement flexibility at lower expenditure levels.
- Submarine Navigation:Hull-mounted obstacle avoidance and terrain-following sonars integrate with inertial navigation suites for under-ice operations. US Navy Virginia-class and Royal Navy Dreadnought programs sustain demand for high-frequency forward-looking arrays.
- Security Surveillance:Fixed underwater sensor networks protect critical infrastructure against unauthorized intrusion. Port Authority of Singapore and Norwegian Coastal Administration deployments demonstrate dual-use potential for harbor protection and environmental monitoring integration.
- Underwater Mapping:Hydrographic survey vessels deploy multibeam and interferometric systems for nautical chart production.
- Fisheries Management:Scientific echo-sounders assess biomass and species distribution for quota enforcement.
- Ocean Research:Academic institutions deploy autonomous platforms for long-term acoustic monitoring.
Submarine navigation commands the largest budget allocation; security surveillance applications are climbing fastest as critical infrastructure protection mandates expand.
Product Type:
Volume concentration in expeditionary forces rotates procurement toward rapidly deployable configurations that sacrifice permanent integration for operational flexibility.
- Portable Sonar Units:Battery-operated, man-portable systems enable rapid emplacement by amphibious and special operations forces without platform modification. US Marine Corps littoral regiment stand-up and UK Commando Force modernization programs prioritize these configurations for distributed maritime operations.
- Hull-Mounted Systems:Permanent bow and flank arrays remain the structural revenue base for surface combatant construction programs. NATO Frigate for Europe and US Navy Constellation-class procurements sustain demand despite integration complexity with legacy combat management systems.
- Towed Array Sonar:Variable-depth trailing sensors extend detection range beyond hull-mounted limitations.
- Fixed Underwater Sonar:Seabed-mounted networks provide persistent area denial.
- Diver-Borne Systems:Hand-held or helmet-mounted devices support mine clearance and reconnaissance.
Hull-mounted systems retain volume leadership; portable sonar units hold the steepest expansion curve.
End User:
Customer type fragmentation reflects divergent certification requirements, with naval specifications demanding ITAR-compliant supply chains that exclude commercial operators from technology access.
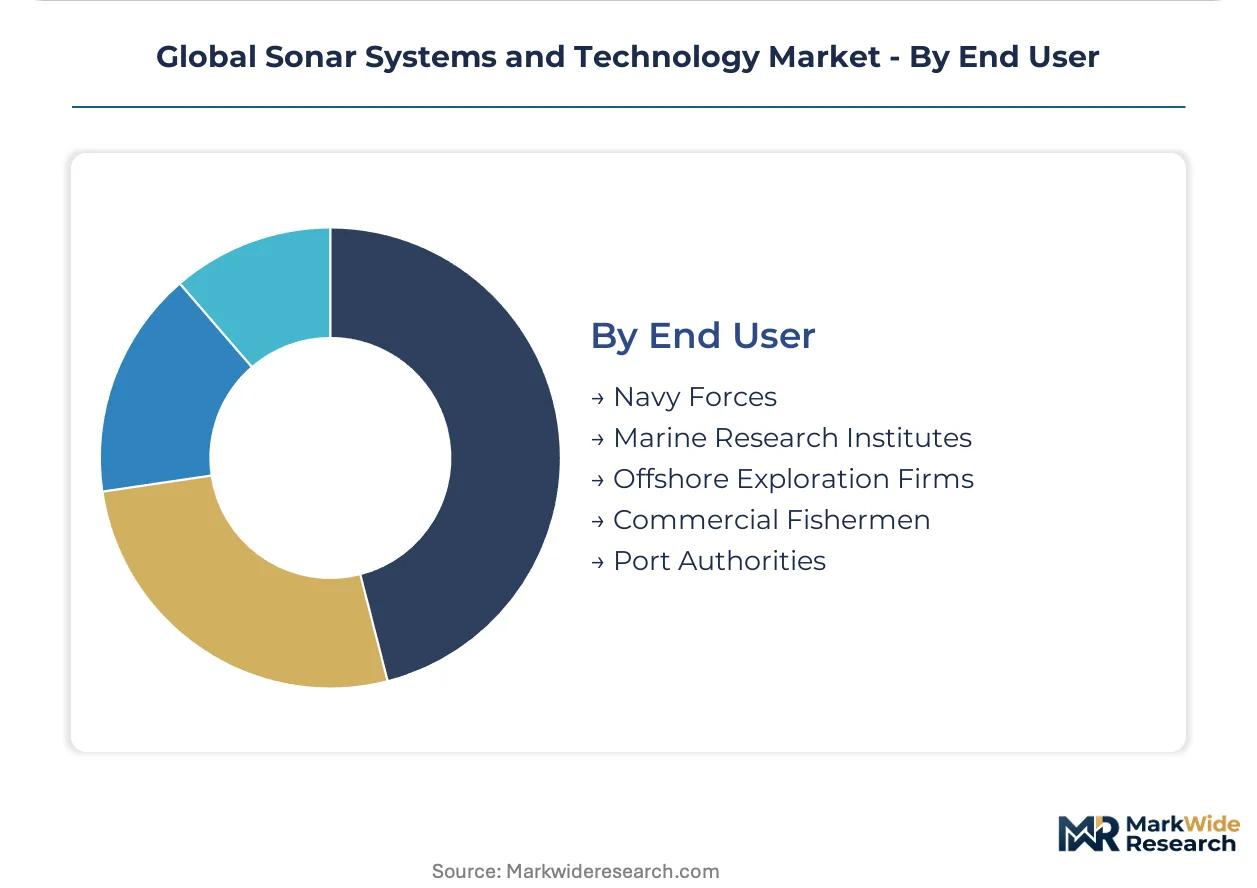
- Navy Forces:Sovereign naval programs specify integrated undersea warfare suites with classified signal processing algorithms and transducer materials subject to export control. US, UK, and Norwegian program offices dominate procurement volume through consolidated combat system contracts.
- Offshore Exploration Firms:Oil and gas operators deploy multibeam and sub-bottom profiler systems for pipeline route survey and site characterization. North Sea decommissioning programs and offshore wind farm developments in UK and Norwegian waters sustain commercial demand.
- Marine Research Institutes:Academic and governmental oceanographic organizations prioritize open-data compatibility and long-term deployability.
- Commercial Fishermen:Vessel-mounted echo-sounders and net sonars optimize catch efficiency.
- Port Authorities:Harbor management agencies deploy security and navigation sonars for vessel traffic control.
Navy forces retain volume leadership; offshore exploration firms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Arctic surveillance states prioritizing fixed seabed networks and expeditionary forces demanding portable rapid-deployment units. Sovereign navies in NATO's northern tier invest in persistent undersea domain awareness, while Pacific operators emphasize modular open-architecture systems for distributed maritime operations.
United States
The US Navy's integrated undersea warfare program office consolidates sonar subsystem awards into platform-level combat system contracts, compressing supplier tiers. FAA coordination governs spectrum management for airborne dipping sonar operations. Defense industrial concentration clusters around Lockheed Martin's Syracuse operations and L3Harris facilities in Massachusetts, where modular towed array production scales for Virginia-class submarine programs.
Norway
Arctic surveillance priorities drive hull-mounted and towed array installations along the Barents Sea littoral, with the Norwegian Coastal Administration expanding fixed underwater sensor networks. National regulations align with NATO's Maritime Unmanned Systems initiative for autonomous payload standardization. Kongsberg Maritime anchors domestic production in Horten, supplying both naval and offshore exploration segments with multibeam and synthetic aperture systems.
United Kingdom
Royal Navy Astute-class upgrades and Dreadnought program construction sustain demand for high-frequency forward-looking arrays and passive flank sonars. UK Export Control Organisation protocols on acoustic signal processing algorithms constrain technology transfer to allied programs. Industrial activity concentrates in Weymouth and Portsmouth, where Thales Group leverages its Franco-British supply chain for transatlantic program continuity.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases force transducer encapsulant reformulation for European commercial offshore markets. Atlas Elektronik in Bremen supplies mine countermeasures systems to NATO navies, while German shipyards integrate variable-depth sonar arrays into frigate construction. The country's central defense procurement office pools R&D through the EU's Permanent Structured Cooperation framework.
France
Naval Group's submarine construction programs in Cherbourg drive demand for obstacle avoidance and terrain-following sonars, with Thales Group providing integrated combat system architectures. ANSM and CNIL data governance protocols influence export control compliance for dual-use acoustic sensing technologies. The Brittany maritime cluster hosts specialist transducer design capabilities constrained by acoustic engineer pipeline shortages across university oceanography programs.
Global Sonar Systems and Technology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the sonar systems market, with combat system integrators capturing platform-level contracts while component vendors compete for subsystem positions. The upper tier concentrates around defense conglomerates with classified signal processing capabilities and ITAR-compliant supply chains. Three archetypes dominate: systems integrators bundling sensors into combat suites, transducer specialists supplying tier-2 hardware, and autonomous platform vendors integrating payload-agnostic acoustic modules. Consolidation pressures intensify as procurement offices favor sole-source arrangements, while open-architecture mandates create entry points for modular specialists.
Among transatlantic defense conglomerates, Thales Group and Lockheed Martin Corporation exemplify the integrated systems archetype, each anchoring national program continuity through Franco-British and US supply chains respectively. L3Harris Technologies occupies a position within the modular open-system tier, competing for towed array contracts with designs emphasizing rapid reconfiguration. These three entities represent the competitive spectrum from platform-locked integration to payload-agnostic flexibility that defines current procurement contests.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Raytheon Technologies |
| Teledyne Technologies Incorporated |
| General Dynamics Corporation |
| Atlas Elektronik |
| Kongsberg Maritime |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Twenty-four-month lead times for ITAR-compliant signal processing modules concentrate procurement leverage with sole-source integrators, compressing pricing power for standalone transducer vendors while elevating combat system bundlers.
Pricing Analysis
Long-term sole-source contracts dominate naval procurement, displacing competitive bidding as acoustic engineer shortages force program offices toward single-vendor continuity. Three-tier pricing structure across classified, dual-use, and commercial-off-the-shelf levels segments buyers by ITAR certification tier and integration complexity. Cost compression in portable expeditionary units intensifies as US Marine Corps and UK Commando Force programs prioritize rapid deployment over performance optimization. Commercial offshore exploration firms exhibit highest price sensitivity, while sovereign naval program offices prioritize supply security over unit cost.
Supply Chain Analysis
Inventory buffers for rare earth magnetostrictive materials rarely exceed ninety days as terbium and dysprosium processing concentrates in Chinese facilities. Transducer manufacturing draws from Chinese rare earth processing, Norwegian sensor assembly, and US combat system integration. Single-source vulnerability in terbium supply chains threatens production continuity for high-power projectors. Distribution runs through defense primes acting as gatekeepers to classified program access, with tier-2 component vendors channeled through integrator procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from AI-enhanced active systems that reduce operator dependency and compress detection timelines against legacy passive architectures.
For Market Incumbents: Fortify classified signal processing capabilities through captive acoustic engineering talent pipelines as university oceanography program closures in the United Kingdom and France constrain specialist hiring. Deepen backward integration into rare earth magnetostrictive material sourcing to mitigate Chinese processing concentration. Lockheed Martin and Thales Group positioning demonstrates how Franco-British and US supply chain anchoring sustains transatlantic program continuity against ITAR fragmentation. For New Entrants and Emerging Players: Lead with modular open-system architectures targeting portable expeditionary units where US Marine Corps littoral regiment stand-up creates white-space demand outside incumbent combat system bundling. Prioritize FAA spectrum coordination capabilities for airborne dipping sonar niches where traditional platform integrators lack agility. Norwegian Barents Sea surveillance expansion and NATO Maritime Unmanned Systems payload standardization offer dual entry pathways through autonomous vehicle integration. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core acoustic sensing divisions as procurement consolidation favors platform-level combat system contracts. Mid-cap transducer specialists with ISO/IEC 60565 calibration certification and ITAR-compliant facilities present acquisition candidates for capability-hungry integrators. Monitor EU F-Gas Regulation compliance timelines as encapsulant reformulation requirements force distressed asset availability in European commercial offshore segments.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Engineering Talent Pipeline Investment | University oceanography program partnerships in France and the UK address specialist hiring constraints for transducer design. |
| Rare Earth Backward Integration | Captive terbium and dysprosium sourcing mitigates Chinese processing concentration for magnetostrictive projector manufacturing. |
| Modular Open-Architecture Certification | US Navy integrated undersea warfare program office mandates create competitive positioning against platform-locked incumbents. |
| EU F-Gas Regulation Compliance Program | Polyurethane and epoxy encapsulant qualification maintains European commercial offshore market access against regulatory exclusion. |
| NATO Payload Standardization Alignment | Maritime Unmanned Systems initiative transducer interface compliance enables pooled procurement across EDA member state fleets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across naval program offices, acoustic engineering directors at transducer manufacturers, autonomous platform payload integrators, and commercial offshore survey procurement leads. Primary interview findings were validated against secondary sources including US Navy program office budget justifications, NATO Maritime Unmanned Systems initiative documentation, EU Permanent Structured Cooperation framework R&D pooling records, and International Maritime Organization underwater noise guideline proceedings. Bottom-up segment sizing triangulated against top-down defense expenditure tracking.
Across the analysis window, projections incorporate technology substitution curves for synthetic aperture sonar displacing side-scan systems, procurement cycle compression from sole-source contracting, and Arctic surveillance priority shifts in Norwegian Barents Sea programs. Segmentation modeling spans active versus passive architectures, hull-mounted versus portable product configurations, and naval versus commercial end-user categories. CAGRs derive from volume-weighted platform deployment schedules and capability upgrade phasing across Virginia-class, Astute-class, and Dreadnought construction programs.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense expenditure growth, continued rare earth supply chain concentration, or accelerated AI signal processing adoption would require recalibration. Forecasts reflect documented assumptions regarding acoustic engineer pipeline recovery, ITAR protocol stability, and EU regulatory implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Sensor Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
United States (US) Industrial Sensors Market