
 North America Proximity Sensor Market | 2026-2036
North America Proximity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Proximity Sensor Market Insights
Silicon photonics is decoupling proximity sensor architectures from legacy inductive coil economics, enabling smaller form factors at lower unit costs. TE Connectivity leverages its connector ecosystem to bundle sensing modules with cable assemblies. Rockwell Automation anchors its position through Logix platform integration, embedding sensors directly into programmable automation controllers. Honeywell International Inc. competes via aerospace-grade reliability standards transferred to industrial applications.
A proximity sensor detects object presence or distance without physical contact, typically operating through electromagnetic fields, capacitive coupling, or light emission with detection ranges from fractions of millimeters to several meters. Inductive sensors dominate metal-detection tasks in factory automation, while photoelectric variants capture the fastest growth in packaging and logistics lines requiring longer sensing distances. Capacitive sensors occupy niche but high-margin positions in liquid-level and non-metallic object detection across food processing equipment.
NHTSA mandates on pedestrian detection systems and OSHA machine-guarding regulations are forcing automotive and heavy manufacturing buyers toward certified safety-rated sensor configurations. The FCC governs electromagnetic emissions from wireless-enabled proximity modules, creating compliance barriers for unlicensed spectrum implementations. Stakeholders must monitor evolving functional safety standards and spectrum allocation rulings that will determine which sensor-communication architectures gain procurement approval across North American industrial networks.
Market Dynamics
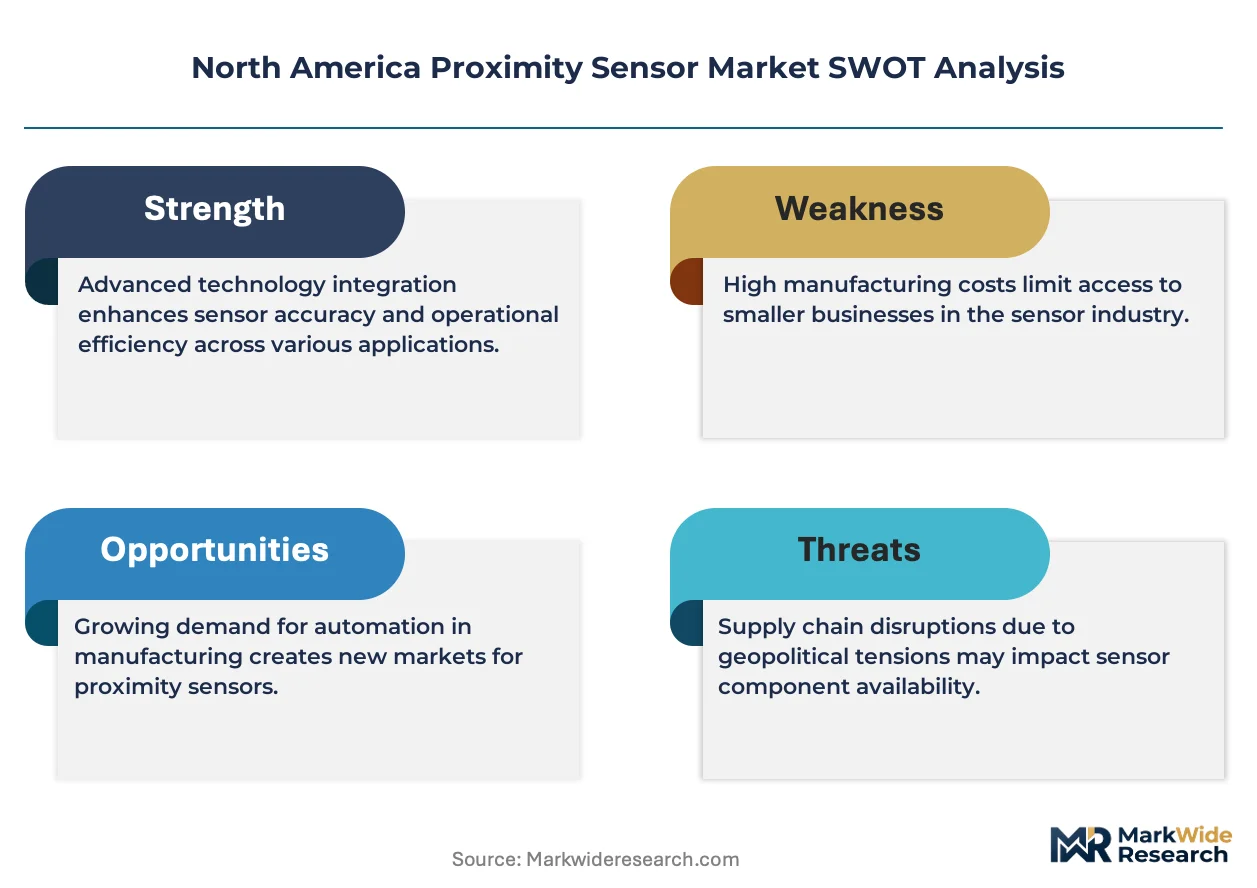
Silicon photonics is severing proximity sensor architectures from legacy inductive coil economics, collapsing form factors and unit costs simultaneously across Michigan automotive corridors and Texas semiconductor fabrication zones.
Growth Catalysts
- NHTSA Pedestrian Detection Mandates:Automotive OEMs in Detroit and Ontario must integrate certified safety-rated proximity modules into all new vehicle platforms, forcing sensor procurement volumes upward.
- OSHA Machine-Guarding Standards:Heavy manufacturing facilities across Ohio and Pennsylvania face tightened detection requirements, accelerating replacement cycles for non-compliant legacy equipment.
- Silicon Photonics Integration:Photonic chip fabrication advances in Austin and Phoenix enable sub-millimeter proximity sensing at price points previously reserved for inductive alternatives.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium supply concentration in Chinese processing facilities exposes North American inductive sensor assemblers to input cost volatility and tariff exposure.
- FCC Spectrum Licensing Friction:Wireless-enabled proximity modules face electromagnetic emission compliance barriers, delaying time-to-market for unlicensed spectrum implementations in industrial IoT deployments.
- Photoelectric Range Limitations:Dust-contaminated packaging environments in Midwest food processing plants degrade optical sensor reliability, preserving inductive incumbent positions despite higher unit costs.
Strategic Opportunities
- Mexican Nearshoring Expansion:Automotive sensor demand in Querétaro and Guanajuato manufacturing corridors remains underpenetrated by certified North American suppliers.
- Capacitive Liquid-Level Applications:Dairy processing equipment in Wisconsin and Minnesota presents high-margin retrofit opportunities for non-metallic detection beyond traditional factory automation.
- IRA Clean Manufacturing Credits:Domestic content requirements for federal procurement create preferential positioning for US-fabricated photonic proximity modules in defense and infrastructure applications.
Industry Challenges
- Photonics Packaging Talent Scarcity:Silicon-to-fiber coupling expertise concentrates in Boston and San Francisco metro areas, creating recruitment bottlenecks for Midwest sensor manufacturers scaling production.
- Functional Safety Certification Timelines:ISO 13849 compliance documentation for safety-rated configurations extends qualification cycles by 8-14 months, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Proximity Sensor Market |
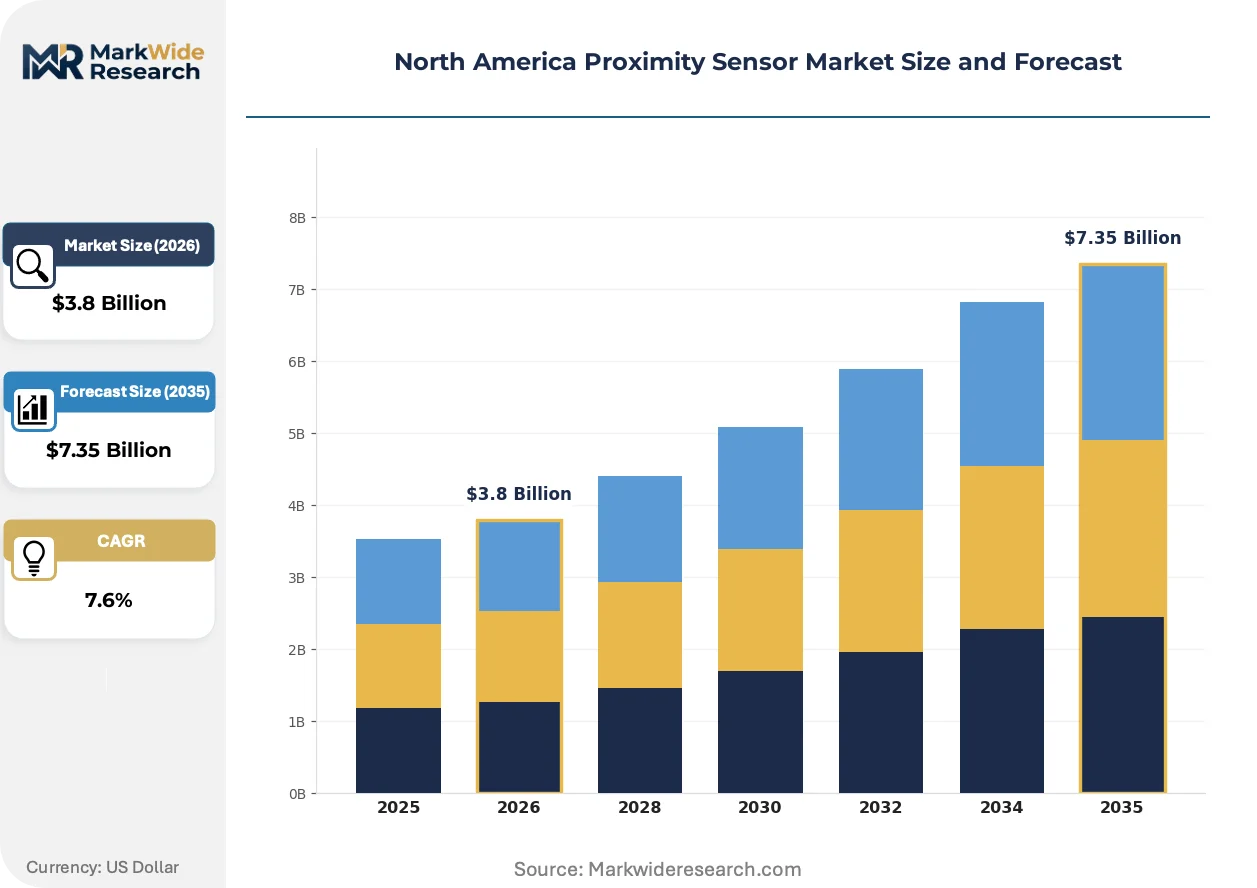
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Sensors, Capacitive Sensors, Ultrasonic Sensors, Photoelectric Sensors Technology: Active Sensors, Passive Sensors, Analog Sensors, Digital Sensors End User: Automotive, Industrial Automation, Consumer Electronics, Healthcare Installation: Embedded Installation, Surface Mounting, Through-Hole Mounting, Remote Installation |
| Companies Covered | Analog Devices, Inc., TE Connectivity, Rockwell Automation Inc., Pepperl+Fuchs, SICK AG, Honeywell International Inc., Fargo Controls Inc., Omron Corporation, Turck, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Proximity Sensor Market Trends and Innovations
Three concurrent vectors are compressing development cycles and rewiring competitive positioning across the North American proximity sensor value chain.
Photonic integrated circuits are electrifying proximity sensor architectures by embedding laser sources, waveguides, and photodetectors onto single silicon dies. Automotive Tier-1 suppliers in Michigan and Ontario are adopting these modules for pedestrian detection systems at triple-digit annual procurement growth rates. This convergence is electrifying price-performance benchmarks previously governed by discrete component assembly economics.
NHTSA pedestrian detection mandates and OSHA machine-guarding enforcement are tightening certification requirements for safety-rated sensor configurations. Automotive assembly lines in Detroit and heavy manufacturing facilities in Pittsburgh must now document functional safety compliance under ISO 13849 Category 3 standards. These regulatory pressures are compressing supplier qualification timelines and favoring vendors with pre-certified module portfolios.
Direct procurement relationships between sensor module vendors and automotive OEMs are displacing traditional distributor intermediaries in high-volume safety applications. Tier-1 suppliers in Michigan and Ohio now negotiate multi-year supply agreements specifying silicon photonics roadmaps and domestic content ratios. This channel consolidation is most visible in electrified vehicle platforms where proximity sensing integrates directly with battery management and autonomous driving compute stacks.
North America Proximity Sensor Market Segmentation
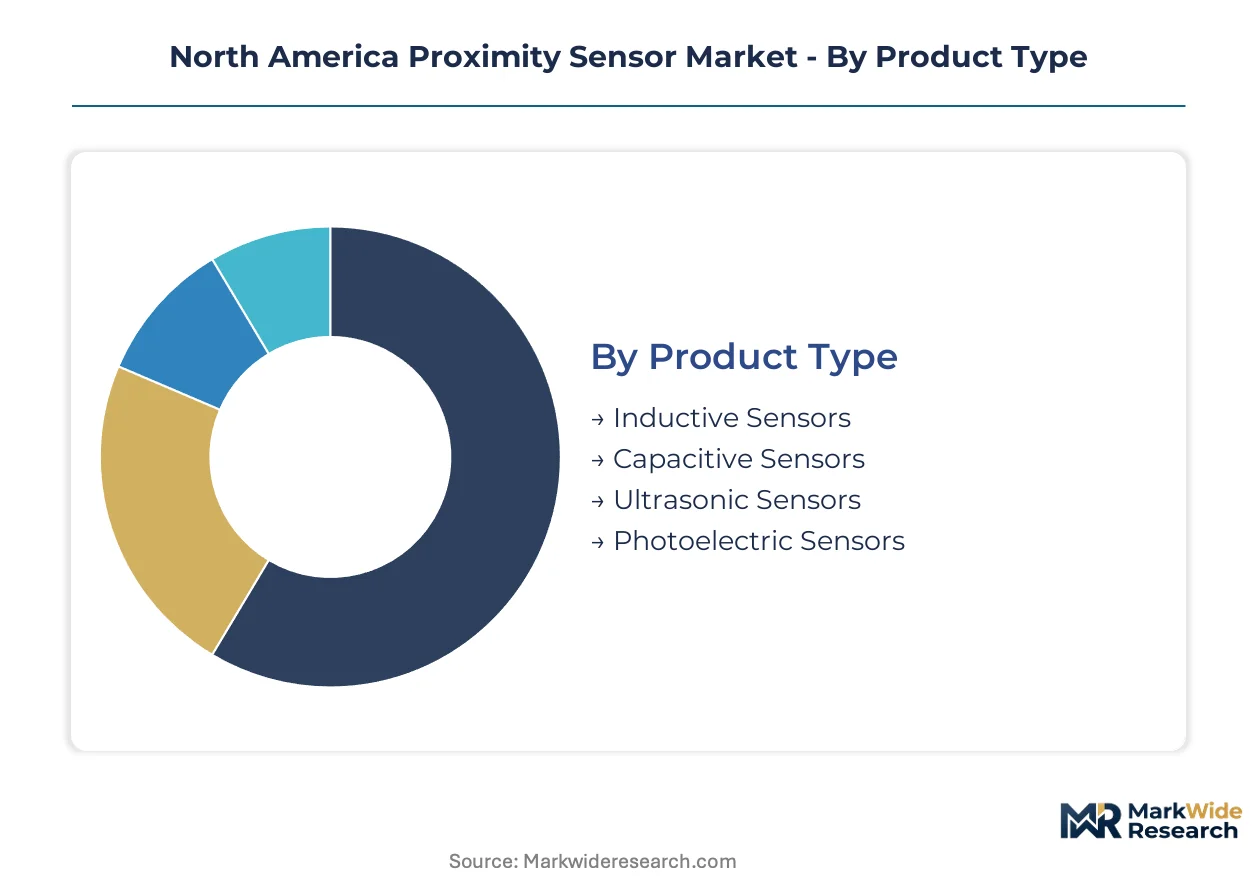
Proximity sensor procurement patterns diverge sharply across North American industrial networks, with automotive OEMs prioritizing safety-rated configurations while food processors favor capacitive variants for liquid-level detection. Understanding these segment-specific demand drivers reveals where technology roadmaps and pricing power concentrate.
Product Type:
Automotive buyers in Michigan and Ontario weight detection reliability against silicon photonics roadmaps when specifying proximity modules for pedestrian safety systems.
- Inductive Sensors:Electromagnetic field detection circuits built around copper coils and ferrite cores deliver millimeter-precision metal proximity sensing. Detroit automotive assembly lines deploy these for robotic weld positioning and conveyor part verification under NHTSA-mandated safety architectures.
- Photoelectric Sensors:Laser diode and photodetector pairs on silicon photonic dies achieve sensing distances exceeding ten meters with sub-microsecond response times. Texas semiconductor fabrication zones and Arizona packaging hubs are scaling procurement of these modules for logistics automation requiring extended range detection.
- Capacitive Sensors:Dielectric field modulation enables non-metallic object detection in Wisconsin dairy processing equipment.
- Ultrasonic Sensors:Piezoelectric transducer arrays generate high-frequency pulses for level sensing in Pennsylvania chemical storage facilities.
Inductive variants lead on scale across North American metalworking corridors; photoelectric modules lead on momentum in semiconductor and logistics clusters.
Technology:
Signal processing architecture determines integration complexity with Rockwell Logix controllers and Honeywell aerospace-grade industrial systems.
- Digital Sensors:On-chip ADC and microcontroller integration outputs pre-processed distance values via IO-Link or EtherNet/IP protocols. Ohio and Pennsylvania heavy manufacturing facilities specify these for OSHA-compliant machine-guarding networks requiring deterministic response timing.
- Active Sensors:Self-energized detection circuits with integrated power management dominate battery-backed automotive applications in Ontario.
- Analog Sensors:Continuous voltage output interfaces with legacy PLC architectures in Minnesota agricultural equipment.
- Passive Sensors:Externally powered resonant circuits occupy cost-sensitive retrofit installations in Mexican nearshoring corridors.
Digital architectures command premium positioning in safety-rated procurement; active sensor configurations dominate electrified vehicle platform integration.
End User:
Functional safety certification requirements and production volume scale create divergent specification patterns across North American buyer categories.
- Automotive:Pedestrian detection mandates from NHTSA force Tier-1 suppliers in Detroit and Ontario toward ISO 13849 Category 3 certified modules with documented failure rates. Direct OEM procurement agreements now specify silicon photonics roadmaps and domestic content ratios under IRA clean manufacturing credit eligibility.
- Industrial Automation:OSHA machine-guarding enforcement in Ohio and Pittsburgh steel facilities accelerates replacement cycles for legacy non-compliant detection equipment.
- Consumer Electronics:Miniaturized capacitive modules integrate into touchless interface panels for California and Washington state device manufacturers.
- Healthcare:FDA-regulated non-contact positioning systems deploy in Minnesota and Massachusetts medical device production lines.
Automotive verticals concentrate revenue volume; industrial automation applications are climbing the fastest on regulatory replacement cycles.
Installation:
Mechanical mounting constraints and environmental sealing ratings determine module selection for specific production line configurations.
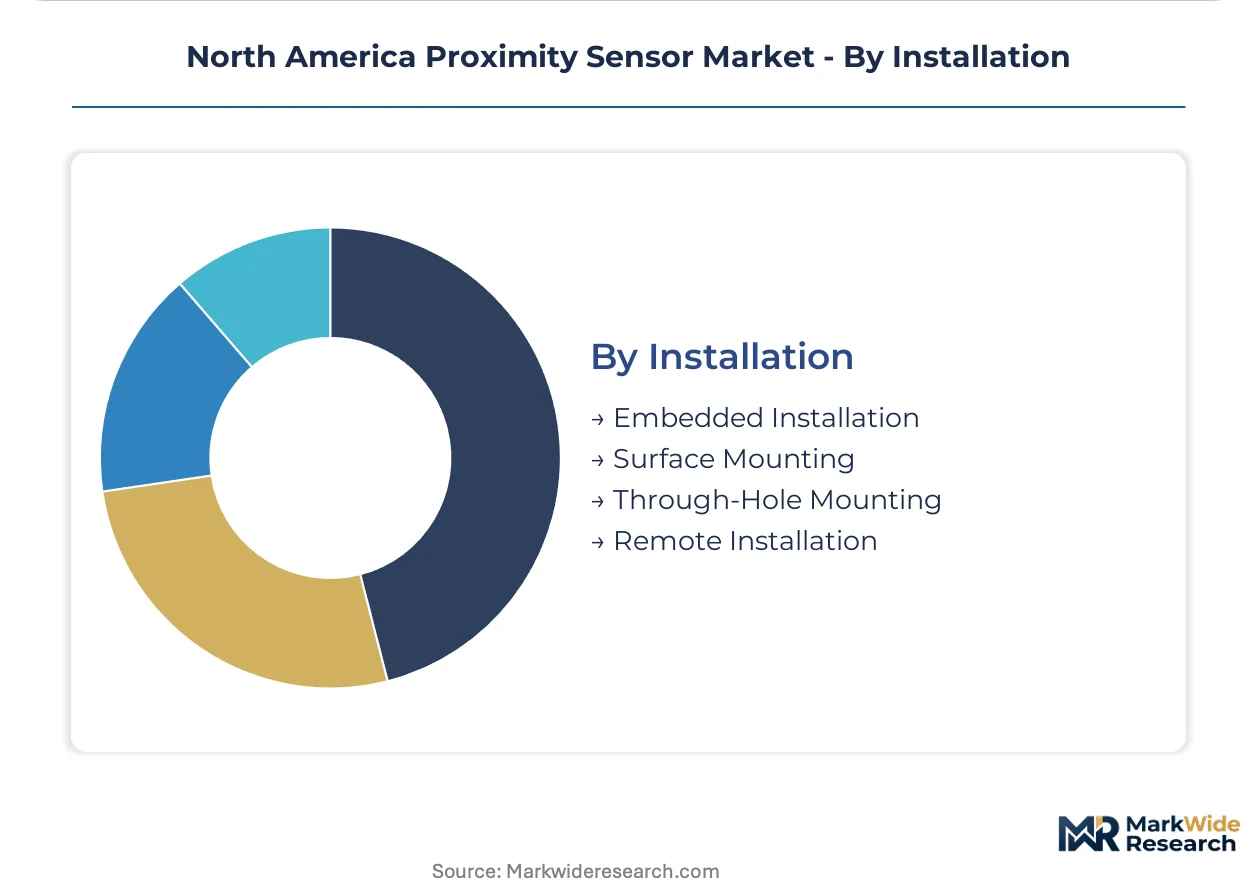
- Embedded Installation:Flush-mounted sensor heads with IP67-rated housings integrate directly into automotive body panel stamping dies and battery pack assembly fixtures. Michigan and Texas manufacturing engineers specify these for contamination-resistant operation in high-debris environments.
- Surface Mounting:Adhesive-backed or bracket-fixed modules enable rapid retrofit deployment in Minnesota food processing equipment upgrade cycles.
- Through-Hole Mounting:Threaded cylindrical housings secure into pre-drilled panels across Pennsylvania material handling conveyor systems.
- Remote Installation:Fiber-coupled photonic sensors separate detection heads from control electronics in Arizona semiconductor cleanroom applications.
Embedded configurations dominate new automotive platform engineering; surface mounting options gain share fastest in retrofit-driven food processing verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan's automotive manufacturing corridor anchors North American proximity sensor procurement, with Detroit Tier-1 suppliers driving safety-rated module volumes under federal pedestrian detection mandates.
United States
OSHA machine-guarding enforcement accelerates sensor replacement cycles across Ohio and Pennsylvania steel facilities. The IRA clean manufacturing credit creates preferential procurement positioning for domestic-fabricated photonic modules in defense applications. Texas semiconductor fabrication zones in Austin and Phoenix are scaling photoelectric sensor deployment for logistics automation requiring extended-range detection.
Canada
Ontario's automotive assembly plants integrate ISO 13849 Category 3 certified proximity modules for NHTSA-aligned export production. Health Canada medical device regulations shape non-contact positioning system specifications in Toronto and Montreal production corridors. Quebec's industrial automation sector concentrates procurement in digital sensor architectures with EtherNet/IP protocol integration.
Mexico
Nearshoring expansion in Querétaro and Guanajuato manufacturing corridors generates underpenetrated demand for certified North American sensor suppliers. Mexican federal labor safety standards are tightening detection requirements across automotive assembly operations. Baja California's electronics manufacturing clusters are adopting surface-mount proximity modules for rapid production line retrofit cycles.
North America Proximity Sensor Market Competitive Landscape
Global majors compete with regional champions across safety certification and silicon photonics integration capabilities. The vendor base stratifies into three tiers: diversified industrial conglomerates with pre-certified safety portfolios, photonics specialists leveraging semiconductor fabrication partnerships, and regional distributors serving retrofit-driven food processing verticals. Dominant competitive moves include direct OEM procurement relationship formation and domestic content ratio positioning for federal credit eligibility.
Among diversified industrial technology providers, Rockwell Automation Inc. and Honeywell International Inc. exemplify the safety-rated systems tier, while TE Connectivity represents the component-integration archetype bundling sensing modules with connector ecosystems. These anchors demonstrate how platform-level controller integration and aerospace-grade reliability standards transferred to industrial applications create differentiation vectors beyond discrete sensor specifications.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| TE Connectivity |
| Rockwell Automation Inc. |
| Pepperl+Fuchs |
| SICK AG |
| Honeywell International Inc. |
| Fargo Controls Inc. |
| Omron Corporation |
| Turck, Inc. |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics packaging specialists concentrated in Boston and San Francisco metro areas command wage premiums that compress Midwest manufacturers' margins and widen spreads between premium-certified and standard-tier proximity sensor offerings.
Pricing Analysis
Input-cost pass-through from neodymium magnet supply volatility directly shapes pricing trajectories across inductive sensor tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13849 Category 3 certified safety modules from uncertified industrial variants and basic retrofit units. Cost compression in economy tiers is intensifying because Chinese rare earth processing concentration exposes assemblers to tariff exposure. Automotive OEMs in Michigan exhibit lowest price sensitivity due to NHTSA mandate compliance requirements, while Mexican nearshoring corridors show highest sensitivity.
Supply Chain Analysis
ISO 13849 functional safety certification documentation requirements gate supplier qualification timelines and concentrate procurement relationships among pre-certified vendors. Silicon photonic chip fabrication draws from Taiwan, South Korea, and domestic US foundries in Arizona and Texas. Neodymium, copper coil windings, and fiber-optic coupling assemblies constitute critical input dependencies. Single-source vulnerability in Chinese rare earth processing facilities creates structural exposure. Distribution runs through direct OEM procurement agreements displacing traditional distributor intermediaries in high-volume safety applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics integration is compressing production costs while NHTSA and OSHA regulatory mandates expand premium-tier addressable market, creating dual margin-expansion vectors for positioned suppliers.
For Market Incumbents: Cement platform-level integration advantages by embedding proximity modules directly into Rockwell Logix and Honeywell aerospace-grade controller ecosystems. Lock in multi-year direct procurement agreements with Detroit Tier-1 suppliers specifying domestic content ratios for IRA credit eligibility. Counter emerging photonics specialists through accelerated ISO 13849 certification pipeline investment. For New Entrants and Emerging Players: The 40-60% price-point gap between premium safety-certified and economy-tier inductive modules opens white-space targeting opportunities. Mexican nearshoring corridors in Querétaro and Guanajuato present underpenetrated demand for certified suppliers. Wisconsin dairy processing equipment retrofits offer high-margin capacitive liquid-level entry points. Pursue channel partnerships with regional automation distributors serving food processing verticals. For Investors and Strategic Acquirers: Automotive Tier-1 suppliers are the most active acquirer in this space, seeking silicon photonics capabilities for pedestrian detection integration. Long-term viability rests on photonic integrated circuit roadmaps and functional safety certification infrastructure. Target acquisition archetype: photonics packaging specialists with silicon-to-fiber coupling expertise. Watch NHTSA rulemaking on autonomous vehicle proximity sensing requirements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Roadmap Investment | Enables sub-millimeter sensing at inductive-comparable price points for Michigan automotive Tier-1s. |
| ISO 13849 Category 3 Certification Acceleration | Compresses 8-14 month qualification cycles to capture NHTSA-mandated replacement demand. |
| Domestic Content Ratio Positioning | Unlocks IRA clean manufacturing credit eligibility for federal defense and infrastructure procurement. |
| Direct OEM Procurement Relationship Formation | Displaces distributor intermediaries in high-volume safety-rated automotive applications. |
| Mexican Nearshoring Corridor Expansion | Captures underpenetrated demand in Querétaro and Guanajuato automotive assembly operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with plant engineers at Ohio and Pennsylvania steel facilities, OEM procurement teams in Michigan automotive corridors, and aftermarket service heads at Texas semiconductor fabrication zones informed demand-side validation. Secondary sources included SEC 10-K filings from diversified industrial technology providers, NHTSA pedestrian detection mandate documentation, OSHA machine-guarding enforcement records, and customs trade data on neodymium magnet imports. Bottom-up sensor unit demand modeling and top-down industrial automation capex triangulation anchored value estimates.
Segment-weighting approaches distributed total market value across product type, technology architecture, end-user vertical, and installation configuration dimensions. Photoelectric, inductive, capacitive, and ultrasonic product categories combined with digital, analog, active, and passive signal processing technologies. Automotive, industrial automation, consumer electronics, and healthcare end-use segments were modeled separately. CAGRs derived from regression analysis against industrial production indices and regulatory mandate implementation timelines. Silicon photonics adoption curves and functional safety certification penetration rates served as industry-specific forecast inputs across the projection horizon.
Caveats apply where NHTSA rulemaking acceleration, Chinese rare earth export restriction escalation, or photonics packaging talent scarcity could materially shift the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and semiconductor fabrication capacity expansion. A model refresh is warranted upon material change in OSHA machine-guarding inspection intensity or IRA domestic content requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market