
 Laser Scanner Market | 2026-2036
Laser Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Scanner Market Intelligence
The fusion of real-time kinematic (RTK) positioning with mobile mapping systems is tilting the market towards higher-accuracy, on-the-go data capture. Trimble Inc. leverages its strong portfolio in geospatial solutions to lead in this area. Hexagon AB sustains a broad market presence through its diverse hardware and software offerings. Meanwhile, FARO Technologies competes by focusing on portable 3D measurement solutions for factory metrology and public safety.
A laser scanner is an instrument that captures the precise geometry of physical objects using laser light to create dense 'point clouds'. These devices measure distances by analyzing reflected light, often using time-of-flight or phase-shift principles to determine coordinates with sub-millimeter accuracy. Time-of-flight systems dominate large-scale applications like surveying & mapping due to their long range. In contrast, triangulation-based scanners command the high-precision segment for industrial inspection and reverse engineering.
Compliance with CE marking in Europe is mandatory for market access, ensuring product safety and electromagnetic compatibility. For medical applications, scanners must adhere to specific FDA regulations in the United States, while broader industrial use aligns with ISO 10360 series standards for acceptance testing. Vendor success will depend on navigating these varied compliance pathways while managing the increasing software complexity inherent in modern scanning workflows.
Market Dynamics
The primary force shaping the market is the convergence of high-accuracy mobile mapping hardware with AI-driven software. This combination automates point cloud processing and transforms raw data into digital twins for industries like construction and advanced manufacturing.
Growth Catalysts
- Digital Twin Demand:Government BIM mandates in Europe are pushing the construction sector to adopt scanners for creating detailed digital twins of infrastructure projects.
- Mobile Mapping Accuracy:Integrating RTK positioning into mobile systems enables high-accuracy, on-the-go data capture, benefiting large-scale urban surveying applications.
- Industrial Metrology:Germany's automotive sector requires high-precision triangulation scanners for automated quality control and in-line inspection on factory floors.
Market Restraints
- High Capital Cost:The significant upfront investment for high-precision scanners remains a primary adoption barrier, especially for smaller engineering and surveying firms.
- Substitution from Photogrammetry:Lower-cost photogrammetry from UAVs is a viable alternative for large-area mapping applications not requiring the highest levels of accuracy.
- Operational Limitations:Time-of-flight systems suffer accuracy degradation in adverse weather conditions, restricting their reliability for continuous outdoor data capture.
Strategic Opportunities
- Forensic Applications:Public safety agencies are an underpenetrated segment for using scanners in rapid crime scene documentation and accident reconstruction.
- Solid-State Miniaturization:Developing compact solid-state scanners opens integration opportunities in industrial robotics, autonomous vehicles, and portable handheld mapping systems.
- Emerging Market Infrastructure:Major infrastructure projects in India and Brazil, backed by public funding, are creating new demand for surveying and construction scanners.
Industry Challenges
- Point Cloud Data Complexity:A shortage of technicians and data scientists skilled in processing, analyzing, and extracting value from massive point cloud datasets hinders workflow efficiency.
- Software Interoperability:Ensuring seamless integration of scanner data with diverse third-party CAD, BIM, and GIS software platforms remains a persistent technical challenge for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Scanner Market |
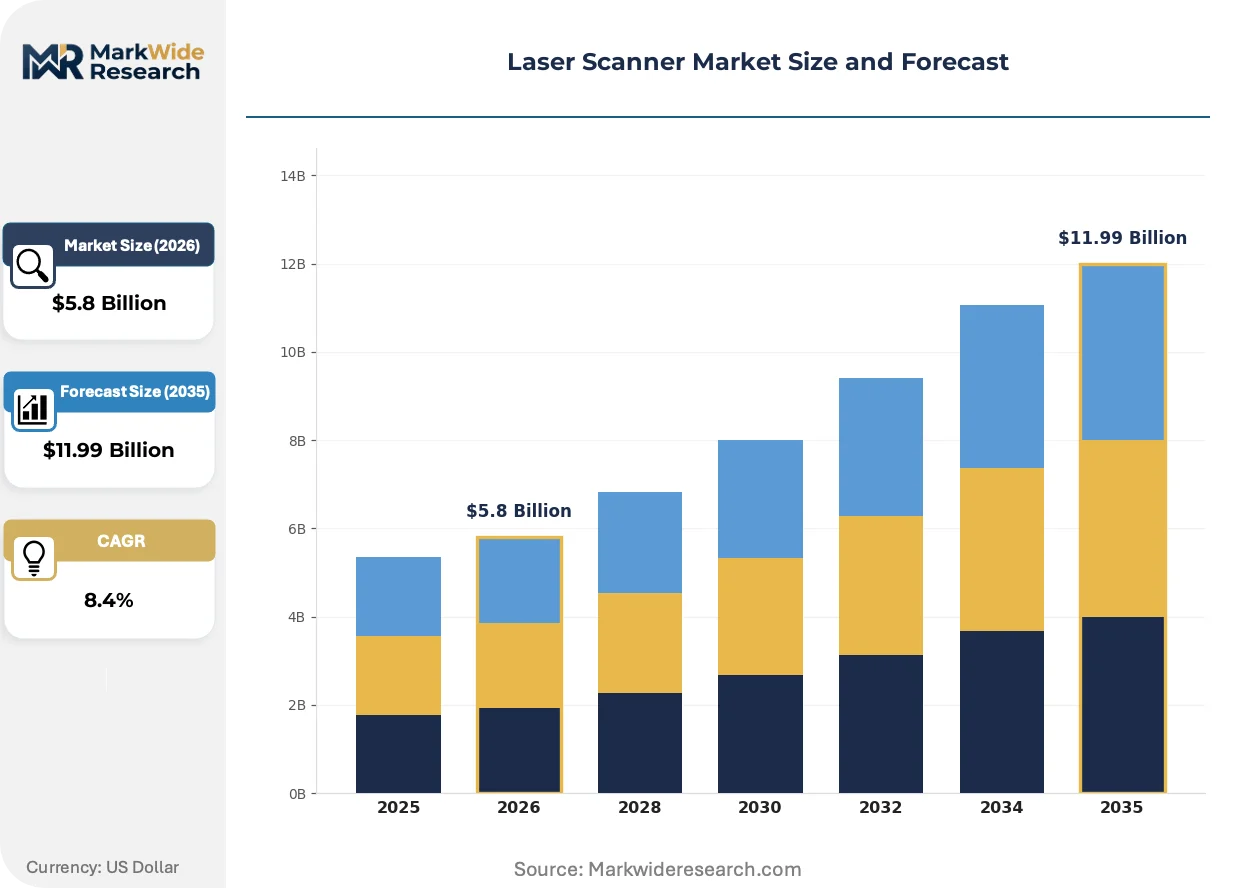
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time of Flight, Phase Shift, Triangulation, Structured Light, Confocal, Others Technology: Terrestrial Laser Scanning, Mobile Mapping Systems, Handheld Scanners, Airborne Laser Scanning, Industrial Automation Solutions Application: Archaeology & Cultural Heritage, Construction & Engineering, Mining & Geology, Agriculture & Forestry, Public Safety & Forensics, Surveying & Mapping End User: Manufacturing Companies, Surveying Firms, Research Institutions, Government Agencies, Energy Providers |
| Companies Covered | Hexagon AB, FARO Technologies, Trimble Inc., Carl Zeiss Optotechnik GmbH, RIEGL Laser Measurement Systems GmbH, Creaform, Topcon Corporation, Nikon Metrology, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Scanner Market Strategic Shifts & Innovations
The market is shifting from static, discrete data capture toward dynamic, real-time 3D modeling. This evolution is driven by advancements in mobile hardware and the embedding of artificial intelligence directly into scanning workflows for immediate analysis.
Edge computing capabilities are now being integrated directly into mobile mapping scanners. Survey crews and construction managers are adopting this to perform on-site point cloud registration and preliminary analysis without a laptop. This integration is collapsing the time between data acquisition and actionable insight, significantly reducing the dependency on lengthy back-office data processing.
Europe's forthcoming AI Act imposes new risk management and transparency obligations on systems that use artificial intelligence. This directly affects vendors developing automated point cloud classification and feature extraction algorithms. Scanner manufacturers embedding AI must now invest in auditable development to comply, especially for systems used in safety-critical sectors like infrastructure inspection.
A notable shift in consumption patterns sees end-users favoring Hardware-as-a-Service (HaaS) and rental models over direct capital purchases. This model disrupts traditional equipment sales channels, benefiting vendors and distributors with strong service and fleet management operations. The trend is most visible in the project-based AEC sector in North America and Europe, where it offers greater financial flexibility.
Laser Scanner Market Segmentation
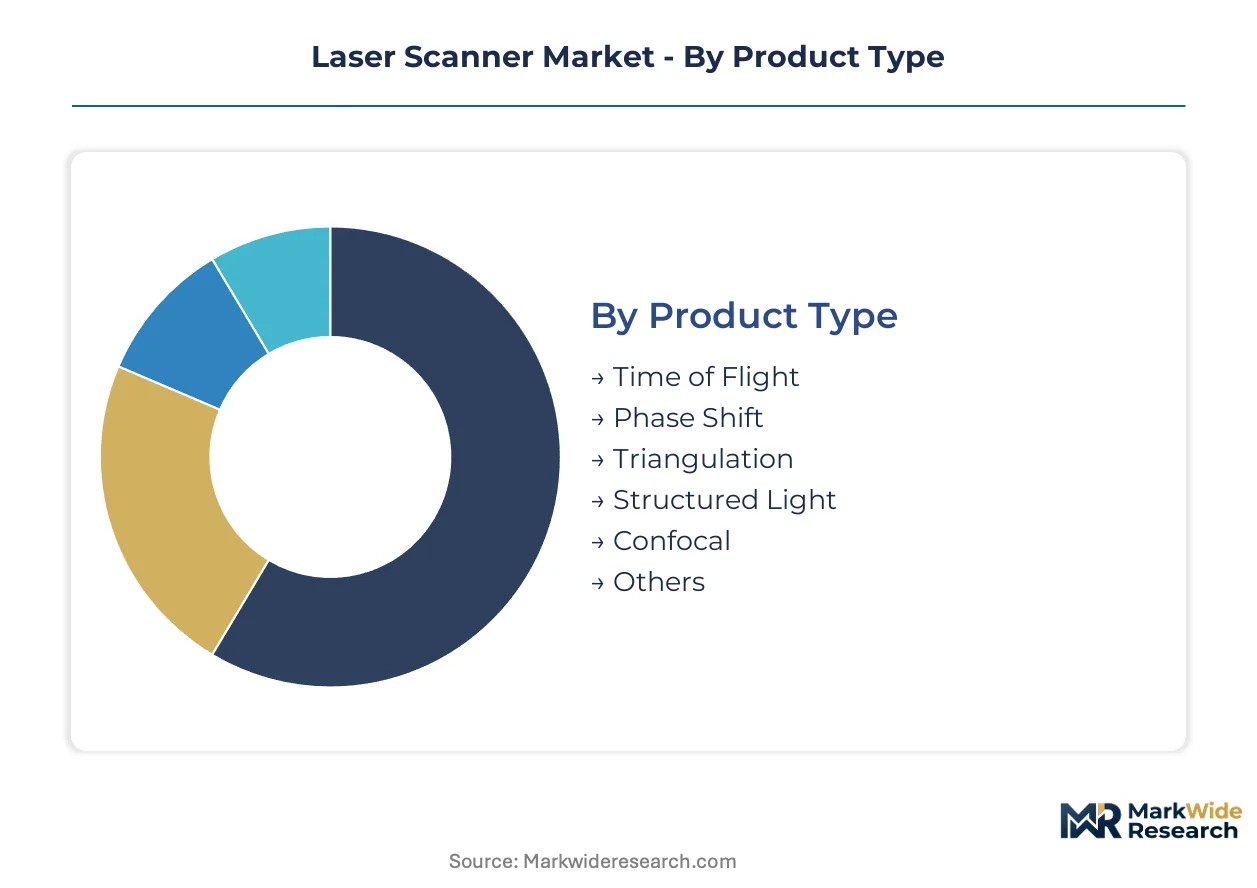
The laser scanner market exhibits diverse segmentation driven by varying technical requirements and end-user applications. Understanding these segments helps to delineate demand patterns, technology preferences, and operational priorities for different industry verticals.
Product Type:
Differences in laser scanner product types dictate their operational speed and data acquisition cycle times across various applications.
- Time of Flight:These systems measure distances by timing a laser pulse's round trip. They excel in long-range data capture, often covering hundreds of meters. Demand concentrates in large-scale surveying and mapping projects due to their extensive range and efficiency over vast areas.
- Phase Shift:Phase shift scanners determine distance by analyzing the phase difference between emitted and reflected continuous laser waves. They offer high accuracy over shorter to medium ranges. Industrial metrology and reverse engineering applications utilize phase shift technology for precise dimensional control in manufacturing facilities.
- Triangulation:Triangulation scanners use a camera to calculate distance based on the angle of reflected laser light. Industrial inspection relies on their sub-millimeter precision.
- Structured Light:Structured light scanners project a known pattern onto an object and analyze its deformation for 3D reconstruction. They are effective for detailed object capture in close range.
- Confocal:Confocal microscopy-based scanners provide high-resolution surface topology data by rejecting out-of-focus light. They serve medical and micro-metrology needs.
- Others:This category includes emerging technologies such as lidar-on-chip solutions or specialized multi-spectral scanners. These cater to niche applications requiring unique data attributes.
Time of Flight systems dominate the installed base for large-area capture. Triangulation technology is where expansion concentrates for high-precision industrial uses.
Technology:
Laser scanner technologies are differentiated by their deployment method and suitability for specific operational environments.
- Mobile Mapping Systems:These integrated systems combine laser scanners with GNSS and IMU for dynamic data acquisition from moving platforms. They enable rapid capture of large areas. Urban surveying and infrastructure inspection leverage mobile mapping systems for efficient data collection along roads and railways across Europe.
- Industrial Automation Solutions:These technologies integrate scanners into automated production lines or robotic systems for continuous monitoring and quality control. They ensure precision in manufacturing. Germany's automotive industry drives demand for these solutions, requiring in-line inspection for vehicle component assembly.
- Terrestrial Laser Scanning:Terrestrial scanners are static ground-based devices used for detailed 3D documentation of buildings and sites. They provide high-accuracy point clouds for BIM.
- Handheld Scanners:Portable handheld devices offer flexibility for on-site 3D measurement and reverse engineering. They are favored for their ease of use in confined spaces.
- Airborne Laser Scanning:Mounted on aircraft or drones, airborne scanners acquire topographical data over vast geographical regions. They are critical for large-scale mapping and environmental monitoring.
Mobile Mapping Systems represent the fastest-growing trajectory due to their efficiency and integration with RTK. Industrial Automation Solutions also demonstrate significant expansion in factory environments.
Application:
The application segments for laser scanners are defined by the specific value proposition they deliver, from digital twin creation to forensic documentation.
- Construction & Engineering:Scanners capture as-built conditions and monitor progress for infrastructure projects, generating detailed digital twins. They support government BIM mandates in Europe. Demand for digital twin creation in large-scale building and infrastructure projects drives scanner adoption in this sector.
- Surveying & Mapping:This application uses scanners to create precise topographical maps, cadastral surveys, and geospatial datasets. It underpins urban planning and land management. Public-funded infrastructure projects in emerging markets like India create significant demand for accurate surveying data.
- Public Safety & Forensics:Scanners rapidly document crime scenes and accident sites, preserving critical evidence in 3D. They provide objective data for investigations.
- Archaeology & Cultural Heritage:Scanners digitally preserve historical sites and artifacts, enabling virtual reconstruction and detailed analysis. They aid in conservation efforts.
- Mining & Geology:Scanners map mine tunnels, measure stockpile volumes, and monitor geological formations. They enhance safety and operational efficiency.
- Agriculture & Forestry:Scanners assess crop health, monitor forest growth, and map terrain for precision agriculture. They optimize resource management.
Construction & Engineering and Surveying & Mapping applications together concentrate the largest share of demand. Public Safety & Forensics is an underpenetrated segment showing nascent growth.
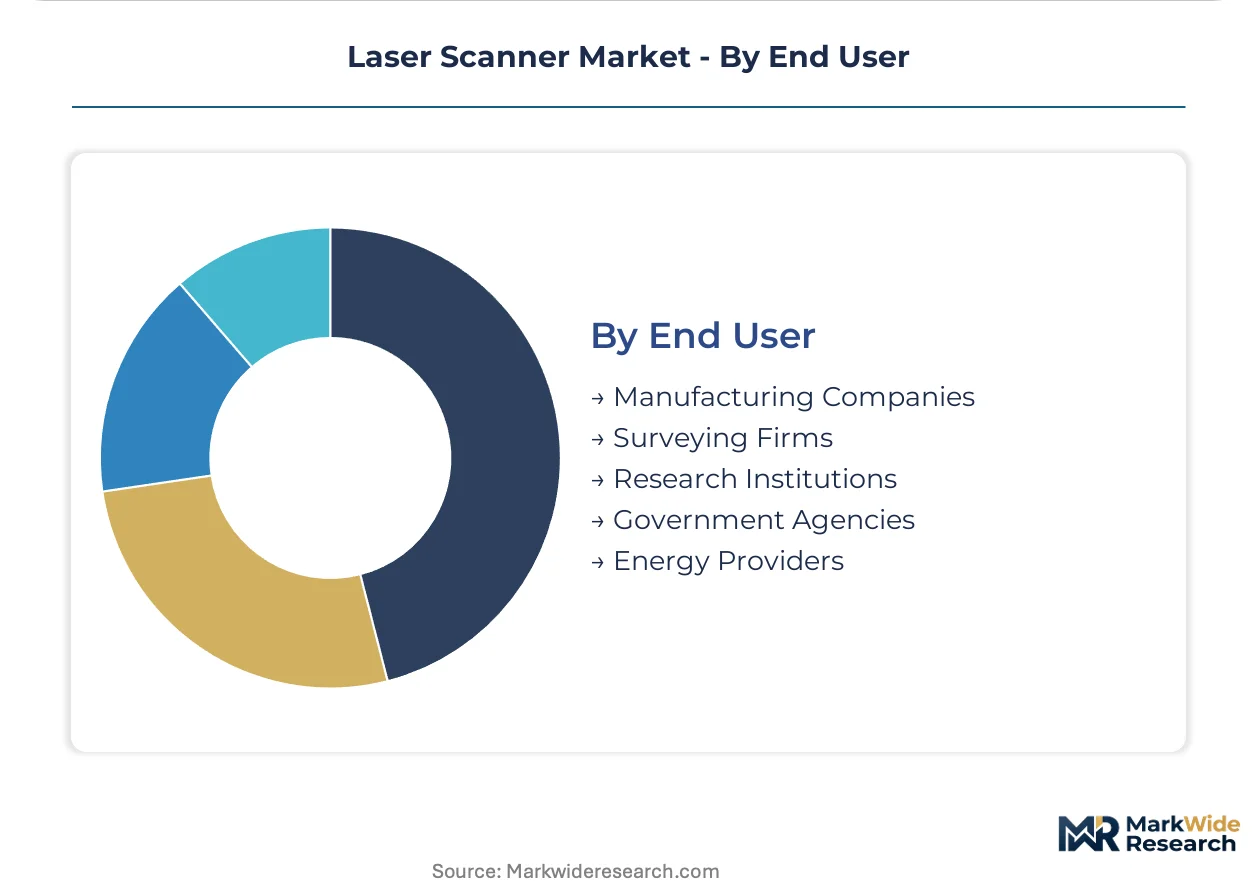
End User:
End-user segments exhibit distinct purchasing behaviors and operational scales, influencing the type and volume of laser scanners acquired.
- Manufacturing Companies:These users deploy scanners for quality control, reverse engineering, and automated inspection on production lines. They require high-precision and integration capabilities. Automotive and aerospace manufacturers in Germany utilize scanners for stringent quality assurance and rapid prototyping.
- Surveying Firms:Surveying firms use scanners for land surveying, topographic mapping, and as-built documentation. They prioritize accuracy, range, and efficiency for field operations. Large infrastructure projects globally drive demand for surveying firms to acquire advanced mobile mapping and terrestrial scanning systems.
- Research Institutions:Academic and scientific organizations employ scanners for diverse research, from material science to environmental studies. They seek cutting-edge and specialized devices.
- Government Agencies:Government bodies use scanners for urban planning, infrastructure management, and public safety applications. They often procure through long-term contracts.
- Energy Providers:Energy companies use scanners for inspecting power plants, pipelines, and transmission lines. They ensure asset integrity and safety compliance.
Manufacturing Companies and Surveying Firms represent the largest market volume. Government Agencies are also significant purchasers, often for long-term strategic projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing companies and surveying firms represent significant buyer archetypes across global laser scanner markets. These end-users, driven by specific project demands and regulatory frameworks, shape regional market dynamics. Their investment patterns influence technological adoption and geographic market expansion.
Germany
Germany's automotive sector demands high-precision triangulation scanners for automated quality control on factory floors. CE marking compliance is mandatory for all laser scanner products entering the European market. The Stuttgart region, a hub for advanced manufacturing, sees continuous integration of these systems for in-line inspection.
United States
Construction and engineering applications drive demand for laser scanners in the United States, particularly for digital twin creation. FDA regulations apply to medical applications, while broader industrial use aligns with ISO 10360 standards. Major urban centers like New York City leverage scanners for large-scale infrastructure projects and as-built documentation.
India
Public-funded infrastructure projects in India create substantial demand for surveying and construction scanners. The PLI scheme encourages domestic manufacturing and technology adoption in various sectors. The Mumbai-Pune industrial corridor is witnessing increased scanner deployment for new factory construction and urban development.
China
China's vast manufacturing base and infrastructure development initiatives fuel demand for laser scanning solutions. GB standards and government investments in smart cities influence product specifications and procurement. The Yangtze River Delta region, a key manufacturing hub, integrates advanced scanners for quality control and automated inspection.
France
France's construction sector adopts laser scanners due to government BIM mandates for infrastructure projects. The EU AI Act imposes new risk management obligations on systems using artificial intelligence in scanning workflows. The Paris region utilizes these technologies for urban planning, heritage preservation, and detailed building documentation.
Laser Scanner Market Key Industry Players
Channel-controlling players compete with product-specialist players across the laser scanner market. This landscape features a blend of large, diversified technology conglomerates and nimble, focused hardware or software providers. Strategic archetypes include comprehensive geospatial solution providers, specialized industrial metrology firms, and portable measurement system developers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these entities.
Among major geospatial and industrial solution providers, Hexagon AB exemplifies a broad market presence through its diverse hardware and software offerings, addressing numerous applications from surveying and mapping to industrial metrology. Trimble Inc. occupies a leading position in integrated geospatial solutions, particularly leveraging its expertise in real-time kinematic (RTK) positioning for high-accuracy, on-the-go data capture across various industries. FARO Technologies, Inc. represents a specialist archetype, focusing on portable 3D measurement solutions meticulously designed for factory metrology, construction verification, and public safety applications such as accident reconstruction and crime scene documentation.
| Leading Market Players |
|---|
| Hexagon AB |
| FARO Technologies |
| Trimble Inc. |
| Carl Zeiss Optotechnik GmbH |
| RIEGL Laser Measurement Systems GmbH |
| Creaform |
| Topcon Corporation |
| Nikon Metrology |
| SICK AG |
| Others |
Cost & Logistics Intelligence
Stuttgart's concentration of advanced manufacturing capacity directly influences the pricing power for high-precision laser scanners. This specialized supply base dictates cost structures for industrial metrology solutions globally.
Pricing Analysis
Cost-plus contracts, often indexed to specialized component costs, govern high-precision laser scanner sales. Price differentiation stems from sub-millimeter accuracy levels, long-range capabilities, and adherence to CE marking. Pricing softness emerges in large-area mapping due to substitution from lower-cost photogrammetry solutions. Smaller engineering and surveying firms exhibit the highest price sensitivity, while large manufacturing companies prioritize performance over initial capital outlay.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive manufacturing of laser scanning systems. Geographic supply concentrates in Germany, Japan, and the United States, which host key optical component and sensor manufacturers. Dependencies include high-power laser diodes and precision IMU sensors, creating single-source vulnerability for some specialized parts. Distribution runs through a blend of direct enterprise sales and a growing network of channel partners offering Hardware-as-a-Service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser scanner market represents a defensive-moat story, primarily due to the high switching costs associated with integrating data into existing BIM and GIS workflows. This entrenchment rewards long-term investments in software interoperability and user training.
For Market Incumbents: Insulate core market share by accelerating AI algorithm development for automated point cloud processing, directly addressing software complexity challenges. Deepen vertical integration into specialized software platforms to create higher switching costs against photogrammetry alternatives. Expand Hardware-as-a-Service offerings, especially in project-based AEC sectors, to counter high capital cost restraints. Invest in compliance with emerging regulations like the EU AI Act to reinforce market leadership in safety-critical applications.
For New Entrants and Emerging Players: Pursue underpenetrated segments like public safety and forensics, offering specialized solutions for rapid crime scene documentation. Target emerging markets such as India and Brazil with cost-effective mobile mapping systems tailored for infrastructure projects. Focus on developing compact solid-state miniaturized scanners for integration into industrial robotics and portable handheld systems. Emphasize simplified workflows and cloud-based processing to lower adoption barriers for smaller firms.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure and industrial enablement play because of its foundational role in digital twin creation and precision manufacturing. Identify acquisition targets specializing in AI-driven point cloud software or miniaturized scanning hardware for robotics integration. Strategic acquirers should also consider regional distributors with strong service and fleet management capabilities. The signal to watch is the acceleration of government BIM mandates and the compliance pathways for the EU AI Act.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Point Cloud Software Development | Automated analysis reduces processing time for end users, enhancing efficiency in construction and manufacturing. |
| Expansion of Hardware-as-a-Service Models | Offers financial flexibility to project-based AEC sector clients, lowering capital expenditure barriers for adoption. |
| Miniaturization of Solid-State Scanner Technology | Enables integration into industrial robotics and autonomous vehicles, opening new application areas for manufacturers. |
| Strategic Partnerships for BIM/GIS Integration | Ensures seamless data flow into existing digital workflows, addressing software interoperability challenges for surveying firms. |
| Targeted Entry into Public Safety & Forensics | Leverages scanners for rapid crime scene documentation, expanding into an underpenetrated segment for government agencies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary interviews to gather qualitative insights. This involved discussions with construction managers, metrology engineers, surveying firm principals, and public safety officials. Secondary validation drew from ISO standards, national infrastructure project databases, and corporate financial filings. A blend of bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation across all segments.
The analytical framework calibrated market size and growth rates across the analysis window by segmenting data by product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected adoption patterns. Key forecast inputs included government infrastructure spending commitments and industrial digital twin adoption rates. This approach provided a robust quantitative outlook.
Macroeconomic conditions sit as an overlay; deviation in global construction spending or industrial CAPEX would shift the trajectory. Forecasts reflect underlying assumptions about technological advancements and regulatory stability. Geopolitical instability or significant supply chain disruptions for optical components could also revise the outlook.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Global Hazardous Location Thermostats Market