
 Light Detection and Ranging (Lidar) Market | 2026-2036
Light Detection and Ranging (Lidar) Market Size, Share, and Industry Trends Forecast 2026-2036
Light Detection and Ranging (Lidar) Market Analysis
Direct sales to automotive Tier 1 suppliers is fragmenting as lidar makers build captive integration teams and bypass traditional distribution. Hesai Group dominates volume shipments for robotaxi programs through in-house manufacturing scale. Valeo sustains its position through deep partnerships with European OEMs on solid-state designs. Innoviz Technologies specializes in MEMS-based architectures for passenger vehicle serial production.
Light Detection and Ranging refers to active remote sensing systems that emit pulsed or continuous wave laser light and measure return time to generate precise three-dimensional point clouds with centimeter-level accuracy. These systems serve geospatial mapping, autonomous navigation, and industrial automation by converting optical returns into actionable spatial intelligence. Ground-based lidar occupies the mature margin pool in civil engineering and construction monitoring where established workflows limit switching costs. Flash lidar represents the fastest-growing technology segment for short-range automotive applications requiring instantaneous scene capture without mechanical scanning. UAV lidar extends into precision agriculture and forestry inventory where payload constraints favor compact solid-state emitters.
The EU AI Act and UNECE WP.29 type-approval frameworks in Europe impose functional safety thresholds on automotive lidar deployed in advanced driver-assistance systems. The US NHTSA and FAA maintain parallel certification tracks for road vehicles and commercial drones respectively, creating dual compliance burdens for cross-application vendors. Stakeholders must monitor divergence between European performance-based standards and US prescriptive testing protocols when allocating R&D across geographic markets.
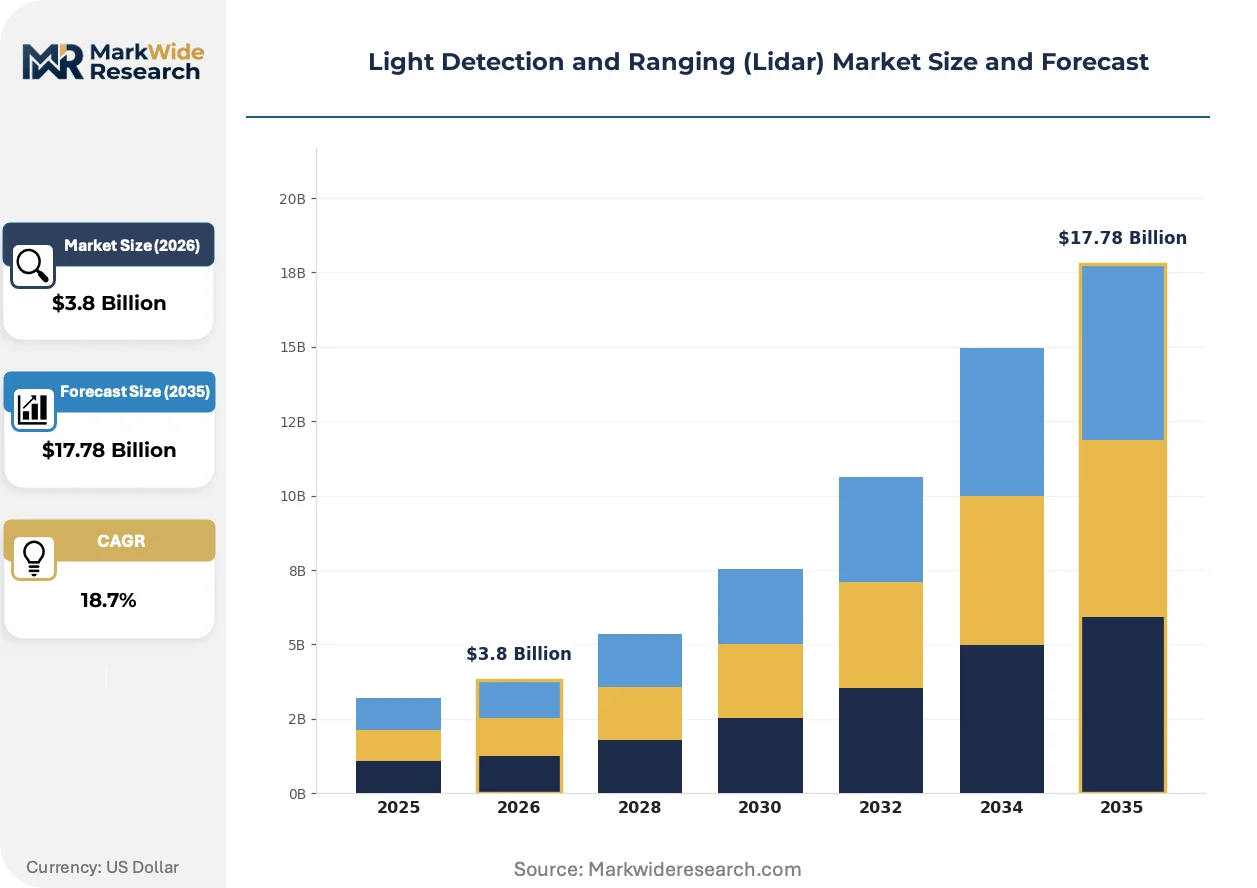
Market Dynamics
Solid-state lidar architectures are compressing unit economics below the $500 threshold that gates mass-market automotive deployment, forcing mechanical spinning vendors to defend mapping margins or migrate downstream.
Growth Catalysts
- EU AI Act certification mandates:Functional safety thresholds for advanced driver-assistance systems create guaranteed demand for automotive-grade sensors that meet UNECE WP.29 type-approval frameworks.
- Robotaxi fleet scaling:Autonomous vehicle operators in California and Arizona are absorbing solid-state volumes at contract structures that amortize sensor costs across multi-year service agreements.
- Flash emitter miniaturization:Indium gallium arsenide photodetector arrays now deliver short-range instantaneous capture without mechanical scanning, opening cabin monitoring and near-field obstacle detection applications.
Market Restraints
- GaAs wafer supply concentration:Gallium arsenide substrate for 1550nm fiber lasers concentrates among Japanese and Chinese refiners, exposing cost volatility to automotive Tier 1 procurement teams.
- Point cloud processing silicon:FPGA and ASIC supply for real-time 3D reconstruction remains captive to TSMC and Samsung foundry allocation, constraining shipment scaling for mid-tier lidar vendors.
- Photodetector thermal drift:Silicon photomultiplier and avalanche photodiode performance degradation above 85°C limits deployment in Middle Eastern and Southwestern US summer operating conditions.
Strategic Opportunities
- India precision agriculture penetration:UAV-mounted solid-state units for crop health monitoring remain underdeployed relative to GPS-guided spraying equipment, creating first-mover terrain mapping contracts.
- Digital twin convergence:Integration of lidar point clouds with BIM software and IoT sensor networks is enabling continuous infrastructure monitoring for bridges and rail corridors.
- Japan METI autonomous logistics incentives:Subsidies for warehouse automation and port container handling are accelerating 3D perception deployment in facilities near Yokohama and Kobe.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for automotive lidar firmware remains concentrated among German and Japanese engineering consultancies, inflating R&D timelines.
- Multi-sensor fusion integration:Synchronizing lidar timestamps with camera frames and radar returns requires specialized calibration protocols that delay vehicle platform integration by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Detection and Ranging (Lidar) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Lidar, Ground-based Lidar, Mobile Lidar, UAV Lidar Technology: Pulsed Lidar, Continuous Wave Lidar, Coherent Lidar, Flash Lidar End User: Aerospace, Agriculture, Forestry, Civil Engineering Application: Mapping, Surveying, Environmental Monitoring, Autonomous Vehicles |
| Companies Covered | Hesai Group, Valeo, Sick AG, Faro Technologies, Trimble Navigation Limited, Leica Geosystems AG, Velodyne LiDAR, Innoviz Technologies, Teledyne Optech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Detection and Ranging (Lidar) Market Emerging Trajectories
Three distinct vectors are restructuring competitive advantage: emitter technology migration, regulatory performance mandates, and procurement model compression favoring vertically integrated suppliers over component distributors.
1550nm fiber laser lidar is migrating from long-haul trucking autonomy into premium passenger vehicle highway pilot systems. Mercedes-Benz and BMW procurement teams are specifying eye-safe extended-range detection for European motorway operation. This wavelength architecture compresses 905nm incumbent positions in the $75,000-plus vehicle segment where thermal management budgets accommodate fiber pump diodes.
The EU AI Act's risk classification system for autonomous functions is forcing lidar vendors to document failure-mode probabilities across environmental conditions. German KBA type-approval examiners are rejecting submissions lacking Monte Carlo simulation datasets for snow and spray occlusion. Suppliers are responding by staffing dedicated homologation teams in Stuttgart and Munich to compress certification cycles.
Fleet operators are consolidating sensor procurement through direct manufacturer contracts that bypass traditional automotive Tier 1 distribution. Waymo and Cruise purchasing teams negotiate multi-year supply agreements with Hesai and Innoviz for standardized solid-state units. This channel compression is most visible in California and Arizona where robotaxi mileage accumulation justifies volume commitments that legacy distribution cannot match.
Light Detection and Ranging (Lidar) Market Segmentation
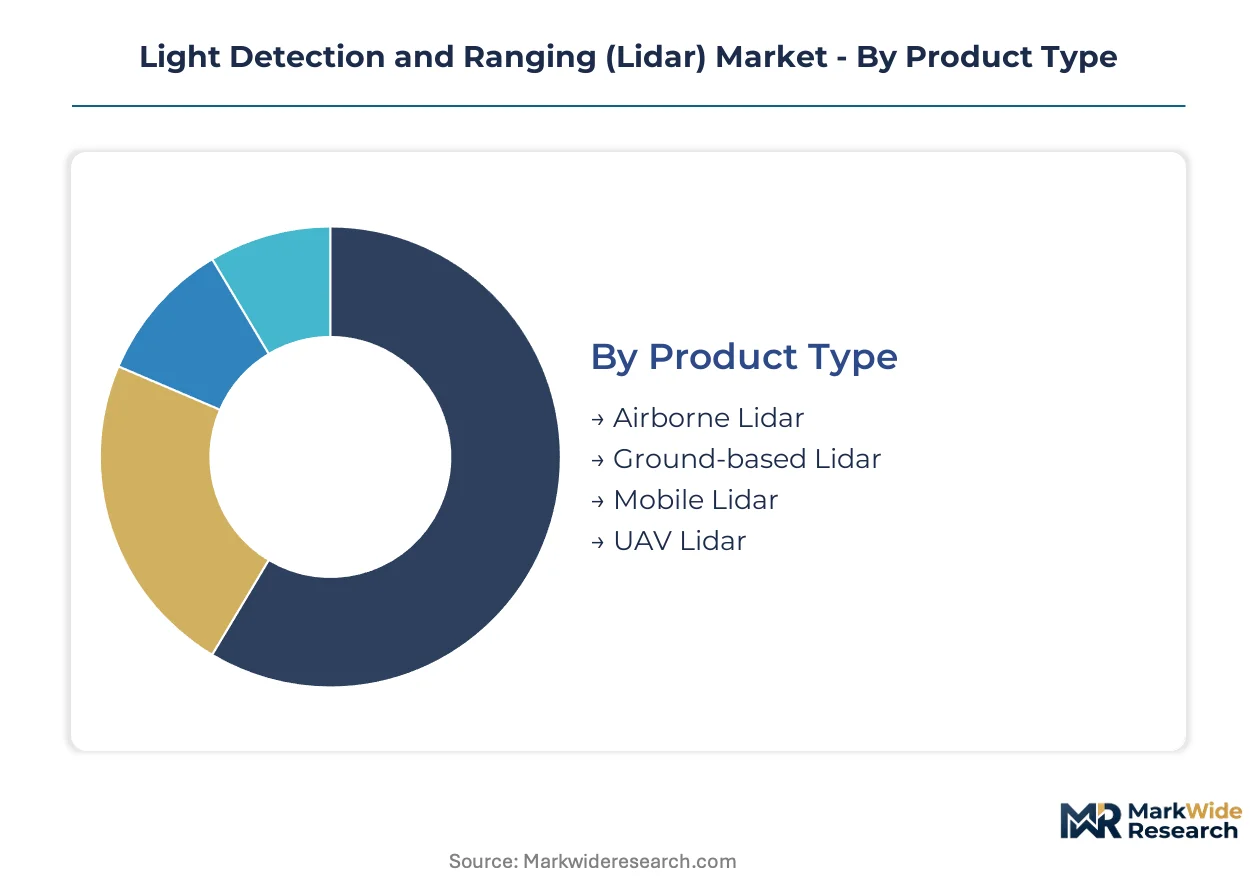
Segmentation in lidar markets reflects divergent service intensity requirements across deployment modes. Airborne platforms demand extensive calibration protocols and field engineering support, while solid-state automotive units prioritize firmware update cycles over physical maintenance.
Product Type:
After-sales service intensity varies dramatically across platform categories, with airborne systems requiring dedicated flight crews and ground-based units needing periodic recalibration contracts.
- Airborne Lidar:Aircraft-mounted laser scanning systems integrate inertial measurement units with GPS receivers for corridor mapping and topographic surveys. Forestry departments in Canada and Australia maintain dedicated flight operations teams for canopy penetration studies. By volume, Ground-based Lidar leads. By growth pace, UAV Lidar is ahead.
- Ground-based Lidar:Tripod-mounted terrestrial scanners capture millimeter-accurate point clouds for construction progress monitoring and heritage documentation. Civil engineering firms in Germany deploy these units for bridge deformation tracking under ISO standards. By volume, Ground-based Lidar leads. By growth pace, UAV Lidar is ahead.
- Mobile Lidar:Vehicle-mounted systems combine multiple laser emitters with odometry sensors for road network inventory.
- UAV Lidar:Compact solid-state emitters on drones enable precision agriculture and infrastructure inspection with rapid deployment cycles.
By volume, Ground-based Lidar leads. By growth pace, UAV Lidar is ahead.
Technology:
Cost tiers separate legacy mechanical architectures from emerging solid-state designs, with flash emitters commanding premium pricing for instantaneous capture capabilities.
- Flash Lidar:Solid-state emitter arrays illuminate entire scenes simultaneously without mechanical scanning, enabling cabin monitoring and near-field obstacle detection. Automotive OEMs in Japan specify these units for driver attention systems under METI safety guidelines. Pulsed Lidar retains volume leadership. Flash Lidar exhibits the steepest expansion trajectory.
- Pulsed Lidar:Time-of-flight measurement via nanosecond laser pulses dominates long-range detection for highway autonomy and aerial mapping. Robotaxi operators in California standardize on 1550nm fiber variants for eye-safe extended range. Pulsed Lidar retains volume leadership. Flash Lidar exhibits the steepest expansion trajectory.
- Continuous Wave Lidar:Frequency-modulated coherent detection enables Doppler velocity measurement for adaptive cruise control systems.
- Coherent Lidar:Heterodyne detection architectures provide velocity resolution for wind sensing and atmospheric research applications.
Pulsed Lidar retains volume leadership. Flash Lidar exhibits the steepest expansion trajectory.
End User:
Application maturity determines margin structures, with established civil engineering workflows limiting pricing flexibility versus emerging autonomous vehicle procurement.
- Civil Engineering:Construction firms and surveyors deploy ground-based scanners for as-built documentation and volumetric calculations. Infrastructure monitoring contracts in the UK specify continuous point cloud capture for rail corridor maintenance. Civil Engineering dominates current procurement volumes. Aerospace climbs fastest on satellite deployment schedules.
- Aerospace:Satellite manufacturers integrate compact lidar units for terrain mapping and atmospheric profiling missions. NASA and ESA procurement cycles drive qualification requirements for space-grade photodetector reliability. Civil Engineering dominates current procurement volumes. Aerospace climbs fastest on satellite deployment schedules.
- Agriculture:Precision farming operations adopt UAV-mounted units for crop height measurement and yield prediction modeling.
- Forestry:Timber companies utilize canopy penetration algorithms for biomass estimation and harvest planning optimization.
Civil Engineering dominates current procurement volumes. Aerospace climbs fastest on satellite deployment schedules.
Application:
Customer type bifurcation separates enterprise fleet operators with multi-year service agreements from project-based survey contractors.
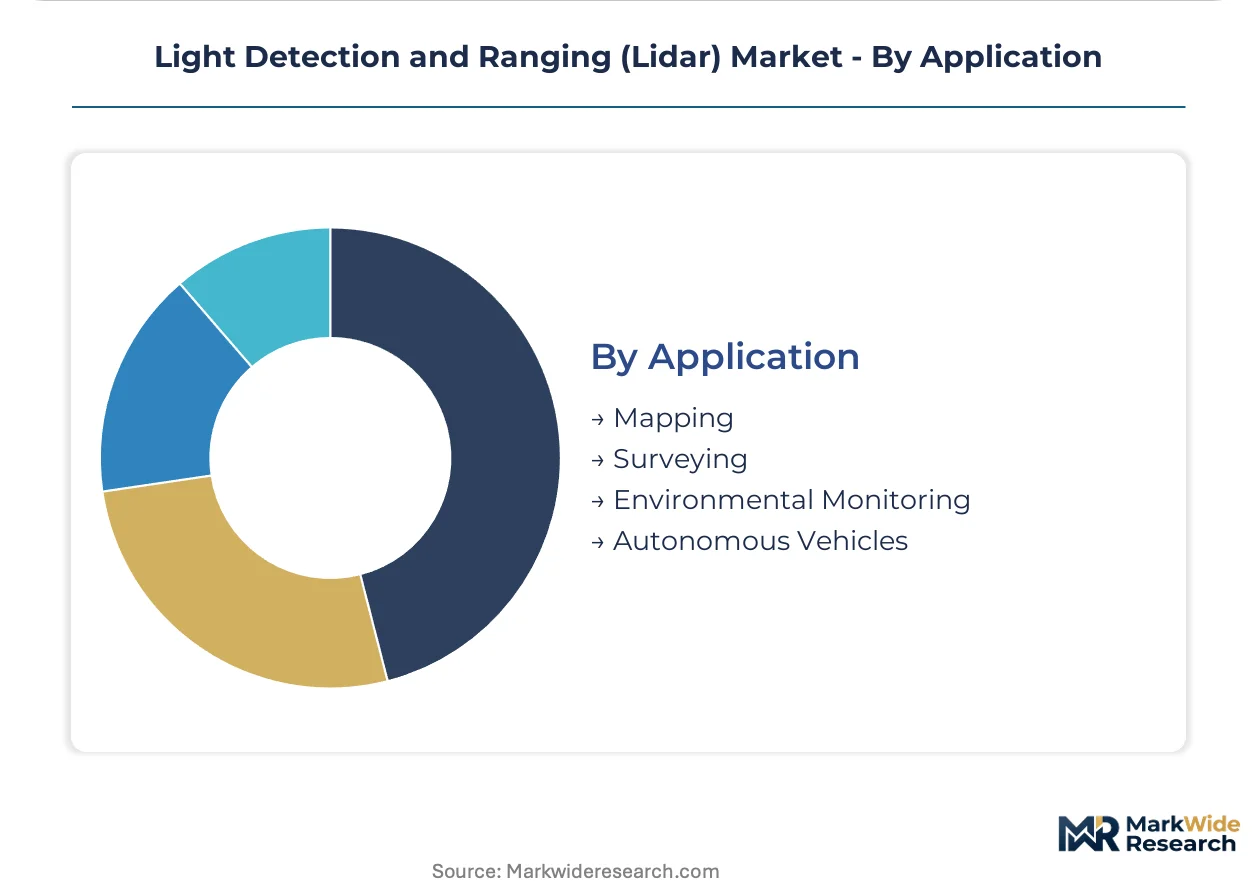
- Autonomous Vehicles:Robotaxi and passenger car programs specify automotive-grade solid-state units with ASIL-D functional safety certification. NHTSA testing protocols and KBA type-approval frameworks impose dual compliance burdens for cross-border deployment. Mapping commands the largest installed base. Autonomous Vehicles gain share fastest.
- Mapping:National mapping agencies and commercial geospatial firms accumulate archival point cloud libraries for urban planning and flood modeling. USGS and Ordnance Survey procurement specifications influence emitter wavelength selection across vendor portfolios. Mapping commands the largest installed base. Autonomous Vehicles gain share fastest.
- Surveying:Licensed surveyors utilize terrestrial and mobile systems for boundary delineation and topographic base mapping.
- Environmental Monitoring:Research institutions track coastal erosion, glacier retreat, and carbon stock changes through repeat-pass lidar acquisition.
Mapping commands the largest installed base. Autonomous Vehicles gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in lidar procurement diverges sharply between Chinese manufacturing clusters and European certification corridors. German OEMs absorb 40-60% premiums for automotive-grade units that satisfy KBA type-approval protocols. Chinese fabs export cost-optimized mechanical spinning systems at margins that compress pricing floors for mapping equipment worldwide.
United States
Robotaxi fleet operators in California and Arizona absorb solid-state volumes through multi-year service agreements that amortize sensor costs. NHTSA maintains parallel certification tracks for road vehicles and commercial drones, creating dual compliance burdens for cross-application vendors. Silicon Valley engineering teams concentrate on point cloud processing silicon for real-time 3D reconstruction.
Germany
Mercedes-Benz and BMW procurement teams specify 1550nm fiber laser architectures for premium passenger vehicle highway pilot systems. German KBA type-approval examiners reject submissions lacking Monte Carlo simulation datasets for snow and spray occlusion. Stuttgart and Munich host dedicated homologation teams staffed by ISO 26262 ASIL-D certification specialists.
China
Manufacturing concentration for cost-optimized mechanical spinning units bound for mapping and surveying export markets sits in Yangtze River Delta production corridors. MIIT standards for automotive lidar performance create domestic certification requirements parallel to UNECE frameworks. Hesai Group dominates volume shipments for robotaxi programs through in-house manufacturing scale.
Japan
METI subsidies for warehouse automation and port container handling accelerate 3D perception deployment in facilities near Yokohama and Kobe. Automotive OEMs specify flash lidar units for driver attention systems under METI safety guidelines. JIS standards for industrial lidar reliability influence procurement specifications across Asia-Pacific distribution networks.
India
UAV-mounted solid-state units for crop health monitoring remain underdeployed relative to GPS-guided spraying equipment, creating first-mover terrain mapping contracts. BIS certification requirements for drone-mounted sensors impose testing protocols that delay market entry for foreign suppliers. Karnataka and Maharashtra host precision agriculture pilot programs integrating compact solid-state emitters.
Light Detection and Ranging (Lidar) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in emitter and photodetector supply. The vendor base compresses into three tiers: vertically integrated automotive suppliers, pure-play lidar specialists, and diversified industrial sensor conglomerates. Competitive positioning depends on certification velocity in European markets and manufacturing scale in Chinese production corridors. M&A activity concentrates on photodetector IP and FPGA processing stacks; strategic partnerships bridge automotive Tier 1 distribution gaps.
Within the automotive-grade tier, Hesai Group and Innoviz Technologies exemplify divergent scale strategies. Valeo occupies a position among European integrated suppliers with deep OEM partnerships. Sick AG represents the industrial sensor conglomerate archetype with diversified automation portfolios. These three anchors illustrate how geographic certification requirements and manufacturing location determine competitive positioning.
| Leading Market Players |
|---|
| Hesai Group |
| Valeo |
| Sick AG |
| Faro Technologies |
| Trimble Navigation Limited |
| Leica Geosystems AG |
| Velodyne LiDAR |
| Innoviz Technologies |
| Teledyne Optech |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta fabs compress mechanical spinning unit costs below $500 thresholds, forcing European solid-state vendors to defend premium positioning through KBA certification moats. This geographic asymmetry in manufacturing scale versus regulatory stringency defines pricing power distribution across automotive and mapping segments.
Pricing Analysis
Configured-to-order pricing for airborne lidar with dedicated flight crews and calibration protocols commands spreads exceeding standard solid-state automotive units by multiples. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive-grade sensors from industrial reliability tiers and cost-optimized mechanical units. Pricing pressure stems from Chinese manufacturing scale in mechanical spinning architectures, compressing mapping equipment margins. Fleet operators with multi-year robotaxi service agreements exhibit lowest price sensitivity; project-based survey contractors face highest procurement pressure.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese and Chinese GaAs wafer refiners anchor 1550nm fiber laser input costs for premium automotive programs. Manufacturing concentrates in China, Japan, and Germany across emitter, photodetector, and final assembly tiers. The chain draws from gallium arsenide substrates, indium gallium arsenide photodetector arrays, and FPGA processing silicon. Single-source vulnerability concentrates in TSMC and Samsung foundry allocation for real-time 3D reconstruction ASICs. Distribution runs through direct manufacturer contracts with fleet operators and automotive Tier 1 suppliers, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware update subscriptions and field calibration service contracts expand faster than hardware shipments, converting lidar procurement from capital expenditure to operational expenditure models. This service-attach dynamic favors vendors with embedded software capabilities and regional field engineering presence.
For Market Incumbents: Harden ASIL-D certification velocity through Stuttgart and Munich homologation team expansion, compressing KBA approval cycles against emerging solid-state entrants. Defend mapping margins by locking civil engineering firms into multi-year recalibration contracts with BIM software integration. Capacity addition in Yangtze River Delta production corridors protects cost position against vertical integration moves by robotaxi operators.
For New Entrants and Emerging Players: India's precision agriculture UAV lidar penetration remains underdeployed relative to GPS-guided spraying equipment, creating first-mover terrain mapping contracts in Karnataka and Maharashtra pilot programs. Flash lidar cabin monitoring applications under METI safety guidelines offer white-space entry with lower certification barriers than highway autonomy. Go-to-market through precision agriculture OEM partnerships bypasses automotive Tier 1 distribution consolidation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photodetector IP and FPGA processing stack specialists over mechanical spinning hardware commoditizers. Long-term viability hinges on software-defined perception architectures and multi-sensor fusion integration capabilities. The signal to watch is consolidation of robotaxi procurement through direct manufacturer contracts, indicating which vendors achieve escape velocity from Tier 1 channel compression.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | German KBA type-approval expertise gates European automotive procurement for highway pilot systems. |
| Photodetector IP Acquisition | Indium gallium arsenide array capabilities differentiate flash lidar for cabin monitoring applications. |
| Direct Fleet Supply Agreements | Waymo and Cruise procurement consolidation favors vendors with California and Arizona engineering presence. |
| Precision Agriculture Partnership | UAV-mounted solid-state deployment in India creates recurring terrain mapping revenue streams. |
| Multi-Sensor Fusion Integration | Timestamp synchronization with camera and radar delays platform integration by 6-12 months without specialized protocols. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with automotive Tier 1 procurement managers, OEM platform engineers, robotaxi fleet operations directors, civil engineering firm survey leads, and precision agriculture UAV operators. Secondary validation drew from NHTSA testing protocol disclosures, KBA type-approval submission databases, METI subsidy program announcements, and USGS procurement specifications. Bottom-up shipment modeling triangulated against top-down automotive production and mapping equipment spend estimates.
Calibration against historical certification cycle durations and foundry allocation announcements anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include platform category, emitter technology architecture, end-use industry vertical, application type, and regional regulatory cluster. CAGRs derived from technology adoption S-curves and fleet operator procurement commitment schedules, with automotive-grade solid-state penetration and UAV agriculture deployment as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by robotaxi operators or foundry capacity expansion by photodetector specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Hall-Effect Sensors Market