
 Global RFID Sensor Market | 2026-2036
Global RFID Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global RFID Sensor Market Outlook
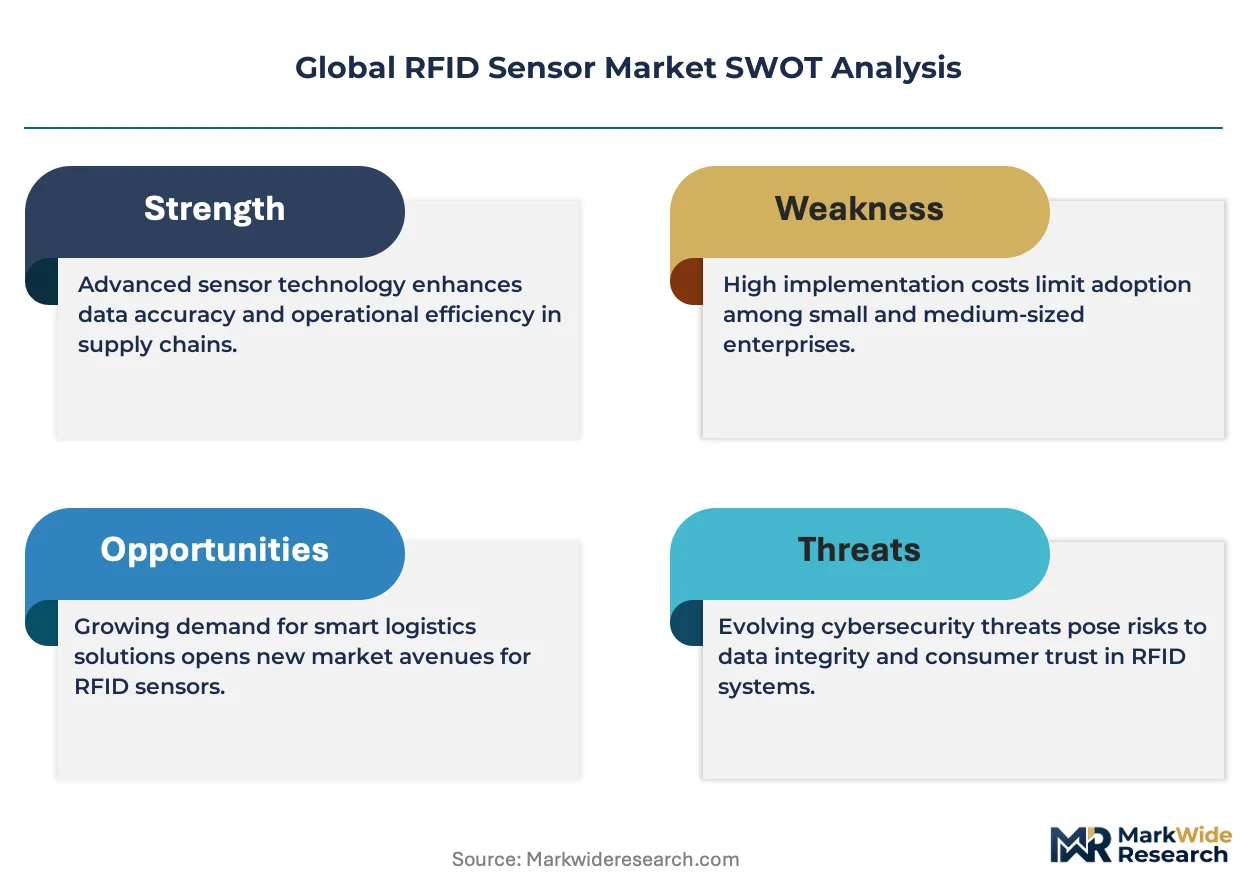
The premium RFID sensor tier is consolidating around encrypted, multi-protocol chips with integrated environmental sensing, while commodity passive tags face margin compression from Asian module assemblers. Zebra Technologies Corp. dominates enterprise-grade handheld interrogator systems through its captive antenna design capabilities. Impinj leverages its proprietary RAIN RFID endpoint IC portfolio to anchor market share in retail item-level tagging. Honeywell International competes across industrial automation by bundling RFID sensors with its broader warehouse execution software stack.
RFID sensors are wireless transponders combining radio-frequency identification with embedded sensing elements such as temperature, humidity, or pressure detectors, typically operating across 125 kHz low frequency to 960 MHz ultra-high frequency bands with read ranges from centimeters to fifteen meters depending on antenna configuration and power source. Their primary commercial purpose is to deliver real-time, non-line-of-sight object identification coupled with environmental condition monitoring for automated decision systems. Passive RFID tags occupy the highest unit volume position but carry thin margins, while active RFID segments with onboard power and sensor fusion command premium pricing in cold chain pharmaceutical logistics. Ultra-High Frequency technology leads value generation due to its balance of read range and tag cost, though Near Field Communication is deepening penetration in consumer-facing retail authentication and access control applications.
The Federal Communications Commission shapes U.S. market access through spectrum allocation rules for UHF RFID at 902–928 MHz, while the European Telecommunications Standards Institute enforces harmonized frequency bands and power limits across member states. REACH compliance from the European Chemicals Agency restricts hazardous substances in tag substrates and adhesives, pushing manufacturers toward halogen-free antenna laminates. China's Ministry of Industry and Information Technology mandates GB standards conformance for domestic RFID deployments in rail and logistics infrastructure. Stakeholders must monitor evolving spectrum reallocation proceedings and material compliance deadlines to preserve product certification validity and avoid supply chain discontinuities.
Market Dynamics
Encrypted multi-protocol RFID architectures are consolidating market power around vendors with captive semiconductor design capabilities, while passive tag assemblers face margin compression from oversupply in Asian module production. The EU AI Act and GDPR compliance requirements are accelerating demand for privacy-preserving sensor deployments.
Growth Catalysts
- EU AI Act mandates:Healthcare facilities across Germany and France must deploy encrypted patient-tracking RFID systems to satisfy automated decision-system audit requirements.
- Pharmaceutical cold chain expansion:Temperature-sensing active tags are penetrating vaccine distribution networks as regulators tighten environmental monitoring protocols.
- Industrial cluster concentration:Automotive manufacturers in Stuttgart and Wolfsburg are driving high-frequency RFID adoption for precision asset management.
Market Restraints
- Silicon wafer cost volatility:Input price swings for 300mm semiconductor substrates compress margins for integrated sensor IC fabricators.
- Asian module assembler oversupply:Concentrated production in Shenzhen and Dongguan floods commodity passive tag markets with undifferentiated capacity.
- UHF spectrum fragmentation:Divergent frequency allocations between FCC and ETSI jurisdictions force dual-SKU inventory strategies.
Strategic Opportunities
- Brazilian pharma logistics:ANVISA cold chain mandates create first-mover advantage for encrypted environmental-sensing tag vendors.
- Sensor-AI convergence:Edge-computing RFID interrogators with onboard inference engines enable real-time anomaly detection without cloud dependency.
- Direct-to-fleet distribution:Bypassing traditional systems integrators, chip vendors now sell RAIN RFID endpoint ICs directly to warehouse automation buyers.
Industry Challenges
- RF engineering talent scarcity:Antenna design and impedance-matching expertise concentrates among legacy radar specialists approaching retirement.
- REACH compliance timelines:ECHA deadlines for halogen-free substrate materials force rapid qualification of new adhesive chemistries.
- Legacy WMS integration friction:SAP and Oracle warehouse management systems require custom middleware for sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RFID Sensor Market |
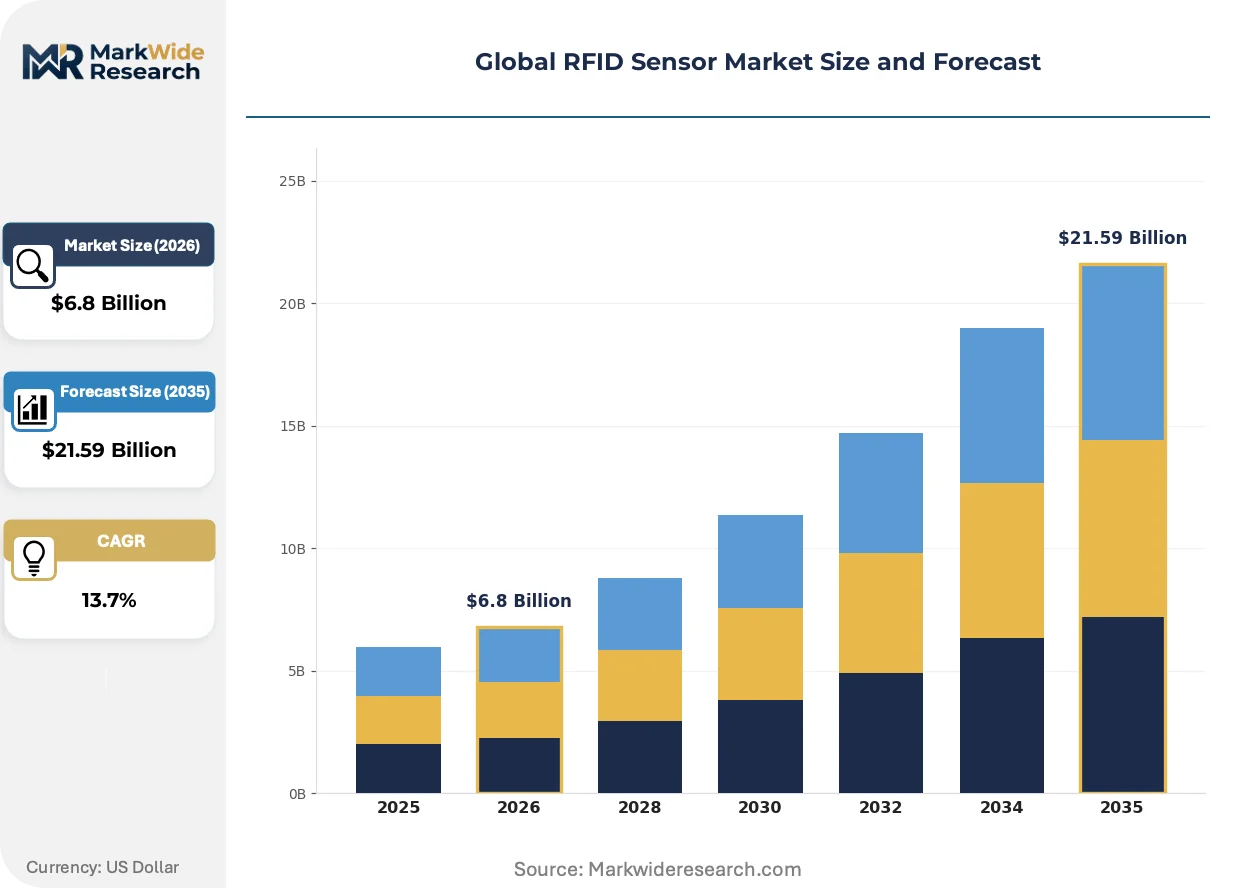
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID, Passive RFID, Semi-Passive RFID, RFID Interrogator Application: Warehouse Management, Asset Tracking, Inventory Management, Personnel Tracking End User: Retail Sector, Manufacturing Industry, Healthcare Facilities, Transportation Services Technology: Near Field Communication, Ultra-High Frequency, Low Frequency, High Frequency |
| Companies Covered | Zebra Technologies Corp., Honeywell International, Impinj, Avery Dennison, NXP Semiconductors, HID Global, Assa Abloy, CCL Industries, Alien Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RFID Sensor Market Strategic Shifts
RFID sensor architectures are bifurcating between premium encrypted systems with environmental fusion and stripped-down passive tags competing on unit economics alone.
Chipless RFID sensors based on printable carbon-nanotube resonators are expanding into disposable pharmaceutical packaging applications. Generic drug distributors in India and Southeast Asia adopt these tags for single-use temperature verification. The technology is expanding into markets where silicon IC costs previously blocked item-level deployment.
REACH restrictions from ECHA now prohibit brominated flame retardants in RFID antenna laminates used throughout European supply chains. Manufacturers must reformulate substrate adhesives with phosphorus-based alternatives or risk product certification invalidation. German automotive suppliers face the steepest reformulation deadlines.
Buying committees at large retailers now unbundle RFID hardware procurement from systems integration services. Direct sourcing of interrogators and endpoint ICs compresses implementation timelines but shifts antenna-tuning and middleware burden onto internal engineering teams. This pattern is most visible among US grocery and apparel chains with captive distribution networks.
Global RFID Sensor Market Segmentation
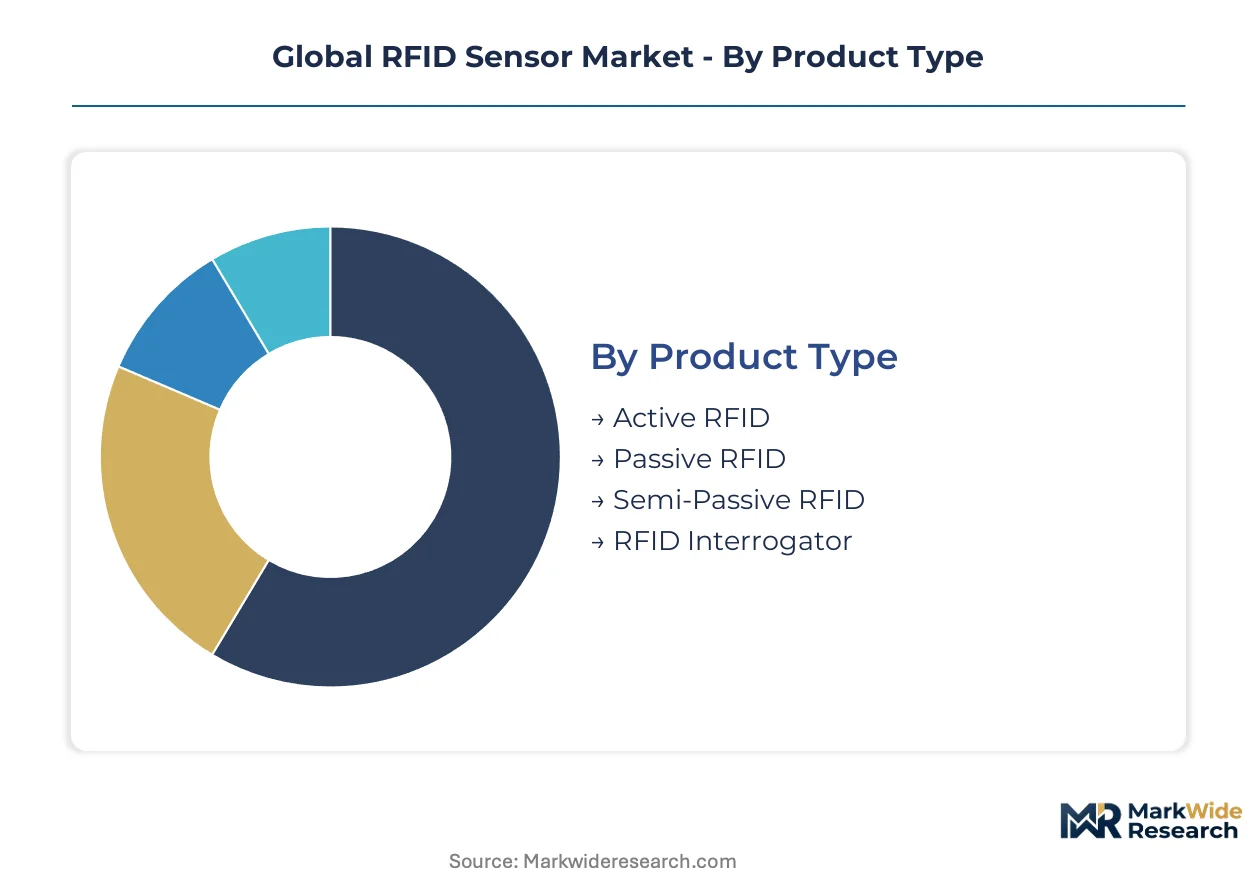
RFID sensor architectures diverge sharply across power source, frequency band, and integration depth, with each configuration commanding distinct margin profiles and deployment complexity. Procurement patterns cluster around application-specific read range requirements and environmental sensing capabilities rather than generic hardware specifications.
Product Type:
Power autonomy defines the technical architecture and total cost of ownership across RFID sensor deployments.
- Active RFID:Onboard battery supplies continuous transmission and sensor fusion for temperature, humidity, or shock monitoring. Pharmaceutical cold chain logistics in Germany and France mandate these units for regulatory compliance with environmental audit trails.
- Passive RFID:Harvests interrogator energy for backscatter communication, eliminating maintenance cycles. Retail apparel tagging across US grocery chains exploits the sub-cent unit economics for item-level inventory visibility.
- Semi-Passive RFID:Combines battery-assisted sensor operation with passive backscatter transmission, extending operational life in asset monitoring. Automotive suppliers in Stuttgart deploy these for precision tool tracking without active tag maintenance overhead.
- RFID Interrogator:Fixed or handheld reader systems with captive antenna designs dominate enterprise-grade deployments. Warehouse automation buyers now source these directly from semiconductor vendors, bypassing traditional systems integrators.
Mature deployment sits with Passive RFID. Newer deployment is concentrated in Active RFID.
Application:
Operational use case dictates antenna configuration, middleware integration depth, and regulatory compliance burden.
- Warehouse Management:Real-time location systems integrate RFID with warehouse execution software for automated put-away and picking validation. US distribution centers with captive networks drive direct-to-fleet procurement of RAIN RFID endpoint ICs.
- Asset Tracking:Precision positioning of high-value equipment requires high-frequency RFID with triangulation algorithms. German automotive clusters in Wolfsburg anchor demand for centimeter-level accuracy in production line tooling.
- Inventory Management:Bulk reading of palletized goods exploits UHF multi-tag detection at fifteen-meter ranges. Brazilian pharma distributors adopt encrypted tags under ANVISA cold chain mandates.
- Personnel Tracking:GDPR-compliant encrypted architectures dominate healthcare facility deployments across France and Germany for patient flow optimization.
Volume concentration rests in Inventory Management. Fastest value expansion is occurring in Asset Tracking.
End User:
Sector-specific compliance regimes and automation maturity shape procurement specifications and vendor selection criteria.
- Retail Sector:Apparel and grocery chains unbundle hardware from integration services, shifting antenna-tuning burden to internal engineering teams. Item-level tagging penetration is deepest among US operators with captive distribution networks.
- Manufacturing Industry:Industrial automation bundles RFID sensors with broader control system architectures. German automotive suppliers face accelerated REACH deadlines for halogen-free antenna laminates.
- Healthcare Facilities:EU AI Act mandates drive encrypted patient-tracking deployments with automated decision-system audit capabilities. Facilities across Germany and France lead regulatory-compliant procurement.
- Transportation Services:Rail and logistics infrastructure in China follows MIIT GB standards conformance for domestic deployments. Cold chain verification for vaccine distribution networks is expanding fastest here.
Procurement scale favors Manufacturing Industry. Regulatory tailwinds are strongest in Healthcare Facilities.
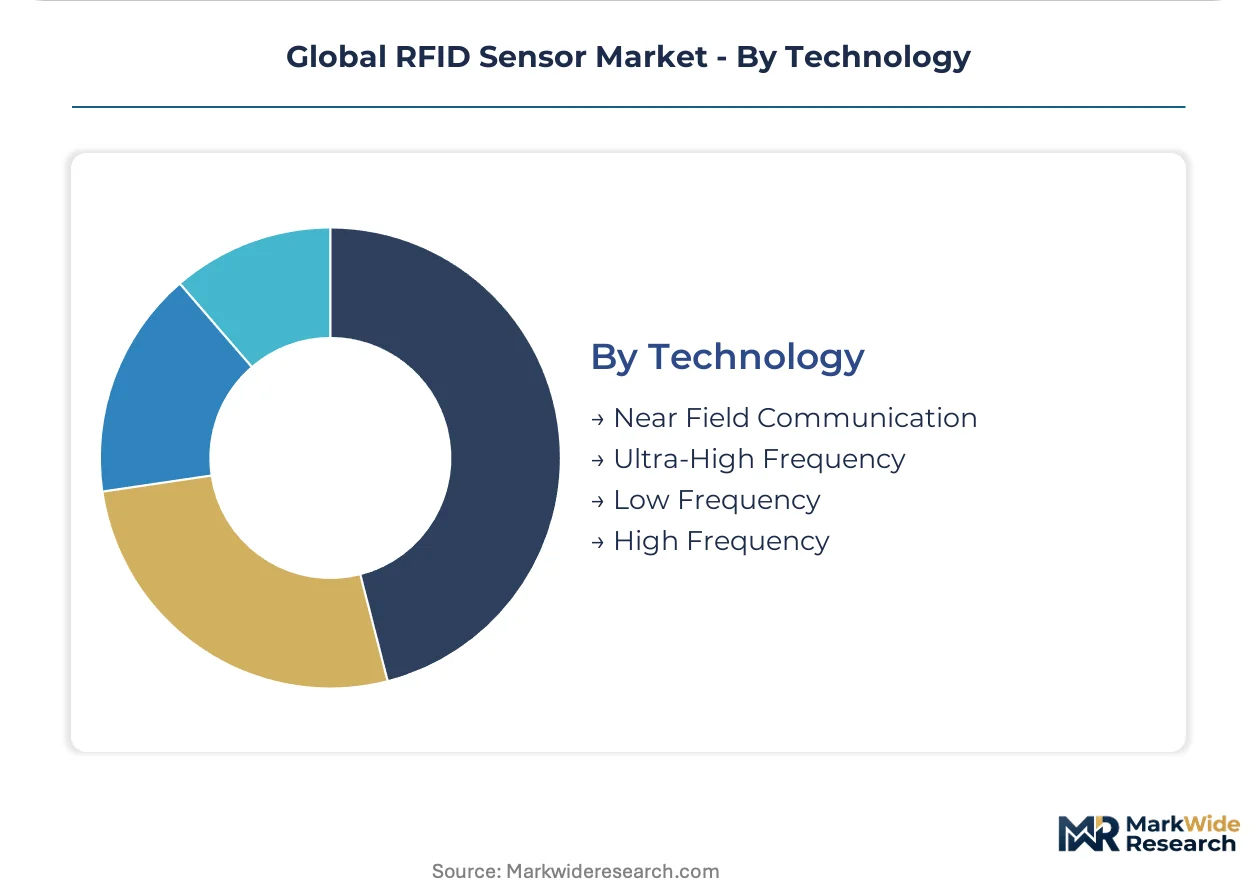
Technology:
Frequency band selection trades read range against interference susceptibility and tag cost structure.
- Near Field Communication:13.56 MHz operation with mandatory encryption suits consumer-facing authentication and access control. Retail payment integration and pharmaceutical anti-counterfeiting concentrate demand in European and Asian markets.
- Ultra-High Frequency:860–960 MHz delivers optimal range-to-cost ratio for supply chain visibility. Divergent FCC and ETSI spectrum allocations force dual-SKU inventory strategies for global tag vendors.
- Low Frequency:125–134 kHz penetrates liquid and metal environments for animal identification and industrial container tracking. Niche applications in harsh environments sustain thin-margin production.
- High Frequency:13.56 MHz with extended read range supports precision asset management in dense metallic environments. Stuttgart automotive manufacturers drive adoption for production line tool verification.
Value generation concentrates in Ultra-High Frequency. Deepest penetration gains are occurring in Near Field Communication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision RFID deployment for German automotive manufacturing, while Wolfsburg clusters anchor high-frequency adoption for production line tooling verification.
United States
Warehouse automation buyers drive direct procurement of RAIN RFID endpoint ICs for captive distribution networks. FCC spectrum allocation at 902–928 MHz shapes UHF tag design specifications. Distribution centers across the Midwest and Southeast exploit fifteen-meter read ranges for bulk pallet detection.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg mandate high-frequency RFID for centimeter-level asset positioning. EU AI Act and GDPR compliance accelerate encrypted patient-tracking deployments in healthcare facilities. REACH deadlines from ECHA force rapid qualification of halogen-free antenna laminates among industrial suppliers.
China
MIIT GB standards conformance governs domestic rail and logistics infrastructure deployments. Shenzhen and Dongguan module assemblers flood commodity passive tag markets with concentrated production capacity. Cold chain verification networks expand fastest in vaccine distribution corridors.
Brazil
ANVISA cold chain mandates create procurement urgency for encrypted environmental-sensing tags among pharmaceutical distributors. Temperature-sensing active tags penetrate vaccine logistics networks under tightened monitoring protocols. São Paulo anchors demand concentration for regulatory-compliant sensor deployments.
France
Healthcare facilities deploy GDPR-compliant encrypted architectures for patient flow optimization. CNIL enforcement shapes privacy-preserving sensor specifications across hospital networks. Paris and Lyon clusters lead regulatory-compliant procurement for automated decision-system audit capabilities.
Global RFID Sensor Market Competitive Environment
Premium-margin players sit above commodity-margin players across semiconductor integration depth, with encrypted multi-protocol architectures commanding pricing power over undifferentiated passive tag assemblies. The vendor base stratifies between captive chip designers, systems integrators with captive antenna capabilities, and module assemblers competing on unit economics. Three archetypes dominate: semiconductor specialists with proprietary endpoint IC portfolios, industrial automation bundlers with warehouse execution software stacks, and Asian module fabricants with scale-driven cost positions. Competitive moves concentrate on direct-to-fleet distribution bypassing traditional integrators, and rapid reformulation of substrate materials to preserve REACH certification validity.
Within the semiconductor specialist tier, Impinj and NXP Semiconductors exemplify proprietary IC portfolio strategies that anchor market positioning. Zebra Technologies Corp. occupies a position among systems integrators with captive hardware design capabilities. Honeywell International sits within the industrial automation bundler archetype, representing the pattern of RFID sensor integration with broader control system architectures.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| Honeywell International |
| Impinj |
| Avery Dennison |
| NXP Semiconductors |
| HID Global |
| Assa Abloy |
| CCL Industries |
| Alien Technology |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up semiconductor specialists have consolidated captive IC design capabilities across Germany and the United States, tightening pricing discipline for encrypted multi-protocol architectures while flooding commodity passive tag markets with undifferentiated Asian capacity.
Pricing Analysis
Value-based pricing anchored to regulatory compliance outcomes dominates encrypted RFID architectures, with healthcare facilities paying premiums for GDPR-auditable patient-tracking systems. Price differentiation separates REACH-certified halogen-free laminates from standard substrate tiers, with German automotive suppliers absorbing the steepest certification premiums. Cost compression in passive tag production intensifies because Shenzhen module assemblers expanded wafer-scale output. Retail apparel chains with captive distribution networks exhibit highest price sensitivity, while pharmaceutical cold chain operators demonstrate lowest sensitivity due to ANVISA audit mandates.
Supply Chain Analysis
Single-source vulnerability sits with 300mm silicon wafer fabrication concentrated in Taiwan and South Korea, where substrate input costs swing unpredictably. The RFID sensor supply chain draws from Chinese module assembly clusters, German automotive-grade laminate specialists, and U.S.-based RAIN RFID endpoint IC designers. Tariff exposure on semiconductor substrates threatens margin stability for integrated sensor fabricators. Distribution runs through direct-to-fleet channels bypassing traditional systems integrators, with warehouse automation buyers now sourcing interrogators directly from chip vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global RFID Sensor Market has become a vertical-integration race, with players pursuing backward control over antenna design and captive semiconductor fabrication to escape margin compression in commodity tag assembly.
For Market Incumbents: To counter margin erosion from Shenzhen module oversupply, Zebra Technologies and Honeywell International should deepen captive antenna-tuning capabilities and expand direct-to-fleet distribution channels. Impinj and NXP Semiconductors must accelerate proprietary RAIN RFID endpoint IC roadmaps to defend encrypted architecture premiums against Asian cost competition. Certification investment in ECHA REACH-compliant halogen-free substrates preserves European automotive access. For New Entrants and Emerging Players: Launch via sensor-AI convergence targeting Brazilian pharmaceutical distributors under ANVISA cold chain mandates, where encrypted environmental-sensing tags face limited incumbent saturation. Chipless RFID specialists should penetrate Indian generic drug packaging through printable carbon-nanotube resonators, exploiting silicon IC cost barriers that previously blocked item-level deployment. Direct sourcing relationships with São Paulo logistics clusters offer fastest route to regulatory-compliant revenue. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap antenna design houses with impedance-matching expertise in Germany and the United States, where RF engineering talent scarcity concentrates value. Long-term viability across the analysis window hinges on semiconductor integration depth rather than module assembly scale. Watch for FCC-ETSI spectrum harmonization proceedings as inflection signal for dual-SKU inventory rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive IC production shields Impinj and NXP from wafer cost volatility. |
| Direct-to-Fleet Distribution Bypass | Warehouse automation buyers at Kroger and Target compress implementation timelines. |
| REACH-Compliant Substrate Reformulation | German automotive suppliers face ECHA deadlines requiring phosphorus-based adhesive chemistry. |
| Sensor-AI Edge Computing Convergence | Onboard inference engines enable real-time anomaly detection without cloud dependency. |
| Chipless RFID Platform Launch | Printable carbon-nanotube resonators unlock Indian pharmaceutical packaging previously blocked by silicon costs. |
Study Parameters
Multi-period observation of RAIN RFID endpoint IC shipment volumes, ECHA REACH compliance certification timelines, and ANVISA cold chain audit adoption anchored the trend analysis, supplemented by interviews with semiconductor design executives, warehouse automation procurement directors, pharmaceutical logistics compliance officers, and RF engineering specialists. Secondary validation drew from FCC spectrum allocation proceedings, ETSI harmonization standards, MIIT GB conformance databases, and SEC 10-K filings of listed RFID vendors. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across power source, frequency band, and integration depth segments.
The input-output matrix framed demand drivers including EU AI Act mandate compliance, pharmaceutical cold chain expansion, and industrial cluster automation against supply constraints spanning silicon wafer fabrication capacity, antenna laminate material qualification, and RF engineering talent availability. Modeled dimensions encompassed product type hierarchy, application use case intensity, end-user regulatory burden, and technology frequency band adoption. CAGRs were derived from regression analysis of historical shipment trajectories adjusted for technology substitution effects and regulatory acceleration factors.
The model assumes a particular technology adoption path; alternative pathways for chipless RFID resonators would alter the outlook if printable carbon-nanotube costs decline faster than projected. Forecasts reflect documented assumptions about spectrum harmonization timelines, REACH enforcement intensity, and healthcare facility automation budgets. Deviation in FCC-ETSI frequency alignment or ECHA material ban acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Global Tilt Sensor Market