
 Encoder Market | 2026-2036
Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Encoder Market Intelligence
The EU Green Deal is restructuring demand patterns across Europe's industrial base, compelling machinery OEMs to specify higher-efficiency motion feedback systems. HEIDENHAIN dominates precision optical encoder supply for German machine tool builders. Sensata Technologies leverages its automotive heritage to anchor position sensing in electrified powertrain architectures. FRABA B.V. specializes in magnetic encoder platforms that compete on durability in harsh-environment deployments.
An encoder converts mechanical position or motion into electrical signals through optical, magnetic, or capacitive sensing principles, typically resolving angular displacement to fractions of an arc-second for closed-loop motor control. Rotary encoders generate sinusoidal or digital pulse trains proportional to shaft rotation, while linear variants track displacement along guideways with sub-micron repeatability. Absolute technology captures the fastest growth as battery-backed multi-turn systems eliminate homing routines in robotics and semiconductor equipment. Optical encoders retain margin concentration in aerospace systems and metrology where resolution requirements exceed magnetic alternatives.
The EU Machinery Directive and CE marking requirements shape product safety and electromagnetic compatibility standards for encoder integration across European automation. FDA 21 CFR Part 820 quality system regulations govern encoder performance in US medical device manufacturing equipment. China's GB standards and MIIT industrial upgrade directives accelerate domestic substitution in precision motion components. Stakeholders must monitor how functional safety certifications under ISO 13849 reshape supplier qualification timelines and R&D allocation across the value chain.
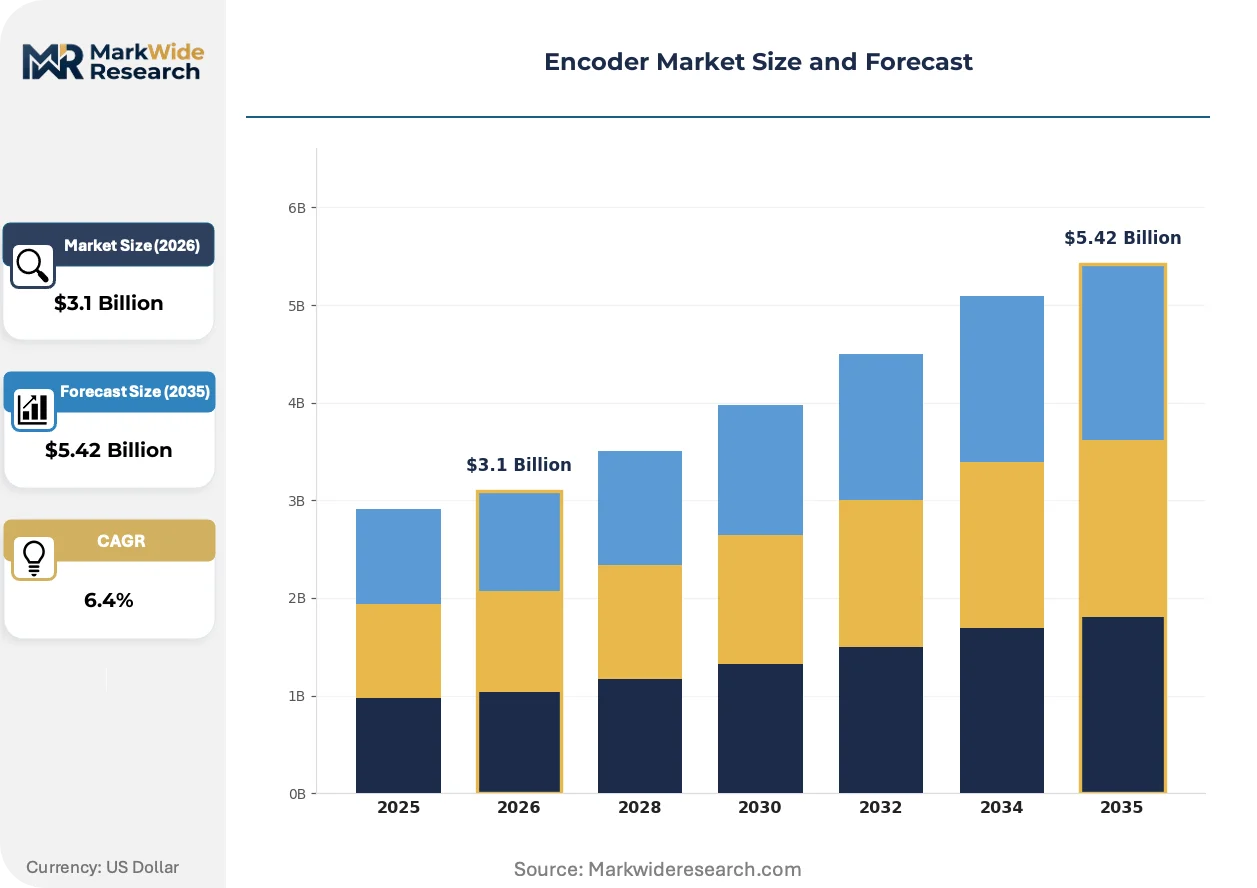
Market Dynamics
Factory automation investments from automotive OEMs are accelerating encoder deployment in precision motion systems, while the EU Green Deal's energy efficiency mandates push industrial equipment makers toward higher-resolution feedback devices across Europe's machine tool corridor.
Growth Catalysts
- EU Green Deal mandates:Energy efficiency directives compel machinery OEMs to specify higher-resolution encoders for closed-loop motor control in industrial equipment.
- Semiconductor fabrication:Absolute encoder technology eliminates homing routines in robotics and wafer handling systems, reducing cycle times in cleanroom environments.
- Stuttgart-Munich corridor:Germany's machine tool builders concentrate demand for precision optical encoders in five-axis machining centers and grinding equipment.
Market Restraints
- Rare earth magnet dependency:Magnetic encoder supply chains face input cost volatility from neodymium and dysprosium price swings in Chinese processing facilities.
- Optical component concentration:Precision glass scale and photolithography mask supply concentrates in Japanese and German specialty substrate manufacturers.
- Resolution ceiling in harsh environments:Magnetic alternatives cannot match optical encoder precision in aerospace and metrology applications requiring sub-arc-second accuracy.
Strategic Opportunities
- Indian PLI scheme:Production-linked incentives for advanced manufacturing create white space for encoder suppliers in automation and robotics assembly.
- Battery-backed multi-turn systems:Convergence of energy harvesting and wireless communication enables maintenance-free absolute position tracking in mobile robotics.
- Functional safety certification:ISO 13849 compliance creates premium pricing tiers for encoders deployed in collaborative robot joints and autonomous guided vehicles.
Industry Challenges
- Embedded firmware expertise:Shortage of engineers proficient in real-time signal processing and safety-critical software development delays product qualification timelines.
- CE marking complexity:Electromagnetic compatibility testing under the EU Machinery Directive extends certification cycles for multi-axis motion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encoder Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Linear, Optical, Magnetic, Capacitive, Inductive Technology: Absolute, Incremental, Resolver, Absolute Optical, Magnetic Resolver, Single-turn Application: Robotics, Aerospace Systems, Semiconductor Equipment, Packaging Machinery, Textile Manufacturing, Printing Machines End User Industry: Industrial Automation, Consumer Electronics, Semiconductor Fabrication, Aerospace & Defense, Packaging Sector, Textile Industry |
| Companies Covered | Sensata Technologies, HEIDENHAIN, Fortive, Renishaw plc, Mitutoyo Corporation, Pepperl+Fuchs, FRABA B.V., ifm electronic, Maxon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encoder Market Strategic Shifts & Innovations
Position sensing technology is fragmenting across optical, magnetic, and capacitive principles as end-users prioritize resolution, durability, or cost in specific deployment environments. Three forces are restructuring competitive positioning.
Capacitive encoder technology is converging with MEMS fabrication processes to deliver nanometer-scale resolution in semiconductor lithography and electron microscopy stages. Equipment builders at ASML's supplier ecosystem are qualifying these devices for vacuum-compatible motion systems. The technology is converging with traditional inductive sensing to compress price-performance ratios in mid-range automation.
REACH substance restrictions and RoHS recast directives are forcing encoder manufacturers to reformulate solder alloys and eliminate hexavalent chromium in bearing surfaces. German machine tool OEMs now specify material compliance certificates upstream in supplier qualification. Medical device builders face compounded scrutiny from MDR technical documentation requirements for encoder-integrated surgical robotics.
Buyer consolidation among automotive Tier-1 suppliers is compressing qualification timelines and demanding multi-year price-down commitments in electrified powertrain contracts. Direct sourcing relationships with Stuttgart-based drivetrain specialists are displacing traditional distribution channels for high-volume rotary encoder programs. This concentration is most visible in e-motor position sensing for battery electric vehicle platforms.
Encoder Market Segmentation
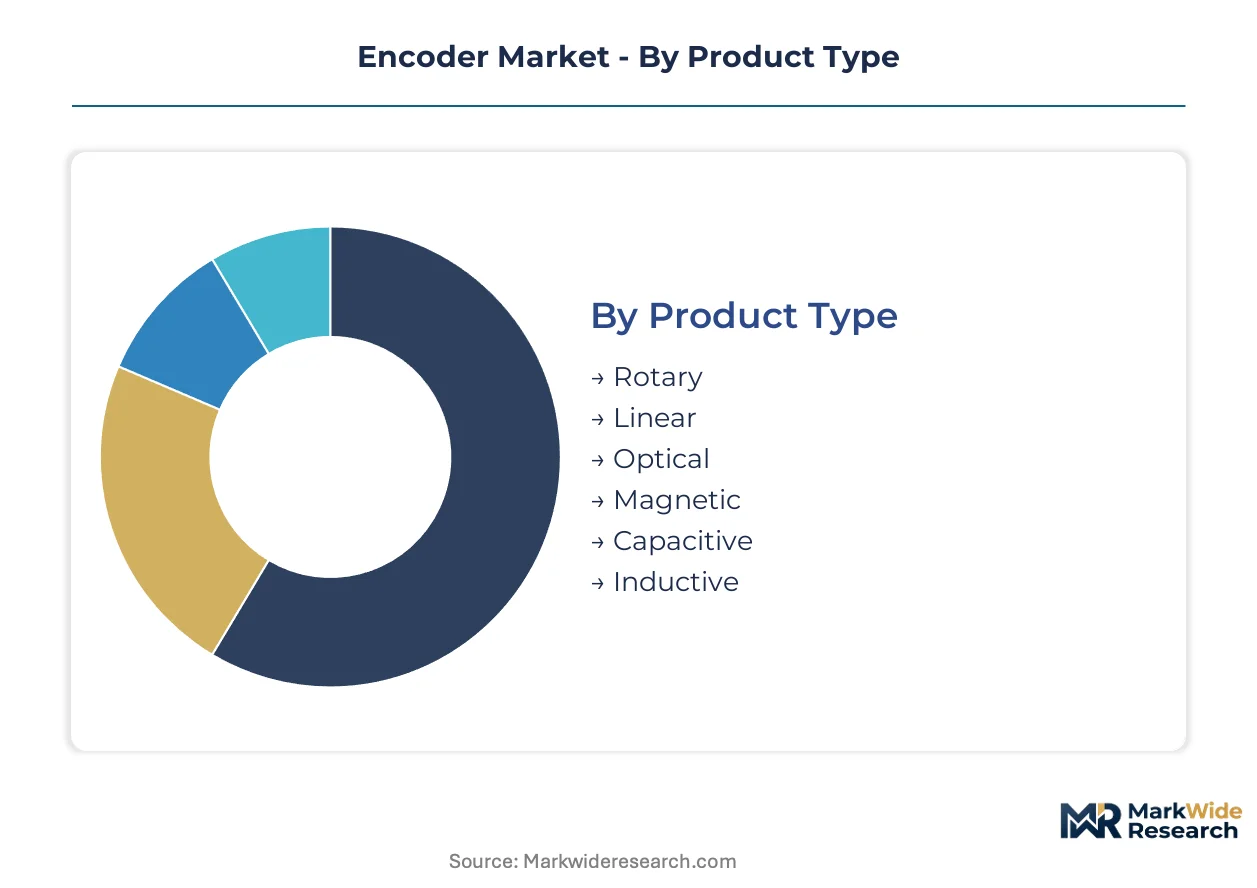
Encoder buyers segment demand across four dimensions that reshape supplier R&D priorities and channel economics. Product type and technology choices determine resolution ceilings and environmental durability, while application and end-user industry dictate certification requirements and volume concentration.
Product Type:
Buyers differentiate primarily by motion axis geometry and sensing physics, trading resolution against contamination tolerance and cost.
- Rotary:These devices measure angular displacement through shaft-mounted code discs or magnetic rings, generating pulse trains proportional to rotation. Demand clusters in Stuttgart-area automotive drivetrain programs where e-motor position feedback requires battery-backed multi-turn architectures. The EU Green Deal's efficiency mandates accelerate replacement of resolver-based systems with higher-resolution optical alternatives.
- Linear:Glass-scale or tape-based encoders track displacement along machine guideways with sub-micron repeatability. German machine tool builders around Munich specify these for five-axis machining centers where thermal expansion compensation preserves accuracy over meter-scale travels.
- Optical:Photolithographed code discs and interferometric readheads deliver sub-arc-second resolution for metrology and aerospace applications. HEIDENHAIN dominates supply for German precision equipment where resolution requirements exceed magnetic alternatives.
- Magnetic:Hall-effect or magnetoresistive sensing survives contamination in packaging machinery and mobile robotics. Rare earth magnet supply concentration in Chinese processing facilities creates input cost volatility for these programs.
- Capacitive:MEMS-fabricated sensors achieve nanometer resolution in semiconductor lithography stages. ASML's supplier ecosystem qualifies these for vacuum-compatible motion systems.
- Inductive:Eddy-current principles deliver robust position feedback in harsh environments without precision optics. These devices compete on durability in heavy machinery and mining equipment.
Rotary encoders lead volumes today; capacitive variants are gaining share fastest in semiconductor fabrication.
Technology:
Absolute versus incremental architectures separate buyers by homing routine elimination needs and power-loss position retention requirements.
- Absolute:Battery-backed multi-turn systems encode unique position values across full rotation ranges without reference moves. Semiconductor wafer handling robotics in cleanroom environments eliminate homing cycles that contaminate sensitive processes.
- Incremental:Quadrature pulse outputs require homing sequences but cost less and integrate simply into standard servo drives. These dominate high-volume packaging machinery where downtime for reference moves is acceptable.
- Resolver:Analog electromagnetic transducers survive extreme temperatures and radiation in aerospace propulsion systems. NASA and ESA programs specify these for launch vehicle actuation where semiconductor devices would fail.
- Absolute Optical:Photolithographed code discs with parallel bit outputs combine resolution with position retention. German machine tool OEMs specify these for safety-critical axes under ISO 13849 functional safety requirements.
- Magnetic Resolver:Variable reluctance sensors deliver resolver-grade durability without brush contacts. Automotive Tier-1 suppliers adopt these for electrified powertrain position sensing in cost-sensitive volume programs.
- Single-turn:Absolute position within one revolution suits indexing tables and rotary indexing machinery. These devices compete on price in standard automation where multi-turn tracking is unnecessary.
Incremental technology leads volumes today; absolute optical architectures are climbing the fastest in precision equipment.
Application:
Environmental severity and resolution requirements fragment demand across equipment types with distinct certification and qualification timelines.
- Robotics:Collaborative robot joints demand compact, safety-certified encoders under ISO 13849 with SIL 2/3 ratings. Functional safety compliance creates premium pricing tiers for suppliers qualified by KUKA and ABB.
- Aerospace Systems:Flight control actuation requires DO-178C software assurance and DO-254 hardware certification. Boeing and Airbus qualification cycles extend 3-5 years for encoder suppliers entering these programs.
- Semiconductor Equipment:Vacuum compatibility and outgassing control dominate encoder specification for EUV lithography stages. ASML's supplier ecosystem imposes material restrictions beyond standard RoHS requirements.
- Packaging Machinery:High-speed filling and sealing equipment prioritizes cost and washdown durability over ultimate precision. These applications drive volume for magnetic encoder suppliers.
- Textile Manufacturing:Yarn tension control and loom synchronization require modest resolution with high reliability in fiber-contaminated environments. Indian and Bangladeshi textile clusters concentrate demand for cost-optimized rotary encoders.
- Printing Machines:Registration control in web-fed presses demands sub-micron repeatability across thermal and tension variations. Heidelberg and Koenig & Bauer specify specialized linear encoders for these applications.
Industrial automation leads volumes today; semiconductor equipment shows the steepest expansion trajectory.
End User Industry:
Regulatory intensity and supply chain power separate buyers by certification burden and procurement leverage.
- Industrial Automation:Factory floor motion control spans conveyors, pick-and-place systems, and CNC machinery. The EU Machinery Directive's CE marking requirements shape electromagnetic compatibility testing for multi-axis systems.
- Consumer Electronics:Smartphone camera autofocus and laptop hinge position sensing demand ultra-compact, low-cost encoders. These programs compress margins and demand multi-year price-down commitments.
- Semiconductor Fabrication:Wafer handling and lithography stages require vacuum-compatible, low-outgassing position feedback. REACH substance restrictions force reformulation of bearing surfaces and solder alloys in these supply chains.
- Aerospace & Defense:Flight control and weapon system actuation imposes DO-178C and MIL-STD-810 qualification. These programs trade cost for reliability and traceability.
- Packaging Sector:Food and pharmaceutical filling equipment faces FDA 21 CFR Part 820 quality system regulations in US markets. MDR technical documentation requirements compound scrutiny for encoder-integrated surgical robotics.
- Textile Industry:Yarn processing and fabric finishing machinery operates in high-contamination environments favoring sealed magnetic encoders. India's PLI scheme for advanced manufacturing creates white space for automation suppliers in this sector.
Industrial automation leads volumes today; semiconductor fabrication is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision motion feedback engineering through its machine tool industry, establishing Stuttgart and Munich as global centers for optical encoder specification. Industrial automation investments now spread this expertise across manufacturing corridors worldwide.
United States
Automotive electrification programs at Detroit-area OEMs drive encoder deployment in e-motor position sensing systems. FDA 21 CFR Part 820 regulations govern encoder performance in surgical robotics and medical device manufacturing equipment. The Pacific Northwest semiconductor cluster demands vacuum-compatible encoders for lithography equipment builders.
Germany
The EU Green Deal's energy efficiency mandates compel machinery OEMs to specify higher-resolution encoders for closed-loop motor control. CE marking under the EU Machinery Directive shapes electromagnetic compatibility testing for multi-axis motion systems. The Stuttgart-Munich machine tool corridor concentrates demand for precision optical encoders in five-axis machining centers.
China
MIIT industrial upgrade directives accelerate domestic substitution in precision motion components across automation and robotics sectors. GB standards establish technical benchmarks for encoder integration in domestic manufacturing equipment. The Yangtze River Delta semiconductor fabrication cluster imports vacuum-compatible encoders for EUV lithography stages.
Japan
METI technology roadmaps prioritize high-resolution position sensing in next-generation manufacturing equipment. JIS standards codify encoder performance specifications for domestic machine tool builders. The Nagoya automotive manufacturing belt sources encoders for hybrid and electric powertrain production lines.
India
The PLI scheme for advanced manufacturing creates white space for encoder suppliers in automation and robotics assembly operations. BIS certification requirements shape product qualification timelines for industrial equipment imports. The Gujarat-Maharashtra industrial corridor concentrates demand for cost-optimized rotary encoders in textile and packaging machinery.
Encoder Market Key Industry Players
Premium-margin players sit above commodity-margin players across resolution tiers and certification grades in encoder supply. The vendor base stratifies between precision optical specialists serving aerospace and metrology, magnetic platform providers competing on harsh-environment durability, and scale-oriented fabricators supplying high-volume automotive programs. Three archetypes dominate: technology-origin specialists with photolithography heritage, automotive-tier suppliers leveraging powertrain integration relationships, and diversified industrial conglomerates with motion control portfolios. Competitive moves concentrate on functional safety certification acquisition and direct OEM qualification bypassing distribution channels.
Within the precision-tier segment, HEIDENHAIN GmbH and Renishaw plc exemplify European-origin specialists anchored in metrology and machine tool supply chains. Sensata Technologies Inc. occupies a position bridging automotive heritage with electrified powertrain expansion. FRABA B.V. represents magnetic encoder architecture focused on industrial durability applications.
| Leading Market Players |
|---|
| Sensata Technologies |
| HEIDENHAIN |
| Fortive |
| Renishaw plc |
| Mitutoyo Corporation |
| Pepperl+Fuchs |
| FRABA B.V. |
| ifm electronic |
| Maxon |
| Others |
Cost & Logistics Intelligence
Firmware engineering talent concentration in Germany's Stuttgart region compresses labor-cost differentials between premium optical encoder tiers and mid-range magnetic alternatives. This skill scarcity widens pricing spreads as OEMs absorb certification premiums for functional safety-qualified devices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates HEIDENHAIN-grade optical encoders from Sensata automotive volumes and Indian textile-market commodity units. Price differentiation hinges on ISO 13849 certification grade and volume scale commitments. Cost compression in standard-tier magnetic encoders is intensifying because automotive Tier-1 consolidation demands multi-year price-down contracts. Packaging machinery buyers exhibit highest price sensitivity; semiconductor lithography equipment makers show lowest.
Supply Chain Analysis
China's MIIT domestic-content mandates and India's PLI local-sourcing requirements are reshaping encoder component sourcing toward regional manufacturing hubs. Precision glass scales draw from Japanese substrate specialists and German photolithography mask suppliers; rare earth magnets rest on Chinese neodymium processing facilities. Single-source vulnerability concentrates in Japanese optical component suppliers. Distribution runs through direct OEM qualification channels displacing traditional industrial distributors in high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal efficiency mandates structurally expand demand for higher-resolution feedback devices across European industrial automation.
For Market Incumbents: Cement functional safety certification leadership by accelerating SIL 3 encoder qualification for collaborative robotics. Deepen backward integration into precision glass scale manufacturing to offset Japanese supplier concentration risk. Expand captive production of battery-backed multi-turn electronics in Stuttgart-area facilities.
For New Entrants and Emerging Players: India's textile machinery OEMs represent an underserved buyer archetype seeking cost-optimized rotary encoders with sealed contamination tolerance. Target Gujarat-Maharashtra corridor packaging automation through BIS-certified distribution partnerships. Pursue white-space positioning in capacitive encoder supply for ASML's vacuum-compatible lithography stages.
For Investors and Strategic Acquirers: Automotive Tier-1 suppliers with electrified powertrain portfolios are the most active acquirer in this space, consolidating e-motor position sensing capabilities. Five-to-ten-year viability favors magnetic encoder specialists with rare earth magnet supply hedging. Watch ASML supplier ecosystem qualification announcements as inflection indicator for capacitive technology adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | ISO 13849 SIL 3 qualification unlocks collaborative robot joint supply contracts with KUKA and ABB. |
| Backward Integration into Glass Scale Manufacturing | Captive photolithography mask production reduces dependency on Japanese specialty substrate suppliers. |
| Battery-Backed Multi-Turn Architecture Development | Eliminates homing routines in semiconductor wafer handling robotics for ASML ecosystem qualification. |
| Direct OEM Qualification Channel Establishment | Bypasses industrial distributors to secure multi-year encoder supply contracts with Stuttgart automotive Tier-1s. |
| Rare Earth Magnet Supply Hedging | Long-term offtake agreements with Chinese processing facilities stabilize magnetic encoder input costs. |
Research Approach
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each market cluster. The research combines structured interviews with OEM procurement managers, automation system integrators, semiconductor equipment engineers, and encoder manufacturer R&D directors with secondary validation against SEC filings, MIIT industrial upgrade directives, EU Machinery Directive documentation, and Japanese JIS standards databases. Bottom-up encoder shipment data triangulates against top-down industrial automation capex estimates.
Rate-of-change decomposition separates volume growth from average selling price evolution across the projection horizon. Segmentation dimensions modeled include product type, sensing technology, absolute versus incremental architecture, application severity, and end-user industry regulatory intensity. CAGRs derive from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporate EU Green Deal implementation timelines and automotive electrification platform ramp schedules.
Underlying measurement precision varies by segment; semiconductor equipment and aerospace systems carry tighter precision than packaging machinery and textile applications. Forecasts reflect assumptions around regulatory implementation pace and rare earth supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Industrial Relays Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Power Inductors Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Crystal Oscillators Market
Electronic Components
North America USB Retimer Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
USB Retimer Market
Electronic Components
Digital Class-D Amplifier Market