
 India HVDC Transmission Systems Market | 2026-2036
India HVDC Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India HVDC Transmission Systems Market Foresight
Buyer concentration among state transmission utilities is decoupling from the earlier fragmented procurement pattern dominated by central public sector undertakings. Power Grid Corporation of India Limited anchors the national ultra-high voltage direct current backbone through its ownership of the multi-terminal HVDC networks. Siemens AG leverages its voltage source converter technology leadership to compete for bipole station contracts in western renewable zones. Tata Projects Limited differentiates through integrated EPC execution capabilities spanning converter halls, electrode stations, and associated transmission corridors.
High-voltage direct current transmission systems employ power electronic converters to transmit bulk electricity over long distances with lower losses than alternating current alternatives, typically operating at voltage levels of 500 kV and above with power ratings exceeding 1,000 MW per pole. Converter stations dominate capital expenditure allocation due to their thyristor and IGBT valve hall complexity, while transmission lines constitute the largest physical footprint element. Voltage source converter technology is displacing line-commutated current source systems in new projects because of its black-start capability and independent reactive power control, particularly for offshore and weak-grid renewable integration applications.
The Central Electricity Authority mandates system planning standards that require HVDC links for inter-regional transfers exceeding 5,000 MW, while BIS certification governs converter transformer and reactor specifications for grid-connected equipment. CEA's national grid standards and the Ministry of Power's tariff regulations shape project economics by determining cost recovery mechanisms for transmission developers. Stakeholders must monitor the evolving renewable purchase obligation enforcement and green hydrogen hub electrification plans, as these will determine the next pipeline of multi-gigawatt HVDC corridors requiring converter station investments and long-distance line infrastructure.
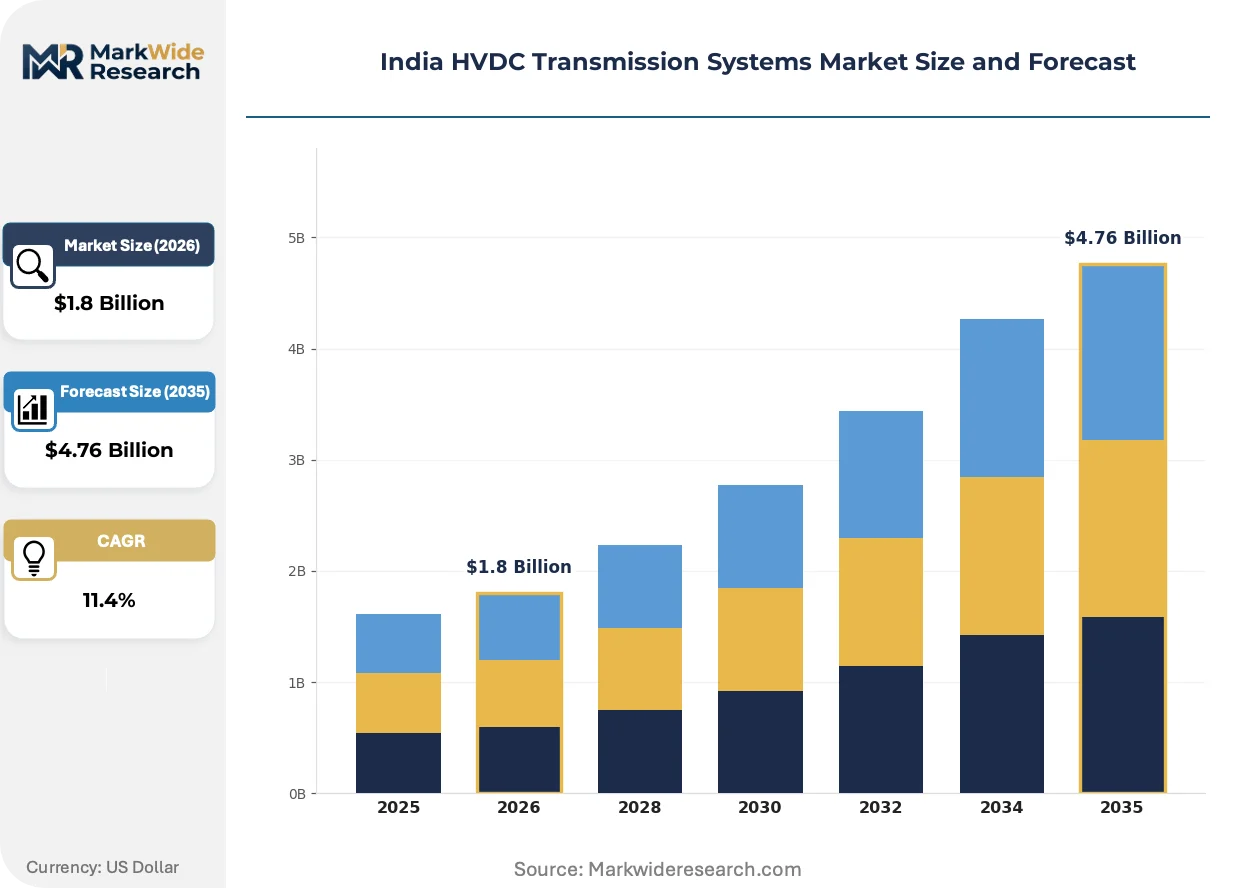
Market Dynamics
Voltage source converter technology is converging with line-commutated systems across India's renewable evacuation corridors, compressing project timelines while elevating converter station complexity. State transmission utilities now dominate procurement decisions, decoupling from the earlier central PSU-led fragmentation.
Growth Catalysts
- Green Energy Corridors mandate:Central Electricity Authority planning standards require HVDC links for inter-regional transfers exceeding 5,000 MW, forcing bipole converter station deployments in Gujarat and Rajasthan renewable zones.
- Voltage source converter adoption:Black-start capability and independent reactive power control are displacing legacy current source systems in weak-grid renewable integration applications.
- State transmission utility procurement concentration:Bulk project awards under Green Energy Corridors are consolidating buyer power among Gujarat, Rajasthan, and Maharashtra state utilities.
Market Restraints
- Converter station capital intensity:Thyristor and IGBT valve hall complexity consumes disproportionate project budgets, constraining developer balance sheets.
- Equipment import dependency:Converter transformers and semiconductor valves rely on limited qualified suppliers, exposing projects to currency and lead-time volatility.
- BIS certification timelines:Grid-connected equipment standards create extended approval cycles for converter transformers and reactors, delaying commissioning.
Strategic Opportunities
- Green hydrogen hub electrification:Ministry of Power plans for multi-gigawatt electrolyzer clusters in Kutch and Barmer will require dedicated HVDC feeder corridors.
- Offshore wind integration:Tamil Nadu and Gujarat coastal zones present untapped demand for subsea cable-connected voltage source converter stations.
- Multi-terminal network expansion:CEA's national grid standards enable meshed HVDC topologies beyond point-to-point links, opening converter station retrofit markets.
Industry Challenges
- Specialized commissioning expertise:Bipole converter station energization requires scarce power electronics engineers familiar with both thyristor and IGBT valve technologies.
- Legacy AC grid synchronization:Weak receiving networks in renewable-rich states complicate fault ride-through compliance for new HVDC infeed points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India HVDC Transmission Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converter Stations, Transmission Lines, Accessories, Equipment Technology: Monopole, Bipole, Voltage Source Converter, Current Source Converter End User: Utilities, Industrial Sector, Renewable Energy Farms, Large Enterprises Application: Grid Interconnection, Power Distribution, Renewable Integration, Long-Distance Transmission |
| Companies Covered | Hitachi Energy Ltd, Siemens AG, General Electric Company, Power Grid Corporation of India Limited, Bharat Heavy Electricals Limited, Adani Transmission Ltd, Tata Projects Limited, Larsen & Toubro Limited, Prysmian Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India HVDC Transmission Systems Market Shifts & Advancements
Modular multilevel converter architectures are compressing station footprints while expanding operational flexibility. Three forces are reshaping competitive positioning: semiconductor material evolution, regulatory planning mandates, and procurement centralization among state utilities.
Silicon carbide power semiconductors are converging with conventional silicon IGBT modules in next-generation valve hall designs. Converter station OEMs are qualifying SiC-based submodule assemblies for 800 kV bipole ratings. This convergence is enabling higher switching frequencies that reduce filter bank size and station land requirements.
CEA's transmission planning mandates now require HVDC feasibility studies for all inter-regional links exceeding 5,000 MW. Developers must demonstrate loss comparisons against AC alternatives in their tariff filings. Western renewable zones face the strictest enforcement, with Rajasthan and Gujarat project approvals contingent on converter technology selection justification.
State transmission utilities are consolidating procurement authority previously dispersed across central PSUs and private developers. Bulk project packaging under Green Energy Corridors is compressing vendor qualification cycles. This concentration is most visible in Gujarat, where GUVNL now coordinates converter station tenders with associated transmission line awards.
India HVDC Transmission Systems Market Segmentation
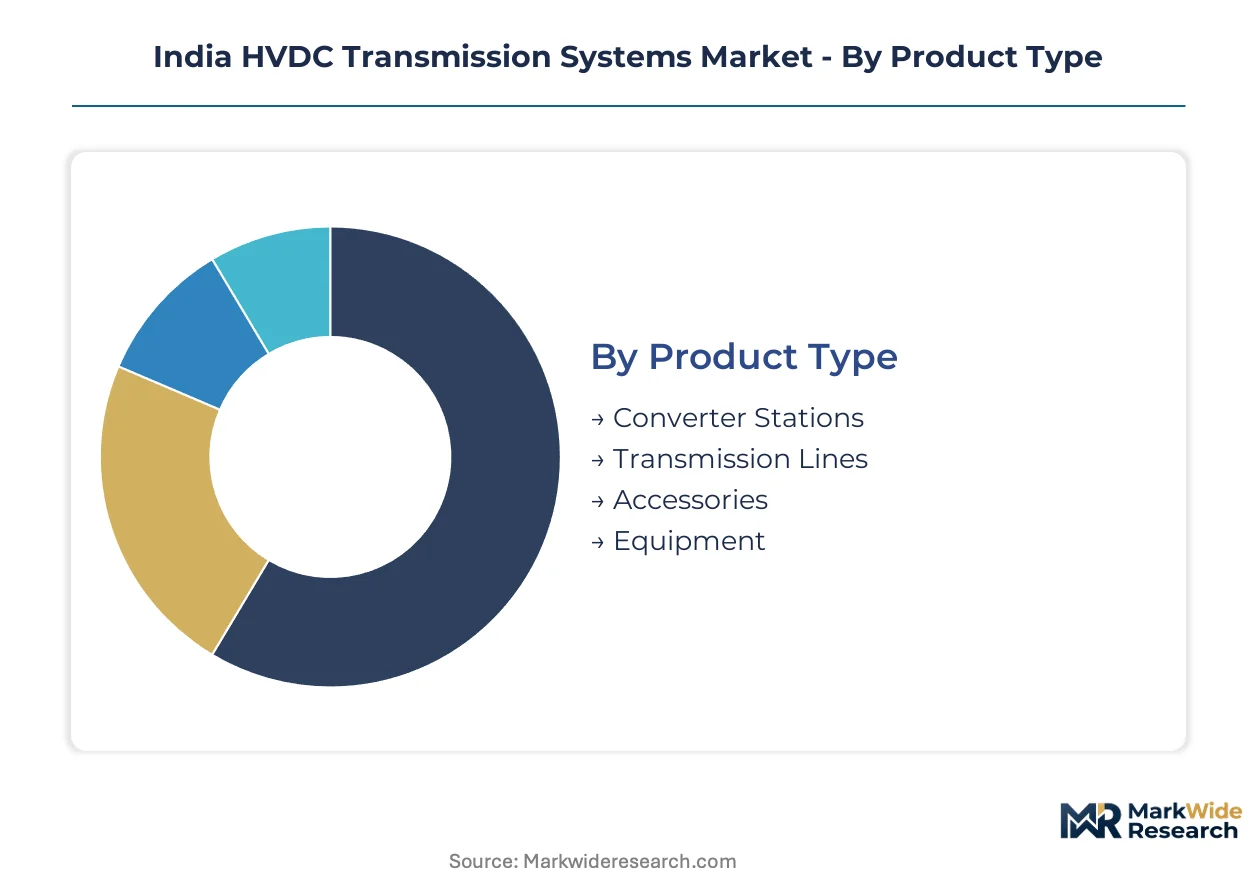
Capital allocation across India's HVDC transmission value chain concentrates heavily in power electronics infrastructure, while technology selection determines project feasibility in weak-grid renewable zones. Understanding segment boundaries clarifies where procurement authority resides and which equipment categories face supply bottlenecks.
Product Type:
Converter stations command disproportionate upfront investment due to thyristor and IGBT valve hall complexity, while transmission lines dominate physical footprint requirements.
- Converter Stations:Thyristor and IGBT valve halls, converter transformers, and control systems constitute the capital-intensive core of bipole HVDC projects. Rajasthan and Gujarat state transmission utilities concentrate procurement here under Green Energy Corridors mandates, with BIS certification timelines creating extended approval cycles for grid-connected equipment.
- Transmission Lines:Overhead and underground conductors spanning hundreds of kilometers form the largest physical infrastructure element. Long-distance bulk power evacuation from renewable-rich zones in Kutch and Barmer drives demand for 800 kV bipole-rated corridors with minimal right-of-way constraints.
- Accessories:Insulators, surge arresters, and hardware assemblies complete the physical transmission infrastructure.
- Equipment:Auxiliary systems including cooling plants, fire suppression, and SCADA integration support station operations.
Converter stations absorb the bulk of installed capacity; transmission lines are expanding most quickly as western renewable evacuation corridors multiply.
Technology:
Architecture selection determines black-start capability and reactive power control flexibility, with voltage source systems displacing legacy line-commutated alternatives in new projects.
- Voltage Source Converter:Modular multilevel converter architectures enable independent reactive power control and weak-grid connection without synchronous compensation. Gujarat coastal zones and Tamil Nadu offshore wind projects favor this technology for its grid-forming capabilities in absence of strong AC networks.
- Current Source Converter:Line-commutated thyristor-based systems retain cost advantages in ultra-high power point-to-point links with strong AC terminals at both ends. Existing multi-terminal networks anchored by Power Grid Corporation continue expanding with this mature technology.
- Monopole:Single-pole configurations with ground return suit lower-capacity interconnections and preliminary feasibility studies.
- Bipole:Dual-pole symmetrical systems provide redundancy and double the power transfer capacity of monopole alternatives.
Voltage source converter systems gain share fastest in new awards; current source converter installations retain the largest cumulative installed base.
End User:
Procurement authority has shifted from central public sector undertakings toward state-level buyers with concentrated renewable evacuation mandates.
- Utilities:State transmission utilities in Gujarat, Rajasthan, and Maharashtra now dominate bulk project awards under Green Energy Corridors, consolidating buyer power previously fragmented across central PSUs. GUVNL coordinates converter station tenders with associated transmission line awards, compressing vendor qualification cycles.
- Renewable Energy Farms:Solar and wind developers in Kutch, Barmer, and Jaisalmer require dedicated HVDC feeder infrastructure for multi-gigawatt cluster evacuation. Green hydrogen hub electrification plans will expand this segment's procurement relevance.
- Industrial Sector:Aluminum smelters and steel plants seek reliable bulk power delivery for energy-intensive processes.
- Large Enterprises:Data centers and manufacturing campuses evaluate captive HVDC connections for power quality assurance.
Utilities absorb the bulk of installed capacity; renewable energy farms are climbing the fastest as green hydrogen and offshore wind projects advance.
Application:
Inter-regional transfer mandates above 5,000 MW trigger HVDC feasibility requirements under Central Electricity Authority planning standards.
- Long-Distance Transmission:Bulk power evacuation exceeding 500 kilometers from western renewable zones to load centers in Maharashtra and Tamil Nadu constitutes the primary deployment driver. Loss comparisons against AC alternatives determine tariff filing approvals.
- Renewable Integration:Weak-grid connection of solar and wind farms demands voltage source converter technology with fault ride-through compliance. CEA's national grid standards shape converter station investments for variable generation absorption.
- Grid Interconnection:Asynchronous linking of regional grids with different frequencies or stability constraints.
- Power Distribution:Urban infeed points requiring compact converter station footprints and minimal electromagnetic interference.
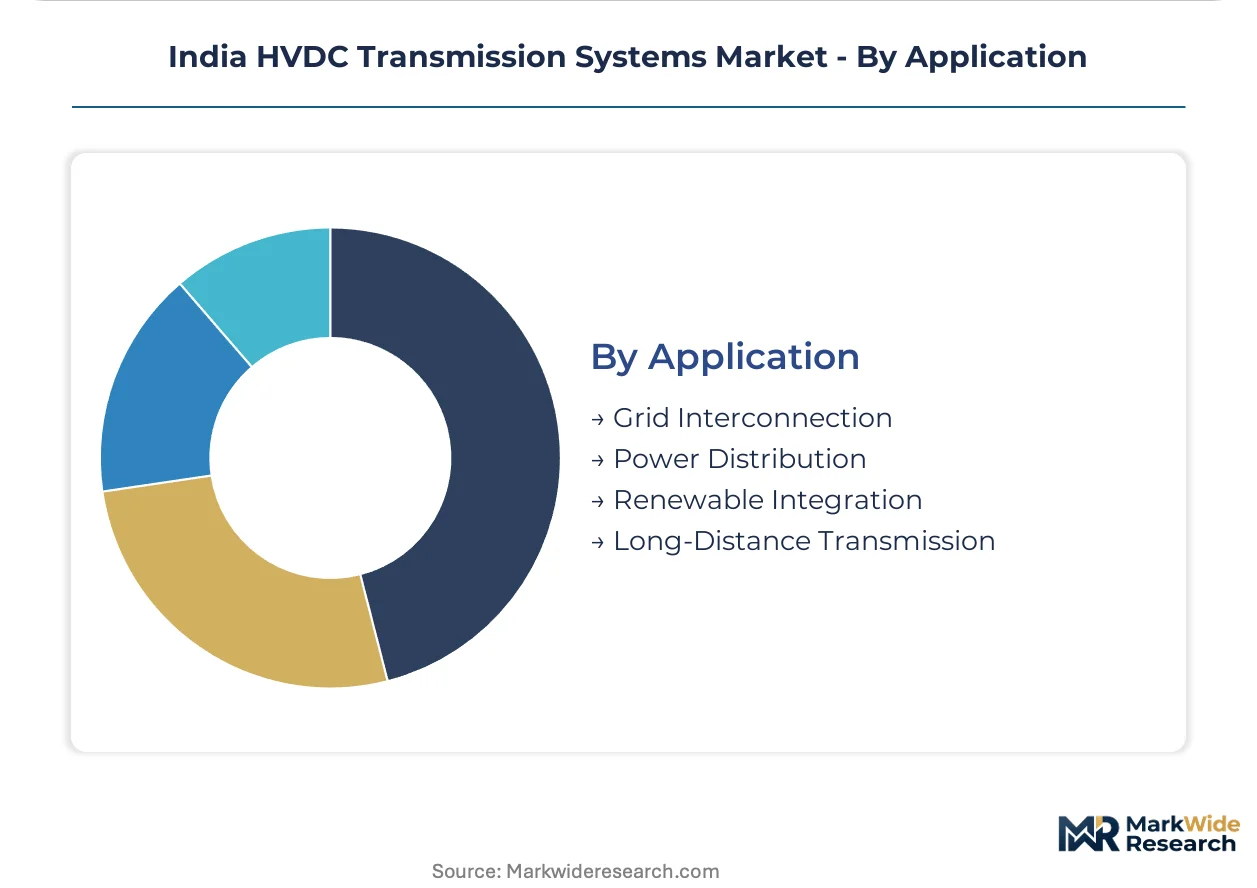
Long-distance transmission absorbs the bulk of installed capacity; renewable integration is gaining share fastest as variable generation penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing clusters in Kerala and Tamil Nadu anchor semiconductor-grade material supply for converter valve manufacturing. Gujarat's Mundra and Hazira ports handle thyristor and IGBT module imports. Rajasthan's Jaisalmer-Jodhpur belt hosts converter transformer winding facilities serving western renewable corridors.
Gujarat
GUVNL coordinates bipole converter station tenders with 800 kV transmission line awards under Green Energy Corridors. CEA mandates require HVDC feasibility for inter-regional transfers exceeding 5,000 MW. Kutch district hosts multi-gigawatt solar clusters demanding voltage source converter infrastructure for weak-grid connection.
Rajasthan
Barmer and Jaisalmer renewable zones drive concentrated demand for long-distance bulk power evacuation infrastructure. BIS certification timelines extend approval cycles for converter transformers and reactors. Jodhpur-Pali industrial corridor houses electrode station fabrication yards serving western HVDC backbone projects.
Maharashtra
MSETCL procurement authority consolidates under state transmission utility concentration trends. CEA national grid standards shape converter station investments for variable generation absorption. Nagpur and Aurangabad industrial zones manufacture cooling plant auxiliary systems for bipole stations.
Tamil Nadu
Offshore wind lease blocks in Gulf of Mannar and Palk Strait create demand for subsea cable-connected voltage source converter stations. Tamil Nadu Generation and Distribution Corporation evaluates black-start capable systems for weak-grid coastal integration. Chennai-Tiruchirappalli manufacturing belt produces surge arrester assemblies for 800 kV-rated corridors.
Karnataka
Karnataka Renewable Energy Development Limited plans dedicated HVDC feeder infrastructure for green hydrogen hub electrification. Ministry of Power electrolyzer cluster roadmaps trigger converter station pre-feasibility studies in Bellary and Raichur districts. Bengaluru electronics corridor supplies control system SCADA integration for western renewable evacuation projects.
India HVDC Transmission Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular multilevel converter specialization and SiC semiconductor integration. The vendor base stratifies across three archetypes: integrated EPC contractors with converter hall execution capabilities, power electronics OEMs with valve technology leadership, and state-owned transmission developers with multi-terminal network ownership. Competitive intensity centers on bipole station tender packaging and BIS certification acceleration rather than pure price competition.
Within the integrated EPC tier, Tata Projects Limited and Larsen & Toubro Limited represent execution-focused archetypes spanning converter halls, electrode stations, and transmission corridors. Siemens AG anchors the power electronics OEM segment with voltage source converter technology positioning for western renewable zone contracts. Power Grid Corporation of India Limited exemplifies the state-owned network developer archetype through its ownership of national multi-terminal HVDC infrastructure.
| Leading Market Players |
|---|
| Hitachi Energy Ltd |
| Siemens AG |
| General Electric Company |
| Power Grid Corporation of India Limited |
| Bharat Heavy Electricals Limited |
| Adani Transmission Ltd |
| Tata Projects Limited |
| Larsen & Toubro Limited |
| Prysmian Group |
| Others |
Supply & Pricing Matrix
State transmission utility procurement concentration under Green Energy Corridors mandates is forcing converter station OEMs to absorb extended BIS certification costs and currency volatility from semiconductor imports, compressing margins on bipole valve hall packages while elevating total project pricing for developers.
Pricing Analysis
Warranty and commissioning service bundling now separates Power Grid Corporation's multi-terminal network awards from state utility tenders, where unbundled maintenance contracts predominate. Project-based lump-sum pricing dominates converter station awards, with differentiation driven by BIS certification tier and black-start capability inclusion. Cost compression in thyristor valve halls is intensifying because of silicon carbide module substitution timelines. State utilities in Gujarat and Rajasthan exhibit highest price sensitivity due to Green Energy Corridor budget caps, while national backbone projects show lowest sensitivity.
Supply Chain Analysis
Refurbishment flows for converter transformers and thyristor valve assemblies concentrate in Rajasthan's Jodhpur-Pali industrial corridor, creating secondary supply for electrode station components. Manufacturing draws from Germany, Switzerland, and Japan for semiconductor-grade thyristor and IGBT modules, with converter transformer cores resting on electrical steel from South Korea and Japan. Single-source vulnerability pervades 800 kV-rated valve hall equipment. Distribution runs through Mundra and Hazira port clusters for western renewable zone projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India HVDC market sits in a technology-transition phase as voltage source converter architectures displace line-commutated current source systems across renewable evacuation corridors.
For Market Incumbents: To counter modular multilevel converter specialist entrants, Siemens AG and Hitachi Energy Ltd must accelerate silicon carbide submodule qualification for 800 kV bipole ratings while securing backward integration into converter transformer winding capacity in Rajasthan's Jaisalmer-Jodhpur belt.
For New Entrants and Emerging Players: Enter via Tamil Nadu offshore wind lease blocks where voltage source converter demand for weak-grid coastal integration remains underpenetrated by established bipole station vendors, targeting black-start capable subsea cable systems as the go-to-market anchor.
For Investors and Strategic Acquirers: The window for entry favors integrated EPC contractors with converter hall execution capabilities and BIS certification acceleration track records, with long-term viability hinging on green hydrogen hub electrification pipeline visibility; watch Ministry of Power electrolyzer cluster roadmap announcements as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Valve Hall Qualification | Reduces filter bank size and station land requirements for CEA-mandated 800 kV bipole projects. |
| Converter Transformer Backward Integration | Secures BIS-certified winding capacity in Rajasthan against import dependency and currency volatility. |
| Offshore Wind Voltage Source Converter Deployment | Captures Tamil Nadu coastal demand for grid-forming black-start capability without synchronous compensation. |
| Green Energy Corridor EPC Packaging | Aligns converter station tenders with transmission line awards under GUVNL coordination mandates. |
| Multi-Terminal Network Retrofit Positioning | Enables meshed HVDC topology expansion beyond point-to-point links under CEA national grid standards. |
Research Methodology
Document review covered Central Electricity Authority transmission planning mandates, Ministry of Power green hydrogen hub roadmaps, and BIS certification records for grid-connected equipment, complemented by interviews with state utility planning officers, EPC contractor project directors, converter station OEM technical leads, and semiconductor import logistics specialists. Secondary validation drew from Power Grid Corporation annual reports, customs trade data for thyristor and IGBT modules, and FERC-equivalent regulatory filings. Bottom-up project pipeline assessment triangulated against top-down national grid expansion targets.
Historical deployment patterns for bipole converter stations were cross-referenced against expert panel input on voltage source converter adoption timelines across the projection horizon. Segmentation modeling covered product type, technology architecture, end-user procurement authority, and application purpose. CAGRs were derived from capacity-weighted project award trajectories, incorporating Green Energy Corridor budget allocation schedules and renewable purchase obligation enforcement intensity as industry-specific forecast inputs.
Revisions become necessary when BIS certification timelines extend beyond baseline assumptions, silicon carbide module supply disruptions materialize, or Green Energy Corridor funding reallocations shift bipole station deployment schedules. Material deviation in these named triggers warrants pause and re-evaluation of converter station investment and transmission line infrastructure forecasts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Tower Market