
 Submarine Electricity Transmission Systems Market | 2026-2036
Submarine Electricity Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Electricity Transmission Systems Market Analytics
Submarine cable procurement channels is fragmenting as national grid operators diversify supplier rosters beyond traditional incumbents. Prysmian SpA leverages its integrated manufacturing footprint across Mediterranean and Baltic plants to sustain delivery timelines for bundled HVDC projects. Nexans SA anchors its position through specialized XLPE insulation R&D centers in Norway. NKT A/S competes by dominating the high-voltage offshore installation vessel segment with purpose-built cable-laying fleets.
Submarine electricity transmission systems encompass high-voltage direct current and alternating current cables engineered with cross-linked polyethylene insulation and armored steel wire sheathing, designed to transmit bulk power across seabed corridors exceeding 500 kilometers. These systems serve intercontinental grid interconnection, offshore renewable integration, and island power supply functions. HVDC technology leads capital deployment due to lower losses over extended distances, while optical fiber composite cables represent the fastest-growing structural segment as grid operators embed monitoring telemetry within power conductors. Application demand clusters around renewable energy, where offshore wind farms drive repeat procurement cycles for array and export cables.
EU Green Deal implementation through the European Commission shapes cable environmental compliance and circular material mandates, while IEC 62288 and CIGRE technical brochures define testing protocols for long-duration subsea reliability. Germany's Bundesnetzagentur and Denmark's Energinet enforce grid code harmonization that dictates cable electrical parameters for North Sea interconnectors. Stakeholders must monitor regulatory divergence between EU decarbonization timelines and national permitting processes that govern seabed rights-of-way.
Market Dynamics
Mass-procurement cycles for offshore wind export cables are compressing supplier lead times and forcing manufacturing capacity allocation decisions across Mediterranean and Baltic production corridors.
Growth Catalysts
- EU Green Deal offshore targets:Binding renewable energy mandates in Germany, Denmark, and the Netherlands are accelerating HVDC interconnector procurement timelines.
- Cross-linked polyethylene insulation:Advances in XLPE manufacturing are extending cable operational lifespans beyond 40 years for subsea installations.
- North Sea corridor concentration:Grid interconnection between continental Europe and British-Scandinavian networks is generating repeat cable-laying contracts.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings compress cable manufacturer margins and complicate long-term project bidding.
- Specialized vessel scarcity:Purpose-built cable-laying fleet availability concentrates with three European operators, creating installation bottlenecks.
- Seabed rights-of-way permitting:Denmark's Energinet and Germany's Bundesnetzagentur impose overlapping environmental review timelines that extend project development cycles.
Strategic Opportunities
- Baltic Sea expansion corridor:Poland and Estonia are issuing preliminary seabed leases for offshore wind zones lacking transmission infrastructure.
- Optical fiber composite integration:Embedding distributed temperature sensing within power conductors enables real-time cable health monitoring for grid operators.
- EU circular material mandates:The European Commission's end-of-life cable recovery requirements are creating secondary material processing partnerships.
Industry Challenges
- Submarine cable jointing technician shortage:Specialized HVDC splice certification programs in Norway and Germany graduate fewer technicians than project pipelines require.
- IEC 62288 testing duration:Long-duration subsea reliability protocols extend product qualification timelines, delaying revenue recognition for new cable designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Electricity Transmission Systems Market |
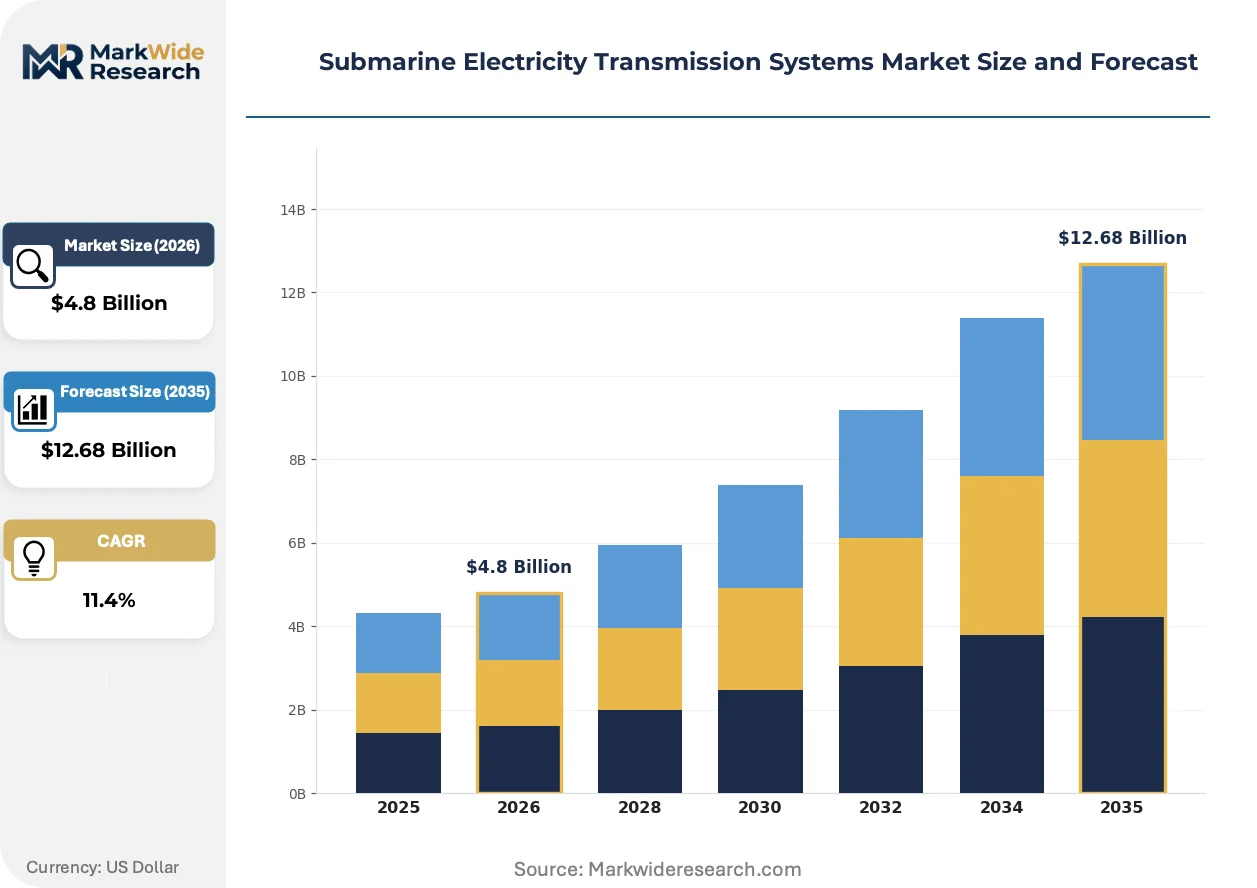
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: HVDC, HVAC, Optical Fiber, Subsea Cables Application: Renewable Energy, Oil & Gas, Interconnection, Military End User: Utility Companies, Offshore Wind Farms, Marine Operators, Industrial Plants Installation Type: Onshore, Offshore, Hybrid, Temporary |
| Companies Covered | Prysmian SpA, Nexans SA, NKT A/S, ABB Ltd, Siemens AG, Sumitomo Electric Industries Ltd, Alcatel Submarine Networks, SubCom LLC, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Electricity Transmission Systems Market Evolving Landscape
Active developments across materials science, regulatory compliance frameworks, and buyer procurement architectures are compressing traditional cable industry operating rhythms.
Mass-impregnated paper-insulated cables, once standard for high-voltage subsea transmission, are rendering obsolete across North Sea offshore wind applications as extruded XLPE systems demonstrate superior thermal performance at 320 kV and above. German and Danish transmission system operators now specify XLPE exclusively for new export cable tenders. This transition is compressing the remaining installed base of legacy paper-insulated links into early replacement cycles.
REACH chemical substance restrictions are forcing reformulation of cable sheathing compounds and anti-corrosion coatings used in armored subsea designs. Manufacturers operating EU-based plants must certify alternative material compositions without compromising mechanical protection ratings. The offshore wind cable segment bears the highest compliance burden, as these projects face dual scrutiny under marine environment directives and electrical safety frameworks.
Transmission system operators are consolidating cable procurement into multi-year framework agreements with embedded volume commitments, displacing project-by-project competitive tendering. This shift concentrates purchasing power with national grid entities in Germany, the Netherlands, and the United Kingdom. Danish Energinet pioneered this model, with British and German operators now replicating the structure for North Sea interconnector programs.
Submarine Electricity Transmission Systems Market Segmentation
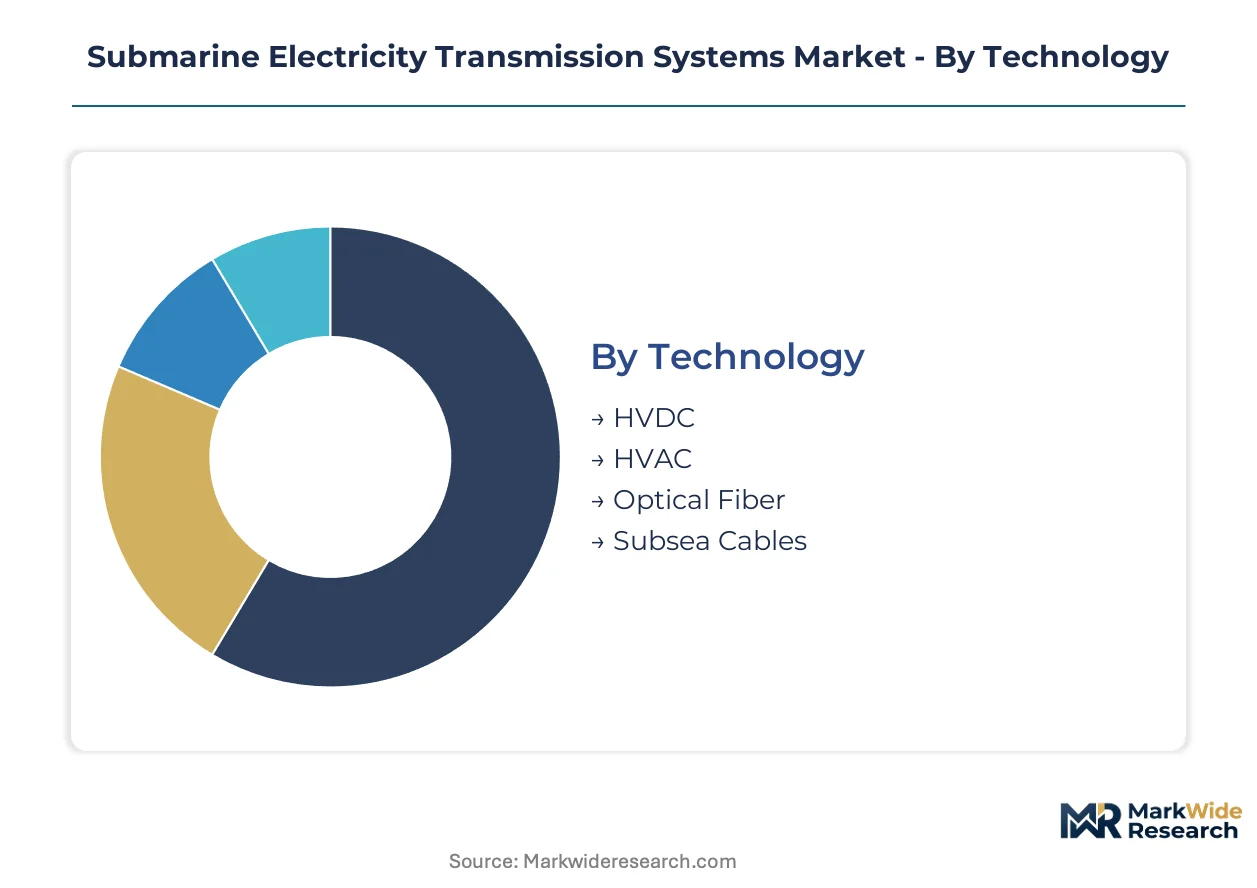
Submarine electricity transmission systems fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct procurement patterns, regulatory exposures, and margin structures that shape supplier strategy and buyer negotiation leverage.
Technology:
Mature extruded insulation systems dominate North Sea procurement, while emerging composite architectures are displacing legacy designs in new project specifications.
- HVDC:High-voltage direct current systems employ extruded cross-linked polyethylene insulation rated for 320 kV and above, with mass-impregnated paper designs now obsolete for new North Sea offshore wind export cables. German and Danish transmission system operators specify HVDC exclusively for interconnector projects exceeding 500 kilometers, where lower electrical losses justify capital premiums.
- HVAC:Alternating current cables with XLPE insulation serve shorter seabed corridors under 80 kilometers, where converter station economics disadvantage HVDC. Array cables connecting offshore wind turbines to substations concentrate HVAC demand in the Dogger Bank and Baltic Sea zones.
- Optical Fiber:Composite power conductors embed distributed temperature sensing fibers for real-time thermal monitoring. Grid operators in the Netherlands and United Kingdom now mandate fiber integration for new interconnector tenders.
- Subsea Cables:Armored steel wire sheathing protects conductors against seabed abrasion and fishing gear impact. Installation contractors specify double-armor designs for rocky Baltic Sea corridors.
HVDC handles the majority of throughput; Optical Fiber is the fastest mover on share.
Application:
Volume concentrates in renewable integration, while interconnection projects command the highest unit values per kilometer.
- Renewable Energy:Offshore wind farms drive repeat procurement cycles for array cables and export links. The North Sea corridor connecting Germany, Denmark, and the Netherlands generates bundled tender packages for 66 kV array and 220 kV export systems.
- Interconnection:Cross-border grid links between continental Europe and British-Scandinavian networks require 400-500 kV HVDC systems with submarine lengths exceeding 700 kilometers. EU Green Deal targets accelerate procurement timelines for these projects.
- Oil & Gas:Platform power supply cables operate at medium voltage with specialized hydrocarbon-resistant sheathing. North Sea decommissioning is compressing replacement demand in this segment.
- Military:Naval base and coastal defense installations require electromagnetic shielding and armored protection against seabed threats. Procurement runs through national defense ministries with classified specifications.
Renewable Energy commands the largest installed base; Interconnection is expanding most quickly on project value.
End User:
Procurement authority clusters with national grid entities, while offshore wind developers are consolidating into multi-year framework agreements.
- Utility Companies:Transmission system operators in Germany, the Netherlands, and the United Kingdom consolidate purchasing through multi-year framework agreements with embedded volume commitments, displacing project-by-project tendering.
- Offshore Wind Farms:Developers in the North Sea and Baltic Sea lease zones procure bundled cable packages covering turbine array connections and export links. Polish and Estonian seabed leases are creating new demand clusters lacking existing transmission infrastructure.
- Marine Operators:Port authorities and coastal infrastructure managers specify medium-voltage shore connection systems for vessel electrification.
- Industrial Plants:Island industrial facilities and coastal manufacturing sites procure dedicated submarine supply links where grid extension is uneconomical.
Utility Companies dominate procurement volume; Offshore Wind Farms are gaining share fastest on project pipeline expansion.
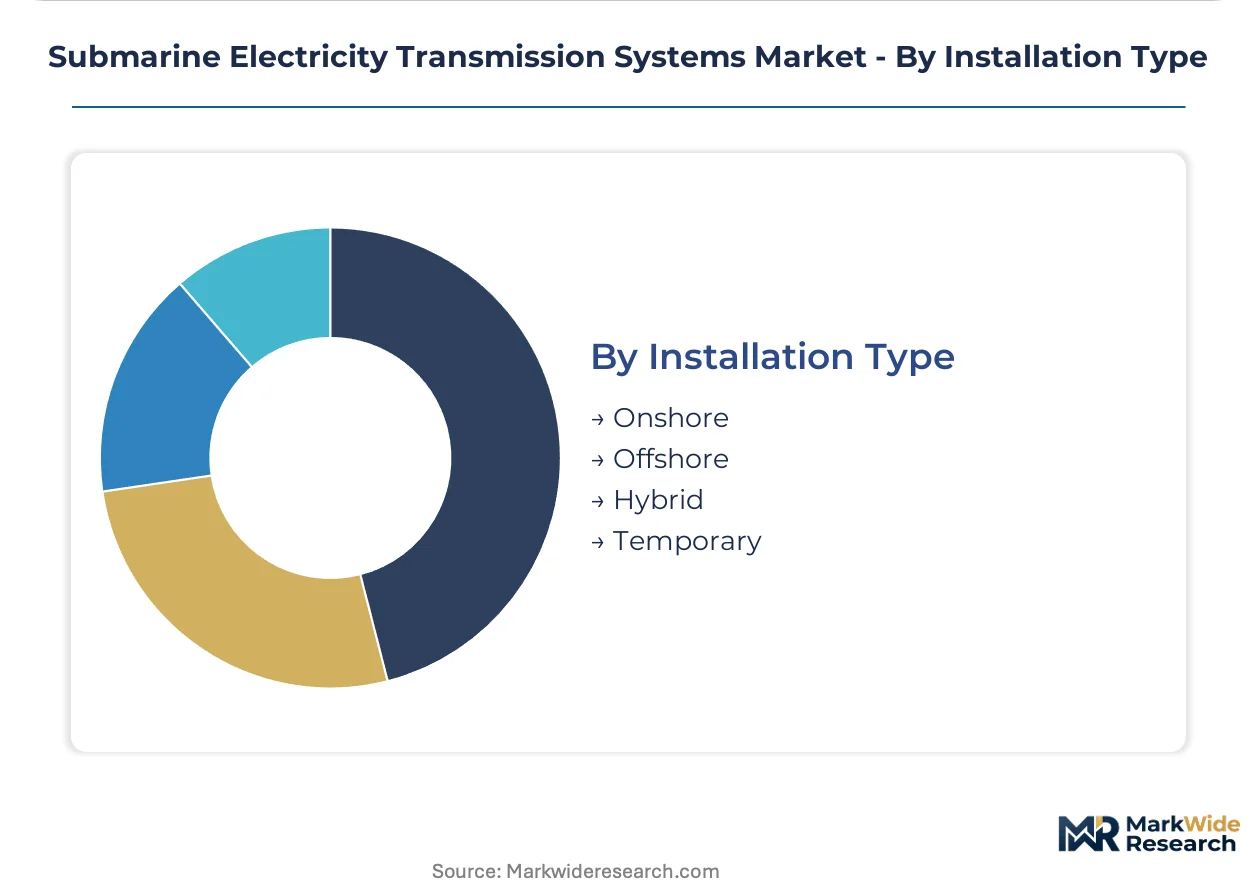
Installation Type:
Offshore deployment commands specialized vessel resources, while hybrid configurations are emerging for complex seabed topography.
- Offshore:Submarine cable-laying requires purpose-built vessels with dynamic positioning and tension-controlled payout systems. European fleet availability concentrates with three operators, creating installation bottlenecks for peak demand periods.
- Onshore:Land-based transition stations and cable termination facilities require civil engineering coordination with seabed rights-of-way permits.
- Hybrid:Combined offshore-onshore routing navigates complex coastal topography and protected marine zones. Denmark's Energinet employs hybrid designs for interconnectors crossing the Kattegat.
- Temporary:Festival power supply and emergency grid restoration deploy removable submarine links with reduced armor specifications.
Offshore absorbs the dominant share of specialized vessel capacity; Hybrid configurations are climbing the fastest on project complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea HVDC interconnector corridor underwrites Germany's commanding position in submarine electricity transmission procurement. German grid operators TenneT and 50Hertz anchor continental European demand for high-capacity subsea links.
Germany
Offshore wind lease rounds in the North Sea and Baltic Sea are accelerating bundled cable procurement for 66 kV array and 220 kV export systems. Bundesnetzagentur enforces grid code harmonization that dictates electrical parameters for interconnectors. Cable manufacturing clusters in Lower Saxony and North Rhine-Westphalia are expanding extrusion capacity for XLPE-insulated HVDC conductors.
United Kingdom
National Grid ESO is consolidating interconnector procurement through multi-year framework agreements with embedded volume commitments. Ofgem regulates revenue caps for subsea transmission assets under the RIIO price control framework. Scottish and Southern Electricity Networks anchors demand in the North of Scotland, where offshore wind zones require dedicated export cable infrastructure.
Denmark
Energinet pioneered framework agreement procurement models now replicated across Northern Europe. Danish Energy Agency seabed leasing for the Kriegers Flak and Thor wind zones is compressing cable-laying schedules. Copenhagen anchors technical specification development, with Energinet's laboratory facilities certifying XLPE insulation systems for 320 kV operation.
Netherlands
TenneT Netherlands is procuring HVDC links to connect 21 GW of offshore wind capacity by 2030. Rijksdienst voor Ondernemend Nederland coordinates seabed rights-of-way with marine spatial planning directives. Rotterdam and Eemshaven port clusters are expanding cable storage and load-out facilities for North Sea installation campaigns.
Norway
Statnett is advancing the North Sea Link and other interconnectors to export hydroelectric surplus. Norwegian Water Resources and Energy Directorate regulates subsea cable routing through fjord systems and fishing grounds. Nexans operates specialized R&D centers near Oslo, anchoring XLPE insulation technology development for Arctic-rated installations.
Submarine Electricity Transmission Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying insulation compounds, armored sheathing, and optical fiber elements. The vendor base concentrates around integrated cable manufacturers with captive vessel fleets and extrusion facilities. Three strategic archetypes dominate: Mediterranean-Baltic manufacturers with bundled HVDC capabilities, Nordic specialists in high-voltage R&D, and diversified industrial conglomerates with power electronics integration. Competitive moves center on manufacturing capacity allocation across production corridors and strategic partnerships for installation vessel access.
Among European cable specialists, Prysmian SpA, Nexans SA, and NKT A/S occupy positions within the integrated manufacturing tier. Prysmian exemplifies the Mediterranean-Baltic production archetype with facilities spanning multiple coastal corridors. Nexans represents Nordic specialization in materials science and subsea reliability testing. NKT A/S anchors Danish-German manufacturing integration with purpose-built installation assets. These three entities collectively illustrate how geographic production distribution and captive vessel access define competitive positioning in submarine electricity transmission systems.
| Leading Market Players |
|---|
| Prysmian SpA |
| Nexans SA |
| NKT A/S |
| ABB Ltd |
| Siemens AG |
| Sumitomo Electric Industries Ltd |
| Alcatel Submarine Networks |
| SubCom LLC |
| Hitachi Energy |
| Others |
Value Network & Pricing Analysis
Lower Saxony's cable manufacturing corridor is expanding XLPE extrusion capacity faster than installation vessel fleets can absorb output, compressing margins for HVDC conductor producers while amplifying pricing power for specialized cable-laying operators. This geographic asymmetry between production scale and deployment capability is reshaping contract negotiation leverage across North Sea procurement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 62288-certified HVDC systems from regional grid-code compliant HVAC links and non-certified legacy inventory. Price differentiation hinges on XLPE insulation voltage rating and bundled optical fiber integration. Cost compression in standard-tier export cables is intensifying because copper and aluminum input volatility complicates long-term project bidding. Offshore wind developers exhibit the highest price sensitivity, while national transmission system operators prioritize technical compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates raw material sourcing risk for armored steel wire sheathing compounds. Manufacturing concentrates in Germany, Italy, and Denmark, with Norway anchoring specialized R&D inputs. The supply chain draws from Chilean copper cathode, Chinese aluminum billet, and Saudi petrochemical feedstock for XLPE compounding. Single-source vulnerability concentrates in purpose-built cable-laying vessel availability. Distribution runs through national grid operator framework agreements with embedded volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Submarine electricity transmission systems are entering a cyclical upswing driven by EU Green Deal offshore wind procurement waves. Capital deployment timing favors positioning ahead of Baltic Sea lease round accelerations.
For Market Incumbents: Harden manufacturing capacity allocation discipline across Mediterranean and Baltic production corridors to defend against emerging Asian cable specialists bidding below cost on North Sea tenders. Prioritize captive installation vessel access through long-term charter agreements with European fleet operators. For New Entrants and Emerging Players: Pursue Polish and Estonian offshore wind zones lacking established transmission infrastructure, where seabed lease awards precede bundled cable procurement by 18-24 months. Target 66 kV array cable segments with lower certification barriers than HVDC interconnector tiers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among installation vessel operators with multi-year framework agreement backlogs from German and Dutch grid entities. Five-to-ten-year viability favors integrated manufacturers with backward control over XLPE compounding. Monitor Baltic Sea seabed lease auction velocity as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Lower Saxony extrusion facilities are adding 320 kV XLPE lines to capture German offshore wind demand. |
| Backward Integration | Captive copper rod casting reduces exposure to London Metal Exchange price volatility for cable producers. |
| Long-term Supply Agreement | Energinet's framework agreements with embedded volume commitments now anchor Danish procurement architecture. |
| Joint Venture | Polish offshore wind developers are partnering with Nordic cable specialists to secure Baltic Sea installation capacity. |
| Green Certification Program | REACH-compliant sheathing compounds satisfy EU circular material mandates for North Sea marine environments. |
Research Methodology
A standing panel of transmission system operator procurement directors, cable manufacturing plant managers, offshore installation vessel operators, and Bundesnetzagentur regulatory affairs specialists provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including Energinet tender documentation, Bundesnetzagentur grid code filings, CIGRE technical brochures, and EU Green Deal implementation progress reports. Bottom-up project pipeline enumeration was triangulated with top-down macroeconomic scenario modeling.
Scenario-bracketing framed low-base-high projections across the analysis window, with segmentation dimensions spanning HVDC versus HVAC technology, renewable energy versus interconnection application, and offshore versus hybrid installation type. CAGRs were derived from fitted growth curves anchored to named project award timelines. Forecast inputs incorporated seabed lease issuance velocity, vessel fleet utilization rates, and XLPE insulation qualification duration under IEC 62288 protocols.
Sensitivities concentrate around EU offshore wind target revisions, copper price volatility, and cable-laying vessel availability constraints. Forecasts reflect documented assumptions regarding regulatory harmonization and permitting timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Surge Tank Market