
 HVDC Transmission Systems Market | 2026-2036
HVDC Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Transmission Systems Market Outlook
IEC 61803 qualification for high-voltage direct-current converter valves is bifurcating the supplier landscape into certified incumbents and excluded aspirants. Siemens Energy leverages its in-house semiconductor fabrication to sustain margin control on insulated-gate bipolar transistor modules. Hitachi Energy anchors European offshore wind interconnections through specialized VSC converter platforms. Prysmian Group competes on cable-laying vessel availability and deep-water installation track record.
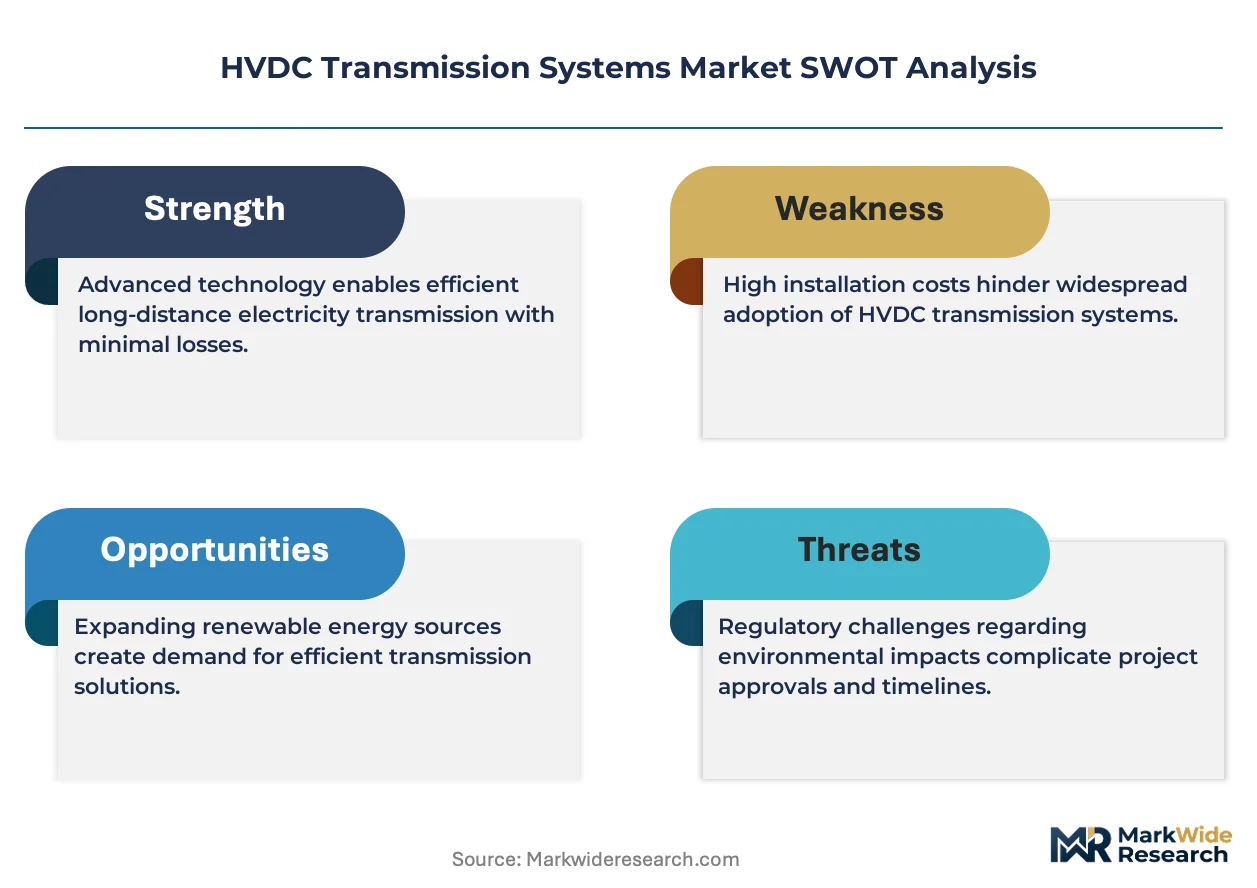
High-voltage direct-current transmission systems move bulk electrical power across long distances or submarine routes using converter stations to alternate between AC and DC, with typical operating voltages from 150 kV to 800 kV and power ratings exceeding 1,000 MW per bipole link. Their primary purpose is to stabilize asynchronous grids, integrate remote renewable generation, and eliminate reactive power losses inherent in AC cables. VSC technology leads new project awards due to superior black-start capability and compact converter station footprints, while LCC retains cost advantages on ultra-long overhead corridors above 2,000 km. Submarine installations command premium pricing and extended lead times, concentrating margin pools with cable specialists who control vessel fleets and polymer compound formulations.
EU F-Gas Regulation and REACH compliance constrain insulating medium selection for gas-insulated switchgear and converter station components, pushing manufacturers toward fluoronitrile blends or vacuum interrupters. The US FERC Order 2023 on interconnection queue reform accelerates HVDC project permitting timelines for cross-regional transmission. China's GB/T 30553 standard for ultra-high-voltage DC equipment shapes export qualification requirements for foreign suppliers. Stakeholders must monitor converter semiconductor supply constraints and evolving national content rules before committing to multi-billion-dollar project timelines.
Market Dynamics
Converter semiconductor supply concentration and vessel fleet scarcity are compressing project timelines and redistributing margin pools toward integrated cable-converter suppliers who control both converter station assembly and submarine installation assets.
Growth Catalysts
- EU Green Deal interconnection mandates:Binding renewable integration targets are accelerating cross-border corridor awards and standardizing procurement specifications across German, Dutch, and Danish grid operators.
- Offshore wind cluster development:North Sea lease rounds are generating bundled HVDC export cable demand that favors turnkey suppliers with combined converter and submarine capabilities.
- VSC black-start functionality:Voltage source converter technology is displacing line-commutated alternatives in islanded grid applications and weak-grid connections where reactive power support is constrained.
Market Restraints
- Submarine cable lead times:Polymer compound formulation and vessel charter availability extend delivery schedules to 36-48 months, freezing out developers with compressed offtake deadlines.
- IGBT module supply concentration:Converter valve manufacturing depends on a concentrated semiconductor fabrication base, exposing project economics to foundry allocation decisions.
- F-Gas Regulation compliance costs:EU restrictions on sulfur hexafluoride insulating medium are forcing gas-insulated switchgear redesigns and qualification retesting before corridor commissioning.
Strategic Opportunities
- Mediterranean offshore wind:Italian and Greek lease developments lack established HVDC supply chains, creating first-mover advantages for cable-laying specialists with vessel repositioning flexibility.
- Multi-terminal VSC networks:Meshed DC grid architectures are enabling incremental connection of dispersed generation without full converter station redundancy at each node.
- US FERC interconnection reform:Order 2023 queue processing acceleration is compressing study timelines for cross-regional transmission, favoring developers with pre-qualified converter platforms.
Industry Challenges
- IEC 61803 qualification timelines:Converter valve type-testing protocols extend 18-24 months, delaying supplier entry and concentrating awards among incumbent certified manufacturers.
- Integrated project delivery complexity:Coordination between converter station EPC, cable manufacturing, and marine installation contractors generates interface risk and cost escalation on multi-billion-euro contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Transmission Systems Market |
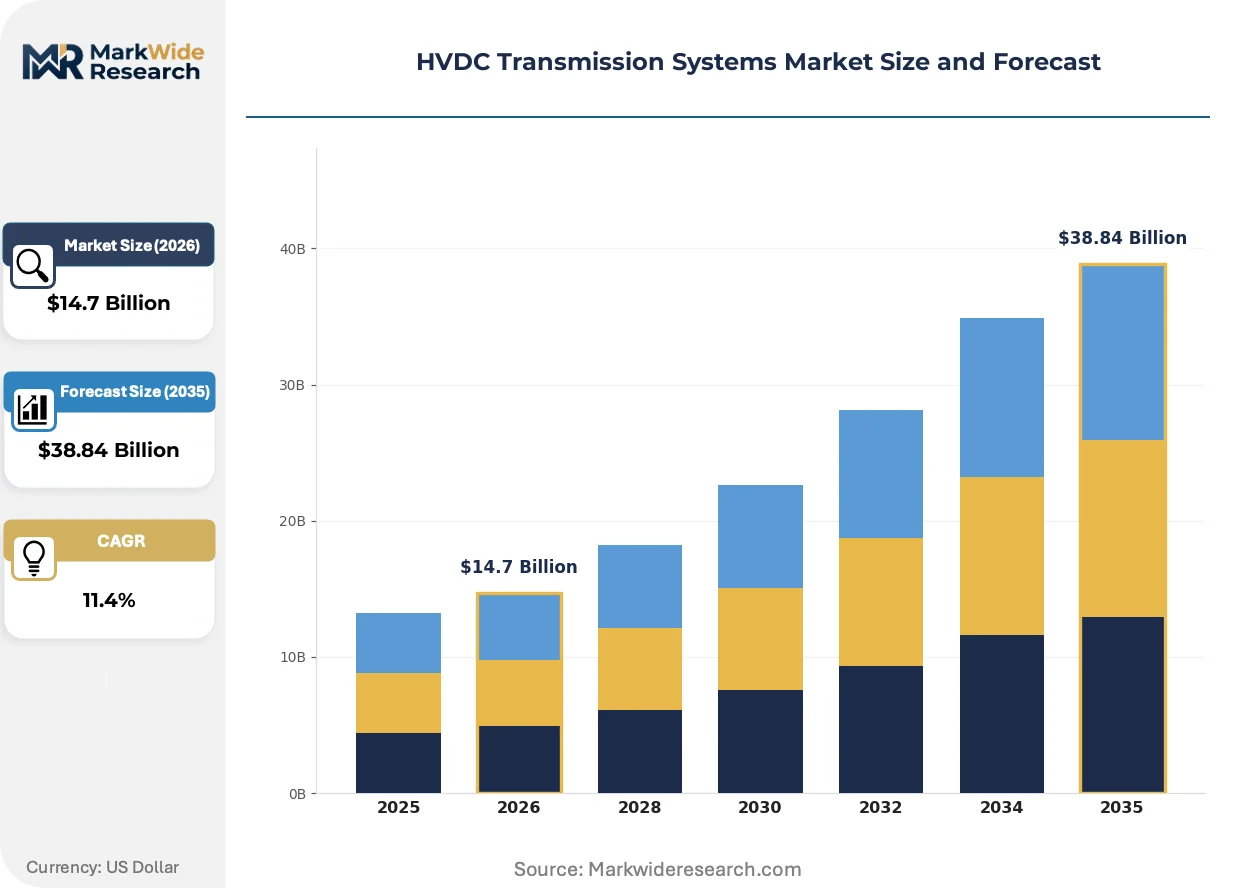
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LCC, VSC, GIL, HVDC Grid Component: Converter Stations, Cables, Transformers, Switchgear End User: Utilities, Renewable Energy Producers, Industrial Users, Independent Power Producers Installation Type: Overhead, Underground, Submarine, Land-Based |
| Companies Covered | ABB Ltd, Prysmian Group, Hitachi Energy, Nexans, NKT A/S, Siemens Energy, Mitsubishi Electric Corporation, Toshiba Corporation, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Transmission Systems Market Strategic Shifts
Modular converter architectures and alternative insulating mediums are restructuring supplier competitive positions, while procurement centralization among offshore wind developers is compressing vendor qualification cycles and bundling awards.
Silicon carbide power semiconductors are decomposing the cost-performance tradeoff that has constrained VSC converter ratings. Offshore wind developers in the North Sea are specifying SiC-based valve stacks for next-generation 2 GW bipole links. The technology is decomposing the historical premium between VSC capital costs and LCC alternatives on long-distance overhead corridors.
EU F-Gas Regulation phase-down schedules are forcing insulating medium transitions in gas-insulated switchgear and converter station components. Manufacturers are reformulating with fluoronitrile blends or redesigning around vacuum interrupters to maintain dielectric performance. German and Dutch grid operators are embedding these specifications into tender documents, disqualifying non-compliant bidders.
Consolidated procurement by offshore wind developers is displacing fragmented utility purchasing patterns. TenneT and 50Hertz are bundling multi-gigawatt corridor awards into framework agreements with single-source converter-cable integrators. This concentration is visible across German North Sea lease areas, where developers prioritize suppliers with proven vessel availability and deep-water installation records over pure component pricing.
HVDC Transmission Systems Market Segmentation
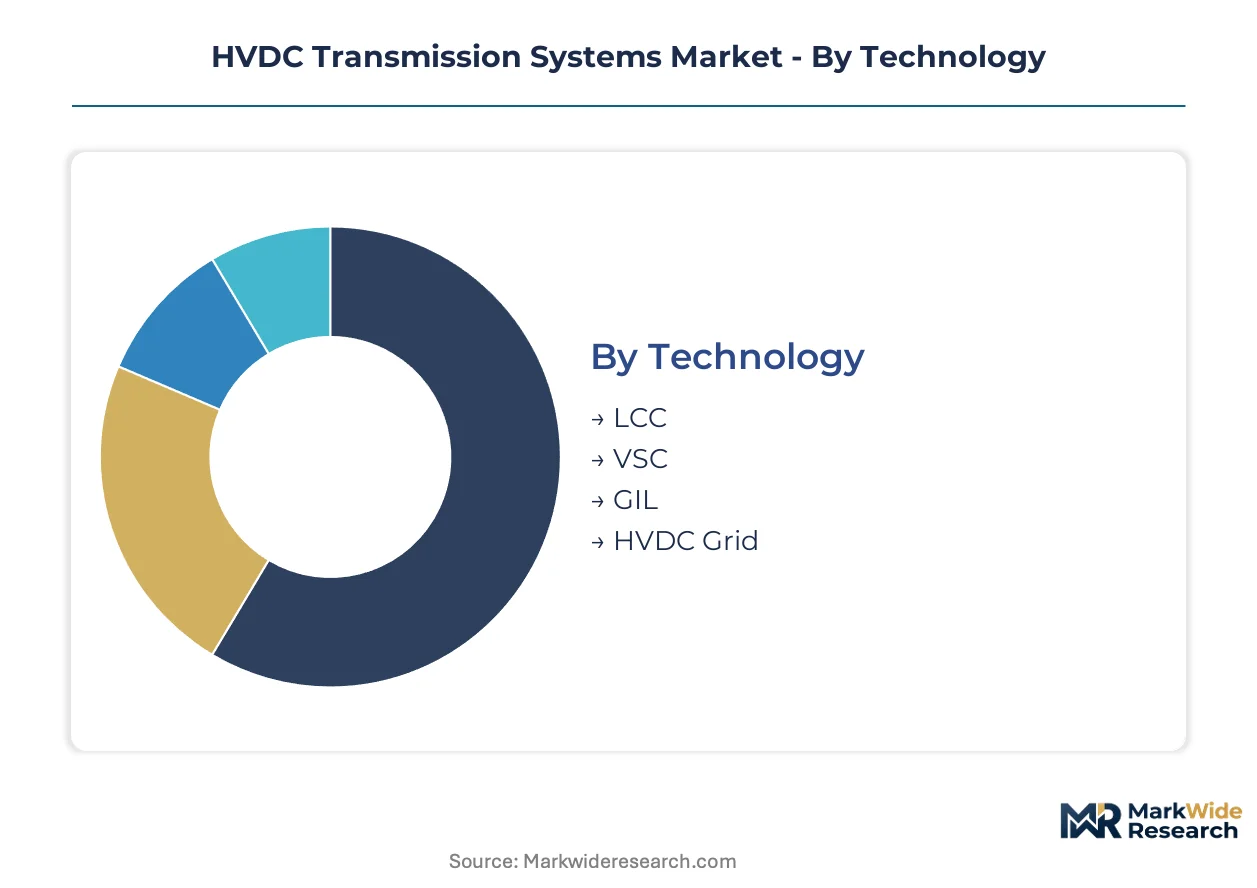
Technology selection, component sourcing, and installation method each impose distinct qualification barriers and margin structures on HVDC project economics. Procurement patterns diverge sharply between domestic grid reinforcement and export-led interconnector developments.
Technology:
Geographic deployment patterns split cleanly between established continental corridors and emerging maritime networks. European and Chinese utilities dominate procurement volumes, with technology choice driven by grid stability requirements and submarine route lengths.
- LCC:Line-commutated converter technology relies on thyristor-based valve stacks with forced commutation from the AC network. Bulk procurement concentrates in China and India for ultra-long overhead corridors exceeding 2,000 km, where capital cost minimization overrides black-start requirements. State Grid Corporation of China specifies LCC for inland UHVDC links to Xinjiang and Tibet generation bases.
- VSC:Voltage source converters deploy insulated-gate bipolar transistor modules with self-commutating capability, enabling independent reactive power control. North Sea offshore wind developers in Germany, the Netherlands, and Denmark specify VSC exclusively for submarine export cables to weak onshore grids, paying premiums for compact converter station footprints and black-start functionality.
- GIL:Gas-insulated lines encase conductors in pressurized sulfur hexafluoride or fluoronitrile mixtures for high-capacity underground routing in dense urban corridors. Tokyo and Seoul metropolitan utilities specify GIL for 500 kV+ substation feeders where right-of-way constraints eliminate overhead options.
- HVDC Grid:Multi-terminal meshed DC architectures enable incremental generation connection without full converter redundancy at each node. Mediterranean offshore wind planning in Italian and Greek waters is driving pilot project specifications for three-terminal VSC networks.
LCC holds the largest share; momentum sits with VSC as offshore wind procurement accelerates.
Component:
Supply chain control varies dramatically by component category, with converter stations and submarine cables commanding the steepest vendor consolidation.
- Converter Stations:Valve halls, AC/DC filters, and control systems constitute 35-45% of project capital expenditure. German and Dutch transmission system operators bundle converter station EPC with cable supply into single-source framework agreements, concentrating awards among integrated suppliers with in-house semiconductor fabrication.
- Cables:Extruded polymer insulated submarine cables for 320 kV+ bipole links require specialized vessel fleets and compound formulation expertise. Prysmian, Nexans, and NKT control European manufacturing capacity, with installation lead times extending 36-48 months for deep-water routes.
- Transformers:Converter transformers with DC bias withstand capability are sourced from Hitachi Energy, Siemens Energy, and Chinese manufacturers. Domestic content requirements in India's Green Energy Corridors program mandate local transformer assembly for awarded projects.
- Switchgear:Gas-insulated switchgear for converter station AC connections faces redesign pressure from EU F-Gas Regulation phase-down schedules. Manufacturers are reformulating with fluoronitrile blends or vacuum interrupters to maintain dielectric performance in German tender specifications.
Converter stations absorb the largest capital share; cables face the steepest supply constraints.
End User:
Procurement centralization distinguishes utility-led corridor development from fragmented industrial offtake patterns.
- Utilities:Transmission system operators in Germany, the UK, and China consolidate multi-gigawatt awards into framework agreements spanning 5-10 year horizons. TenneT's 2 GW North Sea corridor program exemplifies bundled procurement favoring turnkey converter-cable integrators.
- Renewable Energy Producers:Offshore wind developers in Danish and Dutch lease areas specify HVDC export systems as part of grid connection agreements, transferring technical risk to transmission system operators under regulatory asset base frameworks.
- Industrial Users:Aluminum smelters and data centers in Iceland and Norway negotiate direct HVDC ties to remote hydro generation, bypassing national grid tariffs.
- Independent Power Producers:Merchant interconnector developers in the Mediterranean and Southeast Asia pursue bilateral HVDC links between price-convergent markets, bearing full merchant risk on capacity payments.
Utilities dominate procurement volume; renewable energy producers are expanding most quickly as offshore wind lease rounds accelerate.
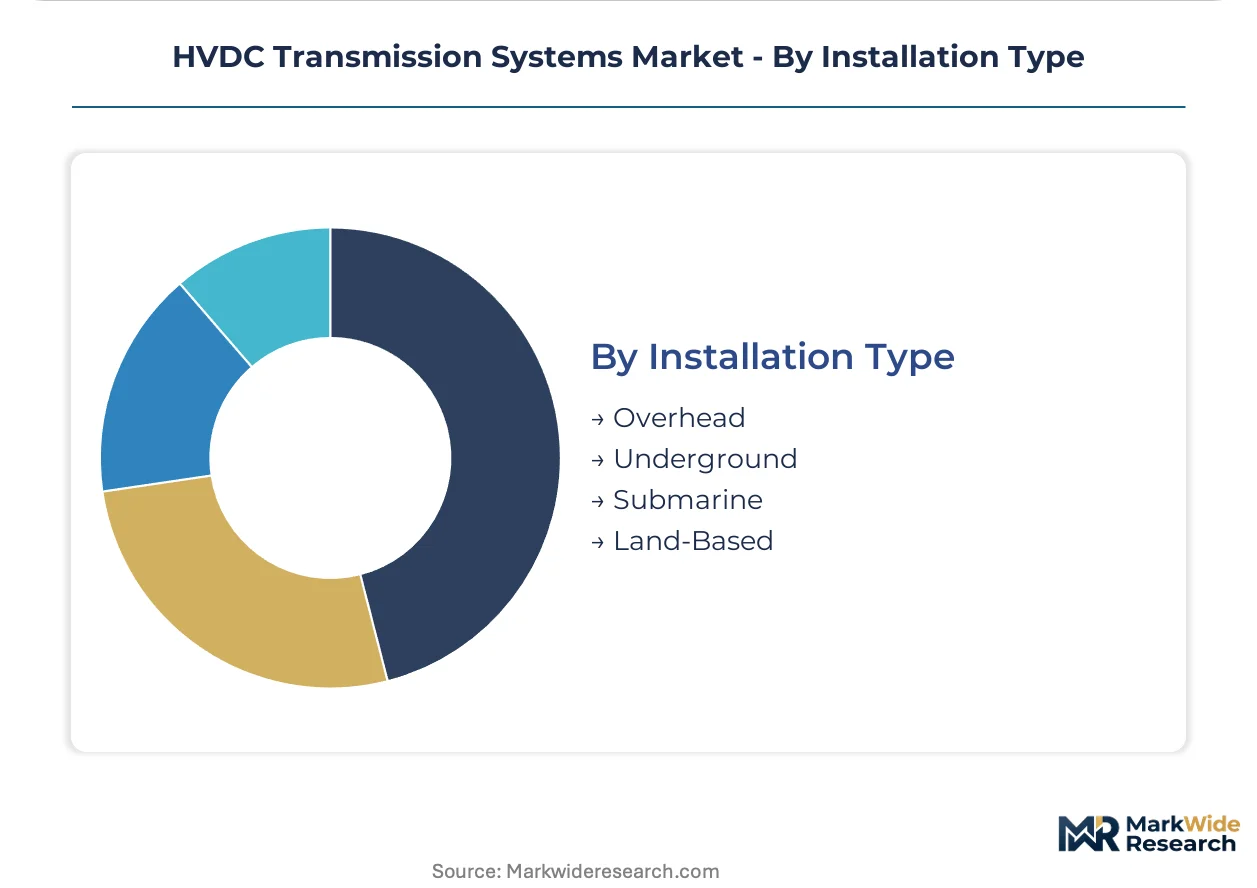
Installation Type:
Route environment dictates contractor specialization, with submarine and underground segments commanding premium pricing and extended lead times.
- Overhead:Lattice tower corridors for 800 kV LCC links span Chinese and Brazilian hinterlands, leveraging established transmission line EPC capabilities and minimizing right-of-way costs per kilometer.
- Underground:Direct-buried or tunnel-installed cables penetrate German and Swiss urban centers where overhead routing faces planning opposition. Boring machine availability and geological risk allocation dominate contractor selection.
- Submarine:Deep-water cable laying for North Sea and Mediterranean interconnectors requires dynamically positioned vessels with 3,000m+ depth capability. Vessel charter rates and weather window constraints compress installation seasons and extend project timelines.
- Land-Based:Converter station construction and onshore cable termination facilities concentrate civil works risk in German and Chinese manufacturing clusters with established high-voltage equipment handling protocols.
Overhead installations retain the largest installed base; submarine routes are climbing the fastest as offshore wind export demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal interconnection mandates and REPowerEU targets are accelerating cross-border corridor procurement across Germany, the Netherlands, and Denmark. Offshore wind developers in the North Sea are consolidating HVDC export cable demand into multi-gigawatt framework agreements. Transmission system operators in China and India are advancing ultra-long overhead corridors for remote renewable integration.
Germany
TenneT and 50Hertz are awarding bundled converter-cable contracts for North Sea offshore wind export corridors. The country's national energy regulator enforces unbundling rules while permitting regulated asset base cost recovery for HVDC infrastructure. Manufacturing clusters in Berlin-Brandenburg and Bavaria host converter valve assembly facilities serving North Sea lease developments.
China
State Grid Corporation specifies LCC technology for inland UHVDC links exceeding 2,000 km to Xinjiang and Tibet generation bases. The GB/T 30553 standard for ultra-high-voltage DC equipment shapes domestic procurement and export qualification requirements. Industrial corridors in the Yangtze River Delta concentrate converter transformer manufacturing and semiconductor fabrication capacity.
United States
FERC Order 2023 on interconnection queue reform is compressing study timelines for cross-regional transmission projects. The Federal Energy Regulatory Commission's permitting acceleration favors developers with pre-qualified converter platforms. Manufacturing activity concentrates in the Northeast Corridor and Texas, where converter station EPC contractors serve emerging offshore wind lease areas.
Netherlands
TenneT Nederland is procuring VSC-based submarine export systems for Dutch North Sea wind zones under integrated framework agreements. The EU F-Gas Regulation constrains insulating medium selection for gas-insulated switchgear in converter station tenders. The Eindhoven Region hosts cable compound formulation facilities supporting deep-water installation specifications.
India
The Central Electricity Authority mandates local transformer assembly under Green Energy Corridors program requirements for awarded HVDC projects. Domestic content rules concentrate procurement with Indian manufacturers for converter station components. Manufacturing clusters in Gujarat and Maharashtra are expanding high-voltage equipment handling protocols for corridor development.
HVDC Transmission Systems Market Competitive Environment
Listed leaders compete with private specialists across integrated converter-cable delivery capabilities. The supplier landscape bifurcates between certified incumbents holding IEC 61803 valve qualifications and excluded aspirants facing 18-24 month type-testing delays. Three archetypes dominate: integrated converter-cable suppliers controlling vessel fleets, pure-play semiconductor fabricators supplying IGBT modules, and specialized cable manufacturers with deep-water installation track records. Competitive moves center on framework agreement capture with transmission system operators and backward integration into polymer compound formulation.
Within the integrated supplier tier, Siemens Energy and Hitachi Energy exemplify archetypes combining converter station assembly with project execution capabilities. Prysmian Group occupies a position representing cable specialists competing on vessel availability and installation track record. These three companies anchor the competitive structure through differentiated control of converter semiconductor supply, submarine installation assets, or combined turnkey delivery platforms.
| Leading Market Players |
|---|
| ABB Ltd |
| Prysmian Group |
| Hitachi Energy |
| Nexans |
| NKT A/S |
| Siemens Energy |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| GE Vernova |
| Others |
Value Chain & Pricing Dynamics
Fluoronitrile blend substitution for sulfur hexafluoride in gas-insulated switchgear is simultaneously relocating compound formulation expertise toward German and Dutch chemical clusters and compressing margins for incumbent switchgear manufacturers facing qualification retesting costs. This input transition concentrates pricing power with polymer suppliers holding REACH pre-certification while forcing converter station EPCs to absorb reformulation premiums or risk tender disqualification.
Pricing Analysis
IEC 61803 certification tier creates the primary price spread between qualified valve manufacturers and excluded aspirants facing 18-24 month type-testing delays. Project-based long-term offtake contracts dominate, with price differentiation driven by converter semiconductor sourcing security and vessel fleet availability for submarine installation. Cost compression in standard-grade cable supply is intensifying because polymer compound formulation capacity is tightening under EU F-Gas phase-down schedules. Merchant interconnect developers exhibit highest price sensitivity due to merchant risk exposure, while German transmission system operators under regulated asset base frameworks prioritize technical compliance over unit cost.
Supply Chain Analysis
Germany and China anchor converter valve assembly and ultra-high-voltage transformer manufacturing respectively, with Taiwan and South Korea feeding semiconductor wafer supply for IGBT module fabrication. The supply chain draws from rare earth elements for permanent magnet components, copper rod for extruded polymer cables, and specialized fluoronitrile compounds for insulating medium reformulation. Single-source vulnerability concentrates in dynamically positioned cable-laying vessel fleets where charter availability determines project timelines. Distribution runs through framework agreements bundling converter station EPC with submarine cable supply into single-source turnkey contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC transmission systems sit at an early-cycle expansion story driven by North Sea offshore wind lease rounds that are consolidating multi-gigawatt procurement into bundled framework agreements with integrated suppliers.
For Market Incumbents: Shield certified converter valve positions by accelerating silicon carbide qualification timelines before SiC-based competitors erode the VSC cost premium on long-distance corridors. Prioritize backward integration into polymer compound formulation to capture fluoronitrile blend margins and preempt REACH-driven supplier consolidation in German tender specifications. For New Entrants and Emerging Players: Post-installation digital asset monitoring represents a service-layer gap where incumbents under-serve, creating entry points for predictive maintenance platforms targeting Mediterranean offshore wind developers lacking established HVDC supply chains. Target Italian and Greek lease areas with vessel-light converter station EPC offerings, partnering with cable specialists for marine installation rather than replicating fleet ownership. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors integrated converter-cable suppliers with captive semiconductor fabrication and vessel fleet control. Long-term viability hinges on framework agreement capture with transmission system operators bundling awards across 5-10 year horizons. Watch for F-Gas Regulation enforcement acceleration as the inflection signal that reshapes competitive positioning toward pre-qualified fluoronitrile-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Valve Qualification | Decomposes VSC-LCC cost tradeoffs for 2 GW North Sea bipole links. |
| Fluoronitrile Compound Backward Integration | Captures insulating medium margins under EU F-Gas phase-down schedules. |
| Vessel Fleet Expansion | Secures installation slots for deep-water Mediterranean routes. |
| Multi-Terminal VSC Network Development | Enables meshed DC architectures for incremental generation connection. |
| Framework Agreement Capture | Locks multi-gigawatt procurement with TenneT and 50Hertz corridor programs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across transmission system operator planning departments, offshore wind developer engineering teams, converter station EPC contractors, cable-laying vessel operators, and semiconductor fabrication specialists. Secondary validation drew from FERC interconnection queue filings, EU tender documentation from TenneT and 50Hertz, GB/T 30553 standard publications, IEC type-test reports, and customs data on high-voltage equipment trade flows. Bottom-up project pipeline aggregation was triangulated against top-down transmission investment forecasts.
Across the analysis window, the forecasting framework modeled technology selection between LCC and VSC architectures, component sourcing patterns for converter stations versus cables, installation method splits across submarine and overhead routes, and end-user procurement centralization trends. CAGRs were derived from project award trajectories and regulatory mandate timelines. Forecast inputs incorporated offshore wind lease round schedules and EU Green Deal interconnection targets.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and FERC Order 2023 implementation; material policy shifts would require re-modeling. Semiconductor foundry allocation decisions and vessel fleet availability constraints represent specific revision risks. Recalibration cycles align with material shifts in transmission system operator procurement patterns and offshore wind lease award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market