
 India Wind Industry Market | 2026-2036
India Wind Industry Market Size, Share, and Industry Trends Forecast 2026-2036
India Wind Industry Market Insights
Turbine technology is fragmenting across multiple drivetrain architectures and blade material formulations. Suzlon Energy Limited anchors onshore manufacturing scale across Maharashtra and Gujarat facilities. Vestas Wind Systems A/S (India) differentiates through advanced control systems and service contracts. Inox Wind Limited specializes in integrated tower and blade production for utility-scale deployments.
The India Wind Industry encompasses the design, manufacture, installation, and operation of systems that convert kinetic wind energy into electrical power through aerodynamic rotor blades connected to generators, with modern units reaching hub heights exceeding 120 meters and rotor diameters above 140 meters to capture stronger, more consistent wind streams at altitude. Horizontal Axis Turbines dominate installed capacity due to proven efficiency and established supply chains, while Energy Storage Systems represent the fastest-expanding technology segment as grid operators require firm dispatchable output. Utility-scale Power Generation captures the deepest margin pools through long-term power purchase agreements, though Distributed Energy Resources are gaining traction among commercial enterprises seeking behind-the-meter supply security.
Central Electricity Authority mandates and MNRE guidelines shape project commissioning timelines and grid interconnection standards, while BIS certification requirements enforce mechanical load and electrical safety benchmarks for turbine components. State nodal agencies in Gujarat, Tamil Nadu, and Karnataka administer land allocation and evacuation infrastructure clearances that determine project viability. Stakeholders must track evolving interstate transmission regulations and green hydrogen offtake agreements that could redirect wind capacity toward electrolyzer feedstock contracts rather than pure grid injection.
Market Dynamics
State renewable purchase obligations are tightening procurement timelines for energy utilities while turbine OEMs race to scale 3 MW-plus platforms with hub heights exceeding 140 meters.
Growth Catalysts
- Renewable Purchase Obligations:State mandates in Gujarat, Tamil Nadu, and Karnataka compel distribution companies to source wind power, creating guaranteed offtake channels for project developers.
- Hub Height Advancement:Taller towers accessing stronger wind streams at altitude are lifting capacity factors across semi-arid zones previously deemed marginal for development.
- Grid-Scale Storage Pairing:Battery energy storage systems co-located with wind farms are addressing intermittency concerns and qualifying projects for firm dispatch contracts.
Market Restraints
- Land Acquisition Friction:Fragmented landholding patterns and competing agricultural use claims delay project commissioning timelines by 18-24 months in key states.
- Transmission Bottlenecks:Inadequate evacuation infrastructure in Rajasthan and Madhya Pradesh forces curtailment during high-generation periods, eroding project returns.
- Import Dependency:Specialized bearings and power electronics remain concentrated with European and East Asian suppliers, exposing developers to currency volatility and logistics disruption.
Strategic Opportunities
- Green Hydrogen Feedstock:MNRE guidelines enabling wind-to-hydrogen projects are redirecting capacity toward electrolyzer offtake agreements with industrial consumers.
- Repowering Legacy Assets:Aging sub-1 MW turbines installed in the 1990s across Maharashtra offer replacement potential with modern high-capacity units on existing land leases.
- Behind-the-Meter Commercial:Open access regulations in Karnataka and Andhra Pradesh allow large manufacturing facilities to contract directly with wind developers, bypassing utility intermediaries.
Industry Challenges
- Specialized Technician Scarcity:Blade repair, drivetrain maintenance, and high-voltage commissioning require skills that training institutes have not scaled to match installation velocity.
- BIS Certification Timelines:Mechanical load testing and electrical safety validation for new turbine models extend product launch cycles by 8-12 months.
- Legacy Grid Integration:Weak transmission networks in eastern states struggle to absorb variable renewable injection, forcing developers to fund dedicated evacuation lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wind Industry Market |
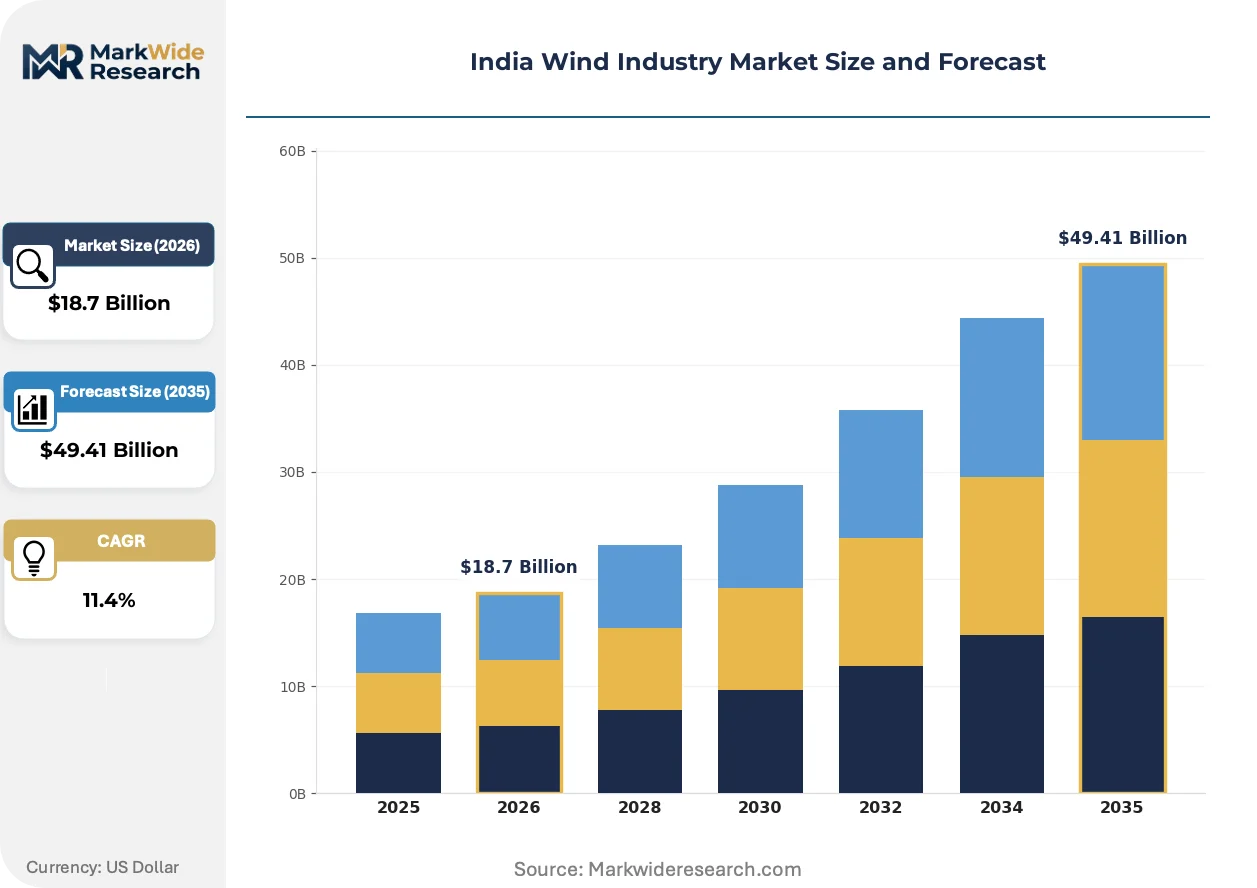
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Small Wind Turbines, Off-grid Wind Systems Technology: Smart Grid Technology, Energy Storage Systems, Remote Monitoring Solutions, Advanced Wind Forecasting Application: Utility-scale Power Generation, Distributed Energy Resources, Rural Electrification, Hybrid Systems End User: Energy Utilities, Commercial Enterprises, Agricultural Sector, Residential Consumers |
| Companies Covered | Envision Group, Suzlon Energy Limited, Inox Wind Limited, TPG-led entity (formerly Siemens Gamesa India), Vestas Wind Systems A/S (India), GE Renewable Energy (India), Wind World India Ltd., Adani Wind, Tata Power Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wind Industry Market Trends and Innovations
Digital instrumentation and predictive analytics are reconfiguring how wind assets are operated, financed, and integrated with broader energy systems across Indian states.
Advanced condition monitoring systems deploying fiber-optic strain sensors and vibration analysis are digitizing turbine health management. Independent power producers and utility-scale operators are retrofitting existing fleets with these platforms to compress unplanned downtime and extend component life cycles. The structural consequence is digitizing maintenance scheduling from calendar-based interventions toward predictive trigger models that optimize technician dispatch and spare parts inventory.
Central Electricity Authority mandates on frequency response and reactive power capability are tightening grid code compliance for new wind farms. These technical standards require turbines to ride through voltage disturbances and provide ancillary services previously reserved for conventional thermal plants. Grid-connected projects in Gujarat and Tamil Nadu are most affected, with developers selecting turbine control systems specifically rated for these dynamic performance requirements.
Corporate renewable energy procurement through group captive structures is displacing traditional utility-mediated power purchase agreements. Large textile, cement, and information technology consumers in Karnataka and Maharashtra are negotiating direct bilateral contracts with wind developers, securing fixed tariffs and supply certainty. This channel shift is most visible among manufacturing facilities with continuous baseload requirements and credit profiles that support long-term contract structures.
India Wind Industry Market Segmentation
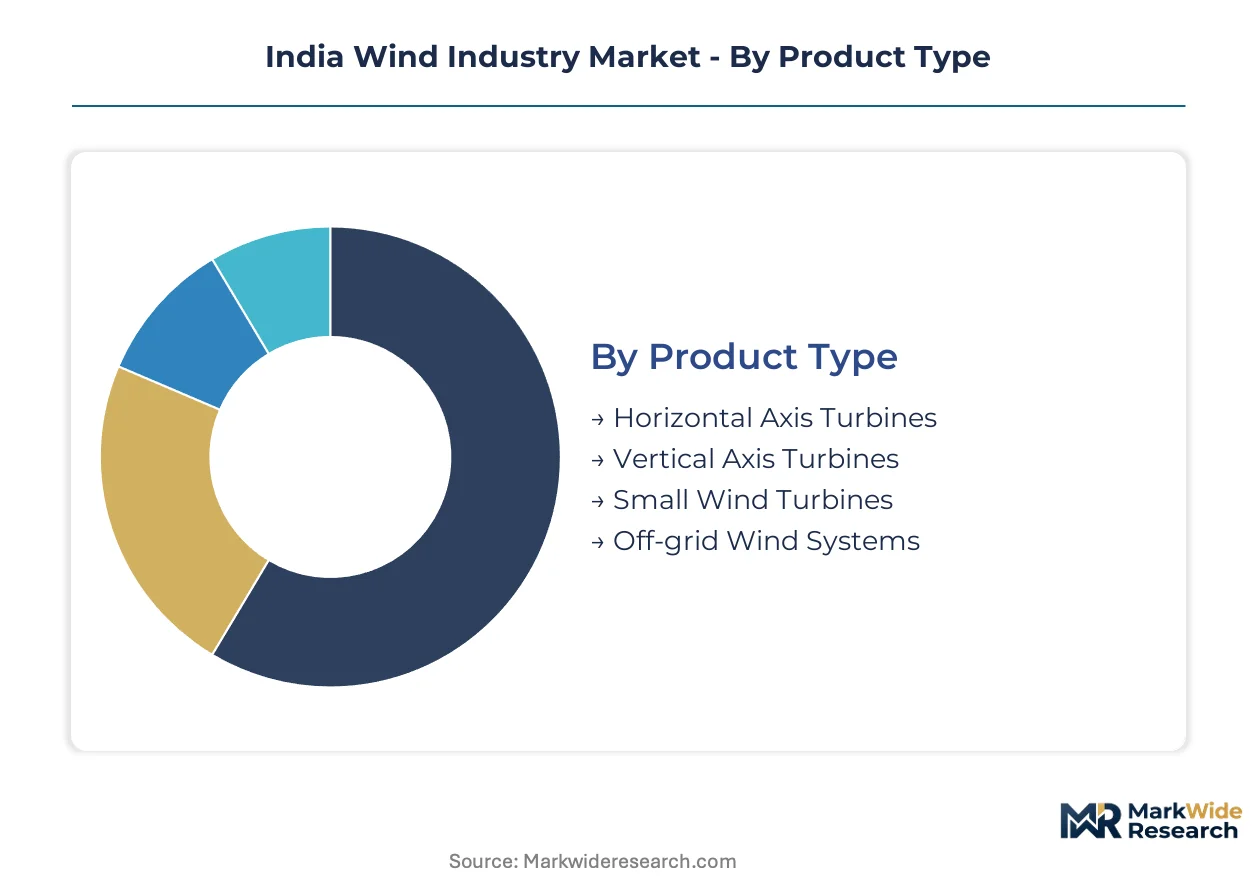
Wind turbine configurations and integration technologies serve distinct investment horizons and risk-return profiles across Indian states. Segmentation reveals where capital is concentrating and which technology pairings are reshaping project economics.
Product Type:
Cost tier stratification separates mass-market deployment platforms from specialized applications requiring distinct engineering approaches.
- Horizontal Axis Turbines:Three-blade upwind configurations dominate utility-scale installations with hub heights exceeding 120 meters and rotor diameters above 140 meters. Procurement concentrates among Gujarat and Tamil Nadu developers seeking capacity factors above 35% through taller tower configurations. CEA grid code compliance requirements are filtering turbine selection toward models with advanced power electronics and ride-through capabilities.
- Vertical Axis Turbines:Darrieus and Savonius designs capture urban and distributed applications where omnidirectional wind acceptance reduces siting constraints. Maharashtra commercial campuses and Karnataka industrial parks are piloting vertical units for behind-the-meter supply where space geometry favors compact footprints over peak efficiency.
- Small Wind Turbines:Sub-100 kW units serve agricultural pumping and rural microgrids in Rajasthan and Madhya Pradesh where grid extension remains uneconomical.
- Off-grid Wind Systems:Battery-coupled configurations electrify remote hamlets in Ladakh and Northeastern states beyond transmission reach.
Horizontal Axis Turbines commands the established base. The steepest expansion runs through Small Wind Turbines.
Technology:
Application maturity varies sharply between grid-facing digital infrastructure and emerging storage pairings still proving commercial viability.
- Smart Grid Technology:SCADA integration and substation automation enable real-time generation forecasting and dispatch optimization. Adoption clusters among Gujarat and Tamil Nadu transmission utilities modernizing control centers to manage variable renewable penetration.
- Energy Storage Systems:Lithium-ion and emerging flow battery configurations co-locate with wind farms to shift generation profiles toward peak demand windows. Karnataka and Andhra Pradesh developers are pairing storage with open access projects to qualify for firm dispatch contracts previously reserved for thermal assets.
- Remote Monitoring Solutions:Fiber-optic strain sensors and vibration analytics compress unplanned downtime across Maharashtra and Gujarat fleets.
- Advanced Wind Forecasting:Mesoscale modeling and LIDAR integration improve day-ahead scheduling accuracy for CEA-mandated generation estimates.
Smart Grid Technology anchors current deployment. Energy Storage Systems are climbing the fastest as tariff structures reward dispatchable renewable output.
Application:
Volume concentration tracks state-level procurement mechanisms while margin pools diverge between utility-scale offtake and distributed commercial structures.
- Utility-scale Power Generation:Grid-connected farms above 25 MW capacity feed state transmission networks under long-term power purchase agreements. Gujarat Urja Vikas Nigam and Tamil Nadu Generation and Distribution Corporation anchor procurement through competitive bidding and feed-in tariff mechanisms.
- Distributed Energy Resources:Commercial and industrial open access installations bypass utility intermediaries through direct bilateral contracts. Karnataka textile clusters and Maharashtra cement plants are contracting wind capacity for baseload supply security and tariff predictability.
- Rural Electrification:Mini-grid wind-diesel hybrids serve unelectrified settlements in Bihar and Uttar Pradesh.
- Hybrid Systems:Wind-solar pairing optimizes land use and generation profiles across Rajasthan's solar-wind parks.
Utility-scale Power Generation retains the dominant share. Distributed Energy Resources are gaining share fastest as open access regulations mature.
End User:
Customer type determines financing structures, contract tenors, and risk allocation across the project development cycle.
- Energy Utilities:State distribution companies procure wind capacity to meet renewable purchase obligations mandated by state electricity regulatory commissions. Gujarat, Tamil Nadu, and Karnataka discoms dominate procurement volumes through centralized auctions and feed-in tariffs.
- Commercial Enterprises:Manufacturing facilities with continuous baseload requirements negotiate group captive structures for supply certainty. Karnataka information technology parks and Maharashtra automotive clusters are contracting directly with independent power producers.
- Agricultural Sector:Farmer cooperatives install small turbines for irrigation pumping in Maharashtra and Gujarat.
- Residential Consumers:Net-metered rooftop units serve high-consumption households in Pune and Bangalore urban peripheries.
Energy Utilities anchor procurement volume. Commercial Enterprises are expanding most quickly as open access frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian turbine manufacturers export components to Southeast Asian and African markets while domestic demand concentrates in five states with favorable wind resource profiles and grid infrastructure.
Gujarat
Coastal wind corridors and dedicated renewable energy zones attract utility-scale developers seeking high capacity factors. Gujarat Urja Vikas Nigam administers competitive bidding for procurement under state renewable purchase obligations. Kutch and Saurashtra regions host manufacturing clusters where blade and tower fabrication facilities co-locate with port infrastructure for export logistics.
Tamil Nadu
Mature wind farms dating to the 1990s create repowering opportunities alongside greenfield expansion in Palakkad Gap wind corridors. Tamil Nadu Generation and Distribution Corporation mandates frequency response capabilities for grid-connected projects. Coimbatore and Tiruppur industrial belts drive behind-the-meter demand from textile and engineering units seeking open access supply.
Karnataka
Chitradurga and Gadag districts combine high wind shear indices with established transmission corridors to Bangalore load centers. Karnataka Renewable Energy Development Limited streamlines land allocation through renewable energy parks with pre-cleared evacuation infrastructure. Bengaluru information technology parks and Mysuru manufacturing facilities anchor corporate renewable procurement through group captive structures.
Maharashtra
Satara and Sangli districts in the Western Ghats retain operational legacy turbines requiring modernization with larger rotor platforms. Maharashtra Energy Development Corporation coordinates repowering clearances for sub-1 MW units installed on expired land leases. Pune industrial corridors generate distributed demand from automotive and pharmaceutical clusters pursuing supply security through direct developer contracts.
Rajasthan
Jaisalmer and Jodhpur wind zones offer superior resource quality constrained by transmission bottlenecks to northern load centers. Rajasthan Renewable Energy Corporation administers land banking for hybrid wind-solar parks under state renewable energy policies. Phased transmission upgrades through Green Energy Corridors aim to reduce curtailment rates that currently erode project returns during high-generation periods.
India Wind Industry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement, manufacturing scale, and service contract tenure. The vendor base separates into three tiers: integrated OEMs with captive component production, technology licensors partnering with domestic fabricators, and independent power producers sourcing equipment through competitive tender. Strategic moves concentrate on hub height advancement through taller tower supply chains and energy storage co-location to qualify for firm dispatch contracts.
Among integrated domestic manufacturers, Suzlon Energy Limited, Inox Wind Limited, and Vestas Wind Systems A/S (India) occupy distinct positioning archetypes. Suzlon anchors manufacturing scale across Maharashtra and Gujarat facilities with backward integration into tower and blade production. Inox Wind exemplifies the integrated specialist model through captive nacelle assembly and control system integration. Vestas represents the technology-licensor archetype, importing core drivetrain components while localizing tower supply and service infrastructure.
| Leading Market Players |
|---|
| Envision Group |
| Suzlon Energy Limited |
| Inox Wind Limited |
| TPG-led entity (formerly Siemens Gamesa India) |
| Vestas Wind Systems A/S (India) |
| GE Renewable Energy (India) |
| Wind World India Ltd. |
| Adani Wind |
| Tata Power Company |
| Others |
Pricing and Supply Chain Analysis
Kutch manufacturing clusters in Gujarat anchor turbine component fabrication, and their capacity utilization swings directly determine pricing leverage for domestic OEMs negotiating with state distribution companies. The concentration of blade and tower production in this coastal belt creates asymmetric bargaining power that ripples through project development economics.
Pricing Analysis
Current-generation 3 MW-plus platforms with 140-meter hub heights command premium positioning against prior-generation 2 MW units and pre-commercial next-gen 5 MW designs. Three-tier pricing structure across premium, standard, and economy levels tracks rotor diameter, hub height, and grid-code compliance certification. Pricing pressure stems from aggressive competitive bidding by Gujarat Urja Vikas Nigam and Tamil Nadu Generation and Distribution Corporation, which compresses developer margins and forces OEMs to absorb cost escalation. State distribution companies exhibit highest price sensitivity due to renewable purchase obligation compliance pressures, while corporate group captive buyers prioritize supply certainty over tariff minimization.
Supply Chain Analysis
Supplier-financing structures including 180-day payment terms and supply-chain finance facilities anchored by REC-backed instruments have become critical liquidity bridges for component vendors. Manufacturing concentration rests on China for permanent magnet rare earth processing, Germany for precision bearings, and domestic Maharashtra-Gujarat corridors for structural steel fabrication. Specialized power electronics and fiber-optic sensor modules draw from South Korean and Japanese suppliers, creating single-source vulnerability for advanced control systems. Distribution runs through EPC contractors with captive logistics fleets for nacelle transport and crane mobilization, bypassing third-party freight networks for oversized cargo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across state regulatory regimes and technology generations creates multiple niche entry points. Corporate renewable procurement through open access frameworks is splintering demand away from centralized utility auctions, enabling specialized positioning.
For Market Incumbents: Insulate service contract tenure by extending operations and maintenance agreements to 15-year terms with predictive analytics bundling, countering emerging IPPs that compete on upfront capital cost. Deepen backward integration into tower fabrication through dedicated steel rolling facilities in Gujarat, reducing exposure to commodity volatility and logistics disruption from third-party suppliers. For New Entrants and Emerging Players: Build out repowering capabilities targeting Maharashtra's aging sub-1 MW turbine fleet, where land lease renewals and evacuation infrastructure already exist. Target behind-the-meter commercial segments in Karnataka textile clusters, where open access regulations enable direct bilateral contracting bypassing utility intermediaries. Lead with energy storage co-location expertise to qualify for firm dispatch contracts that established OEMs have been slow to integrate. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive blade production and control system integration capabilities over pure technology licensors. The 5-10 year viability window hinges on electrolyzer feedstock contract capture for green hydrogen production, redirecting wind capacity away from pure grid injection. Monitor MNRE guideline evolution on wind-to-hydrogen project eligibility as the critical inflection signal for capacity allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hub Height Advancement | Taller tower supply chains accessing 140-meter configurations lift capacity factors above 35% in semi-arid zones. |
| Energy Storage Co-location | Battery pairing qualifies wind farms for firm dispatch contracts previously reserved for thermal assets under CEA mandates. |
| Repowering Legacy Assets | Replacement of sub-1 MW turbines in Maharashtra leverages existing land leases and evacuation infrastructure. |
| Green Hydrogen Feedstock Pivot | Electrolyzer offtake agreements redirect capacity toward industrial hydrogen consumers under MNRE guidelines. |
| Corporate Open Access Expansion | Direct bilateral contracts with Karnataka and Maharashtra manufacturing clusters bypass utility intermediary margins. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through Central Electricity Authority generation estimates, MNRE project commissioning databases, state electricity regulatory commission tariff orders, and BIS certification records. Bottom-up capacity addition tracking across Gujarat, Tamil Nadu, Karnataka, Maharashtra, and Rajasthan was triangulated against top-down renewable purchase obligation compliance targets issued by state regulators.
Forecast inputs considered turbine OEM order backlogs, state-level land allocation timelines, Green Energy Corridor transmission upgrade schedules, and corporate renewable procurement announcements. Segmentation modeling spanned product type, technology pairing, application scale, and end-user category across the analysis window. CAGRs were derived from regression analysis of historical capacity additions against regulatory obligation trajectories, with specific weighting for hub height advancement curves and storage cost decline assumptions.
Stress conditions across transmission bottleneck severity, currency volatility for imported components, and renewable purchase obligation enforcement consistency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on state policy continuity and technology cost curves. Macroeconomic contraction, interstate regulatory fragmentation, or breakthrough next-generation turbine architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Spain Wind Energy Market