
 Global Surge Arrester Market | 2026-2036
Global Surge Arrester Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surge Arrester Market Intelligence
Silicon carbide-to-metal oxide varistor migration is rewriting manufacturing economics across the surge arrester value chain. Siemens AG leverages deep vertical integration in ceramic disc production to sustain cost advantages in extra-high-voltage ratings. ABB Ltd anchors its position through IEC-certified testing infrastructure that spans three continents. Hitachi Energy Ltd specializes in hybrid designs that integrate monitoring electronics directly into the arrester housing.
A surge arrester is a protective device that limits transient overvoltages by diverting surge current to earth, typically constructed from zinc oxide discs sintered at temperatures exceeding 1100°C and housed in polymer or porcelain insulators to withstand switching surges up to several hundred kiloamperes. Metal oxide varistor technology dominates value capture due to its non-linear voltage-current characteristic that eliminates spark gaps entirely, while renewable energy systems represent the fastest-expanding application segment as solar farms and offshore wind installations multiply the count of distributed nodes requiring protection. Power transmission remains the most mature application with established replacement cycles, though telecommunication networks are gaining share as 5G base station deployment multiplies low-voltage arrester demand.
The IEC 60099 series and IEEE C62.11 standards govern arrester energy absorption ratings and pressure relief behavior, while EU REACH regulations restrict cadmium and lead content in varistor formulations, compelling reformulation investments across European supply chains. China's GB 11032 standard mandates seismic withstand testing that exceeds baseline IEC requirements, creating a dual-certification burden for exporters. Stakeholders must monitor how national grid codes incorporate lightning density data into arrester selection protocols, as this shifts specification power from manufacturers toward utility engineering departments.
Market Dynamics
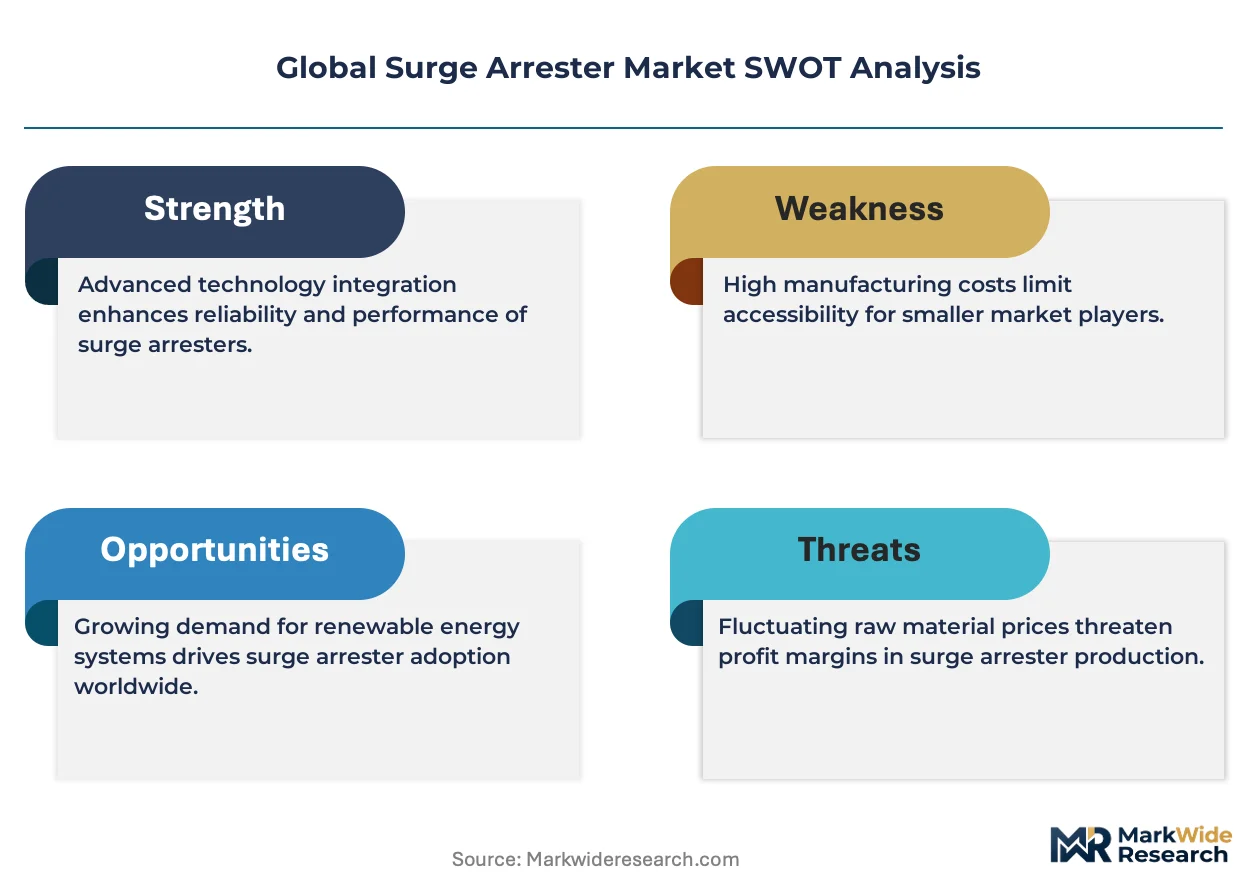
The migration from silicon carbide to metal oxide varistor technology is compressing manufacturing margins while elevating certification barriers across high-voltage applications.
Growth Catalysts
- Grid Modernization Mandates:China's State Grid Corporation and India's Power Grid Corporation are accelerating transmission infrastructure procurement, directly expanding arrester deployment across 765 kV and 1200 kV substations.
- IEC 60099-4 Certification Expansion:European utilities now require third-party witnessed testing for energy absorption ratings above 10 kJ/kV, creating specification pull for certified manufacturers.
- Offshore Wind Proliferation:Collector systems at North Sea wind farms multiply distributed protection nodes, with each 500 MW installation requiring 400+ medium-voltage arresters for transformer and cable protection.
Market Restraints
- Zinc Oxide Disc Supply Concentration:Sintering furnace capacity clusters in Japan and Germany, creating geographic chokepoints for high-grade ceramic substrates.
- EU REACH Cadmium Restrictions:Reformulation of varistor dopants to eliminate heavy metals adds 12-18 months to product qualification cycles for European market entry.
- Porcelain Housing Cost Volatility:Alumina prices fluctuate with bauxite mining output from Guinea and Australia, compressing margin stability for traditional insulator designs.
Strategic Opportunities
- Brazilian Transmission Auctions:ANEEL's biennial capacity auctions mandate local content thresholds, creating entry points for arrester assembly partnerships with domestic transformer manufacturers.
- 5G Base Station Electrification: Low-voltage DC protection at cell towers represents an underserved application segment with distinct specification requirements from utility-grade products.
- Digital Monitoring Convergence:Integration of IoT sensors for leakage current trending enables condition-based replacement cycles, shifting revenue from hardware to predictive service models.
Industry Challenges
- Seismic Qualification Bottlenecks:China's GB 11032 standard exceeds IEC baseline requirements for earthquake withstand testing, forcing dual-certification investments for export-oriented suppliers.
- High-Voltage Testing Infrastructure Scarcity:Laboratories capable of generating 2 MJ impulse currents for UHV arrester validation number fewer than twelve worldwide, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surge Arrester Market |
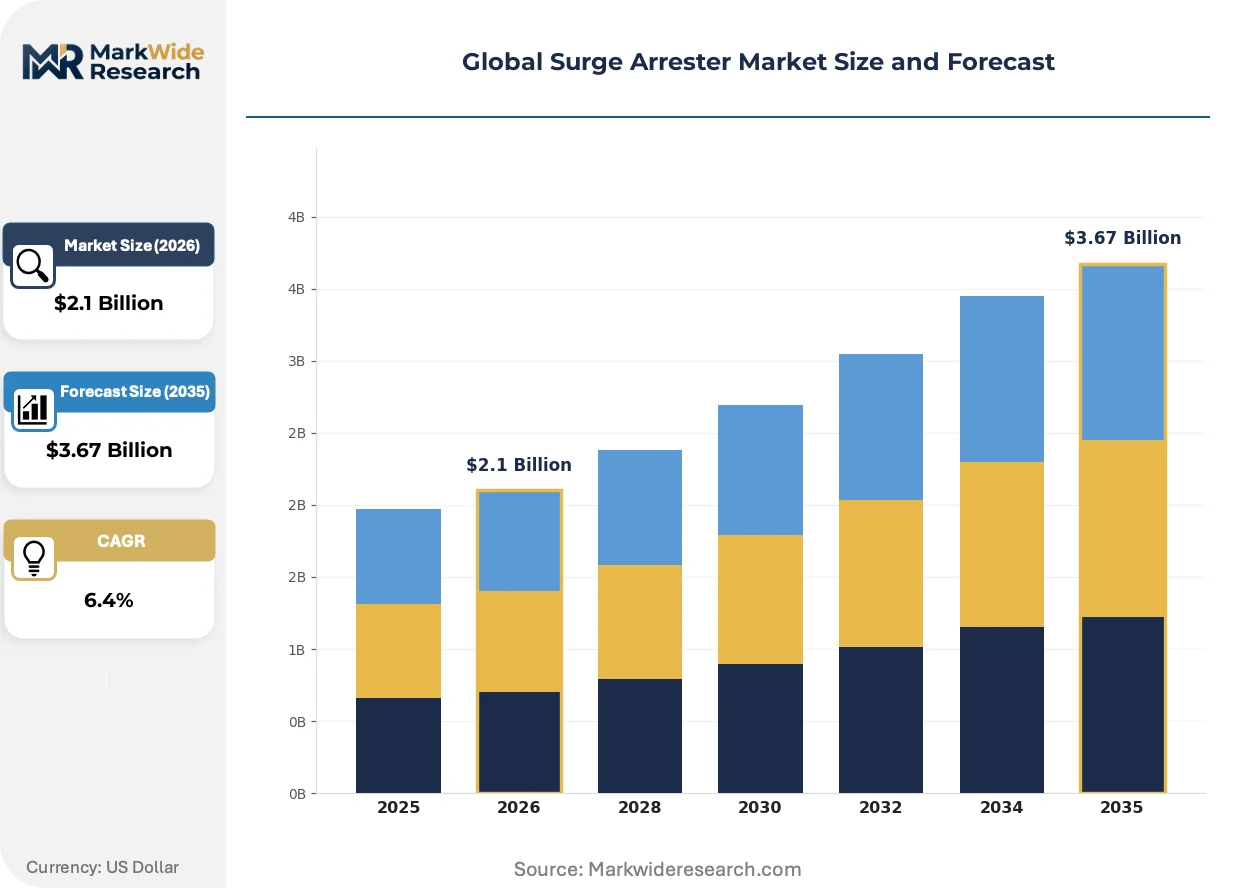
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Oxide Varistor, Gas Discharge Tube, Spark Gap, Silicon Avalanche Diode Application: Power Transmission, Telecommunication Networks, Renewable Energy Systems, Industrial Manufacturing End User: Electric Utilities, Telecommunication Providers, Solar Farms, Heavy Engineering Firms Installation Type: Indoor, Outdoor, Substation, Distribution Line |
| Companies Covered | Siemens AG, ABB Ltd, Hitachi Energy Ltd, Eaton Corporation, Schneider Electric SE, Hubbell Incorporated, General Electric, DEHN SE, CG Power & Industrial Solutions Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surge Arrester Market Strategic Shifts & Innovations
Arrester design is bifurcating between compact polymer-housed units for distribution networks and intelligent monitored systems for critical transmission assets.
Direct-bonded silicone rubber housing technology is collapsing the cost differential between porcelain and polymer insulators. European utilities now specify composite housings for 90% of new 145 kV installations. This material shift eliminates cement growth failures and reduces transport weight by 70%, enabling single-person installation crews.
REACH Annex XVII amendments are forcing reformulation of zinc oxide varistor compositions across EU supply chains. Manufacturers must substitute bismuth oxide dopants for cadmium-based variants without degrading non-linear voltage-current characteristics. German testing houses report 18-month qualification delays as suppliers iterate ceramic recipes to maintain energy absorption ratings.
Utility engineering departments are consolidating procurement through framework agreements that bundle arresters with switchgear and transformer packages. This channel compression disadvantages standalone arrester specialists in favor of integrated equipment suppliers. The pattern is most pronounced in the United States, where FERC Order 1000 incentives favor turnkey substation contractors over component-level sourcing.
Global Surge Arrester Market Segmentation
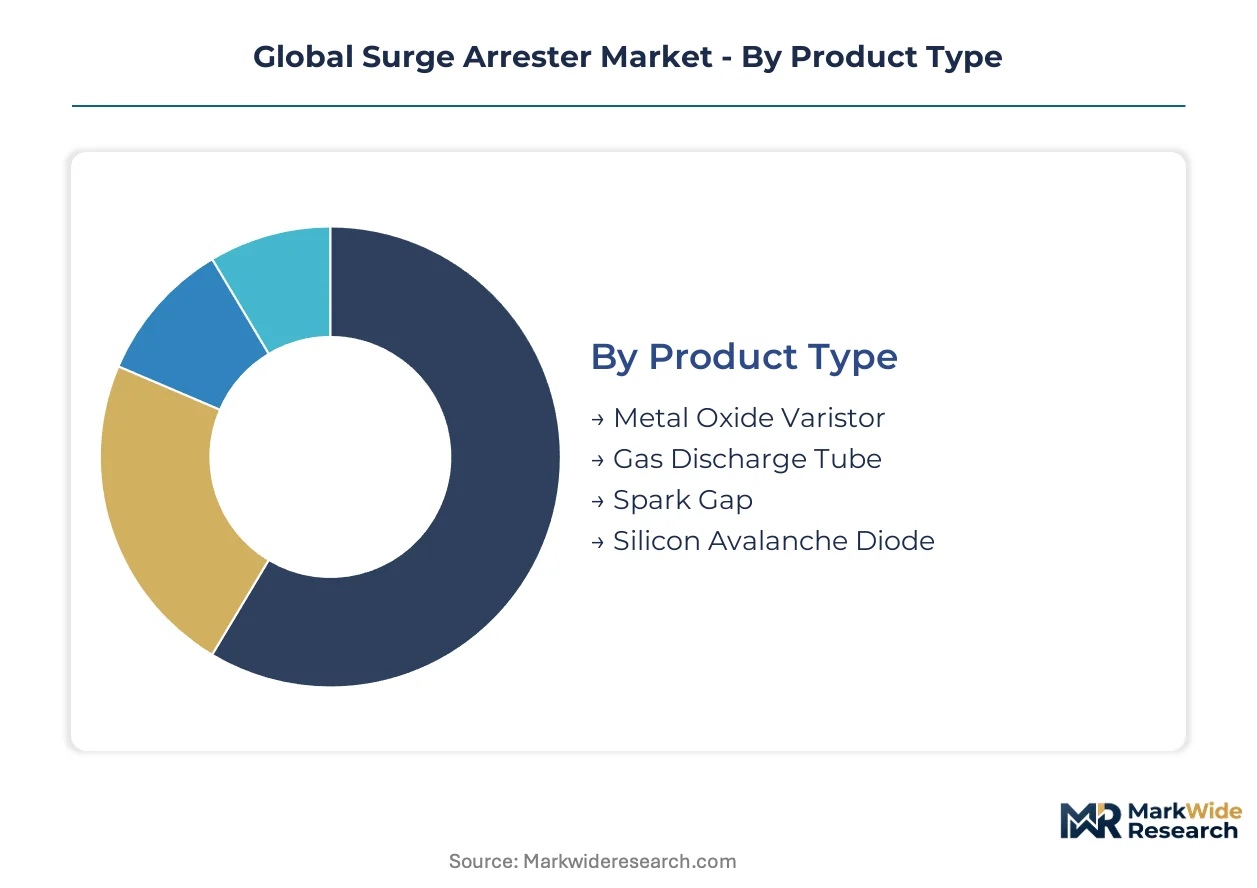
Segmentation in the surge arrester market reveals divergent replacement cycles that shape inventory planning and margin structures across the value chain. Technology migration rates and application criticality create stark differences in how quickly each segment turns over.
Product Type:
Replacement cycles stretch from 5 years in telecommunications to 40+ years in high-voltage transmission, compressing margin recovery windows for some technologies while extending them for others.
- Metal Oxide Varistor:Zinc oxide discs sintered above 1100°C deliver non-linear voltage-current characteristics that eliminate spark gaps entirely. Electric utilities in China and India are standardizing procurement on MOV-based units for 765 kV substations as grid modernization accelerates.
- Gas Discharge Tube:Hermetically sealed noble gas chambers provide microsecond response times for low-voltage signal protection. Telecommunication providers specify GDTs for 5G base station DC power feeds, though solid-state alternatives are eroding share in sub-1 kV applications.
- Spark Gap:Air-gap breakdown technology persists in legacy railway electrification systems and some industrial motor protection schemes where maintenance access permits periodic gap adjustment.
- Silicon Avalanche Diode:Semiconductor junction devices dominate precision electronics protection with clamping voltages accurate to within 5%. Data center operators specify SADs for server rack power distribution units.
Metal oxide varistor anchors the volume base while silicon avalanche diode gains share at the steepest rate.
Application:
Cost tiers separate mission-critical transmission assets from commodity distribution protection, with pricing spreads exceeding 10:1 between ultra-high-voltage and low-voltage installations.
- Power Transmission:Extra-high-voltage arresters rated above 420 kV require multi-column disc assemblies and porcelain or composite housings capable of withstanding switching surges to 100 kA. State Grid Corporation of China and India's Power Grid Corporation drive procurement through centralized tenders with 25-year service life specifications.
- Telecommunication Networks:Compact DC protection modules for cellular infrastructure operate at 48 V with response times under 1 nanosecond. Tower companies specify polymer-housed units for weight reduction on monopole structures.
- Renewable Energy Systems:Offshore wind collector systems multiply protection node counts, with each 500 MW installation requiring 400+ medium-voltage arresters for transformer and cable protection against switching transients.
- Industrial Manufacturing:Motor control centers and variable frequency drives demand arresters with high energy absorption per unit volume to protect against capacitor switching and lightning-induced transients.
Power transmission commands the premium price tier while renewable energy systems expand most quickly.
End User:
Customer concentration patterns split between consolidated national utilities and fragmented private operators, reshaping sales channel economics.
- Electric Utilities:Vertically integrated grid operators in China, India, and the United States account for the majority of high-voltage arrester procurement through multi-year framework agreements.
- Telecommunication Providers:Tower companies and mobile network operators specify standardized low-voltage protection modules across thousands of distributed sites.
- Solar Farms:Independent power producers and asset managers procure medium-voltage arresters for inverter stations and collection system transformers, with procurement fragmented across project finance structures.
- Heavy Engineering Firms:EPC contractors bundle arrester procurement into turnkey substation packages, favoring suppliers with switchgear and transformer integration capabilities.
Electric utilities concentrate the highest-value contracts while solar farms fragment procurement across project-specific sourcing.
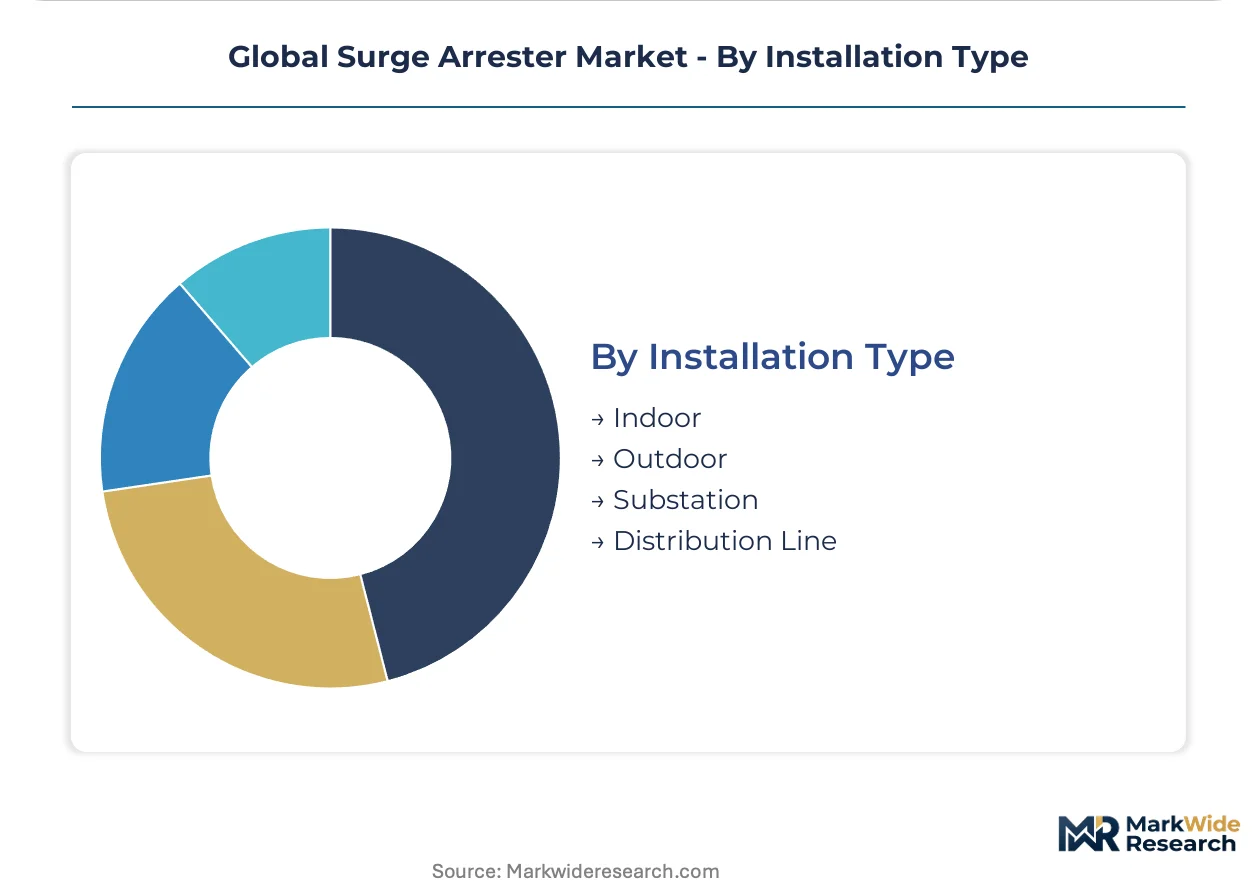
Installation Type:
Environmental exposure severity drives housing material selection and maintenance protocol differentiation.
- Indoor:GIS substations and switchgear rooms specify compact arresters with reduced creepage distances, protected from direct weather exposure.
- Outdoor:Overhead line installations require polymer or porcelain housings with enhanced pollution performance for coastal and desert environments.
- Substation:Dedicated protection bays at transmission substations accommodate the largest unit dimensions and highest energy absorption ratings.
- Distribution Line:Pole-mounted arresters for medium-voltage feeders prioritize light weight and tool-free installation to reduce lineworker exposure.
Outdoor installations dominate unit volumes while substation applications capture the highest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports surge arrester testing equipment and ceramic substrate technologies to utilities across Central Asia and Southeast Asia, with sintering furnace manufacturers in Bavaria supplying furnace systems to Japanese and Indian varistor producers.
China
State Grid Corporation procurement for 765 kV and 1200 kV substations drives arrester deployment at unprecedented scale. GB 11032 mandates seismic withstand testing that exceeds IEC baselines, forcing dual-certification investments from foreign suppliers. Tianjin and Xi'an host clusters of polymer housing fabricators serving domestic transmission projects.
United States
FERC Order 1000 incentives favor turnkey substation contractors, compressing standalone arrester procurement channels. EPA and OSHA regulations govern manufacturing emissions and worker exposure in ceramic sintering operations. Texas and California concentrate renewable energy arrester demand from solar farms and offshore wind planning.
Germany
ECHA REACH Annex XVII restrictions on cadmium and lead in varistor formulations compel 18-month reformulation cycles for EU market entry. Testing houses in Berlin and Munich witness energy absorption validation for export-bound products. Bavaria's ceramics corridor supplies high-grade substrates to ABB and Siemens production networks.
India
Power Grid Corporation tenders specify 25-year service life for extra-high-voltage arresters across greenfield transmission corridors. CEA mandates incorporate lightning density data into arrester selection protocols, shifting specification authority toward utility engineering departments. Gujarat and Maharashtra host assembly partnerships with domestic transformer manufacturers.
Brazil
ANEEL biennial transmission auctions impose local content thresholds, creating entry points for arrester assembly joint ventures. National grid codes adopt IEC 60099-4 with Brazilian annexes for tropical pollution performance. São Paulo state concentrates demand from privatized distribution utilities modernizing urban substations.
Global Surge Arrester Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement frameworks that bundle arresters with switchgear and transformer packages. The vendor base clusters around three strategic archetypes: integrated electrical equipment conglomerates with captive arrester divisions, standalone surge protection specialists with deep certification expertise, and regional fabricators serving price-sensitive distribution markets. Dominant competitive moves include backward integration into ceramic disc production and geographic expansion through local assembly partnerships in markets with domestic content requirements.
Among Germany-based electrical equipment manufacturers, Siemens AG and DEHN SE occupy distinct positions within the competitive structure. Siemens AG exemplifies the vertically integrated conglomerate archetype with in-house production of ceramic substrates and polymer housings. DEHN SE represents the specialist player model with concentrated expertise in lightning and surge protection systems. Hitachi Energy Ltd, organized as a Japanese-structured energy technology company, anchors the hybrid design segment where monitoring electronics converge with traditional arrester housings. These three entities illustrate how competitive positioning fragments across integration depth versus specialization breadth.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Hitachi Energy Ltd |
| Eaton Corporation |
| Schneider Electric SE |
| Hubbell Incorporated |
| General Electric |
| DEHN SE |
| CG Power & Industrial Solutions Ltd |
| Others |
Cost & Logistics Intelligence
Bavaria's ceramics corridor anchors high-grade zinc oxide disc production, with sintering furnace capacity concentrated among German and Japanese equipment suppliers. This geographic chokepoint transmits upstream cost volatility directly into arrester pricing power, particularly for extra-high-voltage ratings where ceramic substrate quality determines performance margins.
Pricing Analysis
Cost-plus contracts with alumina price indexation dominate procurement between housing fabricators and utility buyers. Pricing stratifies across IEC-certified premium tiers, FERC-incentivized standard bundles, and price-sensitive distribution economy segments. Cost compression in porcelain-housed units is intensifying because bauxite mining volatility from Guinea and Australia feeds directly into alumina input costs. Distribution utilities exhibit the highest price sensitivity, while transmission grid operators prioritize 25-year service life specifications over unit cost.
Supply Chain Analysis
Supplier-financing structures including 180-day payment terms and supply-chain finance facilities have become standard for polymer housing procurement from Chinese fabricators. Sintering furnace capacity clusters in Germany, Japan, and China, with high-purity zinc oxide powder feeding from Australian and Peruvian mining operations. Single-source vulnerability runs through Japanese furnace manufacturers, where fewer than twelve laboratories worldwide can validate ultra-high-voltage energy absorption ratings. Distribution runs through EPC contractors bundling arresters into turnkey substation packages, particularly in markets where FERC Order 1000 or equivalent incentives apply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surge arrester market is entering a cyclical recovery phase as transmission infrastructure investment accelerates across China's State Grid Corporation and India's Power Grid Corporation procurement cycles.
For Market Incumbents: Insulate margin structures through captive ceramic disc production and IEC 60099-4 certification investments that emerging competitors cannot replicate quickly. State Grid Corporation's GB 11032 seismic requirements and India's CEA lightning density protocols are elevating specification barriers that favor established testing infrastructure. Backward integration into polymer housing extrusion reduces exposure to alumina price volatility. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANEEL transmission auctions where local content thresholds favor assembly joint ventures with domestic transformer manufacturers. The 5G base station DC protection segment remains underserved by utility-grade specialists, offering distinct specification requirements and lighter certification burdens. Partner with tower companies for polymer-housed low-voltage modules rather than competing directly for ultra-high-voltage tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid design specialists integrating IoT monitoring electronics directly into arrester housings, as condition-based maintenance contracts shift revenue toward predictive service models. Acquisition targets should demonstrate IEC-certified testing infrastructure spanning multiple continents or proprietary sintering furnace relationships. Watch for inflection signals in national grid code adoptions of lightning density data protocols, which transfer specification power toward utility engineering departments and away from component manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Disc Production | Siemens AG's captive sintering capacity insulates margin structures from Japanese furnace bottlenecks. |
| Hybrid Design with Embedded Monitoring Electronics | Hitachi Energy Ltd's sensor integration enables condition-based replacement contracts shifting revenue to services. |
| Local Assembly Partnership in Brazil | ANEEL's local content thresholds create protected market access for joint ventures with domestic transformer manufacturers. |
| REACH-Compliant Varistor Reformulation | German testing houses report 18-month qualification delays as suppliers iterate bismuth oxide dopant recipes. |
| Digital Monitoring Convergence Platform | IoT sensor integration for leakage current trending transforms hardware procurement into predictive maintenance subscriptions. |
Research Approach
A spread of perspectives from utility procurement officers, EPC contractor engineering leads, polymer housing fabricators, and ceramics R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against IEC certification databases, FERC Order 1000 implementation filings, and national grid code evolution tracking across China, India, Germany, and Brazil. Customs data on zinc oxide powder trade flows and sintering furnace import records provided cross-referenced demand indicators. Bottom-up unit deployment estimates triangulated against top-down transmission infrastructure investment forecasts.
Demand-supply balance modeling across the projection horizon incorporated technology migration rates from silicon carbide to metal oxide varistor, segmented by voltage rating tier and application criticality. The analytical framework modeled replacement cycle divergence between 5-year telecommunications turnover and 40-year transmission asset life, with CAGRs derived from utility capital expenditure trajectories and renewable energy interconnection queues. Forecast inputs included offshore wind collector system node counts, 5G base station electrification schedules, and seismic qualification protocol adoption patterns.
Stress conditions across alumina price volatility, sintering furnace capacity expansion, and REACH regulatory amendment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grid modernization mandate continuity and certification standard harmonization. Macroeconomic contraction, abrupt regulatory restriction, or breakthrough solid-state protection technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market