
 Energy Logistics Market | 2026-2036
Energy Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Logistics Market Analysis
ISO tank certification for hazardous energy cargoes is rotating toward higher safety and traceability standards across international corridors. C.H. Robinson leverages its digital freight platform to optimize multi-modal energy shipments across North American shale corridors. Deutsche Post DHL anchors European renewable energy logistics through specialized wind-turbine transport networks. Maersk Group dominates containerized LNG and biofuel shipping routes connecting Atlantic and Pacific basin producers.
Energy logistics encompasses the planning, execution, and control of physical flows for crude oil, natural gas, coal, and renewable energy infrastructure components, requiring temperature-controlled vessels, pressure-rated containers, and real-time cargo monitoring systems to prevent combustion risks and environmental release. The primary commercial purpose is matching intermittent supply from extraction sites and generation facilities with continuous demand from refineries, power grids, and industrial offtakers. Transportation services command the largest value pool given the specialized vessel and vehicle fleets required for hazardous and oversized cargoes, while management services are expanding fastest as energy traders seek algorithmic optimization of inventory positions and route selection. Renewable energy applications are displacing oil supply logistics in capital allocation as project developers commission offshore wind and solar installations requiring heavy-lift marine and modular road transport.
The U.S. Department of Transportation Pipeline and Hazardous Materials Safety Administration enforces strict packaging and routing rules for Class 3 flammable liquids and compressed gases, while the International Maritime Organization's IMDG Code governs oceanborne energy cargo segregation and stowage protocols. The EU Green Deal's Fit for 55 framework is mandating marine fuel sulfur reductions and shore power connectivity at European terminals, reshaping fleet investment schedules and port infrastructure plans. Stakeholders must monitor regulatory divergence between IMO carbon intensity indicators and regional emissions trading schemes to avoid compliance cost fragmentation across trade lanes.
Market Dynamics
The EU Green Deal's Fit for 55 framework is decomposing legacy fleet investment cycles across European energy corridors, forcing logistics operators to accelerate vessel retrofits and shore power connectivity before 2030 compliance deadlines bite.
Growth Catalysts
- Offshore wind installation surge:Renewable energy developers in Germany, Denmark, and the United States are commissioning heavy-lift marine transport for turbine nacelles and blade sets, pulling specialized vessel capacity from oilfield service markets.
- IMDG Code enforcement tightening:The International Maritime Organization's cargo segregation protocols are mandating real-time monitoring systems for LNG and biofuel container movements, expanding addressable market for integrated logistics technology.
- Shale corridor density:Permian and Bakken basin producers are consolidating drilling programs, creating predictable volume lanes that support dedicated crude-by-rail and sand logistics fleets with higher asset utilization.
Market Restraints
- Specialized vessel scarcity:The global fleet of temperature-controlled LNG carriers and pressure-rated ISO tank containers remains concentrated among a handful of Asian shipyards, constraining capacity expansion timelines.
- Marine fuel cost volatility:Low-sulfur fuel oil and methanol dual-fuel systems command premium pricing, compressing margins on spot charter rates for Atlantic and Pacific basin routes.
- Permitting fragmentation:The U.S. Department of Transportation's state-level routing variances for Class 3 flammable liquids create compliance friction for cross-border energy trucking networks.
Strategic Opportunities
- India renewable buildout:Solar park developers in Rajasthan and Gujarat are procuring modular road transport for photovoltaic panel arrays, opening greenfield logistics corridors without legacy oilfield infrastructure competition.
- EU F-Gas Regulation phase-down:Refrigerant transport and recovery logistics are emerging as mandated service categories under the fluorinated gas quota system, creating regulated demand pools.
- Digital freight platform convergence:Algorithmic cargo matching and blockchain-based custody documentation are merging to enable automated spot contracting for intermittent renewable energy component flows.
Industry Challenges
- Heavy-lift marine certification timelines:Wind turbine installation vessel crews face extended training periods for dynamic positioning systems and jack-up rig operations, constraining fleet expansion.
- Intermodal handoff coordination:Crude oil and LNG transfers between pipeline, rail, and vessel modes require precise custody transfer documentation to prevent contamination liability and customs delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Logistics Market |
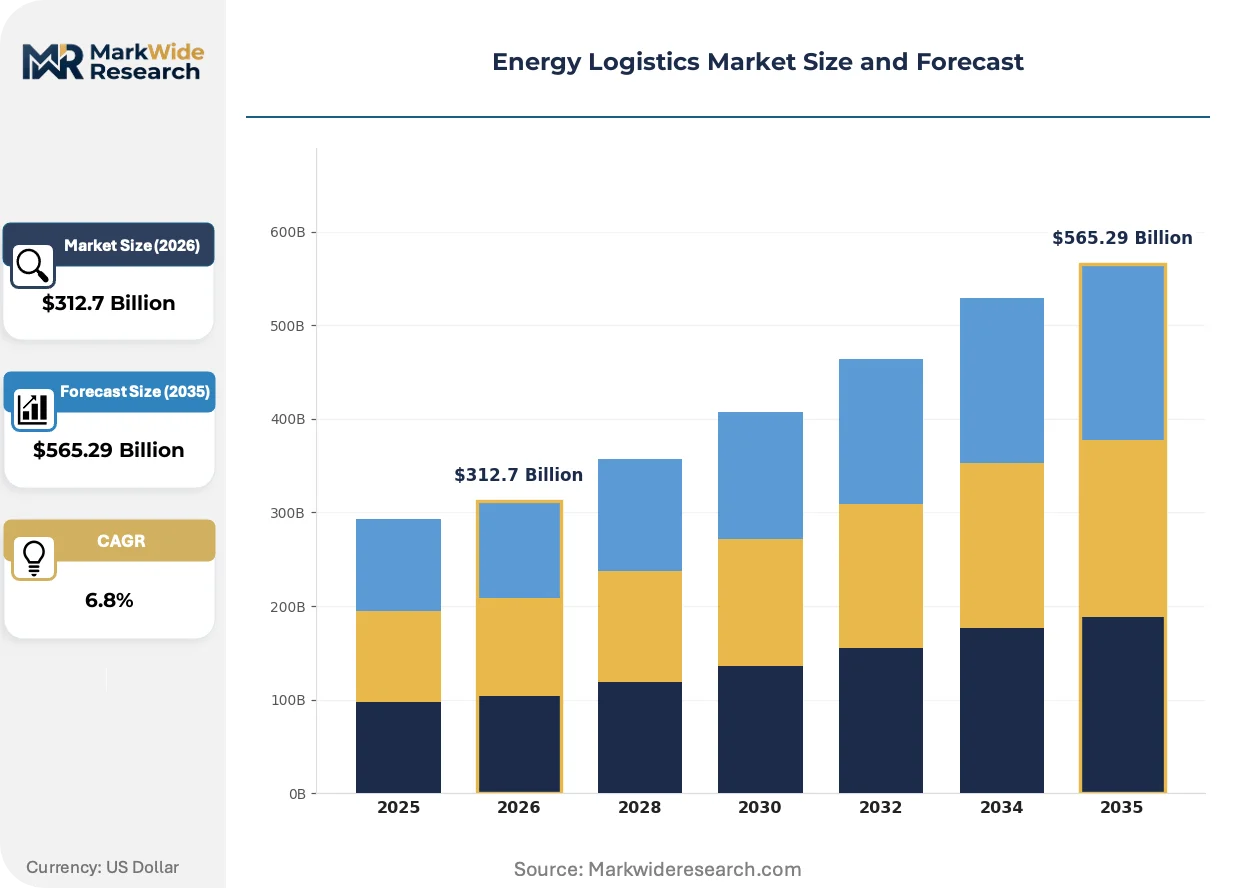
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Distribution, Management Application: Renewable Energy, Oil Supply, Gas Transportation, Coal Handling Installation: Onshore, Offshore, Terminal, Pipeline End User: Utilities, Energy Producers, Industrial Users, Commercial Enterprises |
| Companies Covered | C.H. Robinson, Kuehne + Nagel, Deutsche Post DHL, Geodis, United Parcel Service (UPS), Maersk Group, DSV, Panalpina, DB Schenker Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Logistics Market Emerging Trajectories
Digital freight platforms and autonomous cargo monitoring are compressing planning horizons for energy shippers, replacing monthly contract cycles with algorithmic spot-market participation that matches volatile production schedules to available vessel capacity.
Modular LNG containment systems using Type-C tank technology are decomposing the traditional project finance model for small-scale gas distribution. Remote mining operations and island power grids in Indonesia, the Philippines, and Caribbean territories are adopting standardized 40-foot ISO tank configurations rather than building permanent pipeline infrastructure. This tank standardization is collapsing the minimum viable project scale for gas monetization, opening markets previously stranded by capital intensity.
The EU Green Deal's FuelEU Maritime initiative is mandating well-to-wake greenhouse gas intensity reductions for vessels calling at European ports. Shipowners are responding with methanol dual-fuel engine retrofits and shore power installation programs at Rotterdam, Antwerp, and Hamburg terminals. The regulation is accelerating scrappage of older tonnage and redirecting newbuild investment toward alternative fuel-ready designs.
Energy traders are unbundling long-term logistics contracts into discrete voyage components, purchasing vessel capacity, port services, and last-mile trucking through separate spot transactions. This disaggregation is most advanced in North American crude oil markets where pipeline congestion at Cushing and Houston has normalized multi-modal routing. Trading desks now optimize inventory positions across rail, barge, and vessel legs rather than locking into single-mode annual agreements.
Energy Logistics Market Segmentation
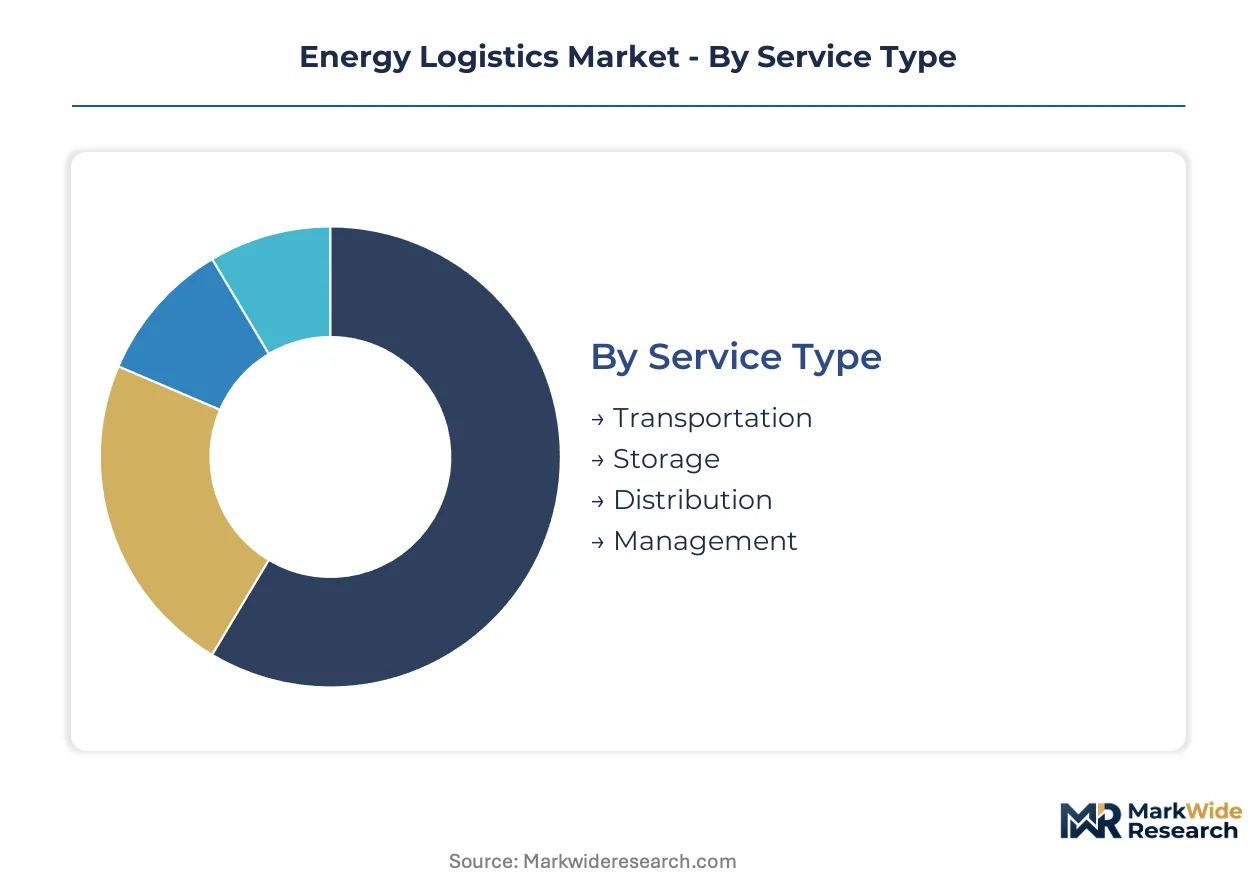
Energy logistics segmentation reveals how specialized infrastructure requirements fragment procurement patterns across fuel types and installation environments. Service providers must match vessel certifications, container specifications, and routing protocols to distinct cargo hazards and dimensional constraints.
Service Type:
Domestic corridors favor storage and distribution assets anchored to fixed infrastructure, while export-led flows concentrate in transportation and management services requiring multi-modal orchestration.
- Transportation:Temperature-controlled vessels and pressure-rated ISO tank containers move LNG, biofuels, and crude across marine, rail, and road legs. German wind turbine nacelles and Permian crude volumes pull specialized heavy-lift and tanker capacity from spot markets.
- Management:Algorithmic cargo matching and real-time fleet positioning optimize inventory across intermittent renewable component flows and volatile shale production schedules. Digital platforms are compressing contract cycles from annual terms to voyage-specific spot transactions.
- Storage:Underground caverns and floating regasification units buffer seasonal demand swings for natural gas utilities.
- Distribution:Last-mile trucking networks and coastal bunker barge fleets complete delivery to refineries, power plants, and industrial offtakers.
Transportation commands the established base. The steepest expansion runs through Management.
Application:
Cost tier separation is pronounced: renewable energy logistics carry premium pricing for oversized components, while fossil fuel handling competes on volume scale and route efficiency.
- Renewable Energy:Offshore wind installation vessels with dynamic positioning systems transport turbine blades and tower sections from manufacturing clusters in Denmark and Germany to North Sea lease areas. Heavy-lift marine certification bottlenecks constrain fleet expansion timelines.
- Oil Supply:Crude-by-rail networks from the Permian and Bakken basins feed Gulf Coast refineries when pipeline capacity saturates. Cushing storage hub congestion normalizes multi-modal routing through Houston and Corpus Christi marine terminals.
- Gas Transportation:Small-scale LNG ISO tank units serve remote mining and island power grids in Indonesia and the Caribbean without permanent pipeline investment.
- Coal Handling:Dedicated bulk carrier fleets and river barge networks link Powder River Basin mines to Midwest power plants.
Renewable Energy is climbing the fastest as capital allocation shifts from hydrocarbon extraction to infrastructure buildouts.
Installation:
Volume concentration tilts toward onshore and terminal assets given their replication across multiple corridors, while offshore and pipeline installations serve point-to-point dedicated flows.
- Onshore:Modular road transport for photovoltaic arrays and wind turbine components traverses Rajasthan solar parks and Texas wind farms. Standardized trailer configurations reduce per-unit logistics costs for gigawatt-scale renewable deployments.
- Offshore:Jack-up installation vessels and dynamic positioning heavy-lift ships position turbine foundations and substation platforms in German and Danish lease areas. Crew certification requirements for these specialized assets extend fleet delivery timelines.
- Terminal:Rotterdam, Antwerp, and Hamburg marine terminals are retrofitting shore power connectivity under EU Green Deal mandates.
- Pipeline:Crude and natural gas trunk lines offer lowest unit cost for high-volume, predictable flows between fixed points.
Onshore commands the established base. The steepest expansion runs through Offshore.
End User:
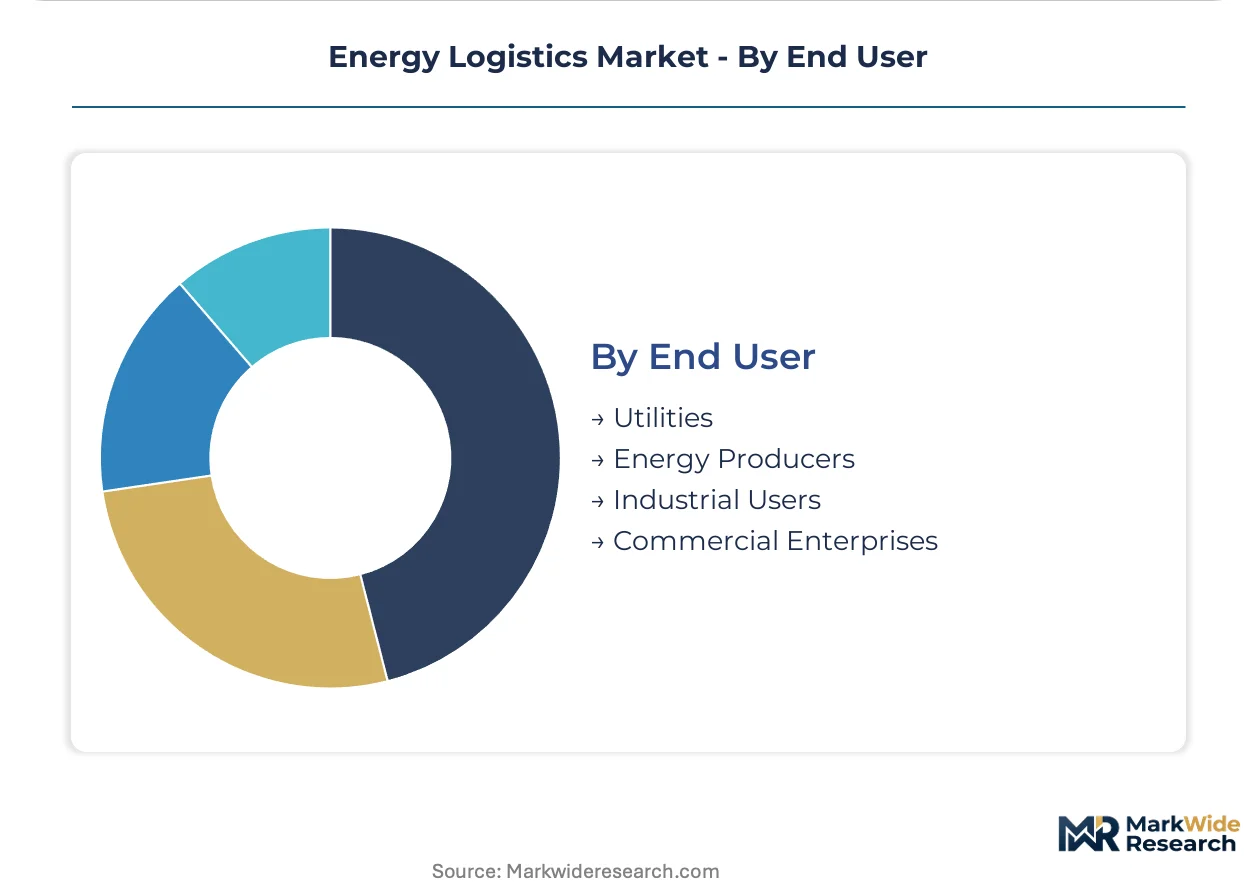
Customer type determines contracting structure: utilities and energy producers favor long-term dedicated capacity, while industrial and commercial offtakers purchase logistics services through spot markets or third-party aggregators.
- Utilities:Electric power generators procure firm transportation and storage capacity to meet renewable portfolio standards and peak demand obligations. German utilities anchor long-term contracts for offshore wind installation vessel fleets.
- Energy Producers:Oil and gas extraction companies manage upstream-to-midstream handoffs through integrated logistics subsidiaries or third-party providers. Permian shale operators consolidate drilling programs to create predictable volume lanes for dedicated sand and crude logistics fleets.
- Industrial Users:Petrochemical and steel manufacturers purchase LNG and coal logistics through annual tenders with price escalation clauses.
- Commercial Enterprises:Data centers and retail chains source renewable energy certificates with associated logistics documentation for Scope 3 emissions reporting.
Utilities command the established base. The steepest expansion runs through Energy Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping energy logistics corridors as Atlantic basin LNG oversupply seeks Asian offtake and North Sea offshore wind components flow to installation sites. Capital deployment concentrates where regulatory clarity meets infrastructure buildout timelines.
United States
Permian shale consolidation and Gulf Coast LNG export terminal expansions are pulling specialized crude-by-rail and cryogenic vessel capacity. The Department of Transportation's Class 3 flammable liquid routing rules enforce state-level compliance variations. Houston and Corpus Christi marine terminals handle multi-modal handoffs when Cushing storage congestion redirects flows.
Germany
Offshore wind lease auctions in the North Sea and Baltic are commissioning heavy-lift installation vessels for turbine nacelles manufactured in Bremerhaven and Cuxhaven. The EU Green Deal's Fit for 55 framework mandates shore power connectivity at Hamburg and Wilhelmshaven terminals by 2030. Rostock port clusters are retrofitting vessel electrical infrastructure ahead of regulatory deadlines.
India
Rajasthan and Gujarat solar park developers are procuring modular road transport for photovoltaic arrays at gigawatt scale. The Central Electricity Authority's renewable purchase obligations enforce utility offtake commitments. Mundra and Hazira port complexes are expanding heavy-lift handling capacity for wind turbine component imports.
China
Yangtze River Delta shipyards dominate global production of LNG carriers and pressure-rated ISO tank containers. The Ministry of Ecology and Environment's dual carbon goals are accelerating methanol dual-fuel vessel orders. Ningbo-Zhoushan port authorities are installing shore power systems for international compliance.
United Arab Emirates
ADNOC's crude export expansion and downstream petrochemical integration are demanding dedicated VLCC and chemical tanker logistics. The country's national petroleum regulator enforces cargo segregation protocols for hazardous materials. Jebel Ali port free zones are attracting third-party logistics providers for regional energy trading hubs.
Energy Logistics Market Vendor Landscape
Concentration sits with integrated multi-modal operators and specialized renewable energy logistics providers. The market structure fragments between global freight forwarders with energy-dedicated divisions and regional heavy-lift marine specialists. Three archetypes dominate: digital platform orchestrators, asset-heavy vessel operators, and project logistics specialists. Competitive moves center on fleet decarbonization partnerships and algorithmic cargo-matching technology licensing.
Among integrated logistics providers, C.H. Robinson, Deutsche Post DHL, and Maersk Group represent distinct strategic positions. C.H. Robinson exemplifies the digital freight platform archetype, occupying a position as a technology-enabled intermediary without owned vessel assets. Deutsche Post DHL anchors the European renewable energy logistics segment through specialized wind-turbine transport networks. Maersk Group sits within the asset-heavy containerized energy shipping tier, dominating Atlantic and Pacific basin LNG and biofuel routes.
| Leading Market Players |
|---|
| C.H. Robinson |
| Kuehne + Nagel |
| Deutsche Post DHL |
| Geodis |
| United Parcel Service (UPS) |
| Maersk Group |
| DSV |
| Panalpina |
| DB Schenker Logistics |
| Others |
Supply Flow & Price Mechanics
ISO tank certification regimes for hazardous energy cargoes gate both supplier qualification and price tiering simultaneously, forcing logistics operators to absorb compliance costs upfront while passing premium pricing to buyers requiring real-time cargo monitoring and blockchain custody documentation.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in energy logistics procurement. Premium tiers command rates for IMDG Code-certified vessels with dynamic positioning systems and jack-up rig capabilities, while standard pricing covers conventional crude-by-rail and ISO tank container movements. Cost compression in the economy tier is intensifying because methanol dual-fuel retrofits and shore power infrastructure amortization are squeezing spot charter margins. Utilities with renewable portfolio standard obligations show least price sensitivity, whereas commercial enterprises purchasing logistics for Scope 3 emissions documentation exhibit highest price elasticity.
Supply Chain Analysis
Strait of Hormuz transit underwrites crude oil logistics cost structures for Atlantic basin refineries sourcing Middle Eastern grades. Manufacturing concentration for LNG carriers and pressure-rated ISO tank containers centers on China, South Korea, and Japan, with Yangtze River Delta shipyards feeding global fleet expansion. Raw material inputs draw from specialized steel alloys for cryogenic containment, marine engine components for dual-fuel systems, and composite materials for wind turbine blade fabrication. Single-source vulnerability runs through Asian shipyard capacity allocation for specialized heavy-lift installation vessels. Distribution runs through Rotterdam, Houston, and Singapore hub terminals with multi-modal handoff capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German utilities and Permian shale consolidators, compressing logistics provider margins through long-term dedicated capacity contracting and algorithmic spot-market arbitrage.
For Market Incumbents: Consolidate heavy-lift marine certification pipelines through crew training partnerships with German and Danish maritime academies to preempt vessel delivery bottlenecks. Anchor digital freight platform licensing revenue streams before commodity traders complete in-house algorithmic cargo-matching development. Capacity addition in Indian modular road transport corridors defends position against emerging regional specialists capturing Rajasthan solar park logistics procurement. For New Entrants and Emerging Players: Fast-track IMO IMDG Code certification for LNG and biofuel container movements to capture regulated demand pools opening under enforcement tightening. White-space targets include EU F-Gas Regulation-mandated refrigerant transport and recovery logistics, plus small-scale LNG ISO tank distribution for Indonesian and Caribbean island power grids. Target India renewable buildout corridors with photovoltaic array modular transport services, positioning through joint ventures with established port operators at Mundra and Hazira. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital freight platform specialists lacking owned vessel networks, presenting roll-up opportunities for integrated multi-modal operators. Long-term viability across the analysis window favors asset-heavy vessel operators with alternative fuel-ready newbuild orderbooks and shore power terminal partnerships. Acquisition target archetype: regional heavy-lift marine specialists holding dynamic positioning system certifications for North Sea offshore wind installation. Signal to watch: EU Green Deal compliance deadline acceleration forcing distressed vessel retrofit capex needs.| Strategic Initiative | Industry Significance |
|---|---|
| Methanol Dual-Fuel Retrofit Program | EU Green Deal's FuelEU Maritime mandates well-to-wake intensity reductions at Rotterdam, Antwerp, and Hamburg terminals. |
| Algorithmic Cargo-Matching Platform | Energy traders at C.H. Robinson and DSV unbundle long-term contracts into voyage-specific spot transactions for crude optimization. |
| Heavy-Lift Vessel Certification Pipeline | German offshore wind lease auctions pull jack-up installation capacity from oilfield service markets through crew training bottlenecks. |
| Modular LNG Containment Standardization | Type-C tank ISO configurations collapse minimum viable project scale for Indonesian and Caribbean stranded gas monetization. |
| Shore Power Terminal Infrastructure | Hamburg and Wilhelmshaven retrofit programs under Fit for 55 framework redirect fleet investment toward electrical connectivity. |
Methodological Framework
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EIA data, IEA reports, FERC filings, and project development databases tracking renewable energy infrastructure buildouts. Bottom-up segmentation modeling across service type, application, installation environment, and end-user category triangulated with top-down macroeconomic indicators to establish volume and value baselines.
Sensitivity analysis frameworks tested forecast robustness across regulatory acceleration scenarios, alternative fuel adoption curves, and vessel capacity delivery delays. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the projection horizon. CAGRs were derived from fitted growth curves applied to disclosed capital expenditure pipelines and announced infrastructure commissioning schedules. Industry-specific forecast inputs incorporated EU Green Deal compliance deadline phasing and Permian shale drilling program consolidation patterns.
Underlying assumptions cover continued regulatory enforcement of IMO carbon intensity indicators and EU emissions trading scheme convergence, with deviation risk concentrated in marine fuel cost volatility and specialized vessel delivery timeline slippage. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and India renewable purchase obligation enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market