
 United States LNG Infrastructure Market | 2026-2036
United States LNG Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
United States LNG Infrastructure Market Analytics
Utility buyers is collapsing as the dominant procurement archetype while industrial manufacturers and export traders gain share in offtake negotiations. Cheniere Energy anchors the Gulf Coast liquefaction corridor through its Corpus Christi and Sabine Pass complexes. Bechtel Corporation dominates EPC contracting for large-scale liquefaction trains, leveraging decades of modular construction expertise. Sempra Energy competes through its Cameron LNG and proposed Port Arthur developments, sustaining a portfolio weighted toward Pacific Basin export markets.
United States LNG infrastructure encompasses the physical systems required to supercool natural gas to minus 162 degrees Celsius for liquid transport, then regasify it for pipeline injection or direct end-use consumption. Cryogenic heat exchangers and multi-stage compression trains enable liquefaction at scale, with single trains now exceeding five million tonnes per annum of nameplate capacity. Liquefaction terminals command the largest capital allocation and longest construction timelines, while storage tanks represent a mature segment where margin pools have compressed due to standardized designs and repeat builder competition. Regasification terminals face structural headwinds domestically as the US remains a net exporter, though Gulf Coast import capacity retains strategic value for supply flexibility during extreme weather events.
FERC maintains jurisdiction over interstate LNG facility siting and certificate issuance, while EPA reviews air quality permits under the Clean Air Act for major source emissions from liquefaction combustion turbines. DOT PHMSA regulates LNG transport safety through 49 CFR Part 193, shaping tank design standards and facility spacing requirements that directly impact land acquisition costs. OSHA process safety management rules apply to cryogenic handling operations, mandating hazard analysis protocols that influence operator staffing and training expenditures. Stakeholders must monitor how evolving methane emissions accounting under EPA greenhouse gas reporting protocols reshapes project finance terms and offtake contract structures.
Market Dynamics
European utility offtake commitments are compressing Gulf Coast project financing timelines while FERC certificate streamlining under NEPA reforms accelerates brownfield expansion approvals along the Texas-Louisiana corridor.
Growth Catalysts
- European energy security mandates:EU diversification policies from Russian pipeline gas are pulling long-term contract volumes toward US Gulf terminals, anchoring project finance.
- Modular liquefaction trains:Standardized cryogenic heat exchanger packages are cutting construction schedules and enabling phased capacity additions at existing sites.
- Brownfield site availability:Decommissioned import terminals and industrial brownfields in Texas and Louisiana offer permitted footprints with existing marine access.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for cryogenic service face sourcing bottlenecks from limited qualified foundries, inflating heat exchanger lead times.
- FERC environmental litigation exposure:Certificate approvals remain vulnerable to judicial review under the National Environmental Policy Act, extending pre-construction timelines unpredictably.
- Electrification substitution:Grid-scale battery storage and renewable hydrogen pilots are capturing utility capex allocations that previously flowed to gas-fired generation infrastructure.
Strategic Opportunities
- Carbon capture integration:Section 45Q tax credits under the Inflation Reduction Act are incentivizing post-combustion capture retrofits at existing liquefaction facilities.
- Small-scale bunkering infrastructure:IMO 2020 marine fuel sulfur regulations are opening portside LNG loading demand along the Mississippi River and Atlantic seaboard.
- Digital twin deployment:Real-time cryogenic process modeling combined with predictive maintenance analytics is reducing unplanned train outages and optimizing refrigerant cycles.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified 9% nickel steel welders and ASME Section VIII inspectors command premium wages, constraining construction crew scaling.
- Integrated control system complexity:Harmonizing distributed control systems from multiple vendors across liquefaction, storage, and marine loading creates commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States LNG Infrastructure Market |
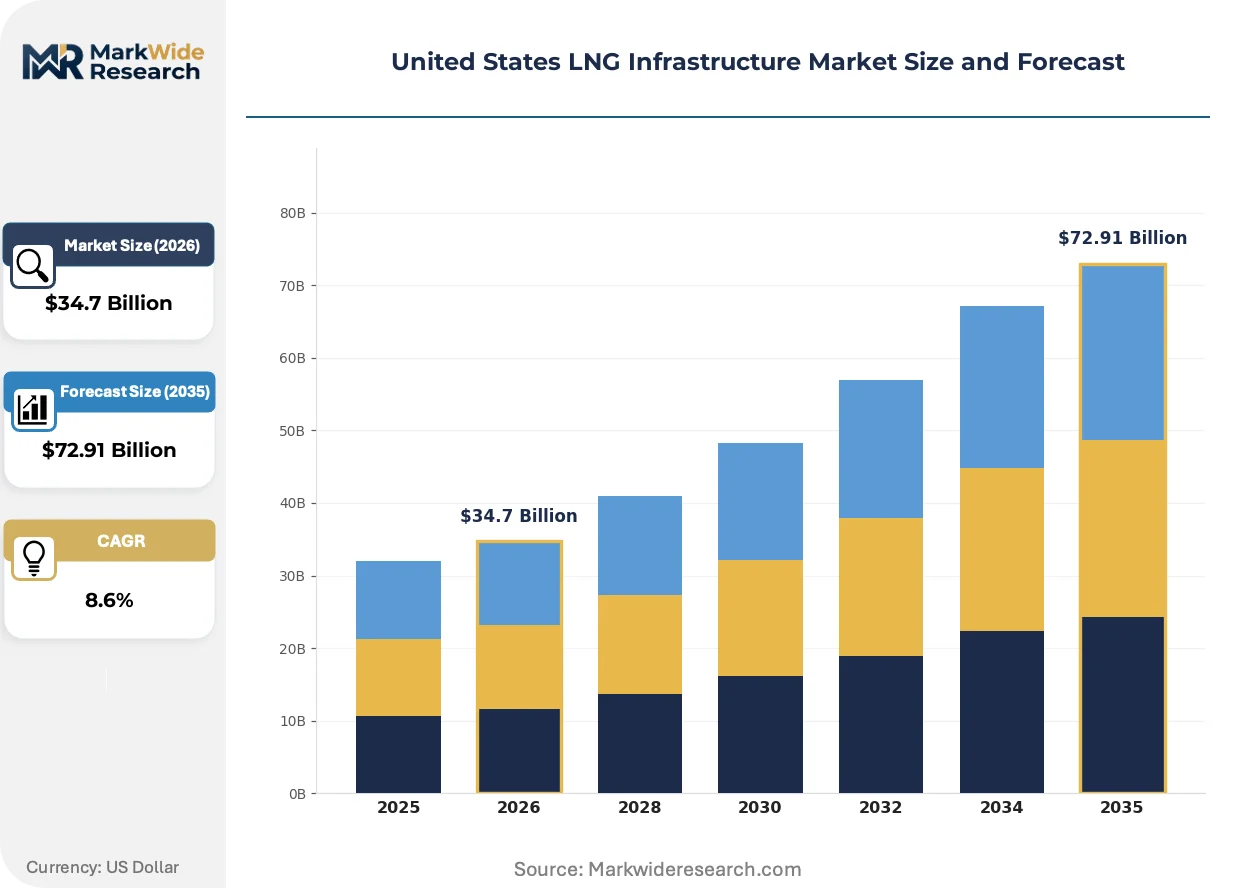
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquefaction Terminals, Regasification Terminals, Storage Tanks, Transportation Vessels Technology: Cryogenic Process, Ambient Temperature Process, Turboexpander Process, Hybrid Systems Application: Power Generation, Industrial Usage, Export Supply, Domestic Supply End User: Utilities, Industrial Manufacturers, Government Entities, Commercial Enterprises |
| Companies Covered | Chiyoda Corporation, Bechtel Corporation, McDermott International Inc, Sempra Energy, Cheniere Energy Inc., Dominion Energy Inc., TotalEnergies, Mitsubishi Corporation, Technip Energies N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States LNG Infrastructure Market Evolving Landscape
Modular construction methodologies and digital process control architectures are compressing project delivery schedules while reshaping operator competency requirements across the Gulf Coast development corridor.
Air-cooled liquefaction technology is miniaturizing cooling water infrastructure footprints at brownfield sites where freshwater access is constrained. Coastal Texas developers are adopting closed-loop dry cooling systems to eliminate thermal discharge permitting conflicts. This configuration is miniaturizing environmental review timelines and enabling project siting closer to existing pipeline interconnections.
EPA greenhouse gas reporting protocols under Subpart W are tightening methane leak detection and repair mandates for compressor stations and storage tanks. Liquefaction terminal operators are deploying continuous emissions monitoring systems to satisfy evolving EPA enforcement thresholds. Gulf Coast facilities face the steepest compliance cost escalations due to concentration of large-source refrigeration compressors.
Industrial manufacturers are displacing utilities as anchor offtakers through direct contracting with liquefaction terminals for process heat and power generation. Chemical producers in the Houston Ship Channel and Beaumont-Port Arthur refining complex are negotiating volume commitments that bypass traditional utility intermediaries. This pattern concentrates most intensely among ammonia and methanol producers seeking feedstock cost certainty.
United States LNG Infrastructure Market Segmentation
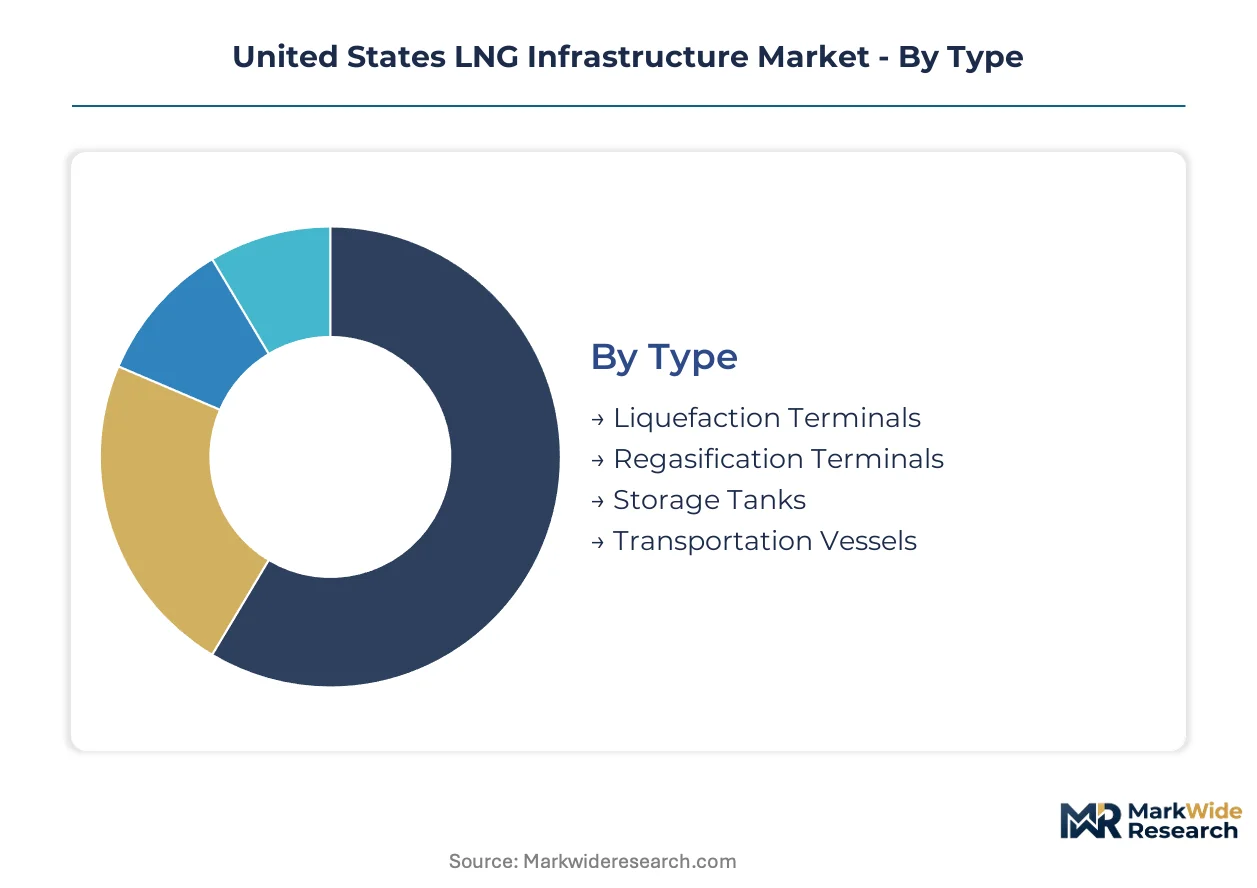
Segmentation across the United States LNG infrastructure market reveals how regulatory jurisdiction, technology maturity, and customer procurement patterns allocate capital across the value chain. FERC certificate requirements and EPA air quality permits create divergent compliance burdens that reshape competitive positioning by segment.
Type:
FERC maintains distinct certificate pathways for greenfield liquefaction versus brownfield expansions, compressing approval timelines for terminal categories with existing environmental baselines.
- Liquefaction Terminals:Cryogenic heat exchangers and multi-stage compression trains supercool natural gas to minus 162 degrees Celsius at single-train capacities exceeding five million tonnes per annum. Gulf Coast brownfield expansions in Texas and Louisiana dominate new capacity additions, anchored by European utility offtake contracts securing project finance.
- Regasification Terminals:Import infrastructure retains strategic value for supply flexibility during extreme weather events despite structural headwinds from persistent US net export status. Gulf Coast facilities face lower utilization rates than liquefaction counterparts, though coastal Texas sites maintain operational readiness for demand spikes.
- Storage Tanks:Standardized double-wall cryogenic designs with 9% nickel steel inner shells face margin compression from repeat builder competition.
- Transportation Vessels:DOT PHMSA regulations under 49 CFR Part 193 govern tank design standards and facility spacing requirements shaping fleet deployment economics.
Liquefaction terminals handle the majority of throughput; storage tanks are expanding most quickly on share through modular tank additions at existing sites.
Technology:
Cost tiers separate established cryogenic process dominance from emerging ambient temperature alternatives targeting constrained freshwater access.
- Cryogenic Process:Multi-stage refrigeration cycles using propane, ethylene, and methane precooling dominate large-scale Gulf Coast trains. Bechtel Corporation and licensors Air Products and Chart Industries anchor technology deployment across the Sabine Pass and Corpus Christi corridors.
- Ambient Temperature Process:Closed-loop dry cooling systems eliminate thermal discharge permitting conflicts at brownfield Texas sites where freshwater constraints block conventional cooling tower construction. This configuration miniaturizes environmental review timelines and enables siting closer to existing pipeline interconnections.
- Turboexpander Process:Pressure letdown systems recover refrigeration work in pipeline gas processing applications.
- Hybrid Systems:Integrated configurations combine cryogenic and ambient cooling stages for load-following flexibility.
Cryogenic process technology commands the dominant share of installed capacity; ambient temperature systems are gaining share fastest in brownfield expansions.
Application:
Customer procurement patterns concentrate volume commitments by end-use sector, with industrial direct contracting displacing traditional utility intermediation.
- Export Supply:Long-term offtake agreements from European utilities anchor Gulf Coast liquefaction project finance under EU energy security diversification mandates. Contract structures now incorporate destination flexibility clauses and carbon intensity benchmarks reshaping terminal design specifications.
- Industrial Usage:Ammonia and methanol producers in the Houston Ship Channel and Beaumont-Port Arthur refining complex negotiate direct volume commitments bypassing utility intermediaries. Process heat and power generation requirements drive feedstock cost certainty demands in chemical manufacturing.
- Power Generation:Combined-cycle gas turbine plants face electrification substitution from grid-scale battery storage capturing utility capex allocations.
- Domestic Supply:Pipeline injection for residential and commercial heating maintains baseline demand in Northeast and Midwest markets.
Export supply handles the majority of throughput; industrial usage is climbing the fastest on volume share through direct terminal contracting.
End User:
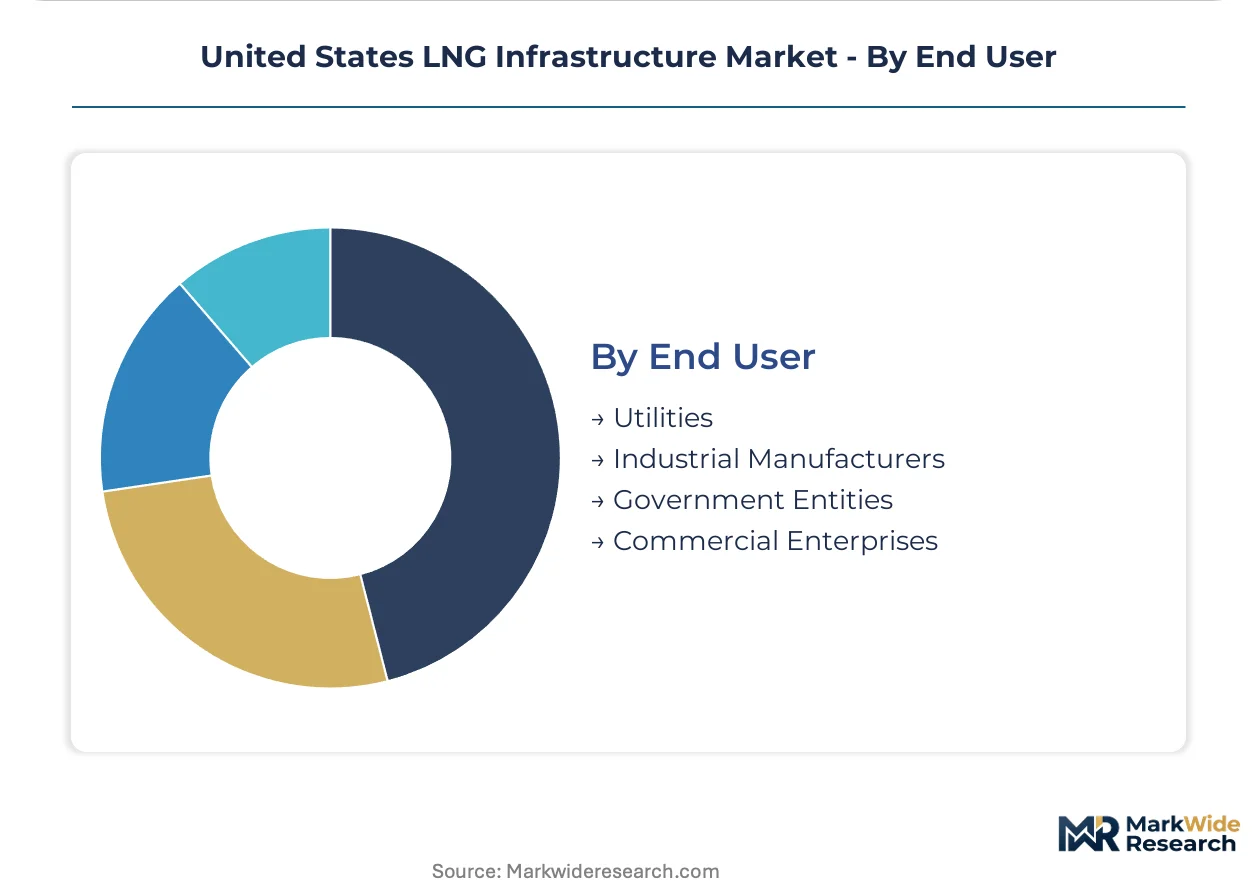
Procurement authority is shifting across customer categories as industrial manufacturers displace utilities in anchor offtake negotiations.
- Utilities:Traditional procurement dominance is compressing as European buyers concentrate contracting authority at holding company level rather than individual utility subsidiaries. FERC rate case proceedings and state public utility commission oversight shape long-term capacity reservation strategies.
- Industrial Manufacturers:Chemical producers, refiners, and fertilizer operators are gaining share in offtake negotiations through direct liquefaction terminal contracting. Methanol and ammonia production facilities in Texas and Louisiana drive feedstock cost hedging requirements.
- Government Entities:Strategic petroleum reserve coordination and defense fuel supply contracts maintain reserved capacity at select Gulf Coast facilities.
- Commercial Enterprises:Marine bunkering operators and remote power developers represent emerging demand clusters along inland waterway corridors.
Utilities retain the dominant share of contracted volume; industrial manufacturers are gaining share fastest through direct procurement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sabine Pass-Neches Waterway anchors Gulf Coast liquefaction capacity, connecting Texas and Louisiana brownfield sites to deepwater shipping lanes serving European utility buyers.
Texas Gulf Coast
Corpus Christi liquefaction trains and Port Arthur expansion proposals concentrate European offtake contracting under FERC certificate pathways. EPA Clean Air Act permitting for combustion turbine emissions shapes project timelines at coastal sites. Houston Ship Channel chemical manufacturers negotiate direct feedstock agreements bypassing traditional utility intermediaries.
Louisiana Gulf Coast
Sabine Pass brownfield expansions dominate nameplate capacity additions through modular train deployment. FERC streamlined environmental reviews compress approval schedules for sites with existing marine infrastructure. Lake Charles and Cameron Parish facilities anchor Pacific Basin export contracting through Sempra Energy portfolio developments.
California
West Coast LNG demand concentrates on marine bunkering applications under CARB maritime emissions regulations. No new liquefaction capacity is proposed; existing import terminals retain strategic value for supply flexibility. Los Angeles-Long Beach port complexes pilot shoreside LNG loading for IMO 2020-compliant vessel fueling.
Alaska
North Slope gas reserves await tidewater liquefaction infrastructure to unlock Asian market access. State of Alaska tax credit programs under AS 43.55.028 incentivize project development studies. Nikiski on Cook Inlet hosts the state's sole existing liquefaction facility, constrained by pipeline capacity to producing fields.
Northeast Corridor
Regasification terminals at Everett, Massachusetts and Cove Point, Maryland maintain operational readiness for winter demand spikes. FERC interstate pipeline certificate requirements limit new infrastructure penetration into constrained New England markets. Boston-area utilities rely on LNG cargoes during pipeline capacity constraints from Appalachian supply basins.
United States LNG Infrastructure Market Competitive Landscape
Listed leaders compete with private specialists across capital deployment scale, with publicly traded energy majors commanding project finance access while private EPC contractors capture construction execution premiums. The market structure concentrates around integrated liquefaction developers, specialized engineering constructors, and utility-backed offtake aggregators. Three archetypes dominate: Gulf Coast terminal operators with brownfield expansion rights, global EPC firms with modular cryogenic expertise, and diversified energy majors with integrated trading desks. Competitive dynamics center on FERC certificate acquisition speed and long-term contract destination flexibility clauses.
Within the integrated developer tier, Cheniere Energy exemplifies pure-play liquefaction strategy through Corpus Christi and Sabine Pass complex ownership. Bechtel Corporation anchors EPC contracting capacity with decades of modular construction methodology deployment. Sempra Energy occupies a position bridging utility-backed development with Pacific Basin market orientation through Cameron LNG and proposed Port Arthur facilities.
| Leading Market Players |
|---|
| Chiyoda Corporation |
| Bechtel Corporation |
| McDermott International Inc |
| Sempra Energy |
| Cheniere Energy Inc. |
| Dominion Energy Inc. |
| TotalEnergies |
| Mitsubishi Corporation |
| Technip Energies N.V. |
| Others |
Value Network & Pricing Analysis
FERC certificate scarcity and EPA air quality permitting tiers simultaneously gate supplier qualification and stratify terminal construction costs across the Gulf Coast corridor. Buyers face price spreads between brownfield expansion slots and greenfield development timelines that reflect these regulatory access differentials.
Pricing Analysis
Contract-based long-term offtake structures dominate, with volume-discount tiering separating anchor utility commitments from industrial direct procurement. Price differentiation rests on FERC approval status and destination flexibility clauses, with certified brownfield slots commanding premiums. Cost compression in standard liquefaction train packages is intensifying because modular construction competition among EPC contractors is standardizing cryogenic heat exchanger designs. European utilities exhibit lowest price sensitivity due to energy security mandates, while domestic industrial manufacturers negotiate aggressively on feedstock cost certainty.
Supply Chain Analysis
Strategic stockpiling of nickel-based superalloys and 9% nickel steel dominates over just-in-timematerials procurement given foundry lead time volatility. Supply concentrates in Japan, South Korea, and Germany for cryogenic heat exchanger fabrication, while domestic steel mills anchor storage tank construction. The chain draws from specialized alloy feedstock, ASME-certified pressure vessel components, and marine loading arm systems. Single-source vulnerability in qualified cryogenic welding certification pools constrains crew scaling. Distribution runs through EPC contractor networks with Bechtel Corporation and Technip Energies N.V. anchoring large-scale project execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial direct contracting is fragmenting procurement authority away from consolidated utility buyers, creating specialized niches for mid-scale liquefaction developers and modular technology suppliers.
For Market Incumbents: Compound brownfield expansion rights through FERC certificate acquisition speed at existing Gulf Coast sites. Secure captive supply of nickel-based superalloy heat exchanger capacity through backward integration into qualified foundry partnerships. Electrification substitution in power generation and carbon intensity benchmarking in European offtake contracts threaten legacy project returns. For New Entrants and Emerging Players: Anchor in small-scale bunkering infrastructure along the Mississippi River and Atlantic seaboard where IMO 2020 marine fuel regulations are opening portside demand clusters. Target carbon capture integration retrofits at existing liquefaction facilities leveraging Section 45Q tax credit economics. Pursue digital twin deployment partnerships with established terminal operators as a service-based entry vector. For Investors and Strategic Acquirers: FERC streamlined environmental review implementation reshapes the acquisition landscape toward brownfield expansion rights over greenfield development portfolios. Five-to-ten year viability favors integrated developers with contracted offtake backlogs and Pacific Basin market access. Monitor EPA methane emissions enforcement thresholds as the signal indicating regulatory cost escalation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Capacity Expansion | FERC certificate streamlining at existing Texas and Louisiana sites compresses approval timelines versus greenfield alternatives. |
| Carbon Capture Retrofit Integration | Section 45Q tax credits under the Inflation Reduction Act incentivize post-combustion capture at liquefaction facilities. |
| Small-Scale Bunkering Infrastructure | IMO 2020 marine sulfur regulations open portside LNG loading demand along inland waterway corridors. |
| Digital Twin Deployment | Real-time cryogenic process modeling reduces unplanned train outages at Gulf Coast liquefaction complexes. |
| Direct Industrial Contracting | Ammonia and methanol producers in the Houston Ship Channel bypass utility intermediaries for feedstock certainty. |
Research Methodology
Cross-validation between FERC certificate filing databases and EPA Clean Air Act permit records anchors the qualitative findings on project timeline compression. Primary interviews with liquefaction terminal developers, EPC project managers, utility fuel procurement officers, and European offtake contract negotiators combined with secondary validation from EIA production data, IEA market reports, and SEC 10-K infrastructure disclosures. Bottom-up capacity addition modeling and top-down European demand aggregation triangulate volume estimates.
Sensitivity analysis across the projection horizon tests FERC approval rate scenarios and European utility contracting velocity assumptions. Segmentation dimensions modeled include facility type, cryogenic versus ambient cooling technology, export versus industrial application, and end-user procurement authority. CAGRs derive from capacity-weighted average construction timelines and nameplate utilization assumptions. Forecast inputs incorporate nickel alloy price volatility and methane emissions compliance cost trajectories.
Material uncertainties — FERC litigation exposure under NEPA, European pipeline gas supply normalization, and electrification substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions on offtake contract tenor and destination flexibility prevalence. Revision becomes warranted when EPA greenhouse gas reporting threshold stringency crosses enforcement escalation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Energy Cable Market