
 In-Circuit Test Market | 2026-2036
In-Circuit Test Market Size, Share, and Industry Trends Forecast 2026-2036
In-Circuit Test Market Intelligence
Aftermarket service revenue is reconfiguring profit pools across the In-Circuit Test landscape as capital equipment buyers prioritize uptime contracts over outright purchases. Teradyne Inc. leverages its installed base in North America to lock in multi-year service agreements. Keysight Technologies anchors its position through calibration and firmware update subscriptions. SPEA S.p.A. competes in European automotive electronics with localized technical support centers.
In-circuit test systems electrically verify populated printed circuit boards by probing individual component connections with test access points as small as 0.3 mm pitch, detecting solder defects, wrong components, and parametric drift before functional assembly. Flying probe testers lead product type adoption for low-to-medium volume production where fixture costs prove prohibitive. Mixed signal testing captures the fastest technology growth as analog-digital integration intensifies in medical devices and telecommunications hardware. Bed of nails testers retain dominance in high-volume consumer electronics where dedicated fixtures amortize across millions of units.
FCC equipment authorization rules in the United States mandate electromagnetic compatibility pre-testing that ICT systems increasingly integrate. ECHA REACH restrictions on hazardous substances in Europe compel manufacturers to verify lead-free and halogen-free solder joint integrity at the board level. FDA quality system regulation for medical devices requires traceable electrical test records that automated ICT platforms generate. Stakeholders must weigh capital deployment between fixture-based throughput and probe flexibility as product lifecycles compress.
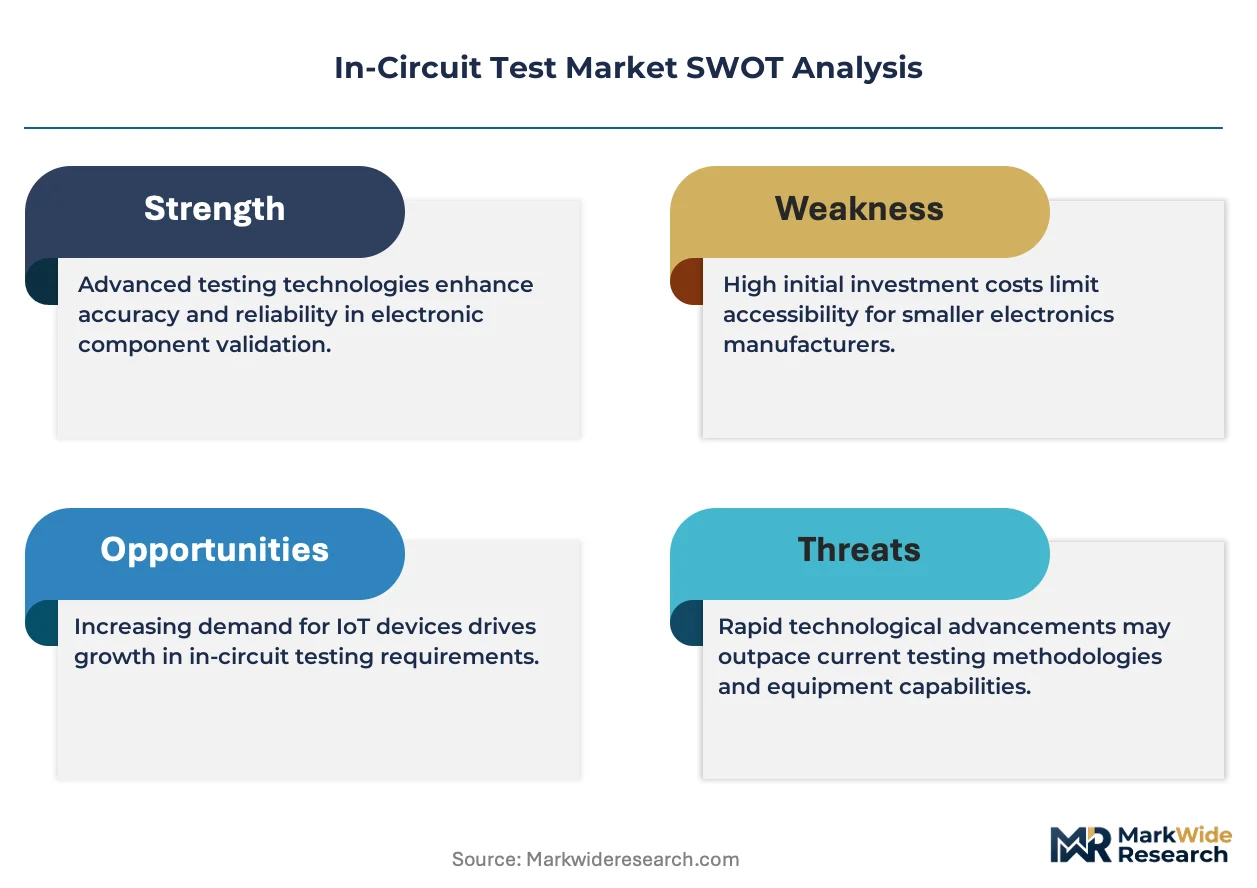
Market Dynamics
Fixtureless test architectures are compressing capital deployment cycles as PCB lifecycles shorten below eighteen months, forcing equipment buyers to trade throughput for reconfigurability in mixed-model assembly environments.
Growth Catalysts
- Automotive ECU complexity:Electric powertrain controllers and ADAS sensor fusion modules require multi-thousand-node test coverage that bed-of-nails systems verify at line speed. German automotive suppliers anchor regional demand.
- REACH substance verification:ECHA restrictions on lead and halogenated compounds compel solder joint integrity testing at the board level before functional assembly stages.
- Telecom infrastructure buildouts:5G base station and optical transceiver manufacturing in China demands mixed-signal ICT platforms for RF-analog-digital integration validation.
Market Restraints
- Fixture fabrication bottlenecks:Precision-milled test fixtures for 0.3 mm pitch access points require six-to-eight-week lead times from specialized tool-and-die suppliers concentrated in Taiwan and Japan.
- Probe replacement cost volatility:Tungsten-rhenium probe tips face price pressure from aerospace alloy demand and rare earth supply concentration in Chinese processing facilities.
- Technical obsolescence risk:Test access point density limits below 0.25 mm pitch outpace mechanical probing capabilities, forcing premature equipment retirement in miniaturized medical device assembly.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor and PCB assembly create greenfield demand for flying probe systems in Noida and Chennai clusters.
- Cloud-connected diagnostics:Remote firmware calibration and predictive maintenance subscriptions transform capital equipment vendors into recurring revenue platforms.
- EU MDR traceability mandates:Medical device quality system regulations require auditable electrical test records that automated ICT data logging satisfies.
Industry Challenges
- Test engineer scarcity:Mixed-signal debugging expertise combining RF, analog, and digital domains commands premium compensation in Munich and Austin manufacturing hubs.
- Legacy system integration:MES and ERP connectivity protocols from 1990s-era ICT installations resist API standardization, delaying Industry 4.0 upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Circuit Test Market |
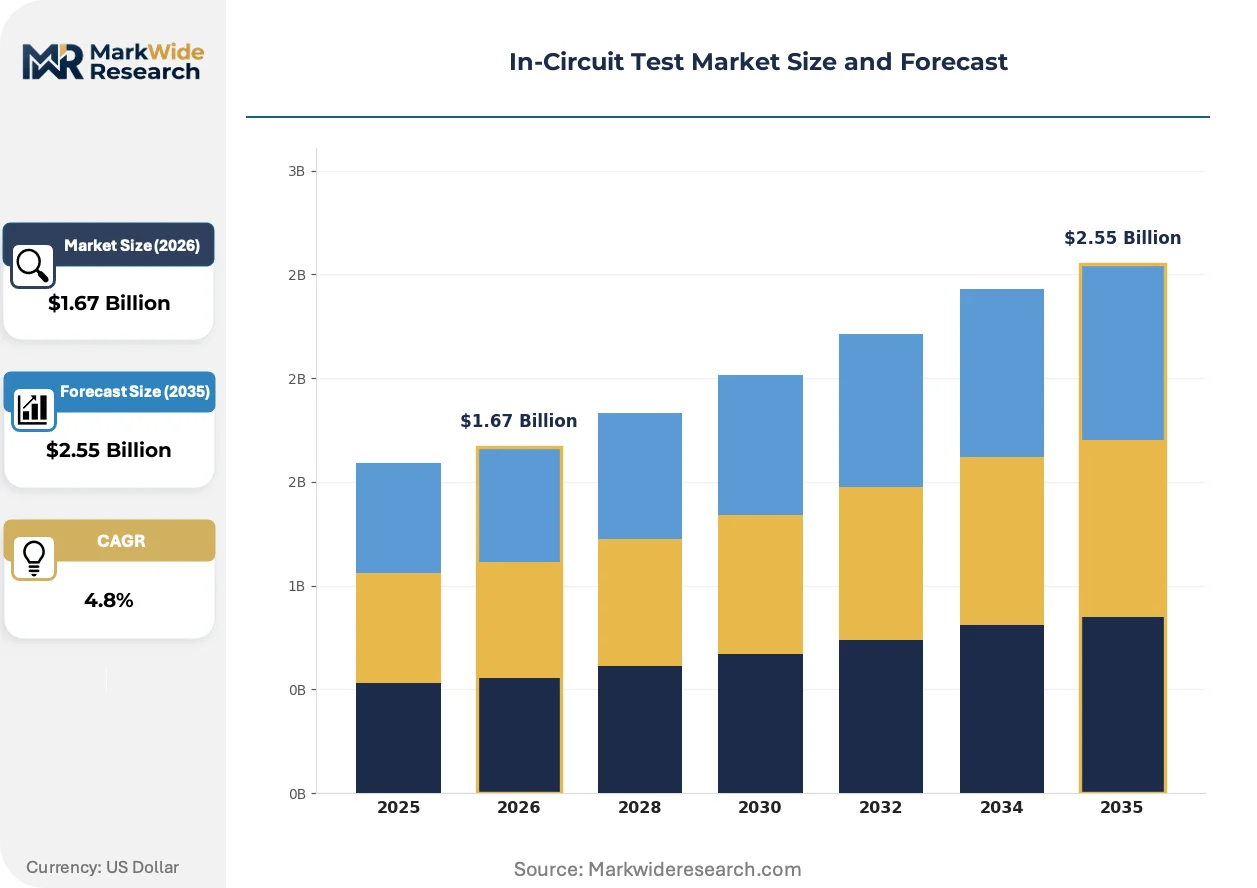
| Market Size in 2026 | $1.67 Billion |
| Market Size in 2035 | $2.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed of Nails Testers, Flying Probe Testers, Functional Testers, Modular Test Systems, Custom Test Systems Technology: Analog Testing, Digital Testing, Mixed Signal Testing, Boundary Scan Testing, JTAG Testing Application: Consumer Electronics, Aerospace Equipments, Telecommunications, Medical Devices, Industrial Automation End User: Electronic Contract Manufacturers, Original Equipment Manufacturers, Semiconductor Foundries, Repair Centers, Technology Laboratories |
| Companies Covered | Hioki E.E. Corporation, Kyoritsu Electric Corporation, Teradyne Inc., Acculogic, Digitaltest GmbH, Test Research Inc., SPEA S.p.A., Konrad GmbH, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Circuit Test Market Strategic Shifts & Innovations
Test system architectures are pivoting from isolated quality gates to networked production nodes, embedding machine learning inference at the edge to compress defect detection latency and reduce downstream rework costs.
Boundary scan integration with IEEE 1149.x protocols is digitizing access to buried interconnects on multilayer HDI boards where mechanical probing fails. Medical device manufacturers in Minnesota and Massachusetts adopt these methods for implantable electronics where test point removal is mandatory. The technology is digitizing fault isolation workflows that previously required destructive cross-sectioning.
FCC equipment authorization rules now mandate pre-certification electromagnetic compatibility screening that ICT platforms incorporate through integrated spectrum analyzer modules. This convergence accelerates time-to-market for IoT device makers facing compressed product launch windows. Consumer electronics assemblers in Shenzhen and Guadalajara reconfigure test floors to accommodate these combined electrical-RF verification stations.
Service contract unbundling separates hardware ownership from uptime guarantees, with buyers in automotive electronics preferring per-test pricing over capital expenditure. Teradyne and Keysight restructure regional service organizations around outcome-based agreements in Michigan and Bavaria. German Tier-1 suppliers now specify availability SLAs rather than equipment specifications in procurement tenders.
In-Circuit Test Market Segmentation
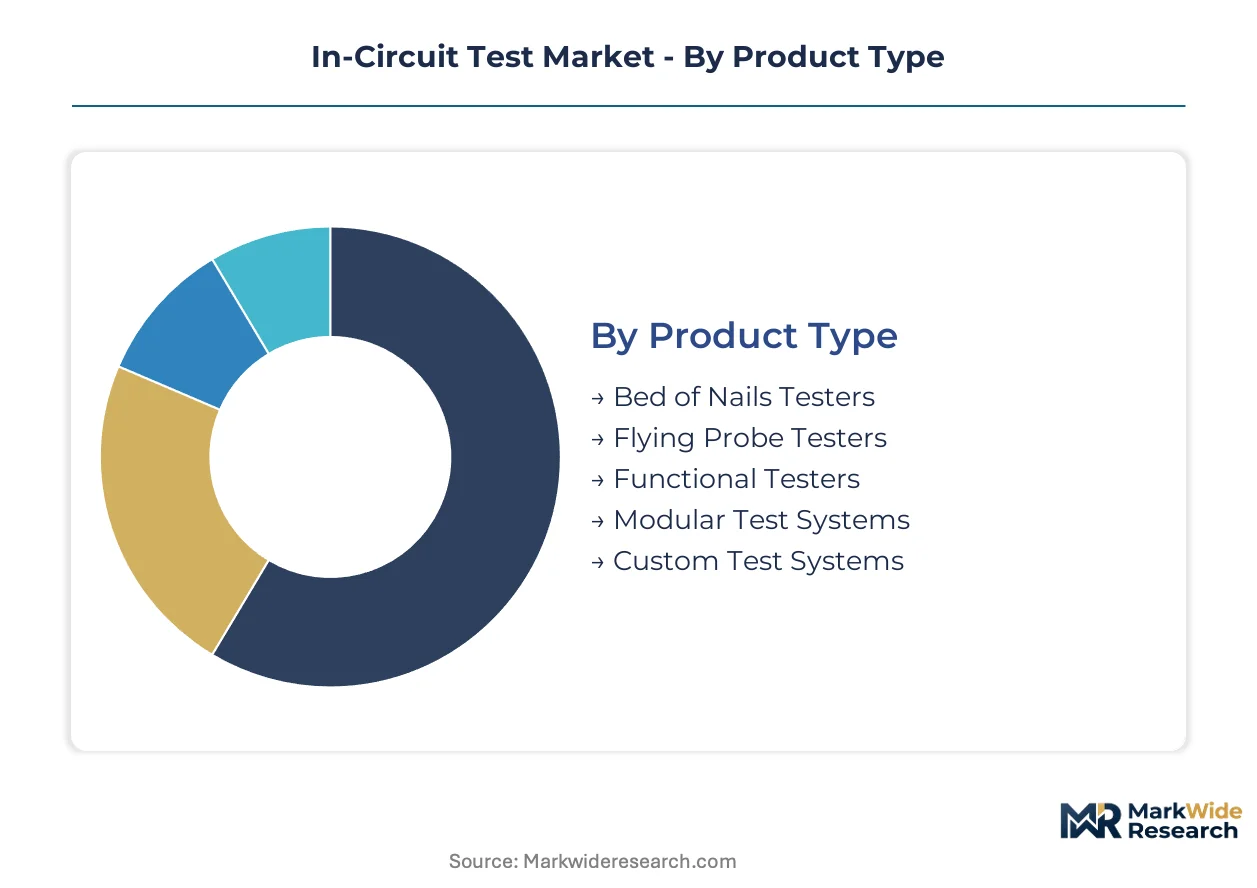
In-circuit test equipment selection hinges on trade-offs between throughput, flexibility, and capital intensity. Segmentation reveals how fixture-based systems dominate high-volume automotive lines while fixtureless architectures capture prototype and medical device workflows.
Product Type:
Mature bed-of-nails architectures coexist with emerging fixtureless platforms as product lifecycles compress below eighteen months.
- Bed of Nails Testers:Dedicated test fixtures with precision-milled probe arrays contact hundreds of nodes simultaneously. Automotive ECU manufacturers in Germany and the United States deploy these systems where amortized fixture costs distribute across million-unit production runs.
- Flying Probe Testers:Programmable probe heads eliminate fixture fabrication, enabling rapid reconfiguration for low-to-medium volume batches. Medical device assemblers in Massachusetts and Minnesota favor this architecture for implantable electronics where test point density exceeds mechanical fixture limits.
- Functional Testers:Verify assembled board operation against design specifications rather than component-level integrity. Aerospace equipment suppliers integrate these for mission-critical avionics validation.
- Modular Test Systems:Reconfigurable chassis accommodate mixed analog-digital-RF instrument cards. Telecommunications hardware manufacturers in China deploy these for 5G base station line cards.
- Custom Test Systems:Purpose-built architectures for specialized form factors or extreme environmental testing. Semiconductor foundries commission these for probe card verification.
Bed of Nails Testers retain volume leadership; Flying Probe Testers hold the steepest expansion curve.
Technology:
Cost tiers separate legacy single-domain methods from premium multi-physics integration demanded by RF-analog-digital convergence.
- Mixed Signal Testing:Synchronized analog stimulus and digital pattern generation validate data converters and sensor interfaces. Telecommunications transceiver manufacturing in China and South Korea drives adoption as 5G infrastructure deployment accelerates.
- Boundary Scan Testing:IEEE 1149.x protocol access to buried interconnects replaces mechanical probing on multilayer HDI boards. Medical device manufacturers adopt this for implantable electronics where physical test point removal is mandatory.
- Analog Testing:Precision voltage and current source/measure units verify passive components and linear ICs. Industrial automation equipment suppliers in Germany maintain installed bases for legacy process control boards.
- Digital Testing:High-speed pattern generators and comparators validate logic devices and memory. Consumer electronics assemblers in Shenzhen deploy these for smartphone motherboard verification.
- JTAG Testing:Serial boundary-scan infrastructure for processor and FPGA debug access. Technology laboratories utilize this for failure analysis and firmware development.
Mixed Signal Testing commands premium pricing; Boundary Scan Testing is climbing the fastest as HDI board penetration deepens.
Application:
Customer type differentiation separates capital-intensive production environments from lower-volume certification and repair operations.
- Automotive Electronics:Electric powertrain controllers and ADAS sensor fusion modules demand multi-thousand-node coverage. German Tier-1 suppliers anchor regional procurement for bed-of-nails systems.
- Consumer Electronics:High-volume smartphone and wearable manufacturing in China and Vietnam prioritizes throughput over reconfigurability. Dedicated fixtures amortize across compressed product lifecycles.
- Medical Devices:FDA quality system regulations mandate traceable electrical test records. Minnesota and Massachusetts clusters adopt boundary scan and flying probe methods for implantable electronics.
- Telecommunications:5G base station and optical transceiver production requires mixed-signal validation of RF-analog-digital integration. Chinese infrastructure buildouts concentrate demand.
- Aerospace Equipments:DO-254 and DO-178C compliance drives rigorous verification of avionics assemblies. US and European defense contractors specify extended temperature and vibration qualification.
- Industrial Automation:Long lifecycle process control boards sustain demand for legacy analog testing capabilities. German manufacturing automation suppliers maintain extended service contracts.
Consumer Electronics sustains the largest installed base; Medical Devices is gaining share fastest on regulatory traceability mandates.
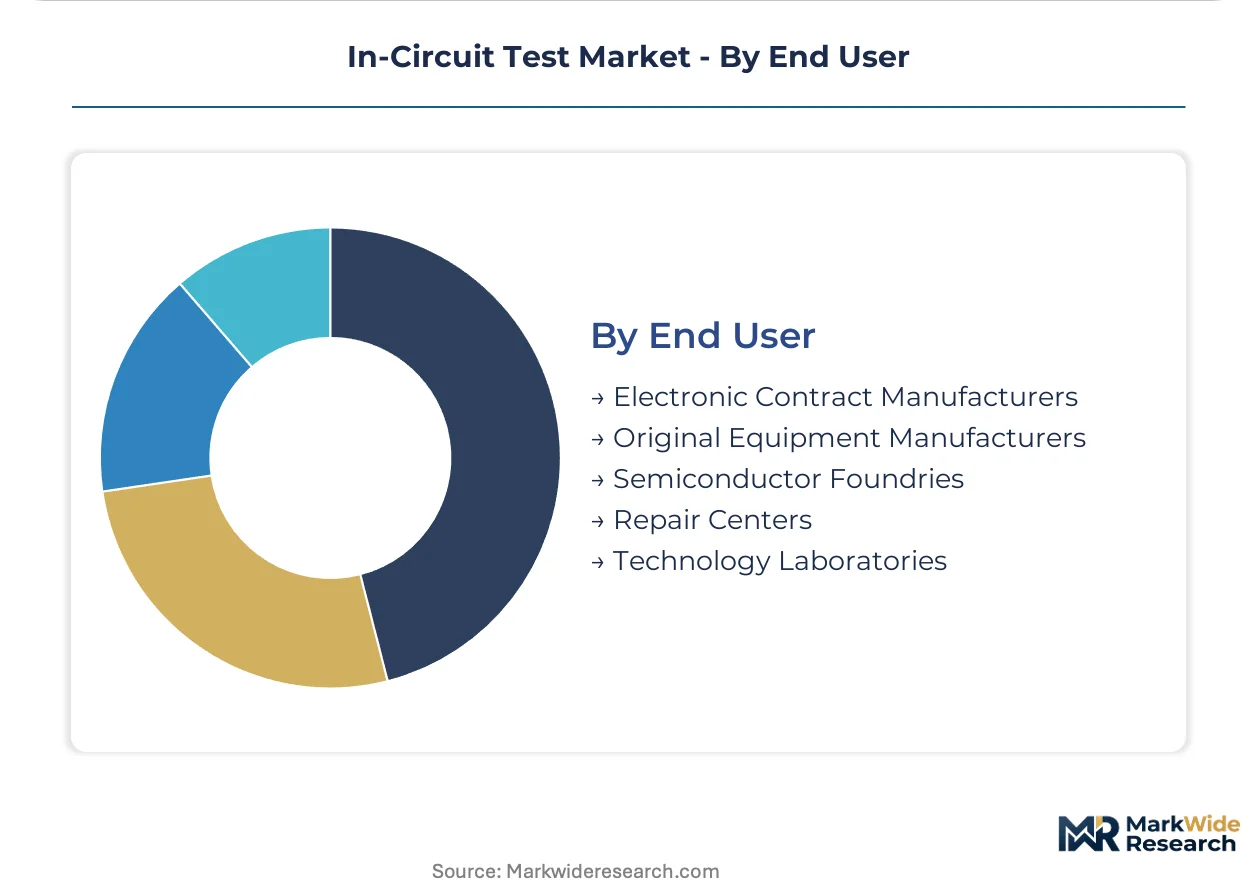
End User:
Geography concentrates procurement among electronics manufacturing clusters with divergent mix flexibility requirements.
- Electronic Contract Manufacturers:Foxconn, Jabil, and Flex operate mixed-model lines requiring rapid test program changeover. Mexican and Vietnamese facilities prioritize flying probe and modular architectures.
- Original Equipment Manufacturers:Captive assembly for automotive and medical verticals favors dedicated bed-of-nails systems. BMW and Medtronic maintain in-house test floors in Bavaria and Minnesota.
- Semiconductor Foundries:Wafer probe card and final test validation requires custom thermal and mechanical environments. TSMC and Samsung commission specialized systems from equipment vendors.
- Repair Centers:Depot-level diagnostics for warranty returns and field failures. US and European aftermarket service networks utilize portable JTAG and boundary scan equipment.
- Technology Laboratories:R&D validation and failure analysis for new product introduction. Austin and Munich engineering hubs deploy mixed-signal and custom test platforms.
Electronic Contract Manufacturers represent the dominant procurement channel; Semiconductor Foundries show the steepest equipment spending trajectory on advanced packaging test requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers in Mexico and Vietnam exhibit the highest price elasticity, squeezing equipment margins through per-test pricing negotiations, while German automotive OEMs absorb premium bed-of-nails systems with minimal procurement friction.
United States
Medical device clusters in Minnesota and Massachusetts drive flying probe demand for implantable electronics where test point density exceeds mechanical fixture limits. FDA quality system regulations mandate traceable electrical test records that automated ICT platforms generate. Austin and Boston engineering hubs concentrate mixed-signal test platform deployment for telecommunications R&D.
Germany
Tier-1 automotive suppliers in Bavaria and Baden-Württemberg anchor European bed-of-nails procurement for electric powertrain controller verification. ECHA REACH restrictions on lead and halogenated compounds compel solder joint integrity testing at the board level. Munich manufacturing automation suppliers sustain extended service contracts for legacy analog testing capabilities.
China
5G base station and optical transceiver manufacturing concentrates mixed-signal ICT demand in Shenzhen and Shanghai. MIIT equipment certification rules mandate electromagnetic compatibility pre-testing that integrated ICT-spectrum analyzer platforms satisfy. Yangtze River Delta electronics assemblers reconfigure test floors for combined electrical-RF verification stations.
Japan
Precision tool-and-die suppliers in Aichi and Osaka prefectures fabricate test fixtures for 0.3 mm pitch access points with six-to-eight-week lead times. METI industrial standardization programs accelerate boundary scan adoption for multilayer HDI boards. Tokyo and Nagoya clusters specialize in tungsten-rhenium probe tip production facing aerospace alloy demand pressure.
India
PLI scheme subsidies for semiconductor and PCB assembly create greenfield flying probe demand in Noida and Chennai electronics clusters. BIS certification requirements for telecom equipment drive integrated test platform adoption. Karnataka and Telangana contract manufacturers prioritize rapid test program changeover for mixed-model consumer electronics lines.
In-Circuit Test Market Key Industry Players
Capability concentration sits with specialized fixture fabricators and mixed-signal instrument developers; scale advantage sits with diversified test equipment conglomerates with installed base leverage. The vendor base stratifies across three archetypes: precision mechanics specialists, broad-line electronic test houses, and regional system integrators. Consolidation pressure intensifies as cloud-connected service models transform capital equipment vendors into recurring revenue platforms. Dominant competitive moves include outcome-based contract restructuring and geographic service organization expansion.
Among Japan-based precision instrument manufacturers, Hioki E.E. Corporation and Kyoritsu Electric Corporation exemplify the specialized instrumentation tier with deep roots in electrical measurement technology. Teradyne Inc. occupies a position as a scale-driven North American test equipment conglomerate with extensive installed base leverage. SPEA S.p.A. represents the European automotive-focused archetype with localized technical support infrastructure. These three anchors illustrate how geographic origin and historical specialization continue to shape competitive positioning despite converging technology requirements.
| Leading Market Players |
|---|
| Hioki E.E. Corporation |
| Kyoritsu Electric Corporation |
| Teradyne Inc. |
| Acculogic |
| Digitaltest GmbH |
| Test Research Inc. |
| SPEA S.p.A. |
| Konrad GmbH |
| Keysight Technologies |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors linking Taiwan and Japan to German automotive hubs transmit tungsten-rhenium probe tip cost volatility directly into bed-of-nails fixture pricing, while contract manufacturers in Mexico and Vietnam exploit this concentration to negotiate per-test service models that compress capital equipment margins.
Pricing Analysis
Service contract subscriptions now generate the dominant lifetime value stream as Teradyne and Keysight restructure regional organizations around outcome-based availability SLAs rather than hardware ownership. Three-tier pricing structure across premium, standard, and economy levels separates German Tier-1 automotive suppliers with minimal procurement friction from Vietnamese contract manufacturers exhibiting extreme price elasticity. Cost compression in the fixture fabrication tier intensifies because precision-milled probe arrays require specialized tool-and-die suppliers concentrated in Aichi and Osaka prefectures. Electronic contract manufacturers in Mexico represent the most price-sensitive buyer segment, while captive OEM test floors in Bavaria and Minnesota absorb premium configurations with limited negotiation leverage.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold dominant contract manufacturing capacity across Noida, Chennai, and Vietnamese electronics clusters, feeding mixed-model assembly demand for rapidly reconfigurable flying probe architectures. Component sourcing draws from Japanese precision mechanics suppliers for probe card fabrication, German automation houses for analog instrument modules, and Chinese spectrum analyzer integration for RF-electrical convergence platforms. Single-source vulnerability concentrates in Taiwan and Japan for 0.3 mm pitch fixture milling equipment with six-to-eight-week lead time exposure. Distribution runs through direct vendor technical support centers in Michigan and Bavaria for automotive OEMs, contrasted with distributor networks serving Mexican and Indian contract manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boundary scan and non-contact optical inspection substitution threats are accelerating as test access point densities below 0.25 mm pitch outpace mechanical probing capabilities, forcing incumbents to defend installed base positions through service contract lock-in rather than equipment refresh cycles.
For Market Incumbents: Entrench multi-year service agreements with automotive OEMs in Germany and the United States before boundary scan displacement accelerates in medical device segments. Deepen backward integration into tungsten-rhenium probe tip production to insulate margin structures from aerospace alloy demand pressure. Prioritize firmware update subscription platforms that transform capital equipment vendors into recurring revenue engines resistant to hardware commoditization. For New Entrants and Emerging Players: Mid-volume medical device assemblers in Massachusetts and Minnesota represent the most penetrable entry point where test point density exceeds mechanical fixture limits and incumbent service coverage remains thin. Indian PLI-subsidized electronics clusters in Noida and Chennai offer greenfield demand for flying probe systems without entrenched competitor relationships. Lead with cloud-connected predictive maintenance subscriptions that incumbent hardware-centric organizations cannot rapidly replicate. For Investors and Strategic Acquirers: Specialized fixture fabricators with precision-milled probe array capabilities in Aichi and Osaka prefectures command scarcity premiums as test access point densities compress below mechanical limits. Long-term viability in this market hinges on service revenue transformation rather than equipment shipment volumes. Monitor boundary scan adoption rates in Minnesota and Massachusetts medical device clusters as the critical inflection signal for mechanical probing obsolescence risk. Quarterly review of automotive OEM service contract renewal rates and probe tip material cost indices is advised to detect margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Separates hardware ownership from uptime guarantees, transforming Teradyne and Keysight into recurring revenue platforms. |
| Cloud-Connected Diagnostics Platform | Enables remote firmware calibration and predictive maintenance subscriptions that lock in automotive OEM relationships. |
| Backward Integration into Probe Tip Production | Insulates margin structures from tungsten-rhenium price volatility driven by aerospace alloy demand. |
| Boundary Scan Technology Partnership | Addresses test access point density limits below 0.25 mm pitch that mechanical probing cannot satisfy. |
| Geographic Service Organization Expansion | Establishes localized technical support centers in Bavaria and Michigan to capture automotive ECU verification demand. |
Research Approach
Desk research of SEC 10-K filings, ECHA REACH substance restriction databases, and MIIT equipment certification records preceded structured interviews with ICT equipment procurement managers at Tier-1 automotive suppliers, test floor engineers at medical device OEMs, and service contract directors at electronic test conglomerates. Primary fieldwork across Munich, Austin, Shenzhen, and Tokyo manufacturing hubs combined with secondary validation of production volume data from automotive ECU and 5G base station assembly lines. Bottom-up segmentation modeling triangulated against top-down market sizing derived from capital equipment shipment tracking.
Assumptions held fixed include ECHA REACH enforcement continuity, FCC equipment authorization rule stability, and automotive ECU test node complexity trajectories; variables included PLI scheme subsidy duration in India and boundary scan adoption velocity in medical device segments. The projection framework modeled product type, technology, application, and end user dimensions alongside regional production cluster concentration. CAGRs derived from regression analysis of historical capital expenditure patterns weighted by electronics manufacturing capacity expansion announcements. Forecast inputs incorporated tungsten-rhenium commodity price indices and automotive platform electrification roadmaps.
Practitioners should monitor ECHA substance restriction amendments, FDA quality system regulation updates, and MIIT electromagnetic compatibility certification timeline shifts for early signals of demand pattern revision. Forecasts reflect assumptions regarding probe tip material supply continuity and automotive production volume stability. Quarterly review of fixture fabrication lead time reports from Aichi and Osaka suppliers alongside automotive OEM service contract renewal announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Pump Testers Market
Test and Measurement
North America Automated Test Equipment Market