
 North America Automated Test Equipment Market | 2026-2036
North America Automated Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automated Test Equipment Market Analytics
Market Context
Texas is reshaping North American ATE capacity through major semiconductor test floor expansions tied to advanced packaging lines. Teradyne leverages its dominant position in system-level test handlers for high-volume memory and logic devices. Keysight Technologies anchors the radio frequency and millimeter-wave test segment with instrumentation that spans 5G baseband through automotive radar validation. Advantest Corporation specializes in burn-in and final test systems for leading-edge DRAM and NAND flash production.
Technical Definition and Segment Structure
Automated test equipment comprises programmable electronic instrumentation that applies electrical stimuli to semiconductor devices, printed circuit assemblies, or subsystems and evaluates parametric responses against defined pass-fail thresholds with nanosecond timing precision and microvolt measurement resolution. Its primary purpose is to screen manufacturing defects, verify functional performance, and ensure long-term reliability before components enter downstream assembly or field deployment. Mixed-signal test technology captures expanding margin pools as automotive radar and power management ICs blend analog sensing with digital processing. Machine learning test represents the fastest-growing technology segment as adaptive algorithms reduce test program development cycles and improve defect detection rates. Functional test equipment maintains the largest revenue share due to its indispensability across telecommunications infrastructure and defense electronics qualification protocols.
Regulatory Framework and Outlook
The Federal Communications Commission governs electromagnetic emissions testing for wireless-enabled devices, while the Department of Defense mandates MIL-STD-883 and MIL-STD-750 environmental screening for all semiconductor components deployed in aerospace and defense platforms. The CHIPS and Science Act imposes domestic content thresholds that incentivize ATE procurement within U.S.-based fabrication facilities, altering vendor qualification criteria. The Environmental Protection Agency's evolving restrictions on perfluorinated compounds in semiconductor manufacturing are beginning to influence thermal management specifications in burn-in test equipment design. Stakeholders must monitor how NHTSA's automated vehicle validation protocols extend functional safety test requirements into automotive ATE procurement specifications.
Market Dynamics
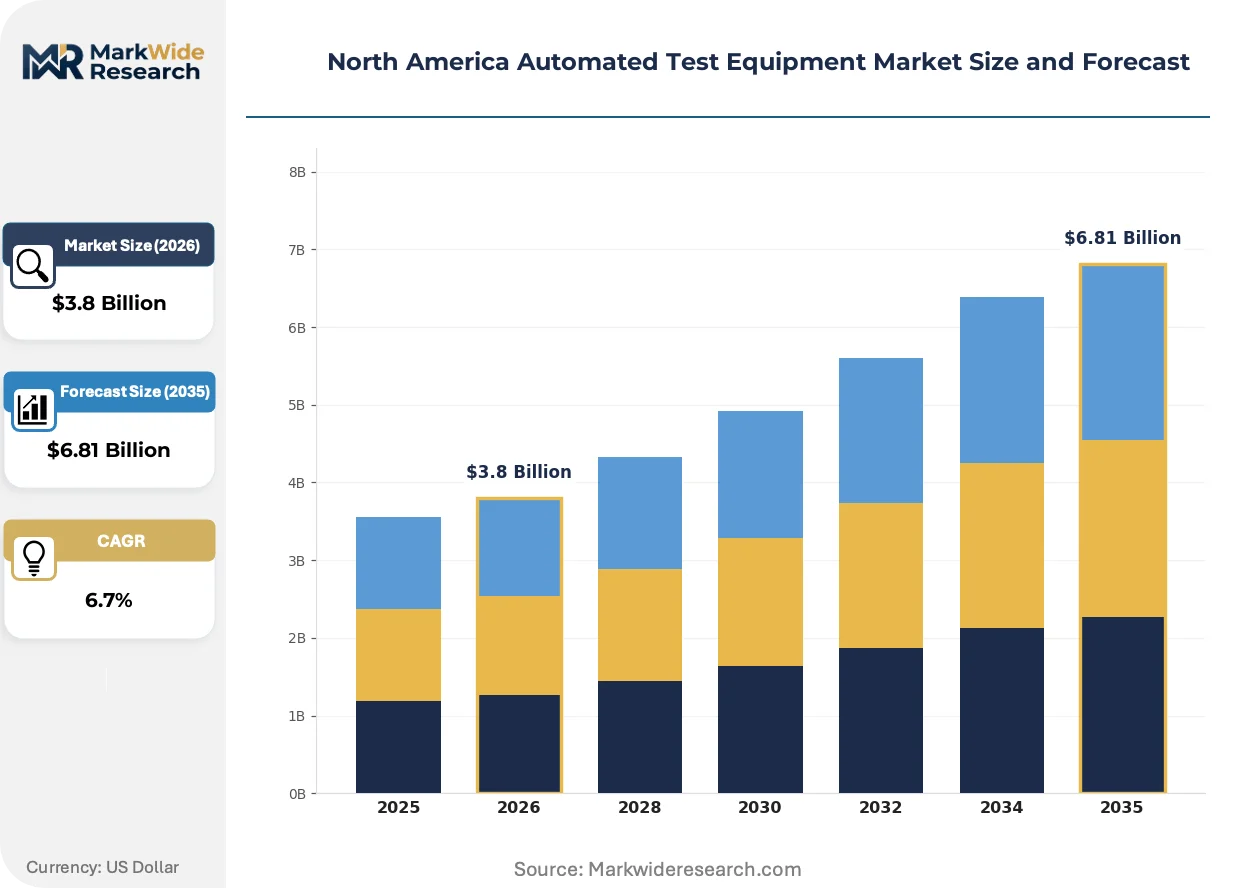
The CHIPS and Science Act is reconfiguring capital deployment patterns across North American semiconductor test floors, tying federal incentives to domestic ATE procurement thresholds and accelerating facility construction timelines in Texas and Arizona.
Growth Catalysts
- Advanced packaging test requirements:Heterogeneous integration of chiplets and 3D stacking architectures demands multi-site probing systems with sub-micron alignment precision. Texas fabs are expanding test floor capacity to accommodate these throughput-intensive validation protocols.
- FCC emissions mandates:Millimeter-wave device proliferation for 5G infrastructure and automotive radar requires comprehensive electromagnetic compatibility screening, expanding the installed base of RF test systems across North American contract manufacturers.
- Powertrain electrification:Electric vehicle OEMs require functional safety validation for SiC and GaN power devices under ISO 26262 protocols, extending ATE utilization from wafer probe through module-level burn-in.
Market Restraints
- Specialized engineering labor scarcity:Test program development for mixed-signal devices requires expertise spanning RF circuit design, digital pattern generation, and statistical process control, with qualified practitioners concentrated in Boston and Silicon Valley corridors.
- Capital intensity of handler-retooling cycles:Thermal conditioning chambers and precision contactors represent 40-60% of system replacement costs, compressing upgrade frequency for mid-volume contract test houses.
- Long-lead critical components:High-speed digitizer modules and precision motion stages depend on Japanese and German sub-tier suppliers, exposing North American integrators to extended delivery timelines.
Strategic Opportunities
- Mexico nearshoring expansion:Electronics manufacturing services are consolidating final test operations in Baja California and Chihuahua to serve US automotive OEMs, creating demand for compact, multi-protocol ATE configurations.
- CHIPS Act domestic content thresholds:Federal procurement rules incentivize ATE sourcing from US-based assembly facilities, favoring vendors with captive manufacturing in Arizona, Texas, or Massachusetts.
- Machine learning test algorithm deployment:Adaptive fault detection is reducing program development cycles for automotive radar SoCs, enabling faster time-to-volume for fabless designers targeting Detroit Tier-1 suppliers.
Industry Challenges
- Legacy system protocol fragmentation:Decades of proprietary test program formats across Teradyne, Advantest, and Cohu platforms impede code portability when fabs transition between contract test houses.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for automotive ATE software stacks extends validation cycles by 8-14 months, delaying revenue recognition for power device test programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automated Test Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Test Equipment, In-Circuit Test Equipment, Programmable Test Equipment, Burn-In Test Equipment Technology: Digital Test, Analog Test, Mixed-Signal Test, Machine Learning Test End User: Telecommunications, Aerospace & Defense, Automotive OEMs, Consumer Electronics Application: Quality Assurance, Research & Development, Production Testing, Compliance Testing |
| Companies Covered | Chroma ATE, Danaher Corporation, Teradyne, STAr Technologies, Keysight Technologies, Advantest Corporation, Astronics Corporation, Roos Instruments, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automated Test Equipment Market Evolving Landscape
Test floor architectures are converging around software-defined instrumentation and cloud-native data pipelines, compressing the boundary between characterization and high-volume production environments.
Mixed-signal test platforms are hybridizing analog stimulus generation with digital pattern application within unified hardware frameworks. Automotive radar and power management IC designers in Detroit and Austin are adopting these configurations to consolidate validation workflows. This convergence is hybridizing previously separate RF and digital test benches, reducing capital footprint per qualified device.
The CHIPS and Science Act imposes domestic content verification requirements on semiconductor manufacturing equipment procurement. Federal grant recipients in Arizona and Texas must document US-sourced test system percentages, altering vendor qualification criteria. ATE integrators with captive assembly in Massachusetts and California are restructuring supply chains to meet these thresholds.
Automotive OEMs are unbundling test program development from equipment procurement contracts. Tier-1 suppliers in Michigan and Ontario now license test IP separately from handler hardware, shifting margin pools toward software and calibration services. This disaggregation is most visible in electric vehicle inverter test lines, where Detroit-based power module specialists retain program ownership across multiple contract manufacturers.
North America Automated Test Equipment Market Segmentation
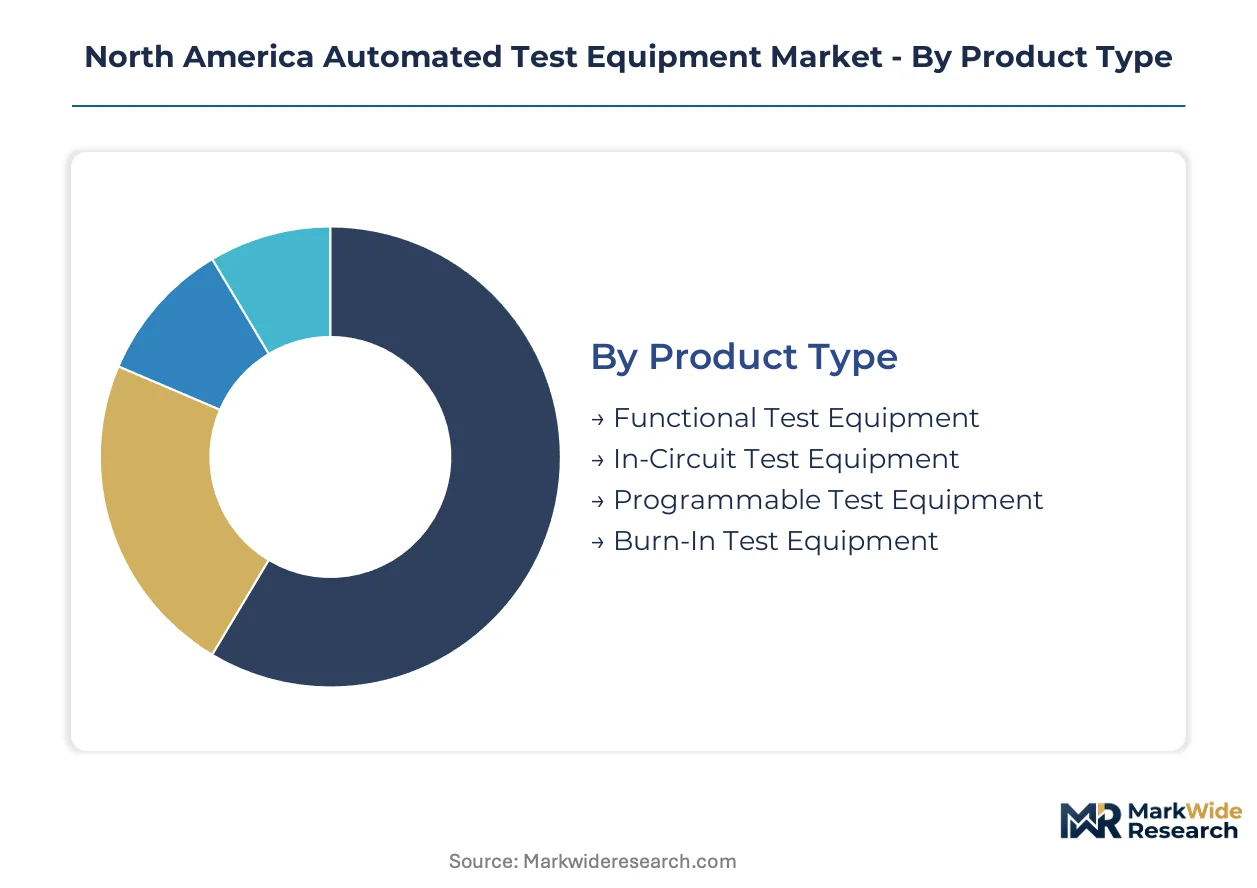
Test floor procurement patterns in North American semiconductor fabs vary sharply by equipment category, with some segments commanding decade-long depreciation schedules while others turn over every 3-4 years. Understanding these velocity differences guides capital allocation for Texas and Arizona facility expansions.
Product Type:
Cycle times diverge most dramatically here: functional test platforms depreciate over 7-10 years in defense electronics qualification, while burn-in chambers require replacement every 4-6 years due to thermal cycling fatigue.
- Functional Test Equipment:Comprehensive systems applying electrical stimuli and measuring parametric responses against pass-fail thresholds for assembled printed circuit boards and subsystems. Defense electronics contractors in Massachusetts and California maintain extensive installed bases for MIL-STD-883 screening, with upgrade cycles tied to program-specific qualification protocols rather than throughput volume.
- Burn-In Test Equipment:Thermal conditioning chambers that accelerate infant mortality screening through elevated temperature and voltage stress. Texas memory fabs expanding advanced packaging lines are procuring multi-site systems to handle 3D-stacked DRAM modules, with replacement driven by thermal chamber degradation rather than obsolescence.
- In-Circuit Test Equipment:Bed-of-nails fixtures verifying component-level integrity on populated PCBs.
- Programmable Test Equipment:Reconfigurable instrumentation platforms supporting multiple device families through software-defined test sequences.
Functional Test Equipment dominates installed base. Burn-In Test Equipment is where expansion concentrates.
Technology:
Cost tiers separate legacy digital-only platforms from premium mixed-signal configurations, with machine learning capabilities commanding 40-60% price premiums over conventional pattern generation.
- Mixed-Signal Test:Unified hardware frameworks hybridizing analog stimulus generation with digital pattern application for devices blending sensing and processing functions. Automotive radar and power management IC designers in Detroit and Austin are consolidating validation workflows onto these platforms, reducing capital footprint per qualified device.
- Machine Learning Test:Adaptive algorithms reducing test program development cycles and improving defect detection rates through statistical pattern recognition. Fabless designers targeting Detroit Tier-1 suppliers are deploying these systems to compress time-to-volume for automotive radar SoCs, with software licensing representing a growing share of total contract value.
- Digital Test:Pattern generation and logic verification for pure digital logic devices and memory arrays.
- Analog Test:Precision voltage and current sourcing with microvolt measurement resolution for linear ICs.
Mixed-Signal Test anchors current revenue. Machine Learning Test is climbing the fastest.
End User:
Volume concentration varies by customer type: automotive OEMs procure through multi-year frame agreements, while consumer electronics manufacturers spot-buy for seasonal production ramps.
- Automotive OEMs:Electric vehicle powertrain electrification is extending ATE utilization from wafer probe through module-level burn-in for SiC and GaN devices under ISO 26262 functional safety protocols. Michigan and Ontario-based Tier-1 suppliers are unbundling test program development from equipment procurement, shifting margin pools toward software and calibration services.
- Telecommunications:5G infrastructure deployment requires millimeter-wave device screening for baseband and radio units. FCC emissions mandates are expanding the installed base of RF test systems across North American contract manufacturers serving base station OEMs.
- Aerospace & Defense:MIL-STD-883 and MIL-STD-750 environmental screening for semiconductor components deployed in aerospace platforms.
- Consumer Electronics:High-volume final test for smartphones, wearables, and smart home devices.
Telecommunications holds the largest historical deployment. Automotive OEMs are gaining share fastest.
Application:
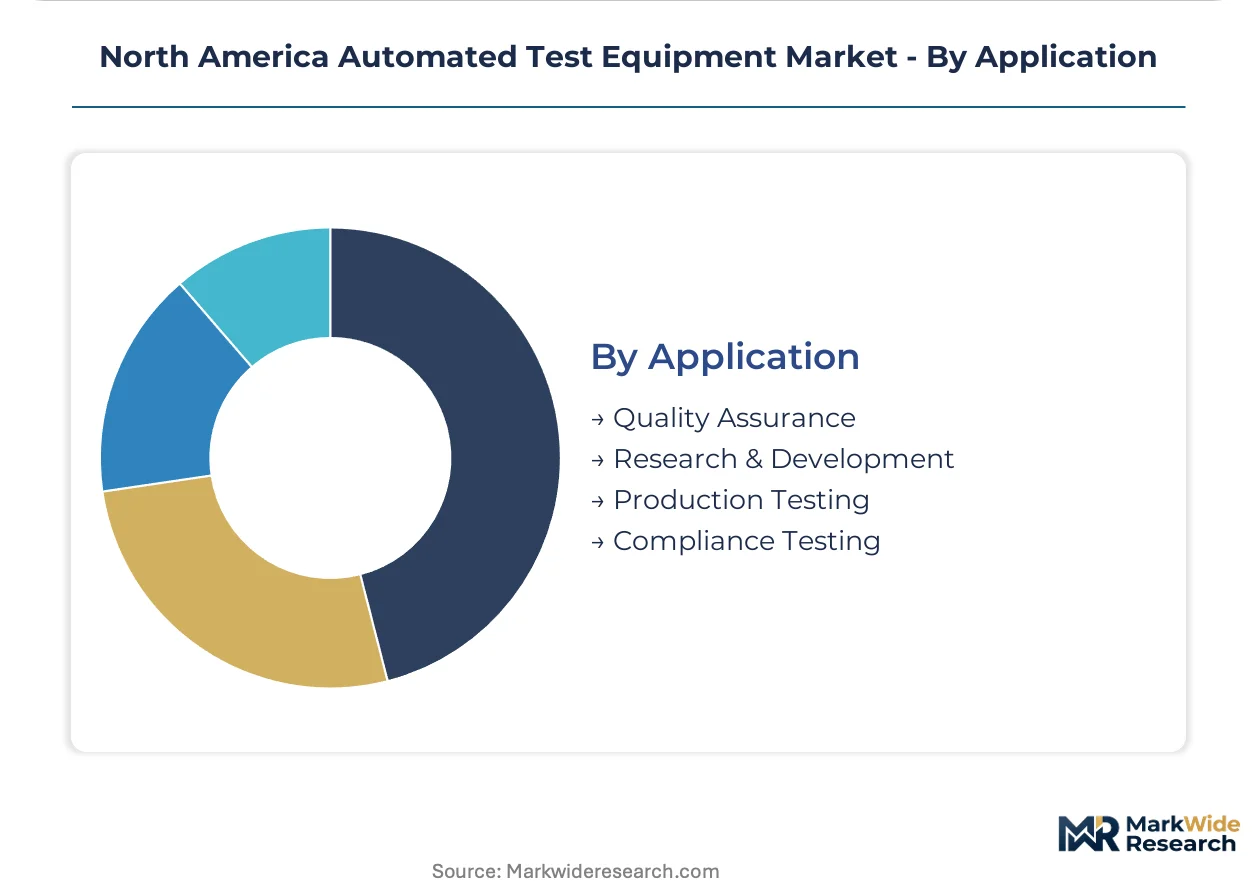
Customer maturity separates established production testing workflows from emerging compliance testing requirements driven by NHTSA automated vehicle validation protocols.
- Production Testing:High-volume screening of semiconductor devices and electronic assemblies at manufacturing scale. Texas and Arizona fabs expanding advanced packaging capacity are prioritizing throughput-intensive multi-site probing systems for chiplet-based architectures.
- Compliance Testing:Regulatory validation against FCC electromagnetic emissions standards, NHTSA functional safety protocols, and defense qualification requirements. The CHIPS Act's domestic content thresholds are altering vendor qualification criteria for federal grant recipients procuring test infrastructure.
- Quality Assurance:Statistical process control and outgoing quality verification for contract manufacturers.
- Research & Development:Characterization and failure analysis during new product introduction cycles.
Production Testing dominates capital deployment. Compliance Testing is where specification complexity is deepening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC emissions mandates and CHIPS Act procurement rules are reconfiguring test floor investments across North American semiconductor clusters. Texas and Arizona fabs are expanding capacity for advanced packaging validation, while Mexico's border states attract final test consolidation for automotive supply chains.
United States
Texas fabs in Austin and Dallas are expanding test floor capacity for 3D-stacked memory and chiplet architectures. The CHIPS and Science Act imposes domestic content thresholds on federal grant recipients, altering vendor qualification criteria for Arizona and Texas facility expansions. Massachusetts and California maintain established defense electronics test clusters serving MIL-STD-883 screening protocols.
Canada
Ontario-based automotive Tier-1 suppliers are procuring mixed-signal test platforms for electric vehicle inverter validation. Health Canada coordinates with NHTSA on automated vehicle functional safety standards that extend into ATE procurement specifications. Toronto-Waterloo corridor fabs are adding RF test capacity for 5G telecommunications components.
Mexico
Baja California and Chihuahua electronics manufacturing services are consolidating final test operations to serve Detroit automotive OEMs. The country's national trade authority facilitates nearshoring incentives that accelerate compact, multi-protocol ATE deployments. Tijuana and Ciudad Juárez contract test houses are expanding burn-in capacity for power module screening.
North America Automated Test Equipment Market Competitive Landscape
Full-stack system integrators and specialized instrumentation developers split the market into distinct capability tiers. Consolidation pressure concentrates around semiconductor test handlers and RF measurement platforms, with mid-volume contract houses facing compressed upgrade cycles. Two strategic archetypes dominate: captive fab equipment suppliers and independent test program licensors. Competitive moves center on handler-retooling partnerships and machine learning algorithm licensing.
Within the instrumentation tier, Teradyne and Keysight Technologies exemplify contrasting strategic positions. Teradyne anchors system-level test handler supply for high-volume memory and logic devices. Keysight Technologies occupies a position in radio frequency and millimeter-wave test segments spanning 5G baseband through automotive radar validation. Advantest Corporation represents the specialized burn-in and final test archetype for leading-edge DRAM and NAND flash production.
| Leading Market Players |
|---|
| Chroma ATE |
| Danaher Corporation |
| Teradyne |
| STAr Technologies |
| Keysight Technologies |
| Advantest Corporation |
| Astronics Corporation |
| Roos Instruments |
| National Instruments |
| Others |
Value Network & Pricing Analysis
Japanese and German sub-tier suppliers of high-speed digitizer modules and precision motion stages anchor upstream concentration, situating margin pools with North American system integrators who control final assembly and test program IP licensing.
Pricing Analysis
Geographic price spreads widen between Massachusetts-based defense electronics contractors and Arizona memory fabs, reflecting divergent certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-883 qualified systems from commercial automotive configurations. Pricing pressure stems from automotive OEM unbundling of test program development from hardware procurement. Contract test houses in Baja California exhibit highest price sensitivity due to compressed handler-retooling cycles.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk planning for motion control and thermal management subsystems. Critical component sourcing draws from Japan, Germany, and South Korea for precision instrumentation. High-speed digitizer modules and thermal conditioning chambers represent concentrated dependencies. Single-source vulnerability persists in sub-micron alignment systems. Distribution runs through captive fab equipment suppliers and independent test program licensors serving Texas and Arizona facility expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test floor economics are shifting toward platform interoperability as automotive OEMs decouple hardware procurement from software licensing, creating ecosystem leverage for vendors controlling test program IP and calibration protocols.
For Market Incumbents: Entrench handler-retooling partnerships with Texas and Arizona fabs expanding advanced packaging capacity. Deepen backward integration into thermal conditioning chamber production to offset Japanese supplier lead times. ISO 26262 ASIL-D certification investment represents the critical defensive lever against emerging software-defined instrumentation entrants.
For New Entrants and Emerging Players: Establish a beachhead in machine learning test algorithm licensing for automotive radar SoC validation. Mexico nearshoring corridors in Baja California and Chihuahua present the most penetrable geography. Channel through Detroit Tier-1 suppliers unbundling test IP from equipment contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized burn-in and final test archetypes with captive assembly in Massachusetts or California. Long-term viability hinges on domestic content threshold compliance under CHIPS Act procurement rules. Watch for NHTSA automated vehicle validation protocol extensions as inflection signal for compliance testing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Handler-Retooling Partnership | Teradyne and Advantest secure multi-year capacity reservations with Texas memory fabs. |
| Machine Learning Algorithm Licensing | Adaptive fault detection compresses program development for Detroit automotive radar suppliers. |
| Domestic Content Compliance Investment | Arizona and Massachusetts assembly restructuring meets CHIPS Act procurement thresholds. |
| Test Program IP Unbundling | Michigan Tier-1 suppliers retain ownership across multiple contract manufacturers. |
| Mexico Nearshoring Facility Expansion | Baja California EMS consolidation serves Detroit OEMs with compact multi-protocol configurations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor test floor managers, ATE procurement officers at automotive OEMs, fabless design house validation engineers, and contract test house operations directors. Secondary validation drew from SEC 10-K filings, SEMI equipment market data, FCC equipment authorization databases, and CHIPS Act federal grant disclosures. Bottom-up and top-down triangulation reconciled equipment shipment tallies with fab capacity expansion announcements.
Calibration against historical procurement cycles and announced facility construction timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user industry, and application workflow. CAGRs were derived from slope analysis of equipment spending patterns correlated with wafer fab equipment capex cycles. Forecast inputs incorporated thermal chamber replacement rates and RF test system proliferation tied to 5G infrastructure deployment.
Sensitivities concentrate around CHIPS Act domestic content rule refinements, NHTSA automated vehicle validation protocol finalization, and Japanese supplier delivery timeline volatility. Forecasts reflect documented assumptions on fab construction completion rates and automotive powertrain electrification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Analog Multimeters Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Crock Meter Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Fluorometers Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Noise Dosimeter Market