
 Humidity Testers Market | 2026-2036
Humidity Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Humidity Testers Market Outlook
A widening capability gap between captive MEMS foundries and fabless sensor designers is reorganizing competitive tiers in humidity testing equipment. Honeywell International Inc. leverages in-house wafer fabrication to control capacitive sensor supply chains from raw silicon to calibrated modules. Sensirion AG specializes in miniaturized digital hygrometers for consumer electronics, sustaining Swiss precision positioning against lower-cost Asian suppliers. Bosch Sensortec GmbH dominates automotive-qualified humidity sensing through its parent company's semiconductor scale, extending portfolio breadth into battery thermal management applications.
Humidity testers are electromechanical instruments that measure atmospheric water vapor content, typically expressing results as relative humidity percentage, dew point temperature, or absolute humidity in grams per cubic meter; capacitive variants employ thin-film polymer dielectrics that alter electrical capacitance proportionally to moisture absorption, achieving accuracy within ±2% RH across calibrated ranges. Their primary industrial purpose centers on preventing condensation corrosion, controlling hygroscopic material processing, and validating climate conditions for quality-critical manufacturing. Digital hygrometers occupy the largest revenue pool due to integration demands in building automation networks, while humidity data loggers represent the fastest-expanding category as pharmaceutical cold chain validation tightens globally. Capacitive sensors lead technology adoption owing to low power draw and digital output compatibility, though optical sensors are gaining traction in corrosive industrial atmospheres where electrolytic degradation threatens conventional probes.
The EPA enforces Indoor airPLUS certification standards that mandate humidity monitoring in residential construction, while the EU F-Gas Regulation compels refrigerant leak detection systems to integrate continuous humidity tracking for compressor efficiency diagnostics. Japan's METI oversees JIS standards for industrial environmental measurement instruments, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving sensor accuracy mandates from IEC and ISO working groups, as harmonized calibration protocols increasingly determine cross-border market access for instrument manufacturers.
Market Dynamics
The humidity testers market is restructuring around sensor supply chain consolidation, where captive MEMS foundries are pulling calibration expertise in-house while fabless designers face procurement bottlenecks for precision polymer dielectrics.
Growth Catalysts
- Semiconductor cleanroom mandates:Taiwan and South Korea fabs are expanding environmental monitoring procurement to protect yield rates in advanced node production, creating sustained demand for ±2% RH accuracy instruments.
- EU F-Gas Regulation compliance:Cold chain logistics operators across Europe must install continuous humidity tracking for compressor efficiency diagnostics, tightening refrigerant monitoring requirements.
- Capacitive sensor miniaturization:Thin-film polymer dielectrics with digital output compatibility are displacing analog resistive designs in building automation networks.
Market Restraints
- Raw silicon supply concentration:Wafer fabrication for MEMS humidity sensors concentrates in East Asian foundries, exposing procurement to geopolitical disruption.
- Calibration equipment capex barriers:Precision humidity chambers and reference standards require substantial capital investment, limiting new entrant scale.
- Optical sensor substitution threat:Corrosive industrial atmospheres are driving adoption of laser-based hygrometers where electrolytic degradation threatens polymer capacitive probes.
Strategic Opportunities
- Battery thermal management integration:Electric vehicle manufacturers are converging humidity sensing with temperature monitoring for cell conditioning systems.
- Pharmaceutical cold chain validation:Humidity data loggers face expanding requirements from FDA and EMA good distribution practice mandates.
- India manufacturing corridor penetration:PLI scheme incentives for electronics assembly are creating first-time demand for climate-controlled production environments.
Industry Challenges
- Metrology talent scarcity:Skilled calibration technicians capable of traceable humidity standard maintenance are concentrated in established testing laboratories.
- Multi-standard certification complexity:Harmonization gaps between IEC and ISO working groups delay cross-border market access for instrument manufacturers.
- Legacy system integration friction:Analog-output humidity probes in existing building management networks resist digital retrofit without controller replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humidity Testers Market |
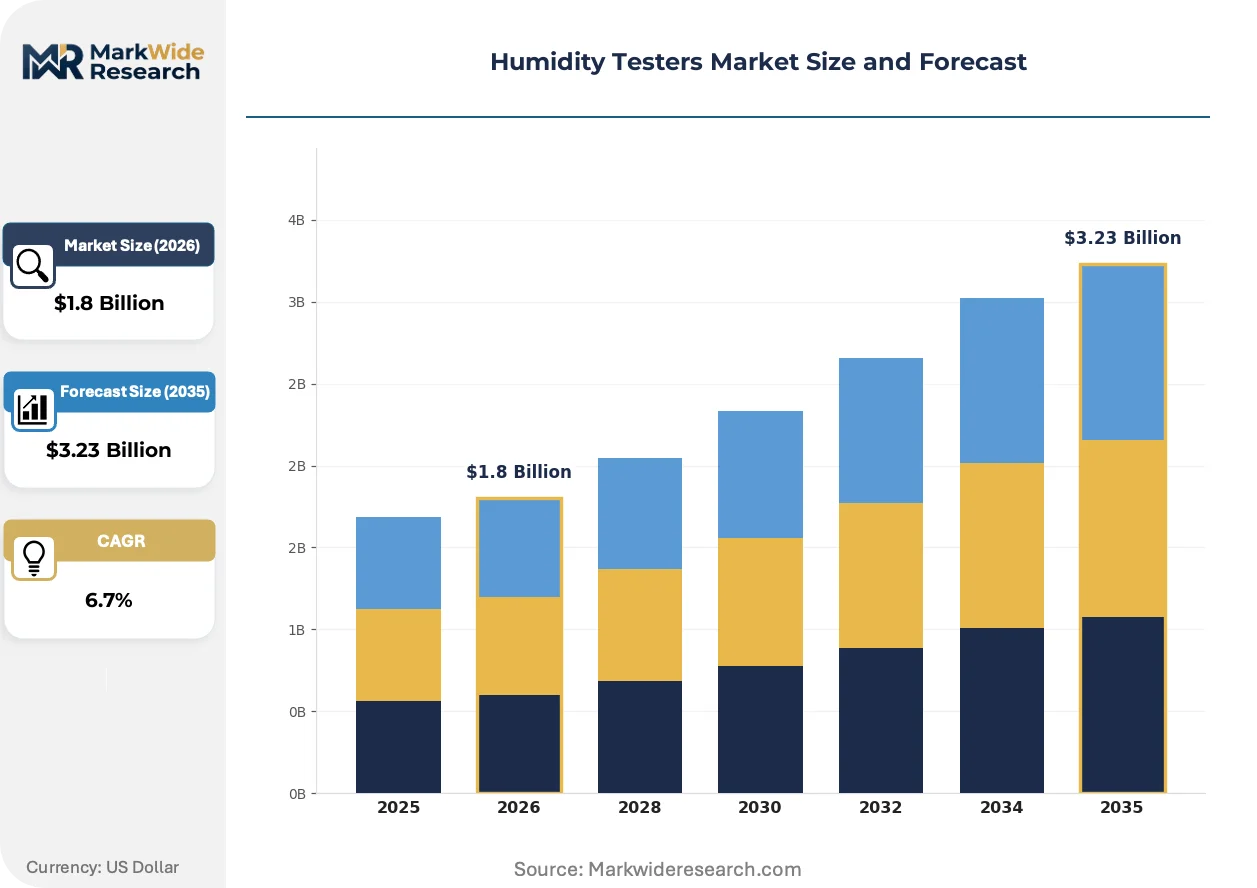
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Hygrometers, Analog Hygrometers, Psychrometers, Humidity Data Loggers End User: Consumer Electronics, Industrial Manufacturing, Agriculture, HVAC Systems Technology: Capacitive Sensors, Resistive Sensors, Thermal Sensors, Optical Sensors Application: Weather Stations, Greenhouses, Storage Facilities, Museums |
| Companies Covered | Honeywell International Inc., Sensirion AG, Bosch Sensortec GmbH, Texas Instruments Incorporated, TE Connectivity Ltd, Amphenol Advanced Sensors, Fluke Corporation, Vaisala, Rotronic AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humidity Testers Market Strategic Shifts
Sensor fusion architectures are redrawing competitive boundaries as humidity measurement converges with pressure and temperature sensing in single-package environmental modules.
Optical chilled-mirror hygrometry is fragmenting the high-precision industrial segment, where NIST-traceable accuracy requirements exceed capacitive sensor limits. Pharmaceutical manufacturers and metrology laboratories are adopting these instruments for critical validation protocols. The technology is fragmenting vendor portfolios into dual-track offerings separating premium reference-grade from production-line instruments.
Japan's METI is tightening JIS certification requirements for industrial environmental measurement instruments, creating compliance barriers for uncertified imports. Japanese automotive and electronics manufacturers are demanding domestic-standard verification for supplier qualification. This regulatory tightening is compressing market access timelines for European and North American instrument vendors.
Buyer consolidation among semiconductor foundries is compressing procurement cycles and unbundling after-sales calibration services. Large-scale Taiwan and South Korea fabs are negotiating direct sensor supply agreements with MEMS foundries, bypassing traditional instrument distributors. This channel disintermediation is most visible in East Asian manufacturing corridors where volume concentration enables custom specification negotiations.
Humidity Testers Market Segmentation
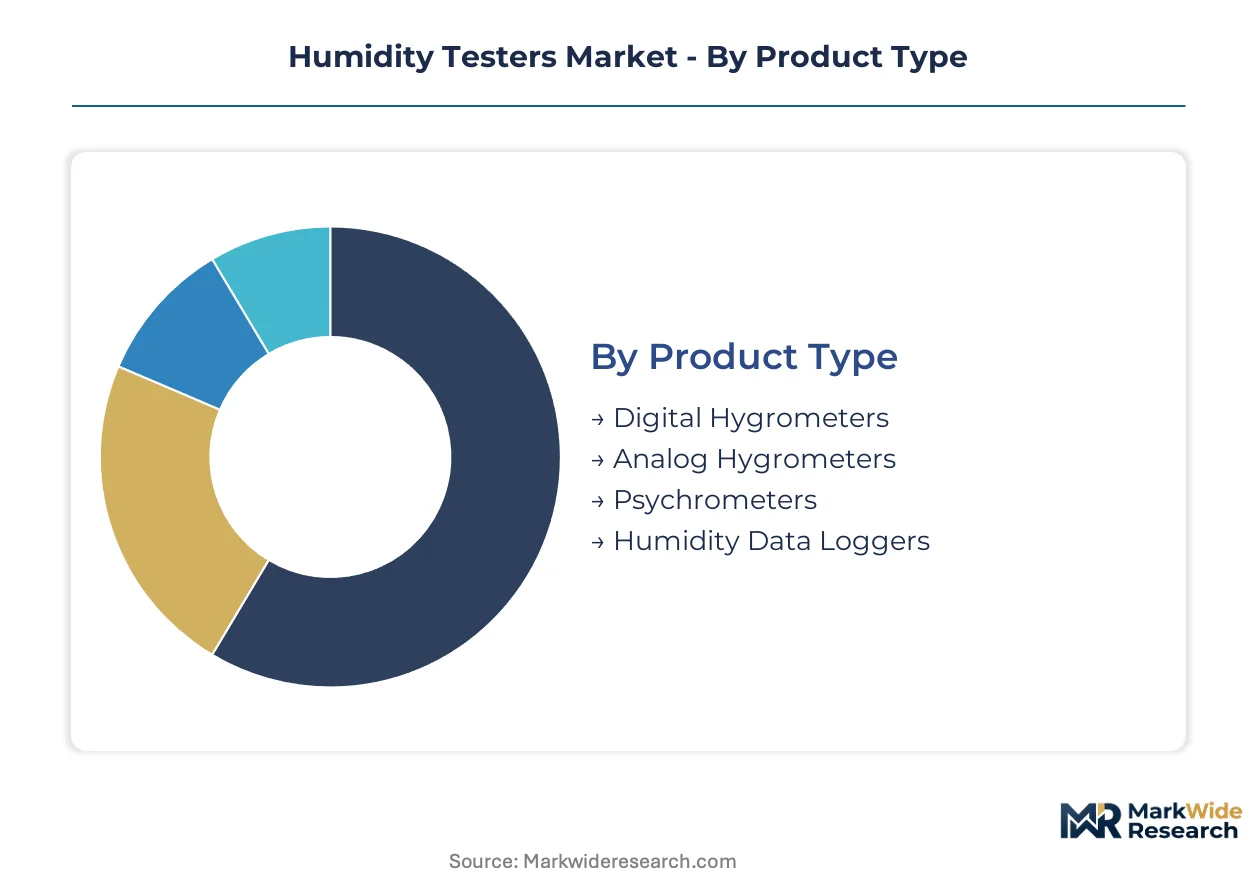
Humidity testers serve fundamentally different calibration and connectivity requirements across product architectures, with channel economics varying sharply between integrated building automation networks and standalone field instruments. Understanding how each segment flows through distributor, direct OEM, and service-contract channels shapes procurement strategy and margin capture.
Product Type:
Digital hygrometers move primarily through building automation distributors serving facility management contracts, while data loggers channel through pharmaceutical validation specialists with attached calibration services.
- Digital Hygrometers:These instruments integrate thin-film polymer capacitive sensors with digital output protocols for direct BMS integration. Demand concentrates in Taiwan and South Korea semiconductor fabs requiring ±2% RH accuracy for cleanroom yield protection.
- Humidity Data Loggers:Battery-powered devices with onboard memory and USB or wireless data retrieval for regulatory documentation. Pharmaceutical cold chain operators across Europe face expanding FDA and EMA good distribution practice mandates driving procurement.
- Analog Hygrometers:Dial-display instruments with bimetallic or hair-tension sensing elements for basic industrial monitoring.
- Psychrometers:Wet-bulb/dry-bulb differential instruments used in HVAC commissioning and meteorological calibration.
By volume, Digital Hygrometers leads. By growth pace, Humidity Data Loggers is ahead.
End User:
Cost tiers separate premium calibrated instruments for regulated manufacturing from economy units for residential and light commercial applications.
- Industrial Manufacturing:Precision instruments with NIST-traceable calibration certificates for quality-critical production environments. Taiwan Semiconductor Manufacturing Company and Samsung Electronics fabs specify custom humidity mapping protocols for advanced node production.
- HVAC Systems:Mid-tier sensors with 4-20mA or Modbus outputs for building climate control. EU F-Gas Regulation compliance is tightening refrigerant monitoring requirements across European cold chain logistics operators.
- Consumer Electronics:Miniaturized MEMS sensors for smartphones and wearables with sub-1% RH accuracy.
- Agriculture:Weather-resistant probes for greenhouse and livestock facility monitoring with simplified calibration cycles.
Industrial Manufacturing commands the highest price points. Consumer Electronics ships the largest unit volumes.
Technology:
Supply concentration for MEMS dielectrics favors capacitive architectures, while resistive and thermal alternatives serve cost-sensitive or extreme-environment niches.
- Capacitive Sensors:Thin-film polymer dielectrics alter electrical capacitance proportionally to moisture absorption. Honeywell's captive MEMS foundry in Minnesota controls supply chains from raw silicon to calibrated modules.
- Optical Sensors:Laser-based chilled-mirror or infrared absorption hygrometry for corrosive industrial atmospheres where electrolytic degradation threatens polymer probes. Pharmaceutical manufacturers adopt these for critical validation protocols exceeding capacitive accuracy limits.
- Resistive Sensors:Bulk or thin-film ceramic elements with resistance varying by humidity, common in residential and automotive applications.
- Thermal Sensors:Absolute humidity measurement through thermal conductivity differential, used in high-temperature industrial processes.
Capacitive Sensors dominates installed base. Optical Sensors is climbing the fastest on pharmaceutical and metrology laboratory demand.
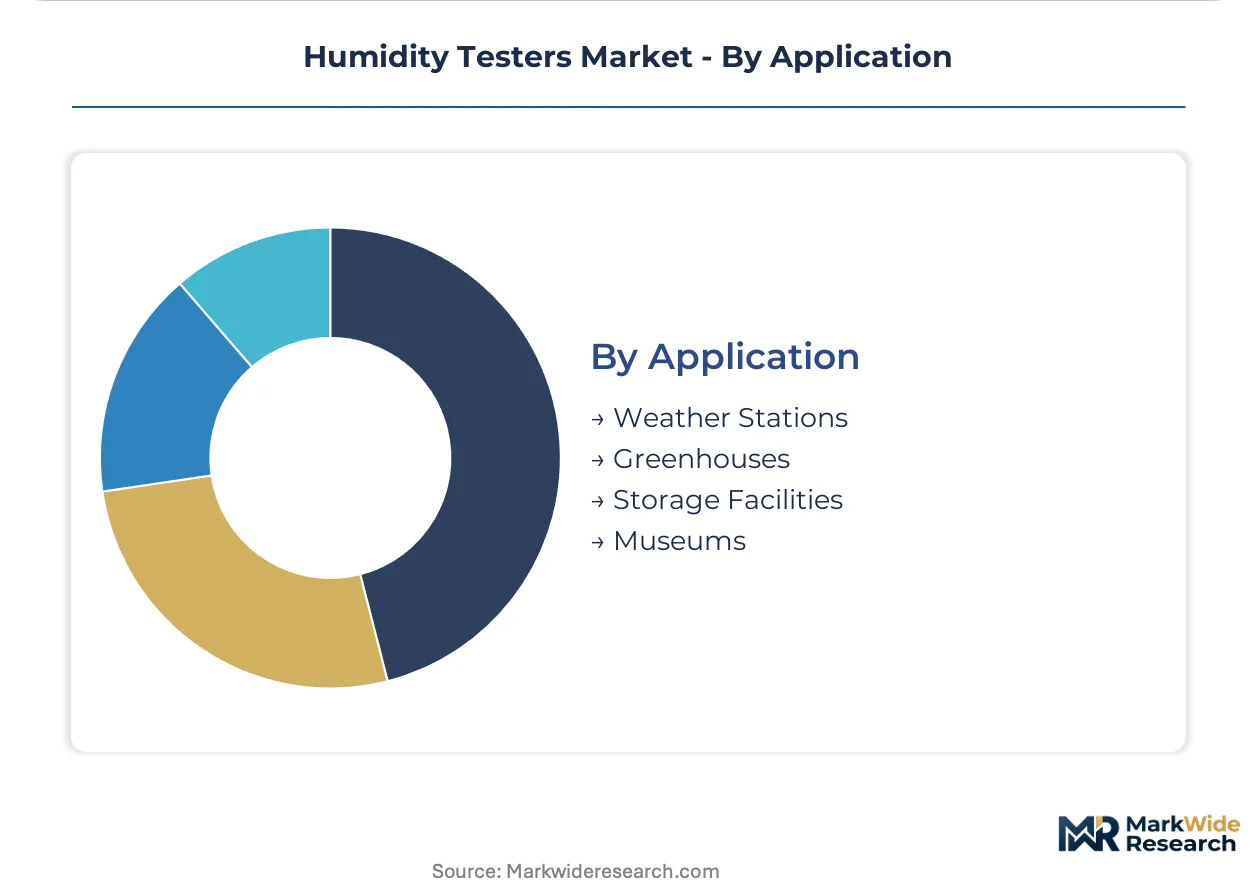
Application:
Customer type segmentation separates institutional buyers with multi-year service contracts from fragmented retail and small commercial purchasers.
- Storage Facilities:Continuous monitoring systems for pharmaceutical, food, and electronics warehouses with alarm integration. EU cold chain operators must install humidity tracking for compressor efficiency diagnostics under F-Gas Regulation mandates.
- Greenhouses:Precision control systems integrating humidity with CO2 and temperature management for optimized crop yields.
- Weather Stations:Meteorological-grade instruments with radiation shields and aspirated housings for national meteorological services.
- Museums:Low-drift instruments for artifact conservation with strict humidity stability requirements.
Storage Facilities generates the most instrument revenue per site. Greenhouses is gaining share fastest on controlled-environment agriculture expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in pharmaceutical and semiconductor applications accept premium pricing for calibrated precision, while agricultural and residential segments drive hard bargains on commodity sensors. Taiwan and South Korea fabs prioritize yield protection over unit cost. European cold chain operators face compliance-driven procurement timelines.
United States
Semiconductor fabs in Arizona and Texas are expanding cleanroom environmental monitoring for advanced node production. The EPA enforces Indoor airPLUS certification standards that mandate humidity monitoring in new residential construction. Boston-area pharmaceutical manufacturers drive demand for NIST-traceable validation instruments.
Germany
Automotive battery manufacturers are integrating humidity sensing into cell conditioning systems for electric vehicle production. The EU F-Gas Regulation compels cold chain logistics operators to install continuous humidity tracking for compressor efficiency diagnostics. Stuttgart's industrial automation cluster sources precision instruments for manufacturing quality control.
Japan
Electronics manufacturers demand domestic-standard verification for supplier qualification under tightening procurement protocols. METI oversees JIS standards for industrial environmental measurement instruments, creating compliance barriers for uncertified imports. Osaka-Kobe manufacturing corridor facilities specify custom humidity mapping for precision component assembly.
South Korea
Samsung Electronics and SK Hynix fabs are negotiating direct sensor supply agreements with MEMS foundries, bypassing traditional instrument distributors. The country's national industrial standards body enforces calibration traceability requirements for cleanroom certification. Pyeongtaek semiconductor complex operators specify ±2% RH accuracy instruments for yield protection.
India
Electronics assembly incentives under the PLI scheme are creating first-time demand for climate-controlled production environments in emerging manufacturing corridors. The Bureau of Indian Standards is developing harmonized protocols for environmental measurement instrument certification. Tamil Nadu and Karnataka contract manufacturers are installing humidity monitoring for smartphone and component assembly lines.
Humidity Testers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in humidity testing equipment. Captive MEMS foundries control supply chains from raw silicon through calibrated modules, while fabless designers face procurement bottlenecks for precision polymer dielectrics. Three archetypes dominate: vertically integrated industrial conglomerates, Swiss precision specialists, and Asian volume producers. Competitive moves center on backward integration into wafer fabrication and geographic expansion into India manufacturing corridors.
Within the integrated industrial tier, Honeywell International Inc. and Bosch Sensortec GmbH exemplify scale-driven positioning through captive semiconductor operations. Sensirion AG represents the precision specialist archetype, anchoring Swiss engineering credibility against lower-cost alternatives. These three companies illustrate how supply chain control and geographic origin signal capability to procurement teams in semiconductor and pharmaceutical applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sensirion AG |
| Bosch Sensortec GmbH |
| Texas Instruments Incorporated |
| TE Connectivity Ltd |
| Amphenol Advanced Sensors |
| Fluke Corporation |
| Vaisala |
| Rotronic AG |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with East Asian MEMS foundries lock in both polymer dielectric supply access and price visibility for instrument manufacturers serving Taiwan and South Korea semiconductor fabs. These arrangements insulate calibration-intensive producers from spot-market volatility in raw silicon wafers while compressing margins for fabless competitors forced into secondary procurement channels.
Pricing Analysis
After-sales calibration service contracts drive lifetime value for precision instrument vendors, with NIST-traceable recertification programs generating recurring revenue streams that offset upfront hardware compression. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade validated units from basic industrial sensors and residential commodity probes. Cost compression in the economy tier is intensifying because Indian contract manufacturers are scaling climate-controlled assembly lines under PLI scheme incentives. Pharmaceutical cold chain operators show least price sensitivity due to FDA and EMA compliance mandates, while agricultural greenhouse buyers negotiate aggressively on per-unit sensor costs.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai and Busan elevate inbound logistics costs for European and North American instrument assemblers sourcing MEMS die from East Asian foundries. Wafer fabrication concentrates in Taiwan, South Korea, and select Minnesota-based captive facilities, while precision polymer dielectrics and reference-grade humidity chambers draw from Swiss and German specialty chemical suppliers. Single-source vulnerability in advanced node MEMS capacity threatens procurement continuity for fabless designers lacking foundry partnerships. Distribution runs through building automation distributors for digital hygrometers and pharmaceutical validation specialists for data logger deployments with attached calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fusion architectures and diverging certification requirements across Japan's METI, the EU F-Gas Regulation, and EPA Indoor airPLUS standards fragment demand into specialized niches that reward focused positioning over broad portfolio plays.
For Market Incumbents: Secure captive wafer supply through foundry joint ventures or equity stakes in Taiwan and South Korea MEMS facilities to defend against fabless entrants facing polymer dielectric procurement bottlenecks. Deepen backward integration into calibration chamber manufacturing to capture service-contract margins that distributors currently extract from pharmaceutical validation workflows. Optical chilled-mirror substitution in corrosive industrial atmospheres threatens capacitive sensor incumbents in metrology laboratory segments. For New Entrants and Emerging Players: Cloud-connected calibration-as-a-service platforms represent the most penetrable white space where Honeywell and Sensirion under-serve mid-tier industrial manufacturers lacking in-house metrology expertise. Target India's emerging electronics manufacturing corridors in Tamil Nadu and Karnataka where PLI scheme incentives are creating first-time demand for climate-controlled production environments without entrenched supplier relationships. Lead with subscription-based sensor health monitoring to bypass capital-intensive calibration equipment barriers. For Investors and Strategic Acquirers: Swiss precision specialists with JIS certification capabilities and pharmaceutical validation track records offer the strongest acquisition target archetype for exposure to premium-migration trends in East Asian semiconductor and European cold chain applications. Long-term viability hinges on regulatory harmonization between IEC and ISO working groups enabling cross-border instrument certification. Watch for METI enforcement actions accelerating domestic-standard verification requirements as the inflection indicator for Japanese market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Captive wafer supply secures polymer dielectric access for Taiwan and South Korea fab procurement cycles. |
| Calibration-as-a-Service Platform Launch | Cloud-based recertification captures pharmaceutical cold chain operators facing FDA and EMA documentation mandates. |
| JIS Certification Investment | Domestic-standard verification enables supplier qualification with Osaka-Kobe electronics manufacturers under METI oversight. |
| Battery Thermal Management Partnership | Humidity-temperature sensor fusion aligns with Stuttgart automotive battery manufacturers' cell conditioning requirements. |
| India Manufacturing Corridor Expansion | Tamil Nadu and Karnataka assembly lines under PLI scheme incentives create first-time climate control demand. |
Study Parameters
The analysis maps digital hygrometer, humidity data logger, and analog instrument sub-sectors, each validated through primary interviews with cleanroom facility managers, pharmaceutical validation specialists, MEMS foundry procurement leads, and building automation system integrators. Secondary sources include IEC and ISO working group documentation, EPA Indoor airPLUS certification records, EU F-Gas Regulation implementation guidance, and customs trade data for environmental measurement instrument flows. Bottom-up segment sizing triangulates against top-down semiconductor fab capital expenditure tracking and pharmaceutical cold chain infrastructure investment patterns.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor cleanroom environmental monitoring procurement disclosures, pharmaceutical distribution network expansion filings, and regional HVAC system upgrade cycles. Segmentation dimensions modeled encompass product architecture, end-use industry, sensor technology, and application environment across the projection horizon. CAGRs derive from unit shipment trajectories by segment married to average selling price evolution reflecting certification tier and after-sales service bundling. Forecast inputs incorporate Taiwan and South Korea fab yield protection protocols and EU cold chain operator compliance timelines.
Forecasts assume regulatory continuity in EPA indoor air quality mandates, EU F-Gas refrigerant monitoring requirements, and Japan METI JIS certification frameworks; material policy shifts would require re-modeling. Sensor accuracy standard harmonization gaps between IEC and ISO working groups present revision risk to cross-border market access assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Impedance Tester Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Metrology Software Market
Test and Measurement
EMC Testing Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Signal Generator Market
Test and Measurement
Tribometer Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market