
 Pump Testers Market | 2026-2036
Pump Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Testers Market Outlook
Chinese pump component foundries is broadening the accessible supply base for test bench manufacturers worldwide. Cat Pumps leverages its ceramic plunger expertise to dominate high-pressure validation rigs for downstream oil applications. Pressure Jet sustains cost-competitive positioning across Asian marine and industrial pump servicing channels. Hydratron anchors its reputation on hydrostatic test systems for subsea valve and pump qualification programs.
Pump testers are precision instruments designed to measure flow rate, pressure head, power consumption, and efficiency across centrifugal and positive displacement pump configurations, typically operating at pressures from atmospheric to 10,000 psi depending on the test protocol. These systems serve the fundamental industrial purpose of certifying pump performance against manufacturer curves and regulatory standards before field deployment. Rotary and reciprocating product categories command the deepest installed base due to their prevalence in hydrocarbon processing and power generation fluid handling circuits. Electronic and smart technology segments are capturing disproportionate R&D investment as end-users shift from periodic manual calibration toward continuous condition monitoring with embedded diagnostic algorithms.
API standards enforced by the American Petroleum Institute, ISO 9906 hydraulic performance test codes, and EPA emissions compliance protocols collectively shape product design specifications and qualification requirements for pump testers serving regulated industries. FDA cGMP guidelines additionally govern validation protocols when pump testers support pharmaceutical fluid transfer equipment certification. Stakeholders must weigh capital allocation between expanding electronic test platform capabilities and defending mechanical system service revenue as customer procurement criteria evolve toward integrated data analytics and remote audit readiness.
Market Dynamics
Smart sensor integration is compressing calibration cycles from annual manual checks to continuous automated monitoring, forcing test bench manufacturers to reconfigure hardware architectures and software stacks around embedded diagnostic algorithms rather than standalone gauge assemblies.
Growth Catalysts
- API certification protocols:North American oil and gas pipeline operators are expanding metrology budgets to comply with stricter American Petroleum Institute standards for pump performance validation.
- Shale field redevelopment:United States upstream operators are signing recurring calibration service contracts to maintain flow assurance across aging Permian and Bakken infrastructure.
- Ceramic plunger technology:Advanced ceramic materials are extending test rig pressure ratings above 10,000 psi for downstream refinery hydrostatic validation programs.
Market Restraints
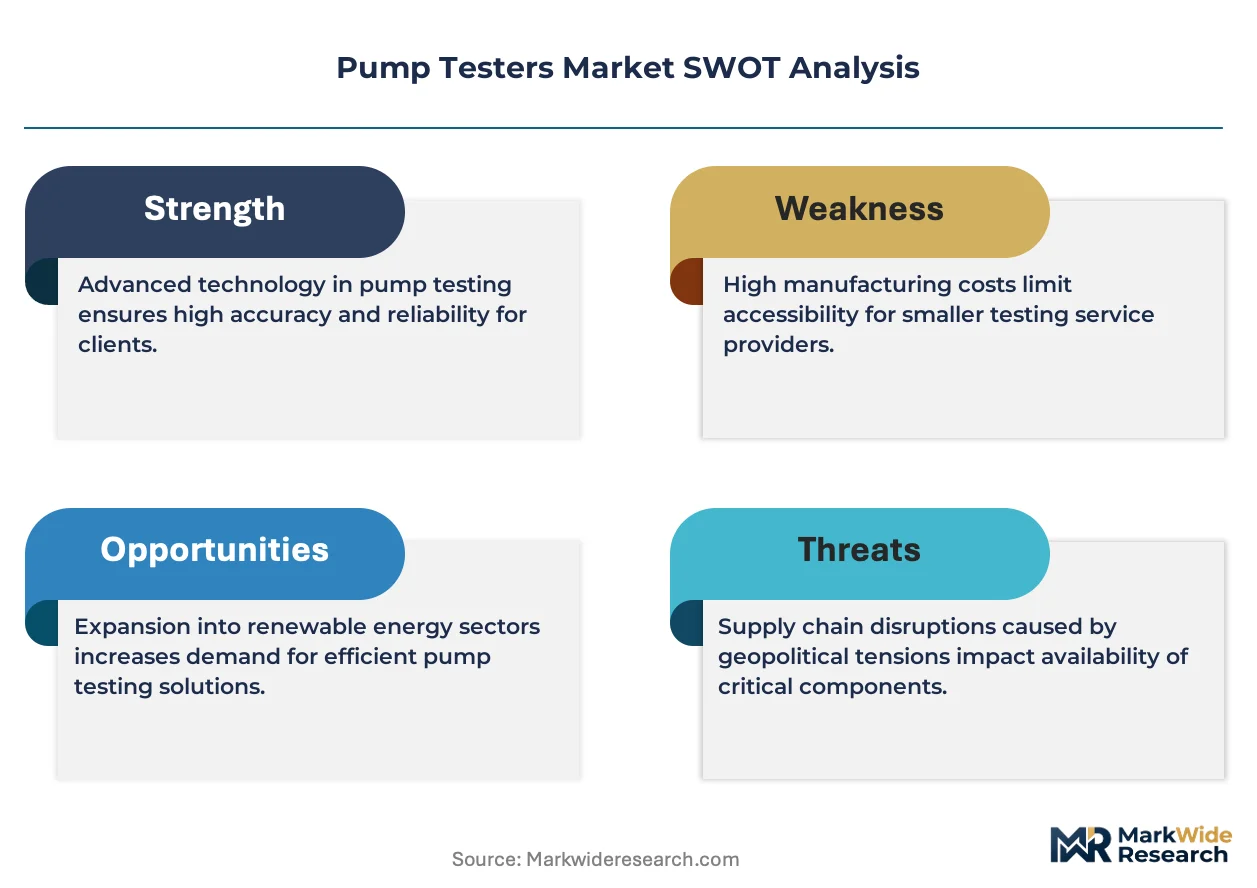
- Specialized alloy input costs:Nickel-based superalloys for high-pressure test fixtures face price volatility tied to mining concentration in specific extraction zones.
- Foundry supply concentration:Chinese pump component foundries control critical casting capacity for test bench chassis and manifold assemblies.
- Mechanical gauge obsolescence:Existing installed base of analog dial configurations creates stranded asset risk for service providers with legacy rental fleets.
Strategic Opportunities
- Subsea qualification programs:Deepwater valve and pump testing for offshore Brazil and West Africa fields requires hydrostatic systems rated for simulated seabed pressure conditions.
- Pharmaceutical fluid transfer:FDA cGMP guidelines create validation protocol demand for sanitary pump testers in biologics manufacturing expansion.
- Remote audit readiness:Cloud-connected test platforms with automated documentation generation address buyer requirements for distributed quality assurance.
Industry Challenges
- Embedded systems engineering talent:Firmware development for real-time pressure transducer signal processing exceeds available skilled labor pools in traditional mechanical instrumentation hubs.
- ISO 9906 compliance timelines:Hydraulic performance test code certification requires extended validation runs that compress equipment utilization rates and extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Testers Market |
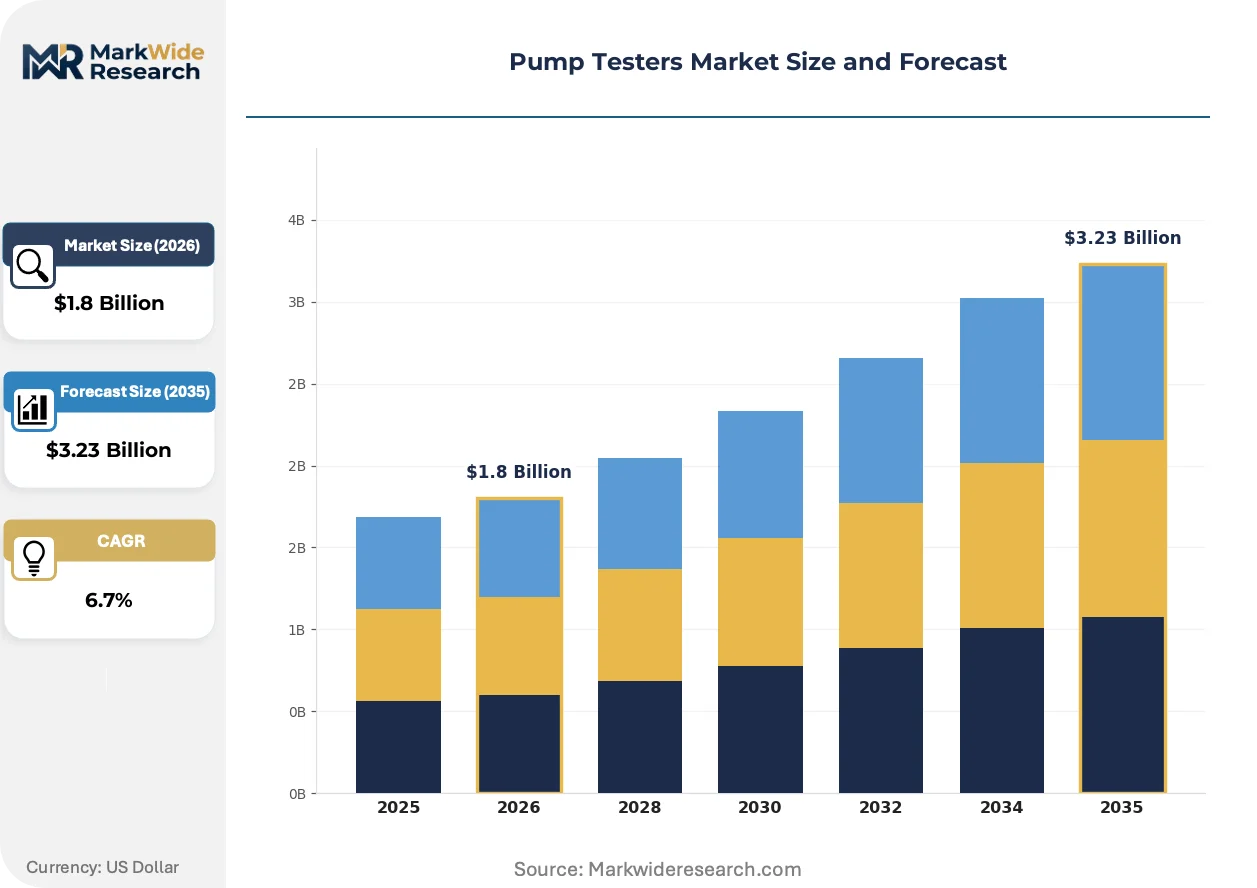
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Reciprocating, Gear, Diaphragm Application: Aerospace, Automotive, Oil & Gas, Manufacturing End User: Industrial, Laboratory, Automotive Services, Educational Institutions Technology: Mechanical, Electronic, Smart, Pneumatic |
| Companies Covered | Cat Pumps, Pump Works, Pressure Jet, Rothenberger, PROCESS PUMPS AND EQUIPMENT, Cascon, Condor Pump, Hydratron, Roper Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Testers Market Strategic Shifts
Digital thread architecture is redefining how pump performance data flows from test floor to asset management systems, collapsing the boundary between validation equipment and operational technology infrastructure.
Edge computing hardware is decentralizing data processing away from centralized test control rooms. Downstream refinery maintenance teams are deploying ruggedized industrial PCs directly onto test skids for millisecond-level pressure anomaly detection. This topology is decentralizing diagnostic authority from centralized engineering departments to field technicians.
EPA emissions compliance protocols are tightening leak detection requirements for reciprocating pump packing systems. Refinery operators must now document methane containment during pressure cycling tests. API 674 and API 675 pump categories face the steepest documentation burdens, driving demand for sealed test enclosures with integrated gas analyzers.
Asset-as-a-service contracting is restructuring how midstream operators acquire test capacity. Compression of capital expenditure approval cycles favors rental and subscription models over equipment ownership. United States shale patch independents are consolidating vendor relationships around providers offering bundled calibration, certification, and remote technical support.
Pump Testers Market Segmentation
Pump tester procurement decisions hinge on certification alignment—different segments carry distinct API, ISO 9906, and EPA compliance burdens that reshape hardware specifications and validation protocols. Understanding these segment boundaries clarifies where R&D budgets concentrate versus where maintenance revenue pools stabilize.
Product Type:
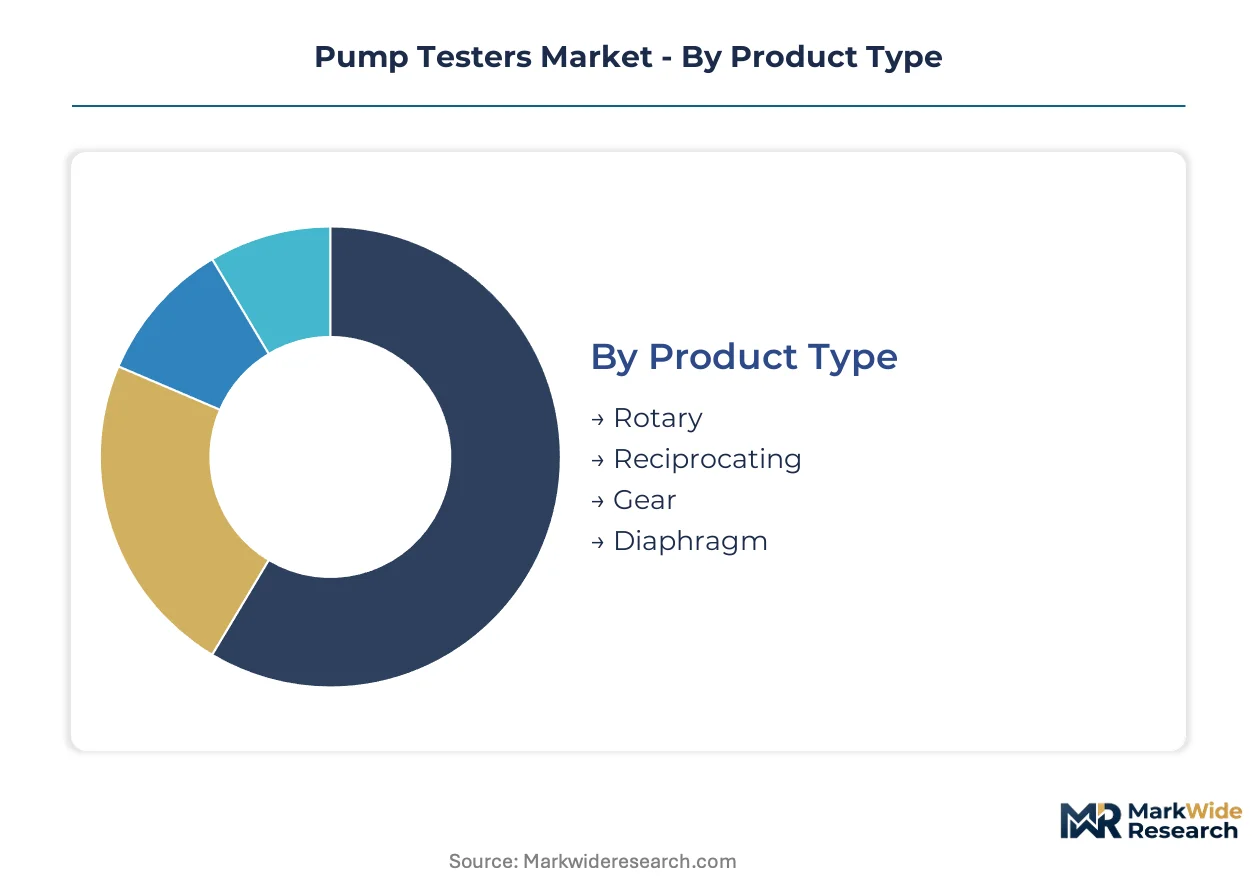
API 674 and API 675 standards impose the heaviest documentation burdens on rotary and reciprocating configurations, while gear and diaphragm variants face lighter regulatory loads but stricter FDA cGMP protocols in pharmaceutical settings.
- Rotary:Centrifugal and axial flow configurations dominate hydrocarbon processing circuits with continuous duty cycles. Permian Basin operators are expanding rotary test rig fleets to manage shale field flow assurance across aging gathering systems. Rotary sits at the top of the volume ranking, with reciprocating climbing the fastest.
- Reciprocating:Positive displacement piston and plunger designs achieve pressure ratings exceeding 10,000 psi for downstream refinery hydrostatic validation. Downstream maintenance programs are displacing mechanical gauge configurations with smart sensor integration on these high-pressure rigs.
- Gear:Interlocking rotor designs suit viscous fluid handling in marine and industrial lubrication systems.
- Diaphragm:Seal-less construction meets sanitary requirements for biologics manufacturing fluid transfer equipment.
Reciprocating systems command the steepest expansion trajectory as ceramic plunger technology extends pressure envelopes for subsea qualification programs.
Application:
Cost tier differentiation separates aerospace validation programs—where NADCAP accreditation drives six-figure test cell investments—from manufacturing floor acceptance testing where portable units suffice.
- Aerospace:Fuel system and hydraulic actuation pump testing requires precision flow measurement within 0.25% uncertainty bands. FAA certification protocols and NADCAP special process accreditation create substantial entry barriers for test equipment suppliers serving tier-one aerostructures manufacturers.
- Automotive:Powertrain cooling system and transmission pump validation spans OEM development labs and tier supplier quality gates. EPA emissions compliance protocols are tightening leak detection documentation requirements for electric vehicle thermal management pump assemblies.
- Oil & Gas:Upstream flow assurance and downstream hydrostatic validation represent the deepest installed base for high-pressure test systems.
- Manufacturing:General industrial pump acceptance testing favors cost-optimized electronic platforms over laboratory-grade instrumentation.
Oil and gas retains the largest revenue footprint, though automotive is gaining share fastest as electrification reshapes thermal management architectures.
End User:
Customer type stratification mirrors capital intensity gradients—industrial facilities amortize equipment over decade-long depreciation schedules while laboratory procurement prioritizes measurement uncertainty and calibration traceability.
- Industrial:Refinery, chemical plant, and pipeline operator demand concentrates in the United States where shale field redevelopment drives recurring calibration service contracts. Industrial buyers favor asset-as-a-service contracting to compress capital expenditure approval cycles.
- Laboratory:National metrology institutes and third-party certification bodies require ISO 17025 accredited calibration chains with documented measurement uncertainty budgets. These procurement specifications favor electronic and smart technology platforms with embedded diagnostic algorithms.
- Automotive Services:Independent repair and remanufacturing operations seek cost-competitive mechanical gauge configurations for aftermarket pump validation.
- Educational Institutions:University engineering programs and vocational training centers prioritize durable, low-maintenance test benches for instructional fluid mechanics laboratories.
Industrial installations dominate the installed base, with laboratory demand expanding most quickly as third-party certification outsourcing accelerates.
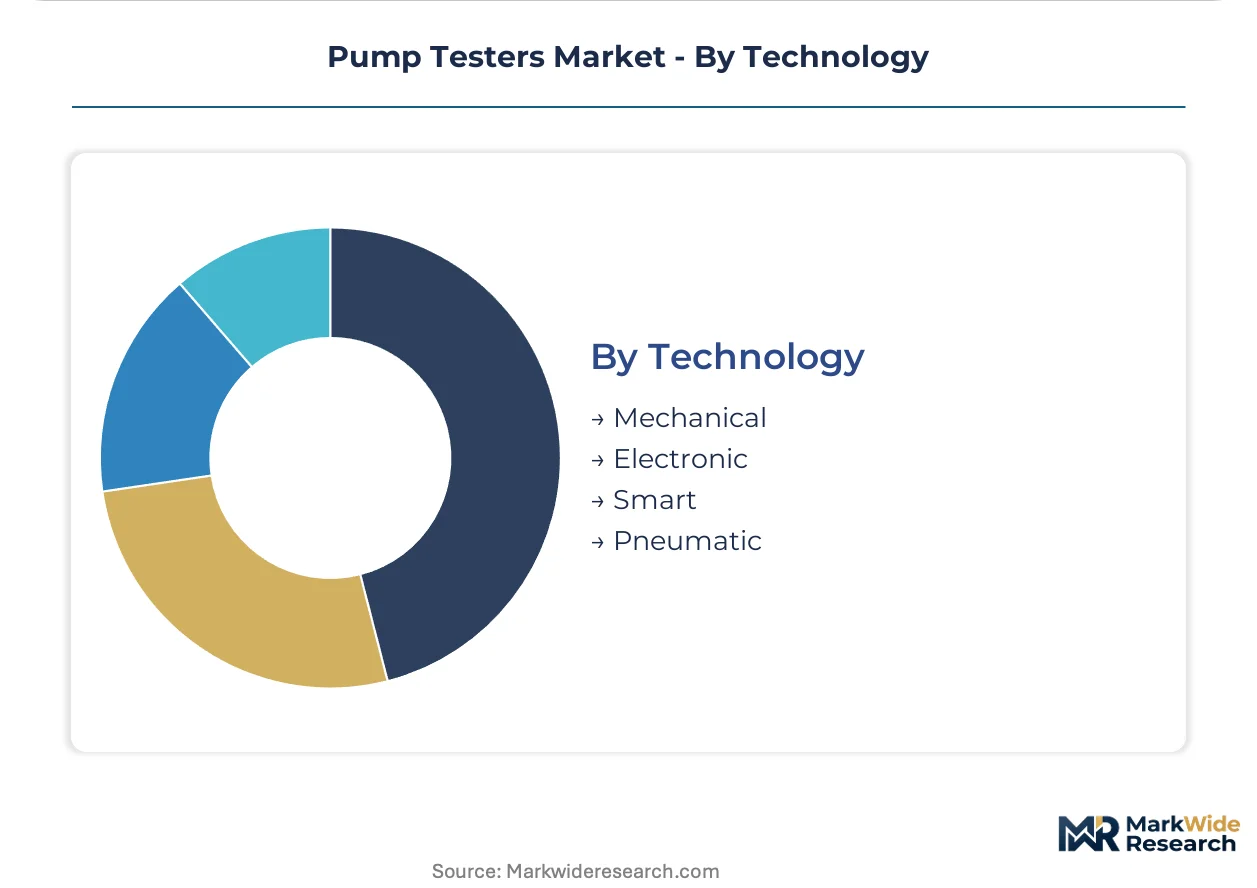
Technology:
Margin concentration favors smart platforms where firmware-enabled predictive maintenance commands subscription pricing, while mechanical systems compete on upfront capital cost alone.
- Mechanical:Analog dial gauge configurations retain residual demand in developing economy industrial sectors and educational settings. The installed base creates stranded asset risk for service providers with legacy rental fleets as end-users shift procurement criteria toward data analytics integration.
- Electronic:Digital pressure transducers and programmable logic controllers displaced standalone gauge assemblies across midstream oil and gas metrology programs. These platforms satisfy API certification protocols without requiring full smart sensor architectures.
- Smart:Embedded diagnostic algorithms and cloud connectivity enable continuous condition monitoring with automated documentation generation for remote audit readiness. Firmware development for real-time signal processing exceeds available skilled labor pools in traditional mechanical instrumentation hubs.
- Pneumatic:Compressed air-driven test systems serve explosive atmosphere environments where electrical ignition sources are prohibited.
Electronic platforms anchor current revenue, with smart technology climbing fastest as edge computing hardware decentralizes diagnostic authority to field technicians.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States shale operators outspend Canadian pipeline counterparts on metrology equipment, while Chinese foundries supply test bench chassis to manufacturers worldwide.
United States
Permian Basin redevelopment drives recurring calibration service contracts for aging gathering infrastructure. EPA emissions compliance protocols tighten documentation requirements for reciprocating pump packing systems during pressure cycling tests. Houston anchors the largest concentration of oil and gas pipeline metrology programs.
China
Pump component foundries in Zhejiang and Jiangsu provinces broaden accessible supply bases for test bench manufacturers globally. MIIT industrial standards govern pressure equipment certification for domestic hydrocarbon processing expansion. Shanghai manufacturers export electronic test platforms to Southeast Asian refinery maintenance programs.
Germany
REACH chemical safety regulations shape material specifications for high-pressure test fixtures serving pharmaceutical fluid transfer equipment. Ruhr Valley industrial clusters demand ISO 9906 compliant validation rigs for chemical plant pump refurbishment. Bavaria hosts precision instrumentation engineering talent pools for smart sensor firmware development.
Brazil
Pre-salt deepwater field development requires hydrostatic test systems rated for simulated seabed pressure conditions. ANVISA pharmaceutical regulations create validation protocol demand for sanitary pump testers in biologics manufacturing. Rio de Janeiro offshore service bases concentrate subsea valve and pump qualification programs.
Saudi Arabia
Aramco downstream expansion drives demand for ceramic plunger test rigs exceeding 10,000 psi ratings. SFDA pharmaceutical guidelines govern validation protocols for sterile fluid transfer equipment in biomanufacturing zones. Jubail Industrial City clusters hydrostatic test capacity for regional refinery maintenance outsourcing.
Pump Testers Market Competitive Environment
United States producers anchor one tier; German and Chinese specialists hold adjacent positions in precision instrumentation and foundry supply respectively. The vendor base separates into three strategic tiers: multinational industrial conglomerates with diversified fluid handling portfolios, mid-scale test equipment specialists focused on certification-aligned hardware, and regional fabricators serving cost-sensitive maintenance channels. Two dominant competitive moves define current positioning: backward integration into ceramic plunger manufacturing for pressure rating extension, and strategic partnerships with cloud infrastructure providers for remote audit readiness platforms.
Among the named participants, Cat Pumps exemplifies the high-pressure validation specialist archetype through its ceramic plunger technology positioning. Pressure Jet occupies a position within Asian marine and industrial servicing channels. Hydratron anchors the subsea qualification segment with hydrostatic system specialization.
| Leading Market Players |
|---|
| Cat Pumps |
| Pump Works |
| Pressure Jet |
| Rothenberger |
| PROCESS PUMPS AND EQUIPMENT |
| Cascon |
| Condor Pump |
| Hydratron |
| Roper Technologies |
| Others |
Value Chain & Pricing Dynamics
API certification protocol tightening across North American oil and gas operators is forcing test bench manufacturers to absorb specialized alloy input costs for high-pressure fixtures, compressing margins on mechanical gauge configurations while rewarding ceramic plunger technology investments with pricing power.
Pricing Analysis
Distributor margins on electronic test platforms run 15-20 points thinner than mechanical gauge rentals due to bundled firmware support obligations. Three-tier pricing structure across premium smart sensor systems, standard electronic transducer rigs, and economy mechanical configurations reflects certification grade and after-sales service bundling. Cost compression in the mechanical tier is intensifying because shale field independents are consolidating vendor relationships around asset-as-a-service providers. Laboratory procurement committees show least price sensitivity, prioritizing ISO 17025 traceability over capital expenditure minimization.
Supply Chain Analysis
API and ISO 9906 qualification gating restricts qualified foundry sources for nickel-based superalloy castings to Chinese pump component suppliers in Zhejiang and Jiangsu provinces, German precision machining clusters in Bavaria, and domestic US specialty alloy fabricators. Test bench chassis and manifold assemblies draw from Chinese casting capacity, ceramic plunger blanks source from Japanese advanced materials specialists, and pressure transducer modules feed from German sensor engineering houses. Single-source vulnerability concentrates in Chinese foundry supply for high-pressure test fixtures. Distribution runs through direct OEM relationships for large refinery operators and rental fleet aggregators for shale patch independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pump testers market functions as a stable compounder anchored by recurring calibration service contracts tied to aging Permian and Bakken infrastructure with mandated API compliance refresh cycles.
For Market Incumbents: Lock in ceramic plunger supply agreements with Japanese advanced materials specialists before competitor backward integration captures capacity. Expand firmware development teams in Bavaria to address embedded systems engineering talent scarcity threatening smart platform roadmaps. Defend service revenue pools by converting mechanical gauge rental fleets to electronic platforms ahead of stranded asset risk realization. For New Entrants and Emerging Players: Regional fabricators serving cost-sensitive marine servicing channels in Southeast Asia represent the most penetrable entry point. Target pharmaceutical fluid transfer validation protocols where FDA cGMP guidelines create documentation-intensive demand underserved by oil and gas-focused incumbents. Partner with cloud infrastructure providers to deliver remote audit readiness platforms without building proprietary data architectures. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale test equipment specialists holding ISO 9906 certification alignment and captive ceramic plunger manufacturing capacity. Five-to-ten-year viability rests on conversion of maintenance revenue from periodic calibration to continuous monitoring subscriptions. Watch for inflection when shale field redevelopment capex cycles trigger consolidation of vendor relationships around bundled service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Plunger Manufacturing | Captures pressure rating extension capability and insulates margin from nickel superalloy volatility. |
| Cloud Infrastructure Partnership for Remote Audit Platforms | Addresses buyer requirements for distributed quality assurance without proprietary data center investment. |
| Firmware Development Talent Acquisition in Bavaria | Secures embedded diagnostic algorithm capabilities exceeding availability in traditional mechanical instrumentation hubs. |
| Asset-as-a-Service Contracting Model Expansion | Compresses capital expenditure approval cycles for United States shale patch independents. |
| Pharmaceutical cGMP Validation Protocol Specialization | Opens biologics manufacturing fluid transfer equipment certification demand outside hydrocarbon processing concentration. |
Study Parameters
Direct dialogue with refinery maintenance directors, pump OEM procurement teams, third-party certification body technical managers, and aftermarket service fleet operators grounded qualitative assessment in operational reality. Secondary validation drew from API certification registry data, EPA emissions compliance filings, ISO 17025 accreditation databases, and customs records of pump component trade flows. Bottom-up equipment shipment tallies and top-down hydrocarbon processing capex allocations were triangulated to anchor volume estimates.
Segment-level outputs across rotary, reciprocating, gear, and diaphragm product types combined with technology tier splits and end-user stratification produced granular projections across the analysis window. CAGRs emerged from curve-fitting historical replacement cycles against regulatory compliance deadline clustering and shale field infrastructure age profiles. Smart sensor adoption curves incorporated edge computing hardware cost decline trajectories and firmware development labor market tightness indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to API protocol revision timing, Chinese foundry capacity expansion decisions, and embedded systems engineering graduate pipeline volumes. Deviation in ceramic plunger raw material cost trajectories or EPA methane containment enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Destructive Testing Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
EMC Testing Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
E-Beam Wafer Inspection System Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Network Tester Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market