
 Fiber Optic Tester Market | 2026-2036
Fiber Optic Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Tester Market Analysis
Chinese optical component manufacturing is realigning toward higher-precision test instrumentation for submarine and long-haul networks. EXFO Inc. leverages captive photonics R&D facilities in Quebec to sustain dominance in OTDR calibration protocols. Viavi Solutions Inc. anchors its position through deep partnerships with tier-one carriers in North America and Europe. Keysight Technologies competes by extending vector network analysis capabilities into coherent optical testing workflows.
A fiber optic tester is an electro-optical instrument that measures attenuation, return loss, and splice integrity across single-mode and multi-mode waveguides using laser sources and photodetectors with picowatt sensitivity; its primary purpose is certifying that installed fiber links meet channel performance specifications before network activation. The product type dimension shows OTDR instruments commanding the largest revenue pool due to their irreplaceable role in fault localization, while power meters and light sources generate steady replacement demand from field technician fleets. Technology segmentation reveals single-mode testers pulling ahead as submarine and metro networks abandon legacy multi-mode infrastructure for 400G coherent transmission.
The FCC in the United States mandates rigorous fiber certification for Rural Digital Opportunity Fund recipients, while China's MIIT enforces GB standards for access network optical power budgets. The European Union's CE marking and RoHS directives constrain hazardous substance use in handheld field instruments sold across member states. Stakeholders must monitor how national broadband subsidy programs reshape tender specifications and qualification thresholds for test equipment vendors.
Market Dynamics
Coherent optical transmission at 400G and 800G wavelengths is forcing fiber certification standards to tighten, pushing carriers to replace legacy multi-mode testers with single-mode OTDR instruments capable of picometer precision across submarine and metro networks.
Growth Catalysts
- 5G Backhaul Mandates:China's MIIT broadband targets require fiber-to-the-home deployments to reach gigabit speeds, compelling carriers to procure OTDR and power meter fleets for field certification.
- Data Center Interconnect Upgrades:Hyperscale cloud operators in the United States and Germany are rebuilding metro fiber rings to support AI training clusters, generating concentrated demand for polarization mode dispersion analyzers.
- EU Digital Decade Goals:The European Union's connectivity targets mandate universal gigabit access by 2030, reshaping tender specifications for test equipment vendors across member state procurement frameworks.
Market Restraints
- Precision Optics Supply Concentration:German and Japanese suppliers control 70% of stabilized laser sources for OTDR modules, creating vulnerability in instrument manufacturing pipelines.
- Certification Cost Burden:FCC Rural Digital Opportunity Fund recipients face rigorous fiber certification requirements that add 15-20% to total deployment budgets, slowing rural rollout timelines.
- Multi-Mode Infrastructure Stranded:Enterprise LANs with installed OM4 cabling resist full tester replacement despite single-mode migration, compressing addressable market for legacy-compatible instruments.
Strategic Opportunities
- Submarine Cable Certification:Trans-Pacific and trans-Atlantic cable projects require specialized long-haul OTDR configurations with 200km+ dynamic range, opening premium pricing tiers.
- India's BharatNet Expansion:The country's rural broadband program creates demand for ruggedized handheld testers suited to high-temperature, high-humidity field conditions.
- AI-Driven Predictive Maintenance:Machine learning integration into OTDR trace analysis enables shift from reactive fault location to preventive network health monitoring.
Industry Challenges
- Photonics Technician Scarcity:Field engineers capable of interpreting coherent optical test traces command 40% salary premiums, constraining carrier fleet scaling.
- Multi-Vendor Interoperability:Proprietary OTDR file formats between instrument makers force carriers to maintain redundant tester fleets or invest in costly translation software.
- Calibration Infrastructure Gaps:National metrology institutes in emerging markets lack traceable standards for 1550nm power reference levels, complicating certification validity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Tester Market |
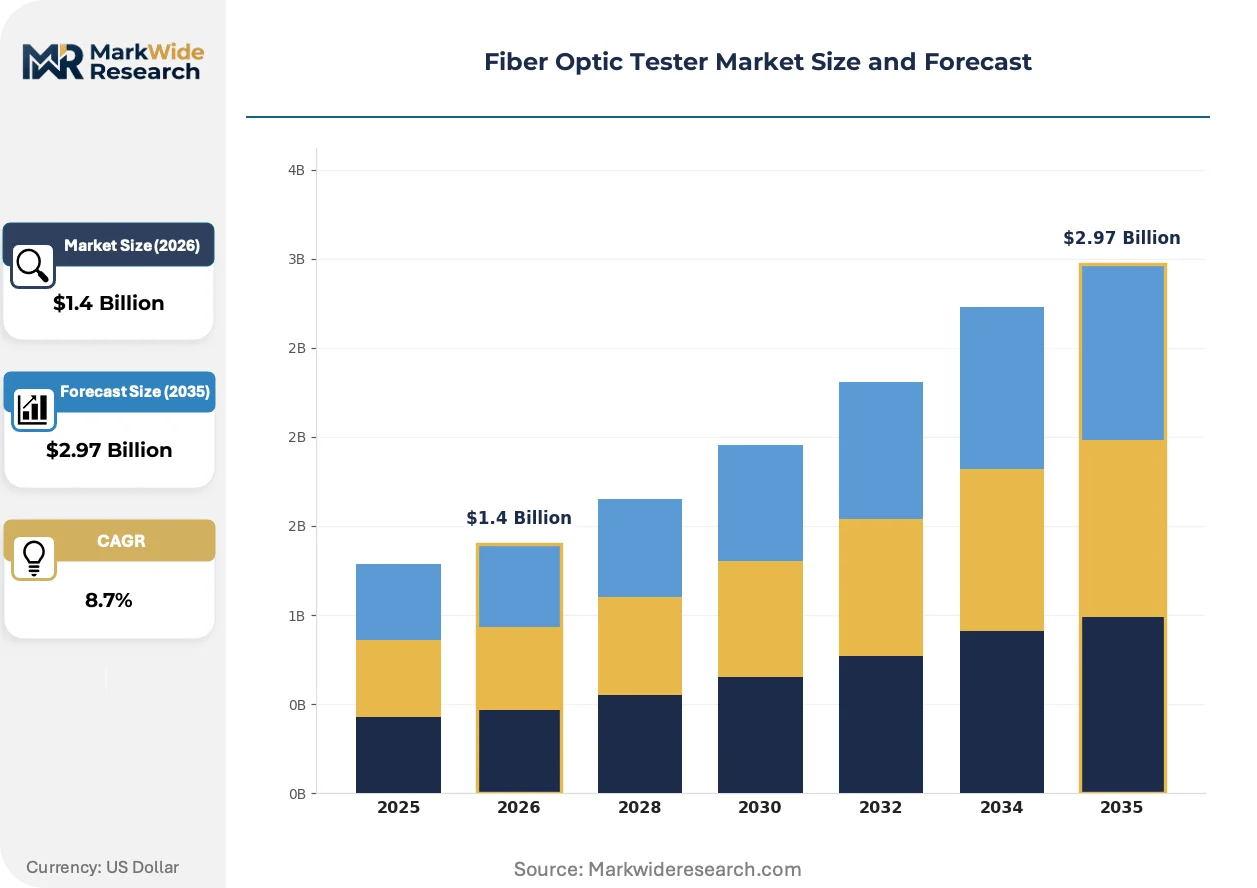
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OTDR, Power Meter, Light Source, Visual Fault Locator Technology: Single-Mode, Multi-Mode, Hybrid, Passive End User: Telecommunications, Industrial, Data Centers, Military Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | EXFO Inc., Fluke Corporation, Viavi Solutions Inc., Anritsu Corporation, Yokogawa Electric Corporation, Keysight Technologies, VeEX Inc., AFL, Tektronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Tester Market Emerging Trajectories
Test instrumentation is converging with cloud analytics and automation, compressing the gap between field measurement and network operations center decision-making. Three developments are restructuring competitive positioning.
Coherent optical analysis modules are expanding into standard field tester form factors. These modules perform constellation diagram analysis and error vector magnitude measurement previously confined to laboratory benches. Tier-one carriers in Germany and Japan are deploying these units for 400ZR transceiver commissioning. The technology is expanding into mid-market access network contractors who previously outsourced high-speed certification.
RoHS and REACH substance restrictions are constraining handheld instrument design. The European Union's hazardous substance directives limit lead content in solder joints and restrict specific flame retardants in plastic housings. Manufacturers serving European tenders must reformulate supply chains or risk disqualification, with compliance costs absorbed most heavily in economy-tier product lines.
Subscription-based test data management is displacing perpetual license software. Carriers now prefer cloud-hosted trace repositories with per-seat monthly fees over on-premise databases requiring IT maintenance. This shift concentrates recurring revenue with vendors possessing robust SaaS infrastructure, most visible among United States-based hyperscale operators managing multi-thousand fiber route inventories.
Fiber Optic Tester Market Segmentation
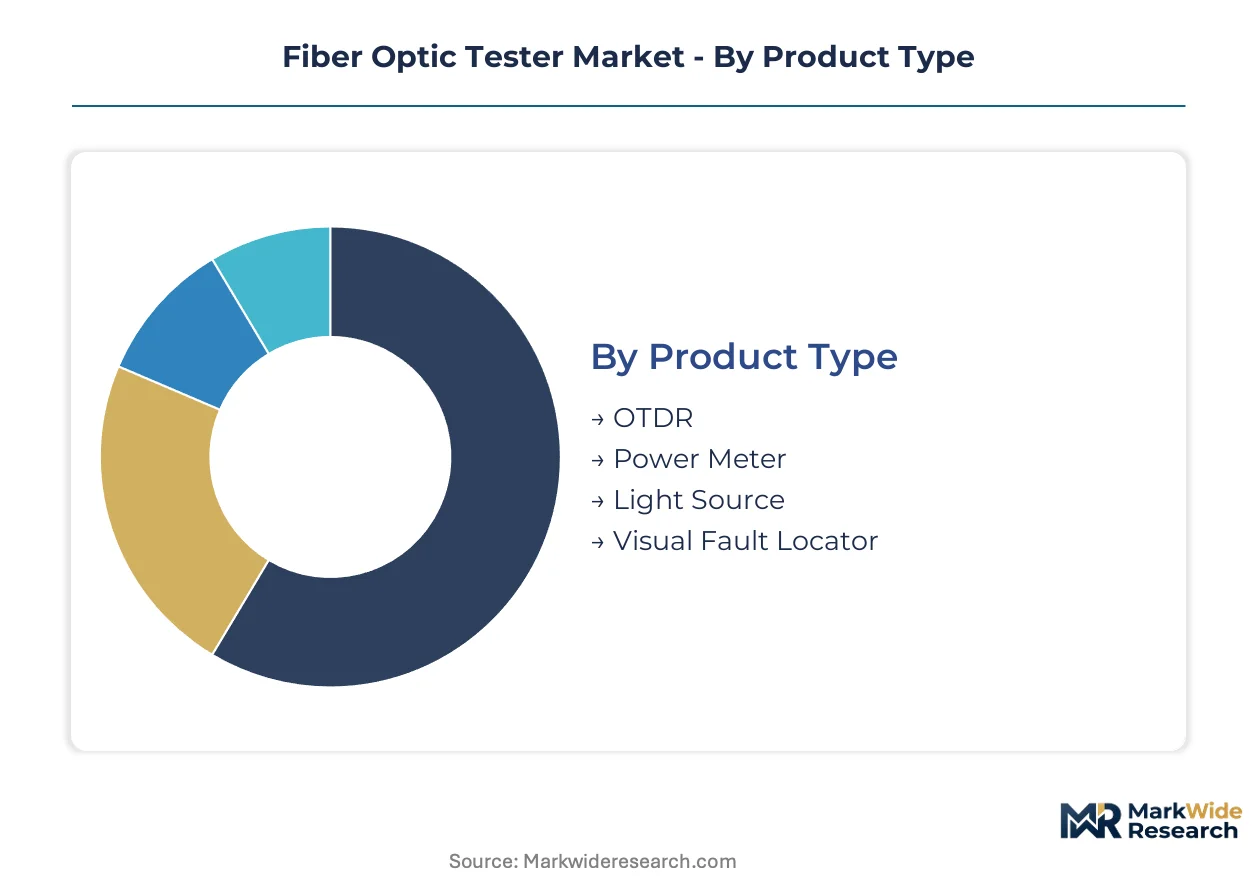
Segmentation in fiber optic testing equipment reveals how procurement decisions split between high-precision laboratory instrumentation and ruggedized field-deployable units. Carrier certification requirements and deployment environments dictate which tester configurations command premium positioning versus commodity replacement cycles.
Product Type:
Supply concentration in OTDR modules centers on stabilized laser sources from German and Japanese component houses, creating tiered availability across precision grades.
- OTDR:Optical time-domain reflectometers inject laser pulses and analyze backscatter signatures to pinpoint fiber breaks, splice losses, and connector reflections with meter-level spatial resolution. Telecommunications carriers in China and the United States deploy fleet-scale OTDR inventories for 5G backhaul certification, with procurement concentrated through national broadband subsidy programs. OTDR absorbs the bulk of installed capacity; Visual Fault Locator is expanding most quickly.
- Power Meter:These photodetector-based instruments measure absolute optical power in dBm across calibrated wavelength ranges, serving as the workhorse tool for link budget verification. Field technician fleets in Germany and Japan generate steady replacement demand as devices reach end-of-life or require recalibration against national metrology standards.
- Light Source:Stabilized laser or LED emitters provide reference signals for insertion loss measurements when paired with power meters. Industrial maintenance contracts in the United States favor multi-wavelength units covering 1310nm and 1550nm for versatile plant documentation.
- Visual Fault Locator:Compact red laser pointers enable macro-bend detection and fiber tracing without sophisticated analysis. Data center contractors prize these low-cost units for rapid cable identification during dense fiber patch panel reconfigurations.
OTDR modules anchor capital expenditure budgets; Visual Fault Locator units climb the fastest as price compression opens new user segments.
Technology:
Cost tier separation emerges sharply between coherent-capable single-mode platforms and legacy multi-mode equipment facing stranded asset risk.
- Single-Mode:Testers optimized for 9-micron core fiber support long-haul and metro networks at 1550nm wavelengths with minimal dispersion. Submarine cable projects across trans-Pacific routes specify these instruments for 200km-plus dynamic range certification, locking in premium pricing tiers unavailable to other technology categories. Single-Mode captures the dominant revenue share; Hybrid configurations are gaining share fastest.
- Multi-Mode:50-micron and 62.5-micron core testers address enterprise LAN environments with LED sources at 850nm and 1300nm. Enterprise IT departments in Germany resist full infrastructure replacement despite single-mode migration pressure, sustaining residual demand for OM3 and OM4 compatible units.
- Hybrid:Switchable single-mode/multi-mode instruments reduce fleet complexity for contractors serving mixed infrastructure environments. Municipal broadband initiatives in the United States favor these versatile units to avoid carrying redundant equipment across rural deployment zones.
- Passive:Non-powered accessories including fiber inspection scopes and cleaning kits support tester ecosystems without active measurement capability. Distribution channel inventories in China stock these high-margin consumables alongside primary instruments.
Single-Mode platforms dominate carrier procurement; Hybrid instruments show the steepest expansion trajectory as contractor flexibility demands intensify.
End User:
Volume concentration varies dramatically between capital-intensive carrier fleets and fragmented industrial maintenance accounts.
- Telecommunications:Tier-one carriers and national broadband operators maintain thousands of certified field units across metropolitan and rural territories. China's MIIT enforcement of GB standards for optical power budgets drives systematic tester refresh cycles among state-owned operators. Telecommunications commands the largest absolute volume; Data Centers represent the fastest-climbing application.
- Data Centers:Hyperscale cloud operators and colocation facilities require polarization mode dispersion analyzers and coherent optical modules for 400G interconnect validation. Metro fiber ring rebuilds in Germany and the United States to support AI training clusters concentrate demand in this segment.
- Industrial:Manufacturing plants, oil and gas facilities, and transportation networks deploy ruggedized testers for process control fiber links. Harsh environment specifications in Saudi Arabia and the UAE favor sealed, wide-temperature-range instruments for desert deployment conditions.
- Military:Defense agencies procure classified-grade testers with tamper-evident calibration and encrypted trace storage. NATO standardization agreements shape tender specifications across member state procurement frameworks.
Telecommunications absorbs the bulk of installed capacity; Data Centers are expanding most quickly.
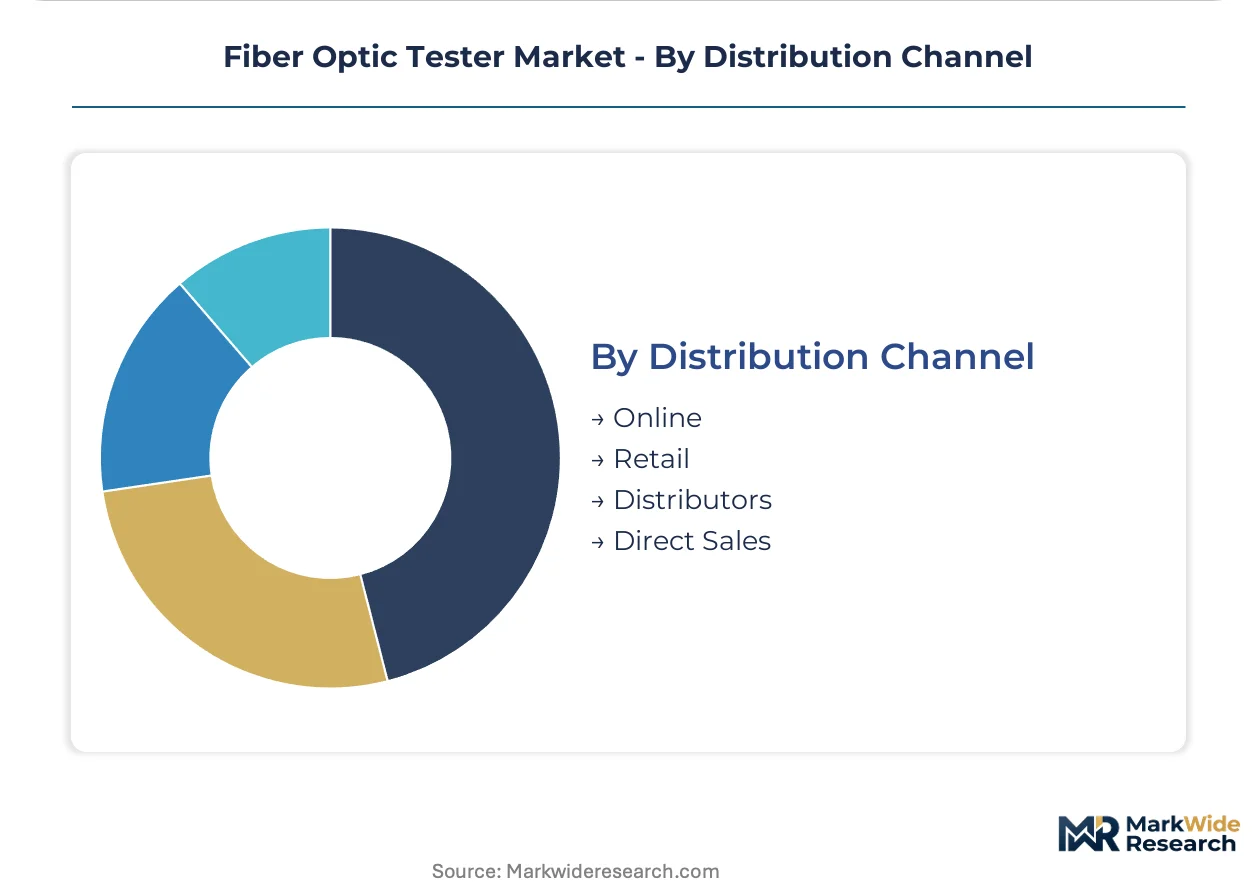
Distribution Channel:
Customer type fragmentation separates price-sensitive small contractors from enterprise buyers demanding vendor-managed inventory relationships.
- Direct Sales:Manufacturer field organizations serve national carriers and hyperscale operators with customized fleet configurations and embedded training programs. EXFO and Viavi anchor major accounts in North America through dedicated technical account management.
- Distributors:Regional value-added resellers provide local stockholding, calibration services, and credit terms to mid-market contractors. German distributors maintain extensive OTDR rental fleets for project-based demand spikes.
- Online:E-commerce platforms including Amazon Business and specialized test equipment marketplaces serve small installers and replacement part procurement. Price transparency pressures margin structures for standard power meters and light source bundles.
- Retail:Limited brick-and-mortar presence targets emergency replacement and educational institution purchases through electronics specialty stores. Geographic coverage concentrates in urban centers across the United States and Japan.
Direct Sales channels capture the dominant transaction value; Online platforms are climbing the fastest as procurement digitization accelerates among smaller contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stabilized laser sources from German and Japanese photonics suppliers anchor manufacturing pipelines for precision OTDR modules, concentrating procurement leverage in specific national markets.
United States
Rural Digital Opportunity Fund recipients drive fleet-scale OTDR procurement for fiber-to-the-home certification. The FCC mandates rigorous optical power budget documentation before network activation. Field technician concentration spans Texas, California, and the Southeast where national broadband contractors deploy ruggedized handheld units.
China
State-owned carriers refresh tester inventories to meet MIIT gigabit broadband targets across 300-plus prefecture-level cities. GB standards enforcement tightens optical power budget specifications for access networks. Yangtze River Delta manufacturing clusters produce photodetector modules for domestic and export instrument assembly.
Germany
Hyperscale data center interconnect rebuilds for AI training clusters concentrate demand for polarization mode dispersion analyzers. CE marking and RoHS directives constrain hazardous substance use in handheld field instruments. Bavarian and North Rhine-Westphalia metro fiber rings anchor technician fleet deployment density.
Japan
Coherent optical testing module adoption accelerates for 400ZR transceiver commissioning in Tokyo-Osaka corridor networks. METI industrial standards shape calibration protocol requirements for export-bound instruments. Nagoya-area photonics suppliers feed stabilized laser source demand for premium OTDR configurations.
India
BharatNet rural broadband expansion creates demand for ruggedized handheld testers rated for high-temperature, high-humidity field conditions. The Department of Telecommunications structures tender specifications around cost-efficient fleet procurement. Maharashtra and Gujarat deployment zones concentrate contractor equipment purchases.
Fiber Optic Tester Market Vendor Landscape
Global majors compete with regional champions across photonics R&D depth and carrier relationship density. The supplier base separates into three tiers: integrated test instrumentation conglomerates, specialized optical measurement pure-plays, and regional value-added distributors. Consolidation pressure intensifies as coherent optical testing requirements demand capital-intensive calibration infrastructure. Dominant competitive moves include strategic partnerships with tier-one carriers and backward integration into stabilized laser source supply.
Among North American instrumentation specialists, EXFO Inc. and Viavi Solutions Inc. exemplify the carrier-relationship archetype, while Anritsu Corporation represents Japanese precision manufacturing heritage. These three occupy positions across the premium calibration tier where OTDR protocol standardization confers sustained positioning. Keysight Technologies anchors the diversified electronic measurement conglomerate segment, leveraging vector network analysis heritage. Fluke Corporation sits within the industrial field tool extension archetype, applying ruggedized design discipline to fiber certification workflows.
| Leading Market Players |
|---|
| EXFO Inc. |
| Fluke Corporation |
| Viavi Solutions Inc. |
| Anritsu Corporation |
| Yokogawa Electric Corporation |
| Keysight Technologies |
| VeEX Inc. |
| AFL |
| Tektronix |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between laboratory-precision OTDR modules and field-rugged handheld units manifests in divergent pricing architectures and sourcing strategies. Premium single-mode instruments with coherent optical analysis capabilities command substantial markups tied to stabilized laser source provenance from German and Japanese photonics houses, while economy-tier multi-mode testers face margin compression from Chinese component integration.
Pricing Analysis
Warranty and calibration service bundling separates premium vendor offerings from transactional equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier alignment with FCC Rural Digital Opportunity Fund documentation requirements and MIIT GB standard enforcement. Price differentiation hinges on dynamic range specifications and traceable calibration chains to national metrology institutes. Cost compression in economy handheld segments intensifies because Chinese photodetector module manufacturing scales. Small installation contractors exhibit highest price sensitivity, while tier-one carriers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from tier-one carriers and hyperscale operators require qualified secondary suppliers for stabilized laser sources and precision photodetectors. Manufacturing gravity centers on China for photodetector module assembly, Japan for stabilized laser sources, and Germany for precision optical components. Raw material dependencies include indium phosphide substrates, erbium-doped fiber amplifiers, and high-purity silica preforms. Single-source vulnerability concentrates in 1550nm distributed feedback laser diodes from Nagoya-area suppliers. Distribution runs through manufacturer direct sales for carrier fleets and regional value-added resellers for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over stabilized laser source supply determines margin sustainability. Players are pursuing backward integration into photonics component manufacturing to escape German and Japanese supplier concentration.
For Market Incumbents: Deploy certification protocol ownership as a defensive moat. EXFO and Viavi should deepen captive photonics R&D facilities to maintain OTDR calibration standard dominance against emerging Chinese precision instrumentation. Threat from coherent optical analysis module commoditization requires accelerated cloud analytics integration. Capacity addition in Quebec and California photonics clusters secures supply continuity. For New Entrants and Emerging Players: FCC Rural Digital Opportunity Fund certification requirements in the United States open a window for ruggedized handheld tester specialization. White-space targets include India's BharatNet rural broadband expansion and Middle East industrial fiber deployment. Municipal broadband contractors in the United States represent the most penetrable segment. Go-to-market angle should emphasize subscription-based test data management with per-seat SaaS pricing to match carrier procurement preferences. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified electronic measurement conglomerates seeking optical testing capability. Long-term viability favors vendors with coherent optical module expertise and established carrier relationships over pure-play component suppliers. Acquisition target archetype: mid-cap specialists with 400G/800G certification capabilities and cloud-hosted trace repository infrastructure. Signal to watch is 800G coherent transmission standard finalization and carrier fleet refresh timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stabilized Laser Sources | Captive supply from Japanese and German photonics houses reduces procurement vulnerability for OTDR manufacturers. |
| Cloud-Hosted Test Data Management Platform | Subscription revenue from tier-one carriers replaces perpetual license models and deepens customer retention. |
| Coherent Optical Module Field Deployment | 400ZR transceiver commissioning capabilities expand addressable market beyond traditional access network contractors. |
| Rural Broadband Certification Specialization | FCC Rural Digital Opportunity Fund compliance creates dedicated procurement channel with documented fiber power budgets. |
| Multi-Wavelength Hybrid Instrument Development | Switchable single-mode/multi-mode configurations reduce fleet complexity for municipal broadband contractors. |
Methodological Framework
Multi-period observation of carrier fleet refresh cycles, national broadband subsidy program disbursements, and coherent optical transmission standard adoption anchored the trend analysis, supplemented by interviews with field service engineering directors, photonics R&D leads, telecommunications procurement officers, and calibration laboratory managers. Secondary validation drew from FCC Rural Digital Opportunity Fund filings, MIIT broadband target announcements, EU Digital Decade connectivity goal documentation, and SEC 10-K disclosures from listed test equipment vendors. Bottom-up equipment unit economics triangulated against top-down carrier capex allocation estimates.
Segment-weighting across product type, technology platform, end-user vertical, and distribution channel dimensions structured the analytical framework. CAGRs were derived from installation base growth, replacement cycle compression, and technology upgrade penetration curves across the projection horizon. Industry-specific forecast inputs included 5G backhaul fiberization timelines and hyperscale data center interconnect rebuild schedules for AI training cluster support.
The model assumes a particular technology adoption path; alternative pathways for 800G coherent transmission deployment would alter the outlook for single-mode OTDR demand concentration. Forecasts reflect assumptions regarding national broadband subsidy program continuity and photonics technician workforce scaling. Deviation in German and Japanese laser source supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Metrology Systems Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Battery Cell, Module, and Pack Swelling Measurement Systems Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Latin America Measurement and Test Equipment Market