
 Surface Vision and Inspection Equipment Market | 2026-2036
Surface Vision and Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Vision and Inspection Equipment Market Analytics
Buyer concentration in the automotive and semiconductor sectors is shifting as tier-one suppliers internalize inspection capabilities previously outsourced to system integrators. Cognex Corporation leverages its deep software-hardware integration to dominate high-speed electronics inspection. ISRA VISION GmbH anchors its position in automotive paint and surface finish quality systems. Keyence Corporation differentiates through direct sales channels and rapid deployment cycles for factory-floor vision setups.
Surface vision and inspection equipment encompasses camera-based optical systems, structured-light sensors, and computational imaging platforms that detect dimensional deviations, surface defects, and material inconsistencies at micron-level resolution in production environments. These systems execute real-time pass-fail decisions, feeding data directly into statistical process control loops to minimize downstream rework and scrap rates. Vision systems command the largest installed base due to their flexibility across multiple inspection tasks, while machine learning technology represents the fastest-expanding capability layer as neural networks replace rule-based algorithms for defect classification. Inspection cameras sustain premium positioning in semiconductor wafer inspection where resolution and throughput requirements exclude lower-tier alternatives.
The FDA enforces strict validation protocols for vision systems deployed in pharmaceutical packaging and medical device manufacturing, compelling vendors to maintain 21 CFR Part 11 compliant documentation trails. EMA's Medical Device Regulation and CE marking requirements further tighten performance verification standards for European installations, particularly in sterile product lines. OSHA machine safety directives in the US and EU machinery directives mandate protective enclosures and interlock systems for automated inspection cells, adding mechanical complexity and certification cost to system designs. Stakeholders must weigh the trade-off between proprietary AI inference engines and interoperable platforms as regulatory scrutiny of algorithmic decision-making intensifies across multiple jurisdictions.
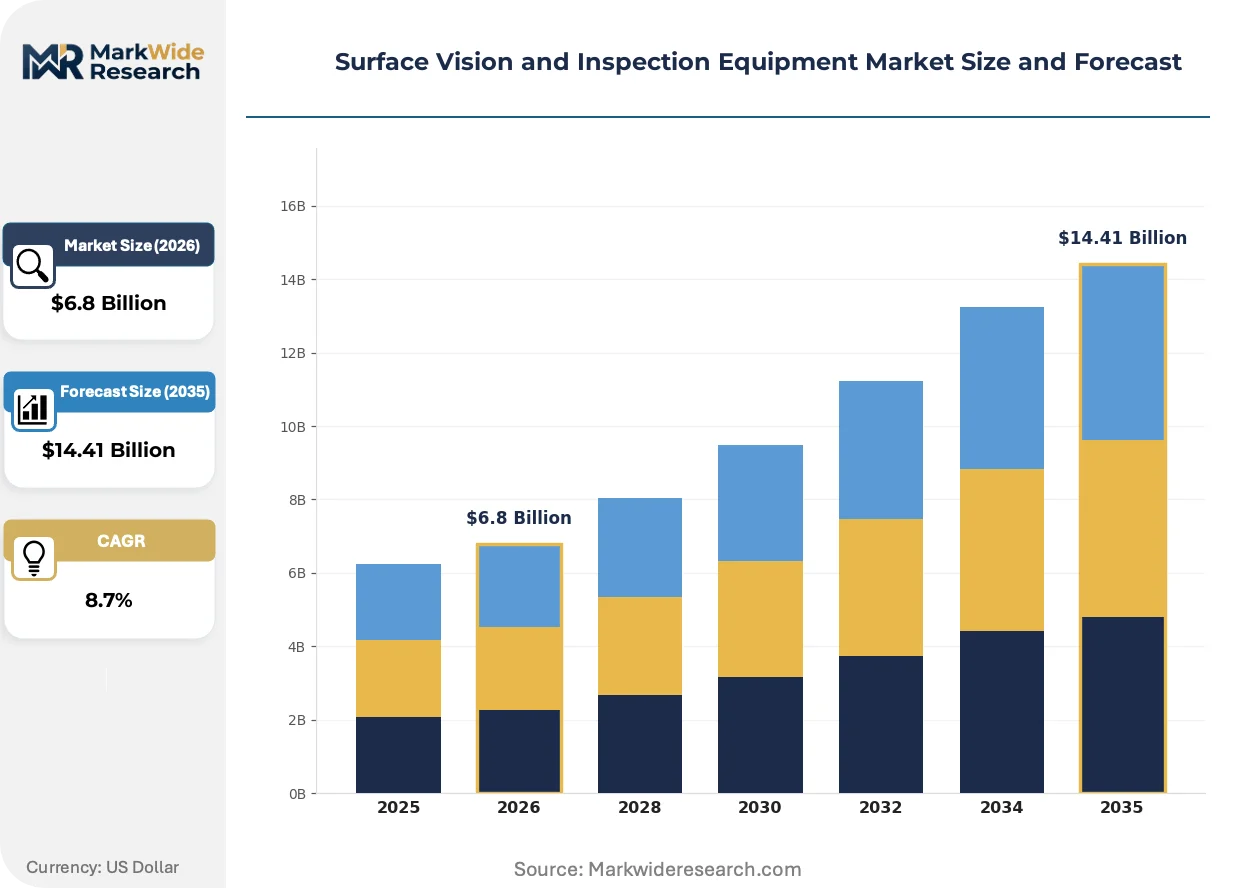
Market Dynamics
Semiconductor node migration below 7nm is forcing fabs to quadruple inspection points per wafer, compressing cycle times while multiplying resolution requirements. This density-pressure dynamic is restructuring equipment procurement priorities across electronics manufacturing.
Growth Catalysts
- EU AI Act certification mandates:European manufacturers must deploy validated autonomous inspection systems for CE marking compliance, accelerating replacement of rule-based vision platforms with neural-network architectures in automotive and medical device production lines.
- Automotive paint finish quality escalation:Electric vehicle OEMs demand defect-free exterior surfaces as brand differentiation intensifies, driving German and South Korean automakers to upgrade inline inspection density on coating lines.
- Structured-light 3D sensing:This technology enables micron-level dimensional verification of complex geometries in real time, penetrating aerospace turbine blade manufacturing and precision medical implant production where contact measurement proves too slow.
Market Restraints
- Specialized optical component supply concentration:High-resolution inspection cameras depend on Japanese and German sensor suppliers, creating vulnerability to export control disruptions and extended lead times for semiconductor wafer inspection systems.
- FDA 21 CFR Part 11 validation burden:Pharmaceutical and medical device manufacturers face documentation-intensive approval processes for vision system deployments, extending sales cycles by 8-14 months compared to unregulated industrial applications.
- Computational imaging hardware cost inflation:GPU and FPGA prices for real-time defect classification have risen substantially, squeezing margins for mid-tier system integrators serving price-sensitive packaging and textile inspection segments.
Strategic Opportunities
- Battery cell electrode inspection white space:Lithium-ion gigafactories in Hungary and Poland lack sufficient surface defect detection capacity for coated electrode foils, creating first-mover advantage for vision vendors with gigapixel-per-second throughput systems.
- India PLI scheme manufacturing incentives:Production-linked incentive programs for electronics and automotive components are attracting greenfield fabs requiring complete inspection infrastructure, bypassing the retrofit constraints of mature manufacturing regions.
- Hyperspectral-multispectral convergence:Combining spatial and spectral analysis enables chemical composition verification alongside physical defect detection, opening pharmaceutical raw material inspection and food safety applications previously served by separate laboratory instruments.
Industry Challenges
- Machine vision engineer scarcity:Deployment of AI-enabled inspection systems requires specialists capable of neural network training and optical system integration, with European and North American manufacturers competing for a limited talent pool against technology sector employers.
- Legacy MES integration complexity:Brownfield factories operate decades-old manufacturing execution systems with proprietary data protocols, forcing vision vendors to develop costly custom middleware for statistical process control connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Vision and Inspection Equipment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vision Systems, Inspection Cameras, Sensors, Imaging Software Technology: Machine Learning, Artificial Intelligence, Optical Inspection, Laser Inspection End User: Aerospace, Semiconductor, Automotive, Electronics Installation: Integrated Systems, Standalone Units, Mobile Solutions, Automated Lines |
| Companies Covered | Cognex Corporation, ISRA VISION GmbH, OMRON Corporation, Keyence Corporation, Teledyne Technologies Incorporated, AMETEK, Inc., Basler AG, Baumer Inspection GmbH, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Vision and Inspection Equipment Market Evolving Landscape
Computational imaging architectures are displacing conventional machine vision pipelines, enabling software-defined inspection parameters that adapt without hardware modification. This shift is compressing product development cycles while expanding addressable application scope.
Edge-deployed neural networks are expanding into semiconductor wafer inspection, executing defect classification within 50 milliseconds to maintain throughput on 300mm wafer lines. Samsung and TSMC fabs in South Korea and Taiwan are piloting these architectures to reduce cloud dependency for sensitive process data. The technology is expanding into front-end manufacturing where latency constraints previously excluded AI-based decision-making.
REACH substance restrictions and RoHS recast directives in Europe are compelling vision system manufacturers to eliminate halogenated flame retardants and specific phthalates from camera housings and cable assemblies. Equipment vendors serving automotive and electronics sectors must redesign mechanical components and requalify supply chains to maintain CE marking eligibility. German industrial camera suppliers are absorbing 12-18 month redesign cycles to achieve compliance ahead of enforcement deadlines.
Contract structures are evolving from capital equipment sales toward availability-guaranteed performance models. Tier-one automotive suppliers in Bavaria and Baden-Württemberg now procure inspection capacity as operational expenditure, transferring uptime risk to equipment vendors. This transformation demands remote diagnostics infrastructure and predictive maintenance capabilities that reshape vendor organizational structures and balance sheet profiles.
Surface Vision and Inspection Equipment Market Segmentation
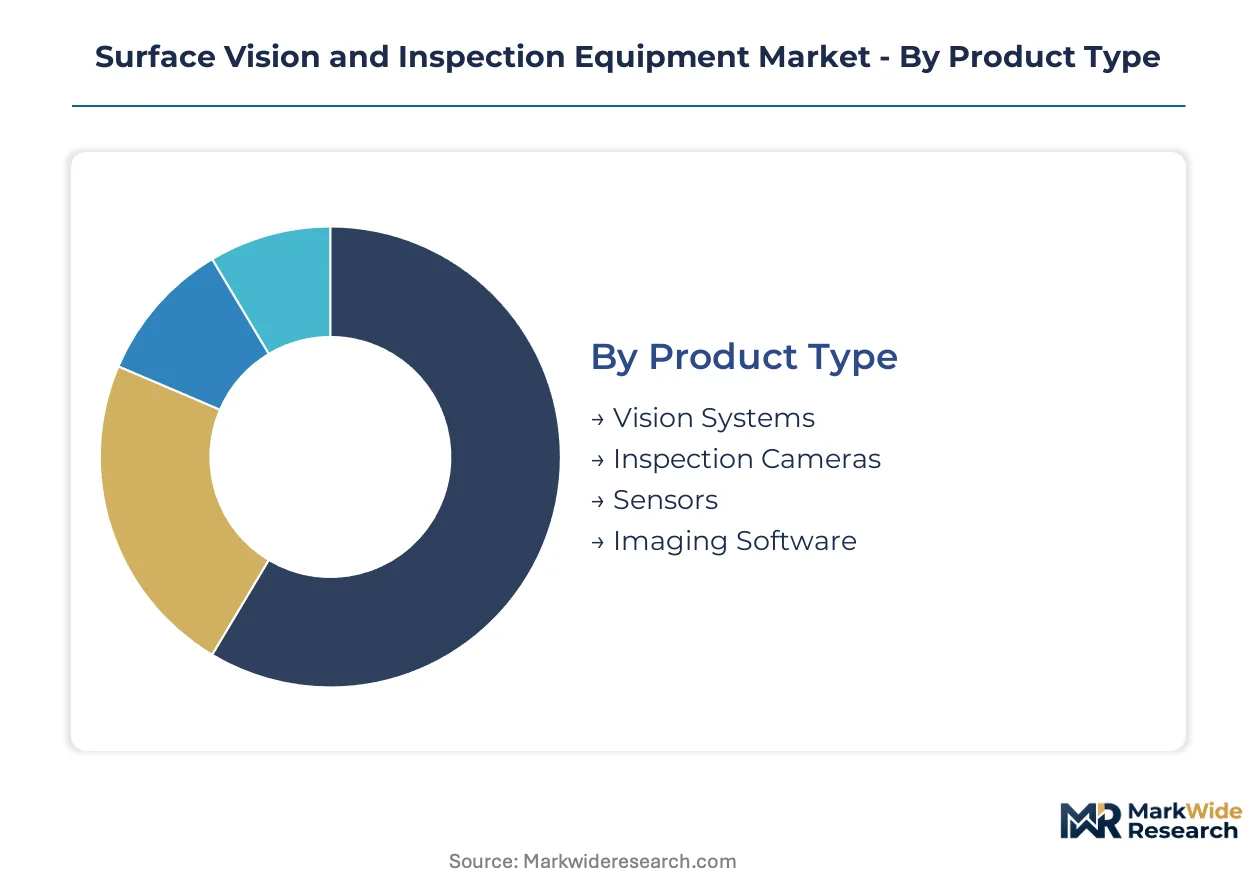
Segmentation in surface vision and inspection equipment reveals how technology specialization and end-use intensity reshape procurement patterns. Equipment buyers prioritize resolution specifications, throughput requirements, and integration complexity differently across semiconductor fabs, automotive paint lines, and aerospace machine shops.
Product Type:
Supply concentration in optical components and sensor manufacturing concentrates margin capture among integrated system vendors rather than discrete component suppliers.
- Vision Systems:Multi-camera architectures with synchronized lighting and computational backends execute dimensional gauging, defect classification, and robotic guidance from unified hardware platforms. German automotive OEMs in Bavaria and Baden-Württemberg dominate procurement volumes as EV exterior quality standards tighten and inline inspection density escalates on coating lines.
- Inspection Cameras:High-resolution CMOS and CCD sensors with specialized optics deliver micron-level resolution for semiconductor wafer inspection and medical device verification. Japanese and German sensor suppliers control critical supply nodes, creating vulnerability to export control disruptions and extended lead times for sub-7nm fab expansions.
- Sensors:Structured-light and time-of-flight modules enable 3D surface mapping without contact measurement delays.
- Imaging Software:Algorithm platforms for defect detection, neural network training, and statistical process control integration.
Today's leader: Vision Systems. Tomorrow's challenger: Imaging Software.
Technology:
Cost tier differentiation separates validated autonomous platforms commanding premium pricing from rule-based legacy systems facing replacement pressure.
- Machine Learning:Neural network architectures trained on labeled defect datasets replace fixed-rule algorithms for classification accuracy in variable production environments. South Korean and Taiwanese semiconductor fabs pilot edge-deployed inference to maintain sub-50-millisecond decision latency on 300mm wafer lines.
- Artificial Intelligence:Autonomous inspection systems with self-optimizing parameters require EU AI Act certification for CE marking compliance in European automotive and medical device production. EMA's Medical Device Regulation and FDA 21 CFR Part 11 protocols impose documentation-intensive validation processes that extend sales cycles.
- Optical Inspection:Conventional bright-field and dark-field imaging with fixed threshold algorithms.
- Laser Inspection:Triangulation and confocal methods for sub-micron dimensional verification.
Machine Learning expands most quickly as fabs quadruple inspection points per wafer below 7nm nodes. Optical Inspection retains installed base defense in cost-sensitive packaging applications.
End User:
Application intensity varies sharply: semiconductor fabs demand nanometer resolution while automotive prioritizes throughput over absolute precision.
- Semiconductor:Front-end and back-end fabs require defect detection at sub-micron resolution with throughput exceeding thousands of wafers hourly. Taiwan and South Korean foundries drive architecture innovation as node migration compresses cycle times and multiplies resolution requirements.
- Automotive:Paint finish quality, weld inspection, and powertrain dimensional verification dominate procurement as EV OEMs differentiate through exterior surface perfection. German industrial corridors concentrate upgrade activity where tier-one suppliers internalize capabilities previously outsourced to system integrators.
- Aerospace:Turbine blade and structural component inspection with stringent traceability requirements.
- Electronics:PCB assembly and consumer device manufacturing with high-speed pass-fail throughput priorities.
Semiconductor commands premium pricing and technology leadership. Automotive delivers volume scale and fastest replacement cycles.
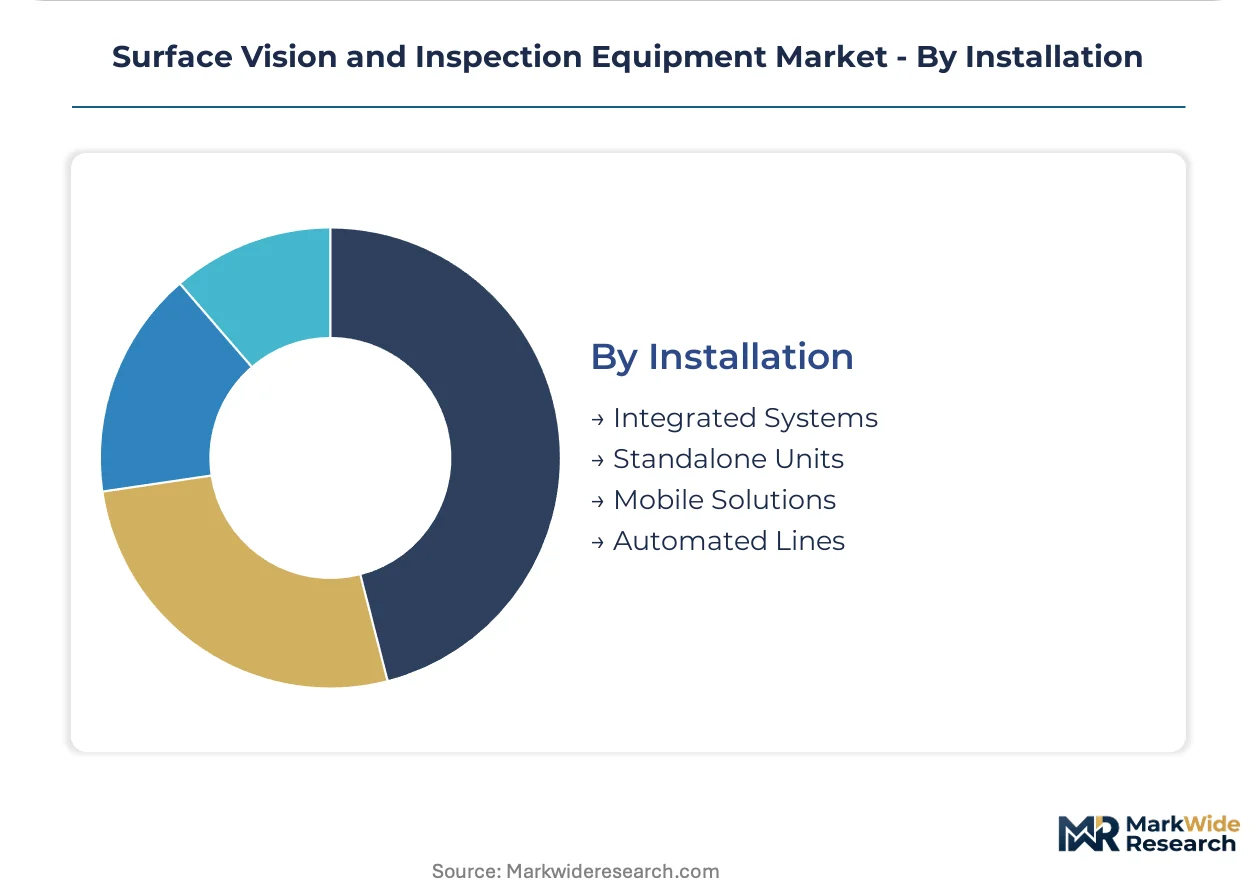
Installation:
Customer type segmentation separates greenfield fabs with unified architecture choices from brownfield sites wrestling with legacy MES integration complexity.
- Integrated Systems:Fully embedded inspection cells with robotic handling, automated lighting, and direct MES connectivity for closed-loop process control. Hungary and Poland battery gigafactories represent greenfield demand as lithium-ion electrode foil inspection capacity lags coated production volumes.
- Automated Lines:Conveyor-integrated architectures with synchronized throughput matching production line speeds. India's PLI scheme electronics manufacturing incentives attract complete inspection infrastructure investments bypassing retrofit constraints of mature regions.
- Standalone Units:Benchtop or floor-mounted systems for sampling inspection and quality lab verification.
- Mobile Solutions:Portable or reconfigurable platforms for multi-station deployment and maintenance applications.
Integrated Systems anchor strategic vendor relationships. Mobile Solutions address capability scarcity in distributed manufacturing footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive paint line upgrades while South Korea drives semiconductor wafer inspection innovation, revealing how regional industrial specialization shapes equipment procurement patterns.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are internalizing inspection capabilities previously outsourced to system integrators. The EU AI Act mandates validated autonomous systems for CE marking compliance on automotive production lines. Stuttgart and Munich industrial corridors dominate upgrade activity as EV manufacturers demand defect-free exterior surfaces.
United States
Semiconductor fabs in Arizona and Texas are expanding inspection footprints as domestic chip production scales. FDA 21 CFR Part 11 protocols enforce strict validation documentation for pharmaceutical and medical device vision deployments. Boston and San Francisco Bay Area precision manufacturing clusters drive demand for micron-resolution dimensional verification systems.
South Korea
Samsung and SK Hynix fabs are piloting edge-deployed neural networks for sub-50-millisecond defect classification on 300mm wafer lines. MFDS medical device regulations align with international validation standards for sterile product inspection. Seoul and Suwon semiconductor manufacturing complexes anchor Asia-Pacific technology leadership in front-end inspection architecture.
Japan
High-resolution CMOS and CCD sensor suppliers control critical supply nodes for sub-7nm fab expansions. METI industrial policy supports domestic equipment vendor competitiveness in precision optics. Kyoto and Tokyo camera component manufacturing clusters face export control vulnerability as semiconductor inspection demand intensifies.
India
Electronics and automotive component manufacturers are building complete inspection infrastructure under PLI scheme incentives. BIS certification requirements shape equipment selection for domestic market access. Karnataka and Tamil Nadu greenfield fabs bypass retrofit constraints of mature manufacturing regions through unified architecture choices.
Surface Vision and Inspection Equipment Market Competitive Landscape
German producers anchor the precision optics tier; Japanese and American specialists hold positions in sensor technology and software integration. The vendor base separates into three strategic layers: integrated system architects controlling full hardware-software stacks, component specialists dominating discrete optical supply nodes, and regional system integrators serving price-sensitive packaging segments. Competitive maneuvering concentrates on strategic partnerships for AI inference engine development and geographic expansion into battery gigafactory greenfields.
Within the integrated system tier, Cognex Corporation and ISRA VISION GmbH exemplify contrasting geographic anchoring and end-use specialization. Cognex represents American software-hardware integration depth in high-speed electronics inspection. ISRA VISION occupies a position as a German GmbH-structured entity anchored in automotive surface finish quality systems. Keyence Corporation sits within the direct-sales archetype, demonstrating rapid deployment cycle capabilities for factory-floor vision setups through its Japanese corporate structure.
| Leading Market Players |
|---|
| Cognex Corporation |
| ISRA VISION GmbH |
| OMRON Corporation |
| Keyence Corporation |
| Teledyne Technologies Incorporated |
| AMETEK, Inc. |
| Basler AG |
| Baumer Inspection GmbH |
| SICK AG |
| Others |
Value Network & Pricing Analysis
Family-owned German optical specialists anchor the precision tier, their multi-generational balance sheets enabling patient pricing discipline while Japanese sensor houses command premium positioning through captive technology. This ownership dispersion creates asymmetric pricing power across component and system layers, with integrated vendors capturing margin from fragmented buyers.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for high-resolution inspection cameras as Samsung and SK Hynix fabs expand sub-7nm inspection footprints. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from automotive paint-line units and cost-sensitive packaging alternatives. Price differentiation hinges on certification grade and throughput specification, with EU AI Act compliance adding substantial premium capture. Semiconductor fabs show least price sensitivity given yield-loss exposure, while textile and packaging converters resist upgrade cycles amid GPU cost inflation.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Germany and semiconductor fabs in Taiwan compel vision system vendors to qualify secondary sensor suppliers despite performance gaps. Critical optical components concentrate in Japan and Germany, with CMOS sensors and precision optics drawing from Tokyo and Stuttgart manufacturing clusters. Supply chain risk centers on export control vulnerability for sub-7nm fab expansions. Distribution runs through direct sales channels for large OEM accounts and regional system integrators for mid-tier packaging and electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU AI Act certification deadline creates irreversible replacement demand across European automotive and medical device production lines.
For Market Incumbents: To counter GPU and FPGA cost inflation squeezing mid-tier margins, Cognex and ISRA VISION should deepen backward integration into computational imaging hardware while accelerating edge-AI inference engine development to reduce cloud dependency. Certification investment in FDA 21 CFR Part 11 and EU AI Act validation protocols anchors pricing power against unvalidated challengers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in battery electrode inspection opens white-space entry for gigapixel-per-second throughput systems targeting Hungary and Poland gigafactories. India's PLI scheme electronics manufacturing incentives offer greenfield bypass of legacy MES integration complexity. Direct sales channel establishment with rapid deployment cycles mirrors Keyence's proven factory-floor penetration model. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier system integrators serving price-sensitive packaging segments, where margin compression from computational hardware cost inflation has outpaced pricing recovery. Long-term viability favors vendors with validated autonomous platforms and pharmaceutical certification moats. The signal to watch is EU AI Act enforcement intensity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | CE marking compliance unlocks automotive OEM procurement budgets across Stuttgart and Munich corridors. |
| Edge-AI Inference Engine Development | Sub-50-millisecond defect classification maintains throughput on Samsung and TSMC 300mm wafer lines. |
| Battery Gigafactory Geographic Expansion | Electrode foil inspection capacity lags coated production volumes in Hungary and Poland. |
| Backward Integration into Optical Components | Captive sensor supply mitigates Japanese export control vulnerability for sub-7nm fab equipment. |
| Outcome-Based Performance Contracting | Bavarian automotive suppliers now procure inspection capacity as operational expenditure transferring uptime risk. |
Research Methodology
Coverage spans Germany, South Korea, Japan, the United States, and India, with primary inputs from each region combining interviews with semiconductor fab engineers, automotive quality directors, pharmaceutical validation specialists, and vision system integration architects alongside secondary validation. FDA 21 CFR Part 11 guidance documents, EMA Medical Device Regulation technical files, EU AI Act implementation standards, and SEC filings from listed equipment vendors anchored supply-side assessment. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates underwent triangulation.
Granularity-level modeling addressed product type, technology layer, end-use intensity, and installation architecture across the projection horizon. Semiconductor node migration timelines, automotive EV exterior quality escalation curves, and pharmaceutical validation cycle durations informed analytical framework construction. CAGRs derived from equipment procurement pipeline analysis and fab capacity expansion announcements.
Caveats apply where EU AI Act enforcement timing or export control expansion could materially shift the outlook. Deviation in GPU and FPGA pricing trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Hour Meter Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Color Meter Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Test Benches Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Battery Drop Tester Market