
 Duct Integrity Tester (DIT) Market | 2026-2036
Duct Integrity Tester (DIT) Market Size, Share, and Industry Trends Forecast 2026-2036
Duct Integrity Tester (DIT) Market Foresight
The Duct Integrity Tester market is rebalancing as premium automated systems pull away from handheld commodity units on precision, connectivity, and compliance documentation. Fluke Corporation leverages its multimeter distribution network to place portable testers into electrical contractor channels. Retrotec Inc. anchors the North American calibration and training ecosystem, sustaining dealer loyalty through certification programs. Megger Group Limited competes on industrial ruggedness, extending its insulation-test heritage into heavy-duty ventilation environments.
A Duct Integrity Tester quantifies air leakage in ductwork assemblies using pressure differential methods, typically resolving to 1% accuracy of reading at 25 Pascals test pressure, to verify compliance with energy codes and indoor air quality mandates. The instrument serves building commissioning, retrofit verification, and manufacturing quality control across commercial and residential HVAC infrastructure. Portable testers dominate current volume given contractor mobility requirements, while automated systems capture expanding margin pools in large-scale facility management contracts. Pressure decay technology leads installed base owing to ASHRAE and SMACNA protocol alignment, though infrared thermography gains traction for non-destructive spot inspection in existing building audits.
ASHRAE Standard 90.1 and the International Energy Conservation Code shape product specifications by mandating maximum leakage rates for commercial duct systems, directly conditioning DIT accuracy requirements. The U.S. Department of Energy enforces appliance and equipment standards that ripple into duct performance testing protocols for federal buildings. EPA ENERGY STAR certification programs for new homes incorporate duct tightness verification, expanding inspector demand for calibrated instrumentation. Stakeholders must monitor evolving state-level stretch codes that exceed national baselines and determine whether to configure product portfolios for maximum flexibility or targeted premium compliance.
Market Dynamics
The Duct Integrity Tester market is bifurcating as automated calibration systems capture facility management contracts while handheld units serve contractor mobility needs, with ASHRAE 90.1 leakage thresholds tightening precision requirements across commercial building portfolios.
Growth Catalysts
- California Title 24:The state's energy code mandates duct leakage verification for all new commercial construction and major alterations, creating inspector demand for calibrated instrumentation in compliance corridors.
- Deep decarbonization zones:Northeast states including Massachusetts and New York are embedding duct tightness into building performance standards for net-zero retrofit pathways.
- Pressure decay automation:Large-scale property managers are deploying networked DIT systems that integrate with building management platforms for continuous commissioning protocols.
Market Restraints
- Calibration infrastructure concentration:North American traceable calibration services cluster in metropolitan testing laboratories, extending turnaround times for field units in secondary markets.
- Sensor drift in industrial environments:Heavy-duty ventilation applications expose pressure transducers to temperature cycling that degrades 1% accuracy specifications within warranty periods.
- Qualified technician scarcity:SMACNA certification requirements limit the pool of operators who can execute ASHRAE-compliant test protocols, constraining deployment velocity.
Strategic Opportunities
- Existing building audit expansion:Infrared thermography integration creates non-destructive inspection capability for retrofit contractors assessing leakage without system shutdown.
- EPA ENERGY STAR for Homes:The certification program's duct tightness verification requirement opens inspector channel demand in residential new construction markets.
- Cloud-connected documentation:Automated systems that generate timestamped compliance reports are penetrating large REIT portfolios seeking audit trail standardization.
Industry Challenges
- Cross-protocol training burden:Technicians must maintain proficiency across ASHRAE, SMACNA, and state-specific test methods, lengthening certification timelines and raising labor costs.
- Legacy system integration friction:Automated DIT platforms face interoperability gaps with proprietary building automation systems, requiring custom middleware development for facility management contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duct Integrity Tester (DIT) Market |
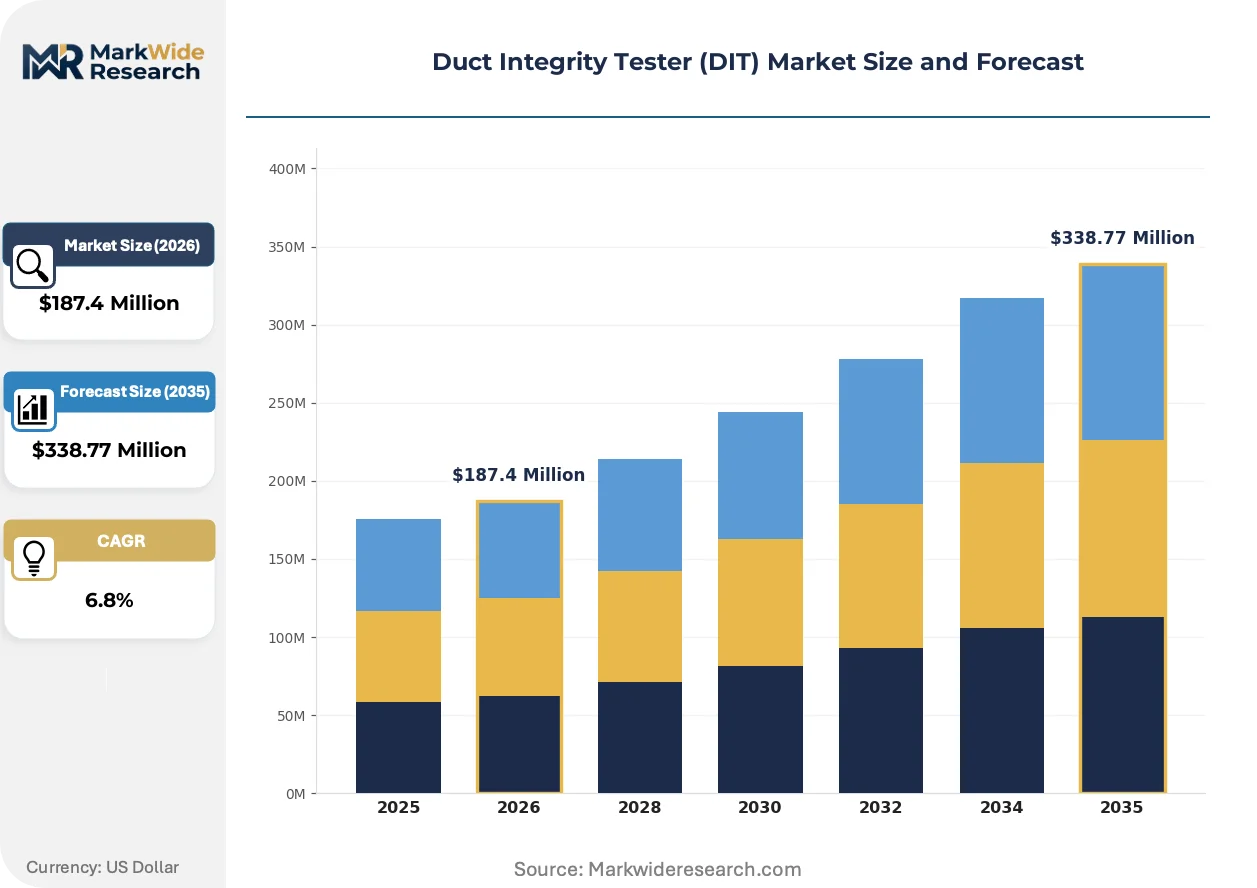
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Stationary Testers, Automated Systems, Software Solutions Application: HVAC Systems, Industrial Ventilation, Residential Ducts, Commercial Infrastructure End User: Manufacturers, Contractors, Facility Managers, Inspectors Technology: Pressure Decay, Smoke Testing, Infrared Thermography, Ultrasonic Measurement |
| Companies Covered | Fluke Corporation, Retrotec Inc., Megger Group Limited, Kanomax USA, Inc., Dwyer Instruments, Inc., The Energy Conservatory, PCE Instruments, SebaKMT, TSI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duct Integrity Tester (DIT) Market Shifts & Advancements
Connectivity and documentation automation are redefining competitive advantage as buyers prioritize audit-ready data streams over standalone measurement accuracy, compressing the viable product architecture toward integrated systems.
Wireless sensor arrays for distributed pressure mapping are modularizing field deployment configurations, allowing commissioning agents to reconfigure test node placement across complex duct geometries without recalibration delays. Commercial retrofit contractors in California's Title 24 corridors are adopting these systems for large-footprint warehouse and healthcare projects. The technology is modularizing what previously required multiple handheld units and manual logging, collapsing labor hours per test by enabling simultaneous multi-point measurement.
The U.S. Department of Energy's appliance and equipment standards are tightening leakage thresholds for federal building procurement, conditioning DIT accuracy specifications on 25 Pascal test pressure resolution. Manufacturers serving GSA schedule contracts must now document calibration traceability to NIST standards. Federal facility managers are responding by specifying automated systems with embedded calibration verification routines, displacing portable units in public building portfolios.
Service unbundling is fragmenting the traditional equipment-sale model as third-party calibration and certification providers capture recurring revenue streams. Independent testing laboratories in the Northeast are offering subscription-based equipment access with included traceability documentation, displacing capital purchase decisions for smaller commissioning firms. This shift is most visible in Massachusetts and New York deep decarbonization zones where project volume fluctuation makes ownership economics marginal.
Duct Integrity Tester (DIT) Market Segmentation
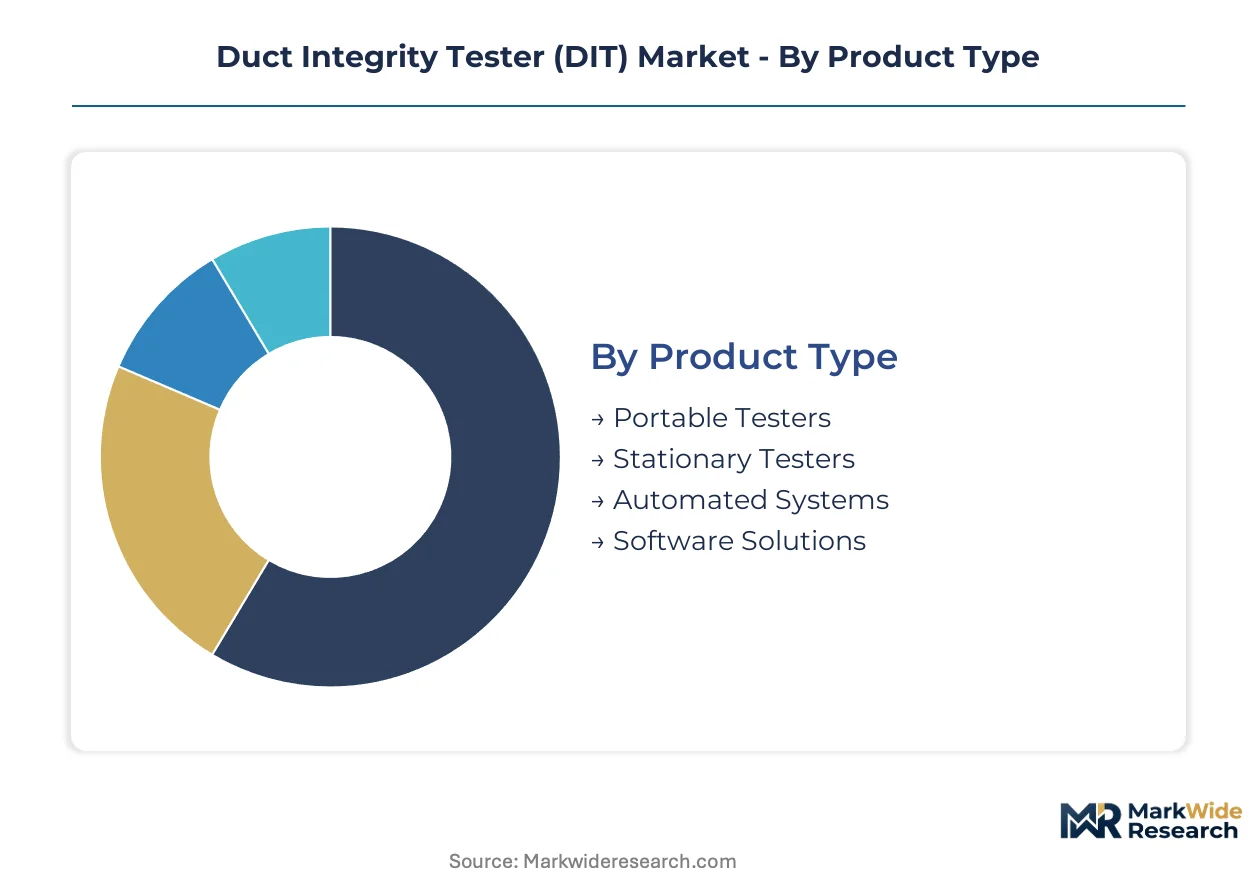
Duct Integrity Tester market segmentation reveals how deployment complexity and compliance documentation requirements reshape product architecture. Buyers sort across mobility needs, automation depth, and integration with building management platforms.
Product Type:
Portable units dominate standalone field use while automated systems embed into networked facility infrastructure, creating divergent margin profiles and service attach rates.
- Portable Testers:Battery-powered units with pressure transducers rated for 25 Pascal resolution serve electrical contractors and commissioning agents requiring job-site mobility. California Title 24 compliance corridors drive replacement cycles as technicians demand lighter form factors with Bluetooth documentation export. Volume placements concentrate in this segment; the faster expansion belongs to Automated Systems.
- Automated Systems:Rack-mounted or permanently installed configurations integrate pressure decay hardware with building automation protocols for continuous commissioning in large commercial portfolios. Deep decarbonization zones in Massachusetts and New York favor these systems for REIT properties seeking audit trail standardization without manual operator intervention.
- Stationary Testers:Bench-top laboratory instruments serve manufacturing quality control for ductwork fabricators verifying assembly tightness before shipment.
- Software Solutions:Cloud-based compliance documentation platforms aggregate test data from distributed hardware, generating timestamped reports for EPA ENERGY STAR certification submissions.
Contractor channel economics favor portable ownership; facility management contracts tilt toward automated system subscriptions with embedded calibration services.
Application:
Commercial infrastructure commands premium pricing for documentation automation while residential ducts sustain volume through inspector channel penetration.
- Commercial Infrastructure:Healthcare campuses and warehouse distribution centers deploy wireless sensor arrays for multi-point pressure mapping across complex duct geometries. The U.S. Department of Energy's tightening federal building standards condition procurement specifications on NIST-traceable calibration verification.
- HVAC Systems:New construction and major alteration projects in California's Title 24 corridors require leakage verification at rough-in and final inspection stages, sustaining handheld tester demand.
- Industrial Ventilation:Heavy-duty ventilation environments expose instrumentation to temperature cycling that accelerates sensor drift, shortening recalibration intervals.
- Residential Ducts:EPA ENERGY STAR for Homes certification mandates duct tightness verification, expanding inspector demand in new construction subdivisions.
Commercial applications absorb automated system deployment; residential markets remain portable-dominant due to inspector mobility requirements.
End User:
Facility managers prioritize integration depth while contractors optimize for capital efficiency and technician training minimization.
- Facility Managers:Large property portfolios specify cloud-connected DIT platforms that feed continuous commissioning data into centralized building management systems, collapsing labor hours per audit cycle.
- Contractors:Electrical and HVAC contractors in North American metropolitan testing laboratory zones favor portable units with rapid recalibration turnaround to maintain project schedules.
- Inspectors:Code enforcement officials require SMACNA-certified test protocols with tamper-evident documentation for Title 24 and stretch code compliance filings.
- Manufacturers:Ductwork fabricators utilize stationary testers for pre-shipment quality control, verifying assembly tightness against SMACNA leakage class specifications.
Contractor purchases drive unit volume; facility management contracts generate recurring software and calibration revenue.
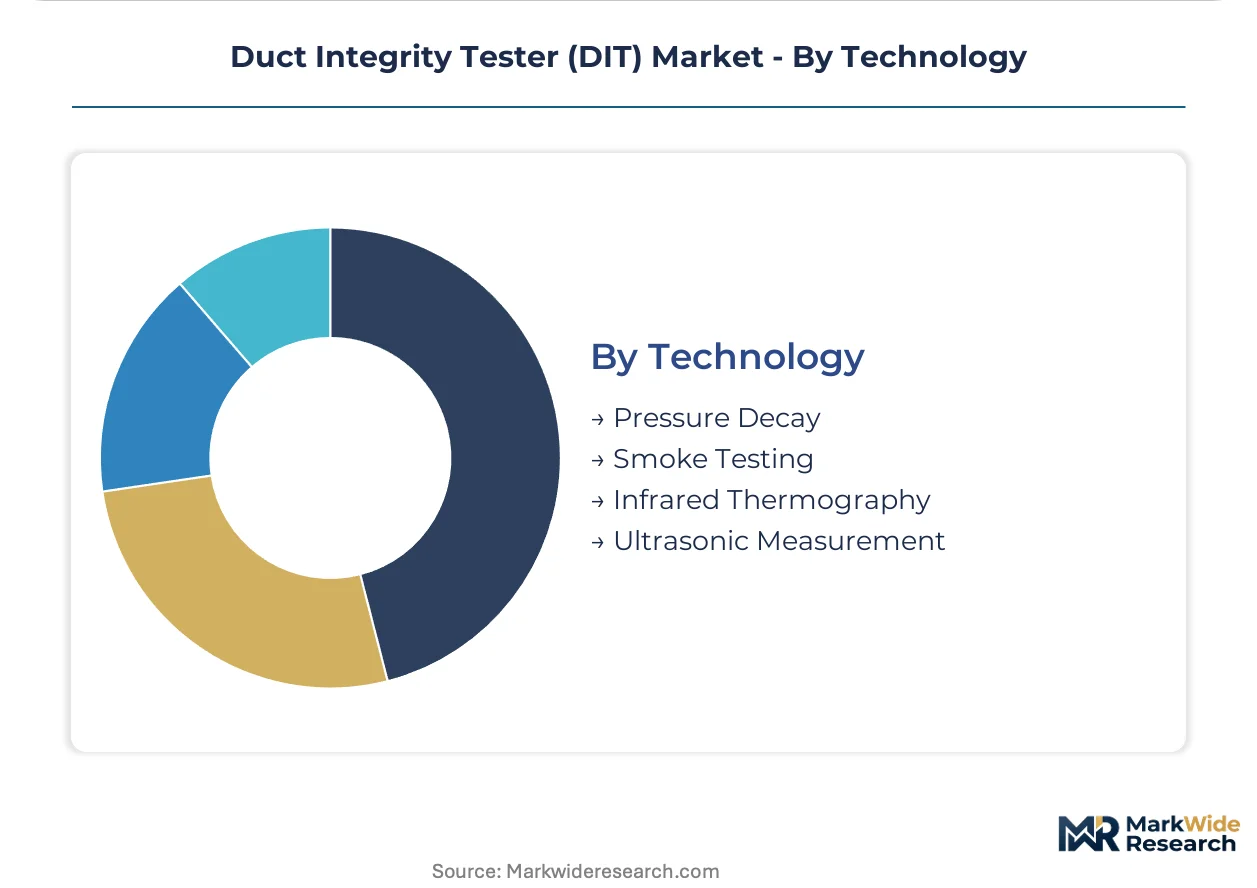
Technology:
Protocol alignment with ASHRAE and SMACNA standards conditions technology selection, with non-destructive methods gaining retrofit application share.
- Pressure Decay:The dominant installed base aligns with ASHRAE Standard 90.1 and SMACNA HVAC Air Duct Leakage Test Manual protocols, resolving leakage rates at standardized 25 Pascal differential pressure.
- Infrared Thermography:Thermal imaging enables non-destructive spot inspection of existing ductwork without system shutdown, penetrating deep decarbonization retrofit markets where pressurization testing disrupts occupied buildings.
- Smoke Testing:Visual leak location methods supplement quantitative pressure decay results in commissioning applications requiring pinpoint remediation guidance.
- Ultrasonic Measurement:High-frequency acoustic detection identifies leakage paths in inaccessible duct sections where physical access limits traditional test port placement.
Pressure decay retains protocol dominance; infrared thermography climbs fastest in existing building audit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area commissioning firms drive automated DIT adoption as California's Title 24 enforcement tightens duct leakage verification requirements across commercial retrofits and new construction corridors.
United States
Federal building procurement standards issued by the Department of Energy condition GSA schedule contracts on NIST-traceable calibration documentation. Deep decarbonization zones in Massachusetts and New York embed duct tightness into net-zero retrofit pathways, sustaining inspector demand for SMACNA-certified instrumentation. Greater Boston property managers deploy cloud-connected systems for continuous commissioning in REIT portfolios.
Germany
The EU Green Deal and national building energy efficiency regulations accelerate leakage testing mandates in commercial HVAC renovation projects. REACH compliance requirements shape sensor material specifications for pressure transducers deployed in industrial ventilation environments. The Rhine-Ruhr metropolitan region concentrates fabrication quality control demand as ductwork manufacturers verify assembly tightness before export shipment.
China
Dual carbon goals and GB standards for building energy efficiency expand commissioning agent demand in Yangtze River Delta megaprojects. The Ministry of Ecology and Environment enforces industrial ventilation performance standards that condition factory audit protocols on quantitative leakage measurement. Shanghai's Pudong district anchors automated system deployment as smart building integration requirements penetrate premium commercial developments.
Japan
METI building energy conservation standards tighten duct performance thresholds for commercial facilities undergoing efficiency retrofits. JIS protocol alignment conditions domestic procurement specifications on pressure decay method accuracy at standardized test pressures. The Kansai region around Osaka sustains manufacturing quality control demand as ductwork fabricators serving Southeast Asian export markets verify assembly specifications.
United Kingdom
Building Regulations Part L and Future Homes Standard implementation expand residential duct tightness verification requirements in new construction subdivisions. The London metropolitan area concentrates inspector channel demand as EPA ENERGY STAR-equivalent certification programs gain traction among volume homebuilders. Midlands-based commissioning firms extend service coverage into deep retrofit zones targeting net-zero pathway compliance.
Duct Integrity Tester (DIT) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the DIT market as automated system developers invest in cloud infrastructure while portable tester specialists outsource sensor manufacturing. The vendor base stratifies across three tiers: integrated building automation platforms, precision instrumentation incumbents with calibration ecosystems, and regional assembly operations serving price-sensitive contractor channels. Consolidation pressure concentrates among portable tester manufacturers as Bluetooth documentation export becomes table stakes. Dominant competitive moves include backward integration into pressure transducer supply and geographic expansion through distributor certification programs.
Within the precision instrumentation tier, Fluke Corporation and Retrotec Inc. exemplify divergent channel strategies. Fluke leverages its multimeter distribution network to place portable testers into electrical contractor channels, while Retrotec anchors the North American calibration and training ecosystem through certification programs that sustain dealer loyalty. Megger Group Limited occupies a position on industrial ruggedness, extending its insulation-test heritage into heavy-duty ventilation environments where temperature cycling accelerates sensor drift.
| Leading Market Players |
|---|
| Fluke Corporation |
| Retrotec Inc. |
| Megger Group Limited |
| Kanomax USA, Inc. |
| Dwyer Instruments, Inc. |
| The Energy Conservatory |
| PCE Instruments |
| SebaKMT |
| TSI Incorporated |
| Others |
Supply & Pricing Matrix
Large REIT portfolio managers and federal facility procurement officers concentrate purchasing power for automated DIT systems, anchoring pricing around NIST-traceable calibration verification and cloud-connected documentation bundles rather than hardware unit costs alone.
Pricing Analysis
Outcome-based pricing tied to compliance audit success rates anchors automated system value propositions, while portable testers transact on per-unit hardware margins with Bluetooth documentation export as a standard feature. Three-tier pricing structure across premium, standard, and economy levels separates systems with embedded calibration verification from field-recalibration-dependent units. Cost compression in the portable segment intensifies as Fluke's multimeter distribution network and Retrotec's certification programs squeeze regional assemblers. Contractor channels exhibit highest price sensitivity; facility management contracts demonstrate lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
Freight costs from Asian pressure transducer suppliers amplify landed costs for North American portable tester assemblers, compressing margins on battery-powered units shipped to California Title 24 corridors. Component sourcing draws from China for MEMS pressure sensors, Germany for precision pump assemblies, and Japan for temperature-stable transducer housings. Single-source vulnerability concentrates in NIST-traceable calibration gas suppliers, where metropolitan laboratory capacity constraints extend turnaround times. Distribution runs through electrical contractor supply houses for portable units and direct specification for automated systems in GSA schedule contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DIT market functions as a vertical-integration race where control over pressure transducer supply and calibration infrastructure determines margin capture, with automated system developers pursuing backward integration into sensor manufacturing while portable specialists defend channel position.
For Market Incumbents: Extend calibration service networks into secondary markets to preempt independent laboratory subscription models threatening equipment-sale revenue. Deepen embedded sensor verification routines in automated platforms to displace portable units in federal building portfolios, countering Megger's industrial ruggedness positioning. For New Entrants and Emerging Players: California Title 24 in the United States opens a window for wireless sensor array specialists to penetrate commercial retrofit corridors with modular multi-point pressure mapping systems. Target existing building audit expansion in Massachusetts and New York deep decarbonization zones, leveraging infrared thermography integration as a non-destructive entry wedge against incumbent pressure decay protocols. For Investors and Strategic Acquirers: The window for entry favors precision instrumentation platforms with captive calibration ecosystems and established SMACNA training relationships. Long-term viability hinges on cloud-connected documentation attach rates in REIT portfolios. Monitor EPA ENERGY STAR for Homes certification program expansion as the inflection signal for residential inspector channel penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Transducer Supply | Captive MEMS sensor production insulates margin pressure from Asian component volatility and accelerates calibration verification routine development. |
| Cloud-Connected Documentation Platform Launch | Timestamped compliance report automation penetrates REIT portfolios seeking audit trail standardization without manual operator intervention. |
| SMACNA Certification Program Expansion | Dealer loyalty anchoring through technician training ecosystems sustains replacement cycle capture against Fluke's electrical contractor channel reach. |
| Infrared Thermography Module Integration | Non-destructive inspection capability opens existing building retrofit markets where pressurization testing disrupts occupied healthcare and warehouse operations. |
| Geographic Distributor Certification Rollout | Metropolitan testing laboratory zone coverage reduces recalibration turnaround times for contractor purchasers in California and Northeast compliance corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with commissioning agents, facility managers, SMACNA-certified technicians, and calibration laboratory directors. SMACNA HVAC Air Duct Leakage Test Manual protocols, ASHRAE Standard 90.1 documentation, and EPA ENERGY STAR certification program guidelines provided regulatory baselines. Bottom-up unit shipment estimates from electrical contractor supply channels reconciled against top-down federal procurement database extractions.
Data-stream reconciliation across product type, application, end user, and technology dimensions shaped the analytical framework across the analysis window. CAGRs derived from segment-level adoption curves weighted by compliance mandate implementation timelines. Federal building performance standard tightening and state-level stretch code evolution served as primary demand-side forecast inputs, with sensor technology cost curves informing supply-side constraints.
The model assumes a particular technology adoption path; alternative pathways for infrared thermography penetration would alter the outlook if non-destructive methods displace pressure decay protocols faster than projected. Forecasts reflect stated assumptions regarding Title 24 enforcement intensity and NIST calibration infrastructure expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Sound Level Measurement Meter Market