
 X-Ray Inspection System for Secondary Battery Market | 2026-2036
X-Ray Inspection System for Secondary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Inspection System for Secondary Battery Market Insights
Multi-source procurement of X-ray tubes and detector arrays is hardening across the secondary battery supply chain. Toshiba anchors its position through captive production of microfocus X-ray sources for cylindrical cell inspection. Comet Group leverages its Swiss-engineered high-voltage generators to sustain premium positioning in European battery plants. Viscom AG differentiates through software-integrated automated optical and X-ray hybrid platforms that occupy the quality-control layer for pouch-cell manufacturers.
An X-ray inspection system for secondary batteries employs penetrating electromagnetic radiation with tube voltages typically ranging from 80 kV to 300 kV to detect internal defects in lithium-ion electrode windings, separator alignment, and electrolyte fill levels without destroying the cell. Automated systems lead volume deployment across Gigafactory lines where throughput demands exceed 300 cells per minute, while 3D imaging and computed tomography segments capture expanding margin pools as solid-state and silicon-anode designs require deeper volumetric analysis. Portable systems remain a smaller but stable category serving aftermarket services and field failure investigations.
The EU Battery Regulation mandates digital passports and conformity assessment procedures that elevate compliance testing as a mandatory end-use segment. China's NMPA enforces GB standards for thermal runaway propagation testing, pushing manufacturers toward real-time imaging systems capable of detecting micro-defects that trigger catastrophic failure. South Korea's MFDS aligns with IEC 62660 cell safety protocols, reinforcing Seoul-area demand for certified inspection platforms. Stakeholders must weigh detector technology roadmaps against evolving regional certification requirements when allocating R&D budgets.
Market Dynamics
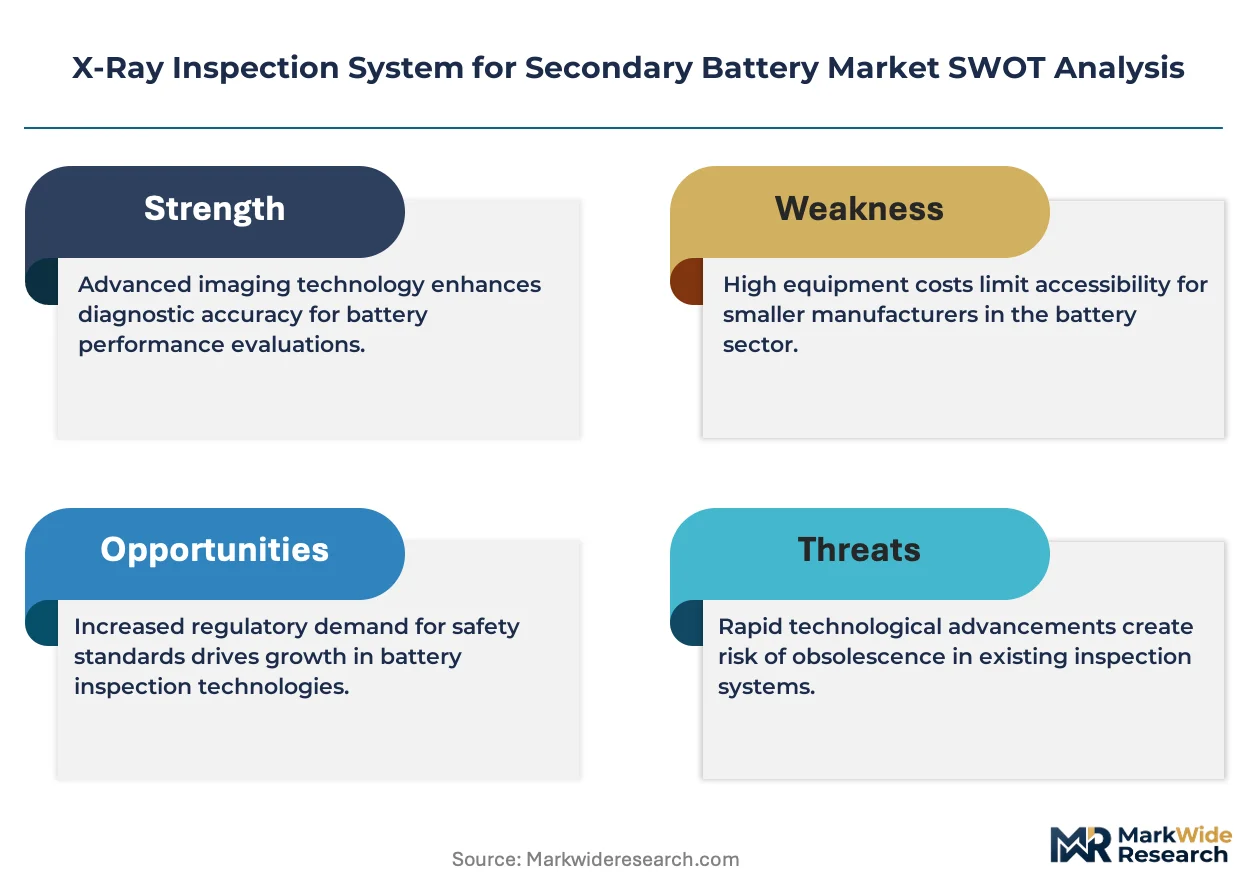
Electric vehicle manufacturers are consolidating in-house X-ray inspection capacity to secure cell quality control, compressing the independent system vendor base while elevating technical specifications for real-time defect detection at Gigafactory throughputs.
Growth Catalysts
- EU Battery Regulation:Digital passport mandates and conformity assessment procedures elevate compliance testing as a mandatory end-use segment, forcing manufacturers to deploy certified inspection platforms.
- Solid-state cell commercialization:Silicon-anode and solid-state designs require deeper volumetric analysis through 3D imaging and computed tomography, expanding margin pools for advanced systems.
- Seoul-area Gigafactory corridor:CATL and LG Energy Solution operations concentrate demand for high-volume automated lines exceeding 300 cells per minute.
Market Restraints
- Tungsten filament supply concentration:Microfocus X-ray source production depends on captive supply chains anchored in East Asian metallurgy, exposing vendors to input volatility.
- Detector array technical limitation:Amorphous silicon flat-panel detectors face resolution ceilings below 50 micrometers for high-speed cylindrical cell inspection.
- China NMPA certification friction:GB standards for thermal runaway propagation testing extend approval timelines by 8-14 months for non-domestic equipment suppliers.
Strategic Opportunities
- Aftermarket service channel:Portable X-ray systems for field failure investigations remain underpenetrated relative to installed base growth in Europe and North America.
- India PLI scheme:Cell manufacturing incentives are attracting Gigafactory investments near Gujarat and Tamil Nadu, creating first-mover positioning for inspection vendors.
- AI-integrated defect classification:Machine learning convergence with automated optical and X-ray hybrid platforms enables predictive quality control layer differentiation.
Industry Challenges
- Multiphysics simulation expertise gap:Vendors struggle to recruit talent capable of modeling X-ray scatter, thermal drift, and mechanical vibration in unified inspection environments.
- IEC 62660 certification timeline:MFDS-aligned cell safety protocols in South Korea require extensive validation documentation, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Inspection System for Secondary Battery Market |
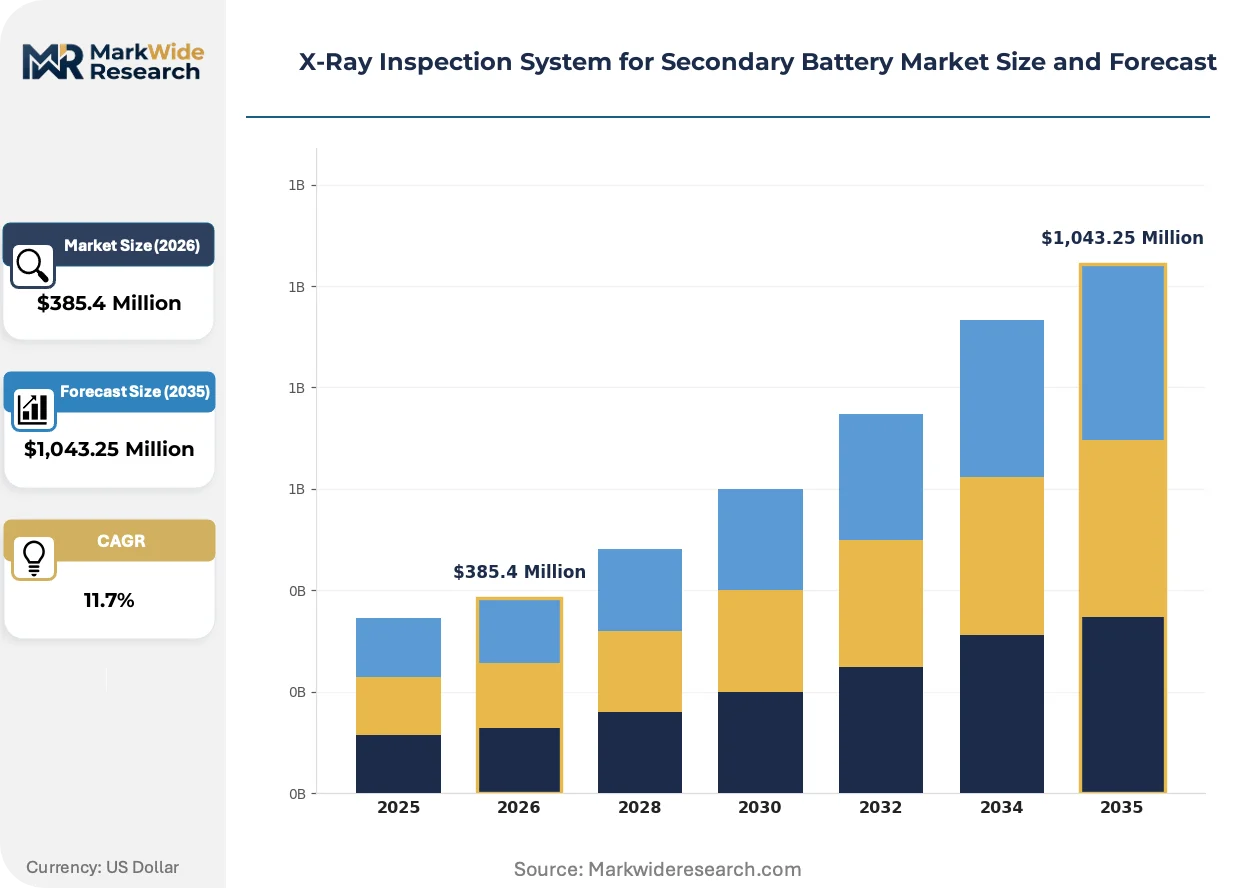
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Systems, Portable Systems, Automated Systems, Manual Systems Technology: 2D Imaging, 3D Imaging, Computed Tomography, Real-Time Imaging End User: Manufacturers, Quality Control Labs, Research Institutions, Aftermarket Services Application: Defect Detection, Material Analysis, Structural Inspection, Compliance Testing |
| Companies Covered | LINEV Systems, Tomra, STEINERT, Toshiba, Mettler Toledo, Nordson Corporation, Comet Group, Viscom AG, YXLON International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Inspection System for Secondary Battery Market Trends and Innovations
Computed tomography is overtaking conventional 2D radiography as the dominant inspection modality for next-generation battery architectures, while regulatory digitization and procurement centralization reshape competitive positioning across the supply chain.
Computed tomography systems with sub-10-micrometer resolution are overtaking line-scan radiography for electrode winding defect detection. Solid-state and silicon-anode cell manufacturers in South Korea and Germany are adopting volumetric inspection at pilot scale. This technology is overtaking planar imaging as the quality gate for high-nickel cathode cells where internal short-circuit risks demand three-dimensional separator alignment verification.
China's NMPA enforcement of GB standards for thermal runaway propagation testing is mandating real-time imaging capabilities. Battery plants must now document micro-defect detection thresholds as part of production release protocols. Cylindrical cell lines serving export markets are retrofitting automated X-ray stations to satisfy dual compliance with NMPA and IEC 62660 requirements.
Centralized procurement through OEM engineering divisions is displacing distributed purchasing by individual Gigafactory quality managers. Volkswagen, Tesla, and BYD have established global equipment qualification frameworks that compress vendor lists to pre-approved system integrators. This concentration is most visible in Germany and China, where battery engineering centers now dictate inspection platform specifications for their entire manufacturing networks.
X-Ray Inspection System for Secondary Battery Market Segmentation
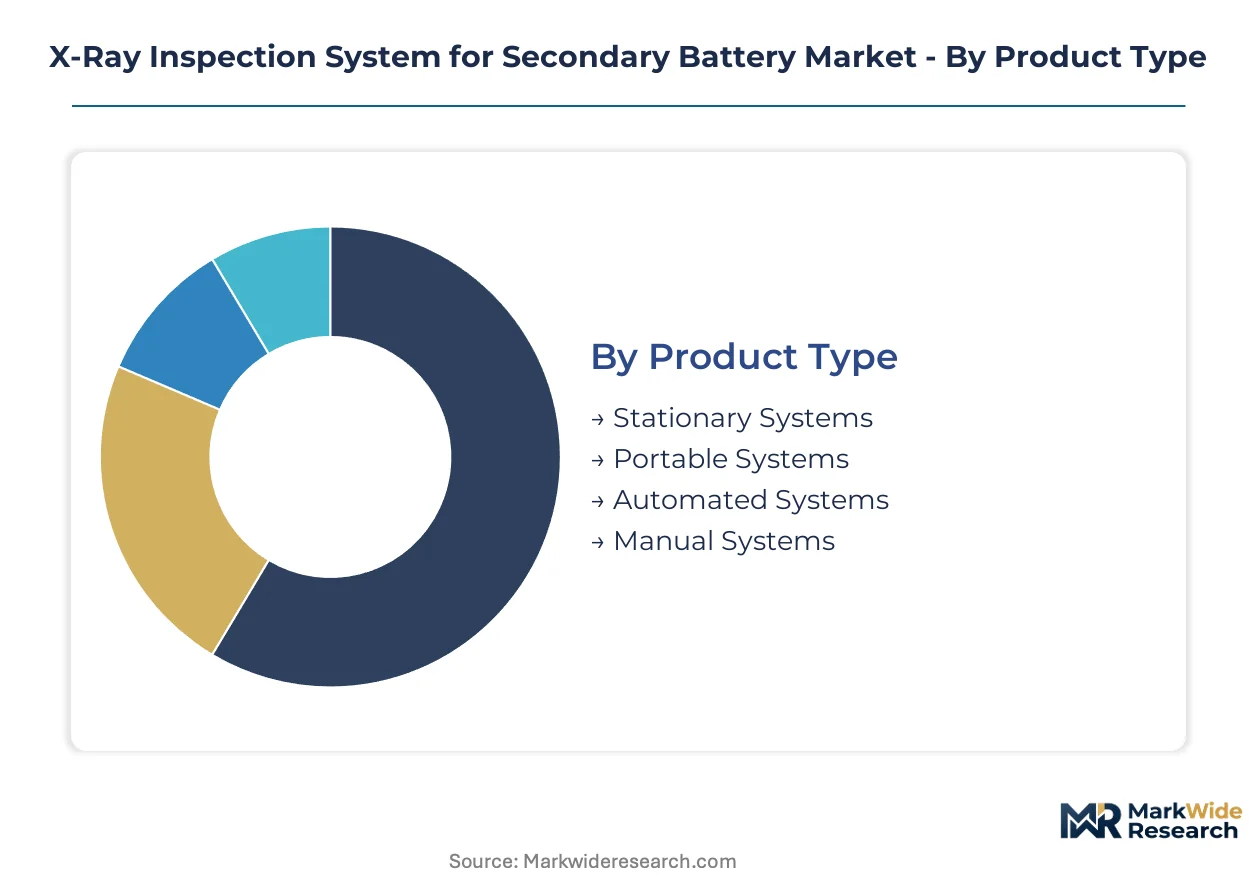
X-ray inspection architectures diverge sharply across battery manufacturing workflows. Procurement decisions hinge on throughput requirements, cell format complexity, and the regulatory stringency of target export markets.
Product Type:
Capital allocation intensity separates buyer tiers more than any technical specification.
- Automated Systems:These platforms integrate conveyor-fed cell handling with machine-vision feedback loops operating above 300 units per minute. Demand clusters at CATL and LG Energy Solution facilities in South Korea's Seoul corridor, where line downtime costs exceed equipment depreciation.
- Stationary Systems:Fixed-installation configurations dominate incoming quality control stations at Gigafactory scale, anchoring volume through multi-year framework agreements with Volkswagen and BYD engineering divisions.
- Portable Systems:Battery-powered field units serve aftermarket failure investigations at third-party service centers.
- Manual Systems:Operator-loaded benchtop configurations persist in pilot lines and R&D environments.
Volume sits with Automated Systems; growth tilts toward Portable Systems.
Technology:
Resolution thresholds and cycle time tradeoffs dictate modality selection for next-generation cell architectures.
- Computed Tomography:Sub-10-micrometer volumetric reconstruction enables three-dimensional separator alignment verification in solid-state and silicon-anode designs. German and South Korean pilot lines are adopting these systems ahead of IEC 62660 certification requirements.
- 3D Imaging:Stereo radiographic techniques reconstruct depth without full rotation, occupying the middle ground for high-nickel cathode cells where internal short-circuit risks demand more than planar inspection.
- 2D Imaging:Line-scan radiography retains cost advantage for cylindrical cell mass production.
- Real-Time Imaging:Continuous frame capture supports thermal runaway propagation testing under China's NMPA GB standards.
Installed base concentrates in 2D Imaging; capability investment flows toward Computed Tomography.
End User:
Procurement centralization through OEM engineering centers is collapsing traditional vendor diversity.
- Manufacturers:In-house inspection capacity expansion at Tesla, BYD, and Volkswagen compresses independent system vendor opportunity while elevating technical specifications for real-time defect classification.
- Quality Control Labs:Third-party certification bodies in Germany and China deploy reference-standard platforms for NMPA and EU Battery Regulation conformity assessment.
- Aftermarket Services:Field failure investigation providers represent an underpenetrated channel relative to installed base growth.
- Research Institutions:Academic and national laboratory procurement supports pre-commercial solid-state cell development.
Revenue weight rests with Manufacturers; margin expansion favors Quality Control Labs.
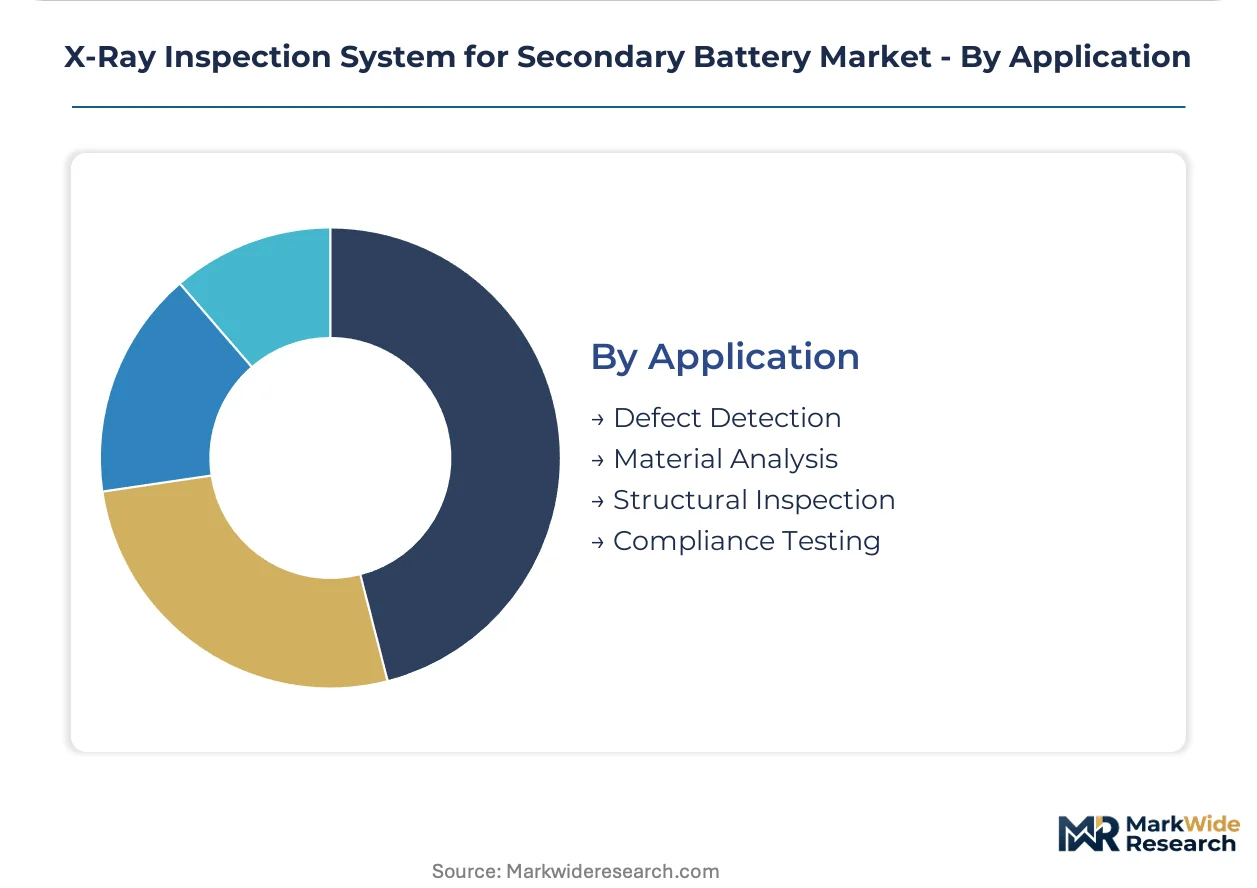
Application:
Regulatory digitization is elevating documentation-intensive use cases above pure production quality control.
- Compliance Testing:EU Battery Regulation digital passport mandates and NMPA thermal runaway documentation requirements transform conformity assessment into a standalone equipment category with dedicated capital budgets.
- Defect Detection:Electrode winding misalignment and separator breach identification anchors throughput-sensitive Gigafactory deployment.
- Material Analysis:Electrolyte fill level verification and contaminant screening support process development.
- Structural Inspection:Housing integrity and weld quality assessment serves prismatic and pouch cell formats.
Deployment scale favors Defect Detection; value capture is climbing fastest in Compliance Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten filament supply chains anchored in East Asian metallurgy shape geographic deployment patterns for X-ray inspection systems serving secondary battery manufacturing.
China
CATL and BYD drive automated inspection line procurement across Gigafactory networks in Fujian and Guangdong provinces. NMPA enforcement of GB standards for thermal runaway propagation testing mandates real-time imaging documentation. Shenzhen and Ningbo engineering centers dictate equipment specifications for export-bound cylindrical cell production.
Germany
Volkswagen and BMW engineering divisions centralize procurement decisions for European battery plant networks. EU Battery Regulation digital passport requirements elevate conformity assessment into a standalone equipment category with dedicated capital budgets. Stuttgart and Munich anchor premium-tier system deployment for solid-state pilot lines.
South Korea
LG Energy Solution and Samsung SDI concentrate demand in the Seoul Capital Area corridor where line downtime costs exceed equipment depreciation. MFDS alignment with IEC 62660 cell safety protocols compresses product launch windows for certified inspection platforms. Incheon and Ulsan host high-volume automated lines exceeding 300 cells per minute.
United States
Tesla and Ford expand in-house inspection capacity to secure cell quality control across Gigafactory and BlueOval SK networks. IRA domestic content incentives accelerate capital deployment for battery manufacturing equipment. Michigan and Texas engineering centers establish global equipment qualification frameworks that compress vendor lists.
Japan
Panasonic and Toyota prioritize volumetric inspection adoption for solid-state cell development programs. METI technology roadmaps emphasize sub-10-micrometer resolution capabilities for next-generation electrode architectures. Kyoto and Osaka prefectures concentrate R&D procurement for pre-commercial solid-state quality control systems.
X-Ray Inspection System for Secondary Battery Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors secure detector array supply agreements and software integration alliances. The vendor base organizes around three tiers: diversified industrial conglomerates with captive X-ray source production, specialized inspection equipment manufacturers with hybrid platform capabilities, and emerging regional system integrators serving price-sensitive markets. Competitive moves concentrate on M&A for detector technology access and geographic expansion through local certification partnerships.
Among diversified technology conglomerates, Toshiba anchors premium positioning through in-house microfocus X-ray source production. Comet Group exemplifies Swiss-engineered component specialization for high-voltage generator supply to European battery plants. Viscom AG occupies the software-integrated hybrid platform tier, serving pouch-cell manufacturers with automated optical and X-ray quality control systems.
| Leading Market Players |
|---|
| LINEV Systems |
| Tomra |
| STEINERT |
| Toshiba |
| Mettler Toledo |
| Nordson Corporation |
| Comet Group |
| Viscom AG |
| YXLON International |
| Others |
Pricing and Supply Chain Analysis
Multiphysics simulation specialists concentrated in Germany and Japan command compensation premiums that widen spreads between premium-tier CT systems and standard radiography platforms. Labor-cost differentials for X-ray scatter modeling talent translate directly into tiered equipment pricing, with Stuttgart and Munich engineering centers extracting value through embedded software-service bundles.
Pricing Analysis
Warranty and field-service bundling separate premium CT vendors from unbundled standard-radiography suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification-grade differentiation—EU Battery Regulation-compliant platforms with digital passport integration command sustained premiums, while price erosion runs through economy-tier 2D line-scan systems serving high-volume cylindrical cell lines. Gigafactory procurement teams exhibit acute price sensitivity on per-cell inspection costs, whereas quality-control labs prioritize resolution specifications over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, Tesla, and BYD engineering divisions, compressing distributor margins. Tungsten filament supply draws from captive East Asian metallurgy, amorphous silicon flat-panel detectors source from Japanese and South Korean semiconductor fabs, and high-voltage generators anchor in Swiss precision engineering. Single-source vulnerability in microfocus X-ray tube production exposes vendors to input volatility. Distribution runs through certified system integrators pre-qualified under OEM global equipment frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfocus X-ray source fabrication capacity constraints prop pricing power for vendors with captive production, creating a supply-constrained market structure favoring incumbents with backward-integrated component supply.
For Market Incumbents: Anticipate detector array supply competition from emerging Asian semiconductor players by securing long-term offtake agreements with amorphous silicon flat-panel specialists. Certification investment for dual NMPA-EC conformity accelerates product launch windows and defends margin position against modular system integrators entering through software-only layers. For New Entrants and Emerging Players: AI-integrated defect classification algorithms offer a technology-first wedge into aftermarket services, the most penetrable white-space target relative to installed base expansion in Europe and North America. Portable system deployment for field failure investigations carries lower certification barriers than Gigafactory automated lines. Go-to-market execution should anchor on third-party service center partnerships rather than direct OEM qualification. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-platform specialists given convergence of automated optical and X-ray inspection layers. Long-term viability over a five-to-ten-year horizon favors vendors with software-integrated quality control architectures over pure hardware component suppliers. The signal to watch is MFDS-aligned IEC 62660 certification velocity as an inflection indicator for Seoul-corridor market access.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Technology Acquisition | Amorphous silicon flat-panel access secures resolution roadmaps for CT migration. |
| Certification Pre-Investment | Early NMPA GB standard alignment compresses approval timelines for export-bound equipment. |
| Software-Service Bundling | Embedded AI defect classification differentiates hybrid platforms at quality-control layer. |
| Aftermarket Channel Development | Portable system networks capture field failure investigation demand in North America. |
| Regional System Integrator Partnership | Local certification partnerships accelerate market entry under India PLI scheme incentives. |
Research Methodology
SEC filings from listed inspection equipment manufacturers, EU Battery Regulation implementation guidance documents, and NMPA GB standard technical specifications formed the secondary backbone. Primary interviews with Gigafactory quality engineering directors, X-ray tube procurement managers at diversified industrial conglomerates, and MFDS certification consultants validated demand assumptions. Bottom-up and top-down triangulation reconciled equipment shipment data against battery cell production capacity announcements across the analysis window.
Bottom-up modeling aggregated segment-level equipment deployment by technology modality, while top-down cross-checks applied battery manufacturing capital intensity ratios. Segmentation dimensions spanned product architecture, imaging resolution tier, cell format application, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to solid-state and silicon-anode commercialization timelines. Forecast inputs incorporated tungsten supply constraints and detector array production yield assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA certification timeline extensions or tungsten filament supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Photostability Chamber Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Ohm Meter Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Hour Meter Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
LAN Tester Market
Test and Measurement
Industrial Metrology Market