
 Failure Analysis Equipment Market | 2026-2036
Failure Analysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Failure Analysis Equipment Market Analysis
Gallium nitride is repositioning silicon carbide in high-voltage failure analysis workflows, altering equipment calibration protocols and capital allocation across inspection labs. Thermo Fisher Scientific leverages its mass spectrometry portfolio to anchor molecular analysis workflows in North American semiconductor labs. Oxford Instruments sustains superconducting sensor R&D intensity, differentiating its cryogenic atomic force microscopy systems for quantum device characterization. Hitachi High-Technologies Corporation dominates electron beam lithography-adjacent inspection tools in Japanese fabrication facilities.
Failure analysis equipment encompasses instruments that characterize material defects, structural anomalies, and performance degradation in manufactured components through electron, photon, or thermal probe interaction, typically operating at nanometer spatial resolution and femtoampere current sensitivity to isolate root-cause failure mechanisms in integrated circuits, composite structures, and metallurgical samples. Scanning electron microscopes occupy the largest installed base due to their versatility in cross-sectional imaging and elemental mapping, though X-ray fluorescence systems are gaining share for non-destructive solder joint inspection in automotive electronics. Image analysis software embedded in optical microscopes is maturing into a distinct margin pool as laboratories seek automated defect classification without electron-beam throughput constraints.
FDA device validation requirements and EPA hazardous substance reporting standards shape equipment procurement specifications in United States medical and industrial electronics labs, while REACH substance restrictions in Europe compel manufacturers to verify coating and plating compositions through certified spectroscopic methods. Semiconductor manufacturers must monitor how ISO 17025 accreditation requirements evolve for third-party failure analysis service providers, as this determines outsourcing eligibility for automotive safety-critical chip verification. Stakeholders should decide whether to internalize advanced focused ion beam capabilities or rely on certified external labs as node geometries shrink below three nanometers.
Market Dynamics
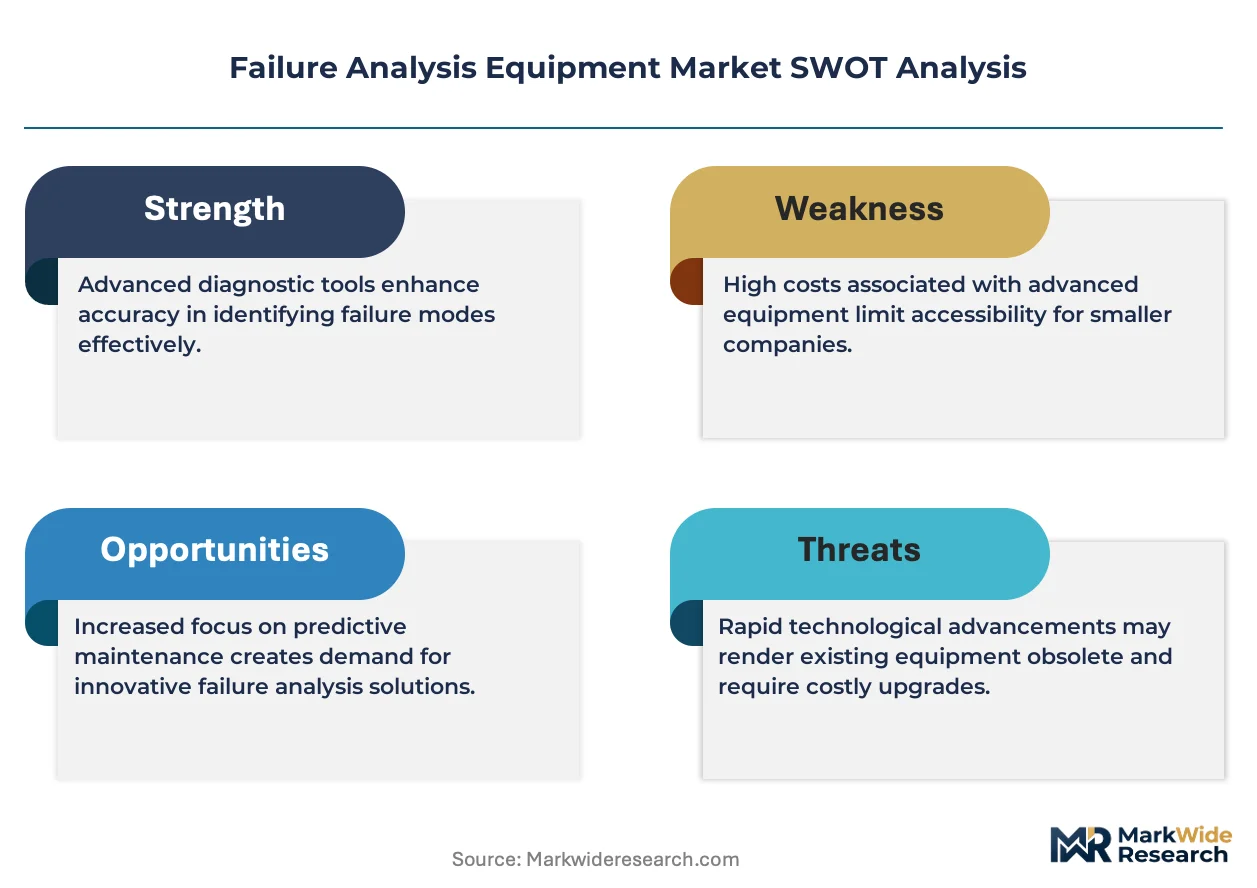
Node geometry compression below three nanometers is forcing semiconductor fabs to recalibrate failure analysis protocols, triggering capital redeployment toward atomic-resolution inspection systems and certified third-party verification services.
Growth Catalysts
- Advanced Node Verification Mandates:Sub-3nm chip production in Hsinchu and Pyeongtaek requires electron-beam systems with femtoampere sensitivity, pulling equipment upgrades across Taiwan and South Korea fabrication clusters.
- REACH Substance Restrictions:ECHA enforcement of coating and plating composition verification compels European electronics manufacturers to deploy certified spectroscopic methods for imported component validation.
- Gallium Nitride Process Migration:High-voltage power electronics manufacturers are reconfiguring inspection workflows as GaN displaces silicon carbide in automotive and industrial applications, altering calibration standards.
Market Restraints
- Helium Supply Concentration:Cryogenic atomic force microscopy depends on helium-3 and helium-4 sourced primarily from Qatar and Russia, exposing equipment operators to price volatility and export restriction risk.
- Technical Resolution Ceilings:Optical microscopy systems face hard physical limits at sub-10nm defect detection, forcing costly electron-beam adoption for advanced packaging inspection.
- FDA Validation Timelines:Medical device manufacturers in the United States encounter 18-24 month equipment qualification cycles under 21 CFR Part 820, compressing effective utilization windows.
Strategic Opportunities
- Automotive Safety-Critical Outsourcing:ISO 17025 accreditation gaps among third-party labs create white space for certified providers to capture automotive chip verification as in-house focused ion beam capacity saturates.
- India PLI Scheme Alignment:Semiconductor manufacturing incentives under India's production-linked incentive framework are attracting failure analysis equipment deployment to Gujarat and Tamil Nadu greenfield sites.
- AI-Accelerated Defect Classification:Machine vision convergence with electron microscopy is enabling real-time pattern recognition, reducing human operator bottlenecks in high-volume production environments.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Superconducting sensor operation and dilution refrigerator maintenance require specialized physicists and technicians unavailable in standard metrology training pipelines.
- Multi-Modal Integration Complexity:Correlating data across scanning electron, atomic force, and X-ray fluorescence platforms demands custom software architectures that fragment laboratory IT ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Failure Analysis Equipment Market |
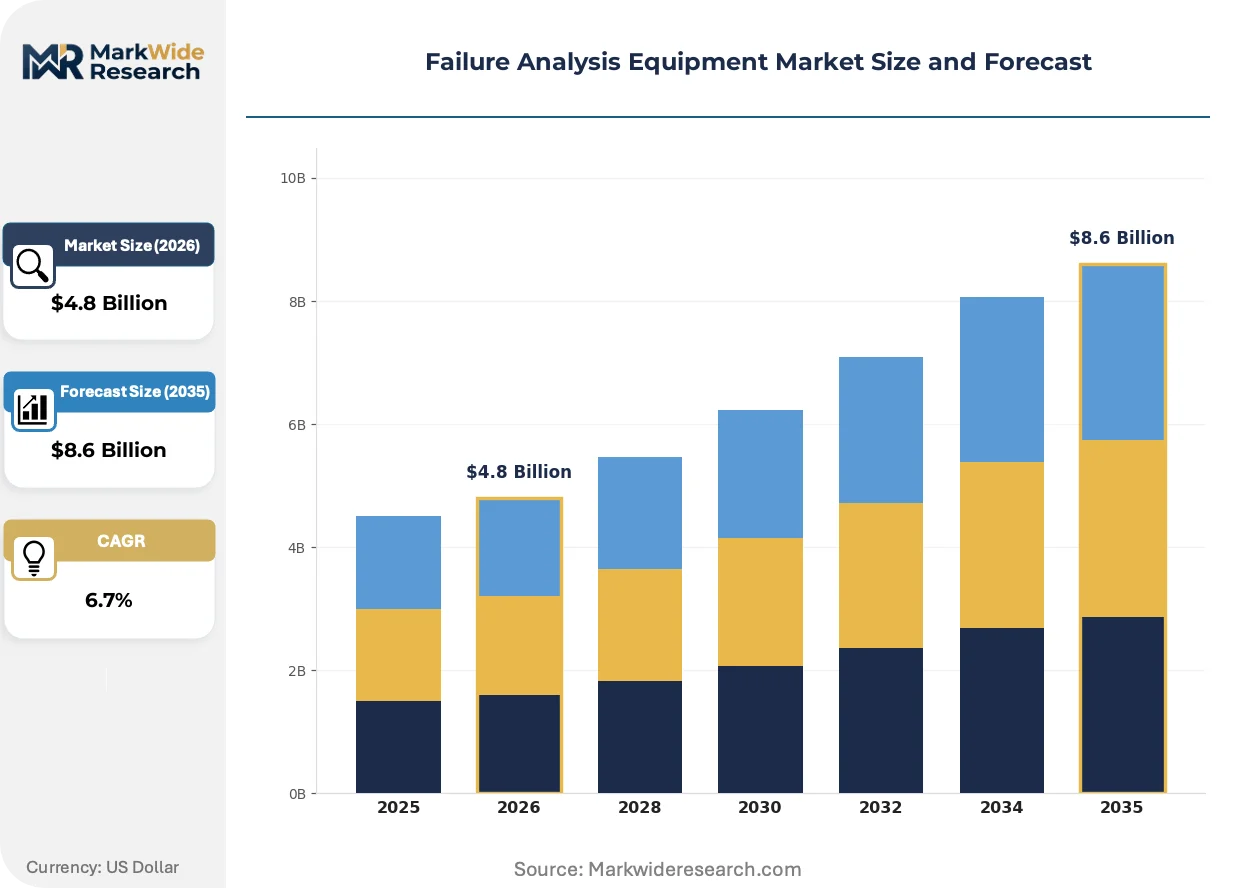
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scanning Electron Microscope, Optical Microscope, X-Ray Fluorescence, Thermal Analysis Technology: Augmented Reality, Image Analysis Software, Acoustic Emission, Signal Processing Application: Microelectronics, Aerospace Components, Automotive Components, Material Testing End User: Research Laboratories, Semiconductor Manufacturers, Automotive OEMs, Academic Institutions |
| Companies Covered | CARL Zeiss SMT GmbH, Oxford Instruments, Thermo Fisher Scientific Inc., Leica Microsystems GmbH, HORIBA Ltd., Hitachi High-Technologies Corporation, Bruker Corporation, TESCAN ORSAY Holding a.s., JEOL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Failure Analysis Equipment Market Emerging Trajectories
Workflow automation and probe technology convergence are compressing analysis cycle times while regulatory substance verification tightens material characterization requirements across electronics manufacturing.
Correlative microscopy platforms integrating electron-beam imaging with atomic force topography are electrifying defect localization workflows in advanced packaging labs. Memory and logic manufacturers in South Korea are deploying these hybrid systems at pilot scale. The technology is compressing time-to-root-cause from days to hours for three-dimensional stacked die failures.
EPA hazardous substance reporting standards under TSCA Section 8(a) are mandating granular material composition disclosure for imported electronics components. Industrial labs in the United States must now maintain chain-of-custody documentation from raw material to finished device. Medical device manufacturers face the steepest compliance burden as FDA device validation intersects with EPA reporting timelines.
Equipment-as-a-service contracts with bundled calibration and certification are displacing traditional capital purchase models among mid-sized contract laboratories. Third-party service providers in Germany and Japan are capturing recurring revenue streams that hardware vendors previously monopolized. Automotive electronics suppliers in Bavaria and Aichi Prefecture demonstrate the strongest uptake of performance-based service agreements.
Failure Analysis Equipment Market Segmentation
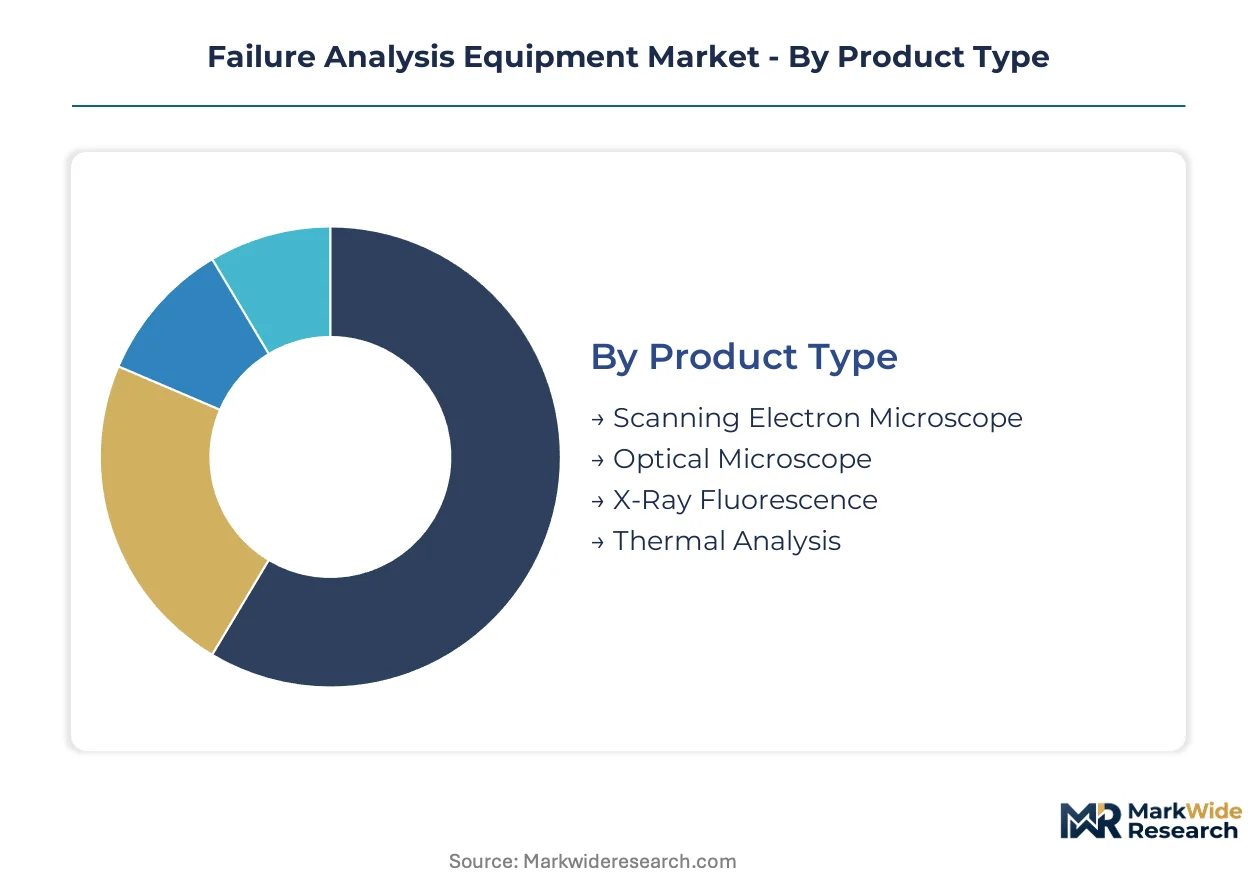
Equipment upgrade cycles in failure analysis labs vary sharply by product complexity, with electron-beam systems demanding decade-long depreciation schedules while software modules refresh biennially. Segmentation reveals where capital concentrates versus where operating budgets flow.
Product Type:
Replacement timelines stretch from five years for optical systems to fifteen for electron-beam platforms, creating distinct revenue rhythms across the installed base.
- Scanning Electron Microscope:These systems employ thermionic or field-emission electron sources to achieve sub-nanometer resolution on cross-sectioned semiconductor samples. Demand clusters around Hsinchu and Pyeongtaek fabrication facilities as sub-3nm node verification mandates femtoampere current sensitivity. Capital intensity limits procurement to tier-one semiconductor manufacturers and certified third-party labs.
- Optical Microscope:Image analysis software integration has transformed these instruments into automated defect classification engines without electron-beam throughput constraints. Automotive electronics suppliers in Bavaria deploy these for solder joint inspection where non-destructive evaluation suffices. Maturity compresses margins, though software attachments recover profitability.
- X-Ray Fluorescence:Non-destructive elemental mapping for coating verification under REACH substance restrictions.
- Thermal Analysis:Differential scanning calorimetry for polymer and composite failure mode characterization in aerospace applications.
Scanning Electron Microscope sits at the top of the volume ranking, with Image Analysis Software climbing the fastest.
Technology:
Margin profiles diverge between capital-intensive hardware layers and recurring software revenue streams that laboratories prefer for budget predictability.
- Image Analysis Software:Machine vision algorithms now execute real-time pattern recognition on electron microscopy feeds, collapsing defect classification from hours to minutes. South Korean memory manufacturers pilot these systems for three-dimensional stacked die analysis. Recurring licensing models displace perpetual purchases among mid-sized contract laboratories.
- Augmented Reality:Head-mounted displays overlay schematic data onto physical samples during probe station operation. German automotive electronics suppliers in Bavaria demonstrate strongest uptake for technician training and remote expert assistance. Hardware-software bundles complicate procurement negotiations.
- Acoustic Emission:Stress-wave monitoring for crack propagation in metallurgical samples under mechanical load.
- Signal Processing:Noise reduction algorithms for faint electrical fault detection in integrated circuits.
Image Analysis Software commands the highest margin tier, while Augmented Reality expands most quickly from negligible base.
Application:
End-use concentration determines whether equipment specifications prioritize throughput volume or analytical depth.
- Microelectronics:Node geometry compression below three nanometers demands correlative microscopy platforms integrating electron-beam imaging with atomic force topography. South Korean logic and memory manufacturers deploy hybrid systems at pilot scale. Time-to-root-cause compression from days to hours justifies premium pricing.
- Automotive Components:Safety-critical chip verification under ISO 17025 accreditation requirements drives outsourcing to certified third-party labs as in-house focused ion beam capacity saturates. Suppliers in Aichi Prefecture face the steepest compliance burden from overlapping FDA and EPA timelines for medical-industrial crossover devices.
- Aerospace Components:Titanium and composite structural analysis for fatigue crack initiation studies.
- Material Testing:General metallurgical and polymer characterization across industrial quality control labs.
Microelectronics absorbs the dominant equipment spend, with Automotive Components gaining share fastest on safety-critical outsourcing trends.
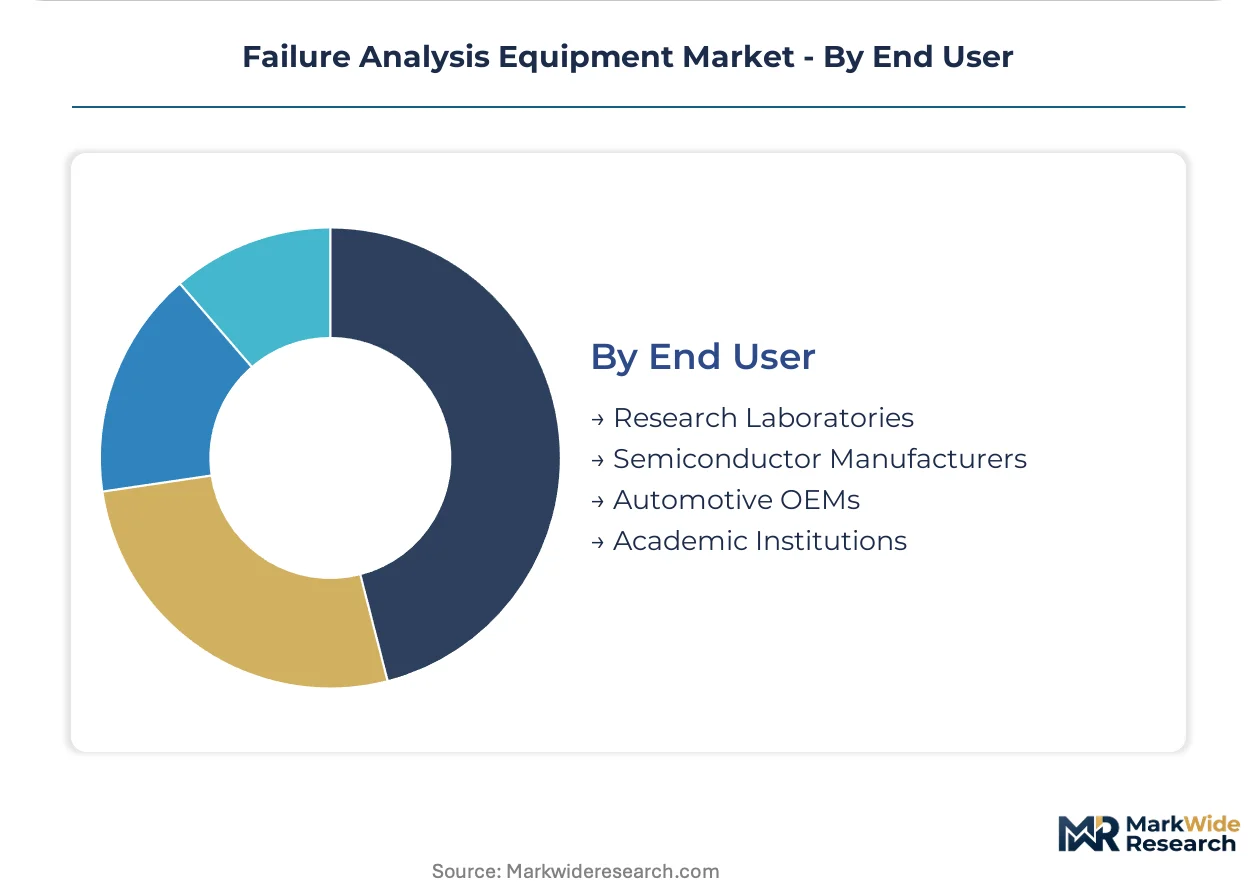
End User:
Procurement authority splits between capital-intensive internalization strategies and flexible outsourcing relationships.
- Semiconductor Manufacturers:Taiwan and South Korean fabrication clusters anchor demand for atomic-resolution inspection systems as advanced node verification mandates tighten. Internal focused ion beam capabilities face saturation thresholds below three nanometers, triggering certified third-party engagement.
- Research Laboratories:Equipment-as-a-service contracts with bundled calibration and certification displace traditional capital purchases. German and Japanese third-party service providers capture recurring revenue streams that hardware vendors previously monopolized. Performance-based agreements align vendor incentives with uptime outcomes.
- Automotive OEMs:In-house metrology investment for supplier audit and incoming inspection protocols.
- Academic Institutions:Grant-funded instrumentation for materials science and engineering research programs.
Semiconductor Manufacturers represent the largest installed base, with Research Laboratories accelerating fastest toward service-based consumption models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu anchors semiconductor fabrication demand for atomic-resolution inspection systems, pulling femtoampere-sensitive electron-beam equipment into Taiwan's advanced node verification workflows. Equipment procurement concentrates in three fabrication clusters across East Asia, with regulatory substance verification tightening material characterization requirements in European electronics manufacturing.
Taiwan
Sub-3nm node production at TSMC's Hsinchu Science Park drives femtoampere current sensitivity requirements for electron-beam systems. The island's National Development Council prioritizes semiconductor equipment localization under its Forward-Looking Infrastructure Plan. Tainan and Taichung fabrication facilities are expanding correlative microscopy platforms for three-dimensional stacked die analysis.
South Korea
Samsung and SK Hynix logic and memory operations in Pyeongtaek and Yongin mandate hybrid inspection systems combining electron-beam imaging with atomic force topography. The Ministry of Trade, Industry and Energy enforces K-REACH substance disclosure for coating verification in automotive electronics. Seoul Capital Area laboratories are piloting AI-accelerated defect classification for high-volume production environments.
United States
FDA device validation under 21 CFR Part 820 compresses equipment qualification cycles to 18-24 months for medical electronics manufacturers. EPA hazardous substance reporting standards under TSCA Section 8(a) mandate chain-of-custody documentation from raw material to finished device. Greater Boston and Silicon Valley research laboratories are adopting equipment-as-a-service contracts with bundled calibration.
Germany
Automotive electronics suppliers in Bavaria deploy optical microscopy with image analysis software for solder joint inspection where non-destructive evaluation suffices. ECHA enforcement of REACH coating and plating composition verification compels spectroscopic method deployment. Aachen and Dresden failure analysis service providers are capturing recurring revenue through performance-based service agreements.
Japan
Hitachi High-Technologies anchors electron beam lithography-adjacent inspection tool demand in Japanese fabrication facilities. METI's semiconductor equipment localization initiatives support domestic atomic force microscopy system development. Kyoto and Osaka industrial electronics labs face overlapping FDA and EPA timeline pressures for medical-industrial crossover devices.
Failure Analysis Equipment Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment vendors reposition around workflow automation and probe technology convergence. The vendor base organizes into three tiers: mass spectrometry and electron microscopy conglomerates, cryogenic sensor specialists, and regional optical system fabricators. Two strategic archetypes have emerged: integrated platform providers bundling hardware-software-service stacks, and modular component suppliers enabling laboratory customization. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire AI-accelerated defect classification capabilities.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific Inc. and Bruker Corporation exemplify platform integration strategies, while Oxford Instruments occupies a specialist position within cryogenic atomic force microscopy. These three entities represent contrasting archetypes: the mass spectrometry-anchored workflow provider, the multi-modal characterization conglomerate, and the superconducting sensor-differentiated niche player. Their collective positioning illustrates how electron-beam system vendors, optical microscope manufacturers, and cryogenic equipment specialists are converging on correlative microscopy platforms.
| Leading Market Players |
|---|
| CARL Zeiss SMT GmbH |
| Oxford Instruments |
| Thermo Fisher Scientific Inc. |
| Leica Microsystems GmbH |
| HORIBA Ltd. |
| Hitachi High-Technologies Corporation |
| Bruker Corporation |
| TESCAN ORSAY Holding a.s. |
| JEOL Ltd. |
| Others |
Supply Flow & Price Mechanics
Tier-one semiconductor manufacturers in Taiwan and South Korea command volume-based pricing leverage, anchoring contract structures around equipment-as-a-service bundles that shift capital risk to vendors. Equipment procurement concentrates in fabrication clusters where femtoampere-sensitive electron-beam systems justify premium calibration-inclusive terms.
Pricing Analysis
Helium-3 and helium-4 supply volatility from Qatar and Russia feeds directly into cryogenic atomic force microscopy operating cost structures, compressing margins for service providers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited labs from uncertified competitors and grant-funded academic installations. Cost compression in mid-tier optical systems is intensifying because image analysis software attachments commoditize hardware differentiation. Contract research organizations exhibit highest price sensitivity, while automotive safety-critical chip verification programs prioritize certification tier over unit economics.
Supply Chain Analysis
Superconducting sensor physicists and dilution refrigerator technicians remain scarce in Taiwan, South Korea, and Japan, constraining cryogenic equipment deployment velocity despite fabrication demand. Electron-beam column assemblies draw from German and Japanese precision optics suppliers, while helium isotopes rest on concentrated extraction from Qatar and Russian gas fields. Single-source vulnerability in specialty gas supply exposes equipment operators to export restriction cascades. Distribution runs through direct vendor-laboratory relationships for capital equipment, with third-party service providers capturing recurring calibration revenue in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Failure analysis equipment functions as a stable compounder, with node geometry compression below three nanometers generating sustained replacement demand across semiconductor fabrication clusters.
For Market Incumbents: To counter helium supply concentration disrupting cryogenic system operations, Thermo Fisher Scientific and Oxford Instruments should deepen backward integration into specialty gas recycling infrastructure and captive sensor fabrication. Certification investment in ISO 17025-accredited service networks defends against third-party lab outsourcing capture in automotive safety-critical verification. For New Entrants and Emerging Players: K-REACH in South Korea opens a window for coating verification spectroscopy specialists to capture automotive electronics supplier demand as ECHA-aligned substance disclosure mandates expand. India's PLI scheme for semiconductor manufacturing presents the most penetrable geography for greenfield equipment deployment. Equipment-as-a-service bundling with AI-accelerated defect classification software offers a differentiated go-to-market angle against capital-heavy incumbents. For Investors and Strategic Acquirers: Diversified instrumentation conglomerates are the most active acquirer in this space, consolidating AI-vision startups to augment electron microscopy platforms. Over a multi-year horizon, the market exhibits durable replacement cycle characteristics tied to node migration rather than cyclical capital expenditure volatility. Acquisition targets should display cryogenic sensor specialization or correlative microscopy software architecture. Helium supply contract renegotiation frequency serves as the signal to watch for margin stress inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Correlative Microscopy Platform Integration | Hybrid electron-beam and atomic force systems compress time-to-root-cause for TSMC and Samsung. |
| Equipment-as-a-Service Contract Expansion | Bundled calibration models shift revenue recurrence to German and Japanese third-party labs. |
| AI-Accelerated Defect Classification Development | Machine vision convergence reduces operator bottlenecks in SK Hynix high-volume environments. |
| Helium Recycling Infrastructure Investment | Captive isotope recovery mitigates Qatar and Russia supply concentration risk for cryogenic systems. |
| ISO 17025 Accreditation Network Buildout | Certified service capacity captures automotive safety-critical outsourcing as in-house FIB saturates. |
Methodological Framework
Direct dialogue with semiconductor fab equipment procurement directors, failure analysis lab managers, cryogenic system maintenance technicians, and third-party service provider executives grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K equipment vendor disclosures, ECHA REACH enforcement bulletins, Taiwan National Development Council infrastructure plans, and South Korea Ministry of Trade semiconductor policy documents. Bottom-up equipment shipment tracking and top-down fabrication capacity modeling enabled triangulation across independent analytical paths.
Bottom-up segmentation by product type, technology layer, application vertical, and end-user procurement authority structured volume and value outputs across the projection horizon. Analytical frameworks modeled electron-beam system depreciation schedules against software module refresh cycles, helium isotope price elasticity, and ISO 17025 accreditation penetration rates. CAGRs were derived from node geometry roadmaps and capital expenditure correlation analysis rather than extrapolated historical trends.
Revisions become necessary when helium export restrictions tighten, sub-2nm node timelines accelerate, or EPA hazardous substance reporting thresholds shift under TSCA Section 8(a) enforcement. Forecasts reflect assumptions about sustained Taiwan and South Korea fabrication cluster dominance and stable regulatory substance verification requirements. Material deviation in specialty gas supply availability or REACH scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Scratch Testers Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
PXI SMU Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Video Measuring System Market