
 China Edge AI Processor Market | 2026-2036
China Edge AI Processor Market Size, Share, and Industry Trends Forecast 2026-2036
China Edge AI Processor Market Insights
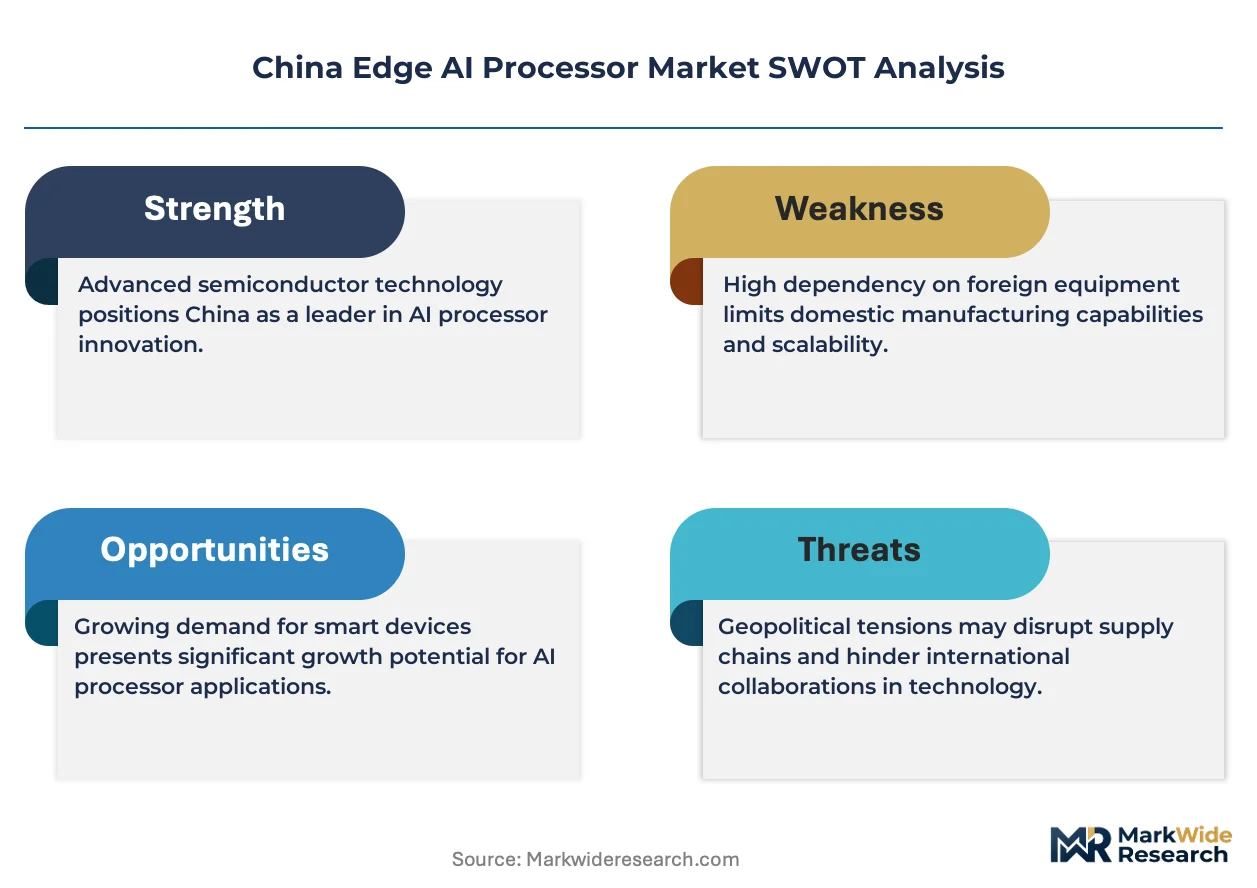
GB standards compliance for information security and data handling is restructuring the cost-of-entry calculus for foreign chip architectures in Chinese edge deployments. Huawei HiSilicon leverages its captive foundry partnerships to sustain supply continuity despite export control pressures. Horizon Robotics anchors its position through purpose-designed automotive inference silicon that dominates intelligent vehicle pilot programs. Cambricon Technologies specializes in datacenter-to-edge tensor processing unit migration, occupying a narrow but defensible niche in government-backed AI infrastructure.
China edge AI processors are integrated circuits engineered to execute machine learning inference at the network periphery with power envelopes typically below 15 watts and latency thresholds under 10 milliseconds, enabling real-time decision-making without cloud dependency for applications spanning factory automation, medical imaging, and autonomous navigation. ASIC designs command the deepest margin pools where volume commitments from automotive OEMs justify mask costs, while FPGA platforms retain flexibility leadership in prototyping phases across smart retail and industrial inspection workflows. GPU accelerators compete most aggressively in hybrid cloud edge nodes where training-inference convergence matters.
SAMR certification requirements and MIIT's dual carbon goals jointly shape product roadmaps, with efficiency benchmarks now gatekeeping access to state procurement channels and state-backed deployment subsidies. BIS-equivalent domestic standards for encryption and data sovereignty are forcing architectural redesigns in chips destined for healthcare and public safety endpoints. Stakeholders must monitor how NMPA medical device classification rules will extend to AI-enabled diagnostic equipment at the edge, as this regulatory boundary will determine which silicon suppliers qualify for hospital and clinic procurement.
Market Dynamics
MIIT's domestic semiconductor substitution mandates are restructuring procurement flows across automotive and industrial automation clusters, forcing foreign architecture suppliers to redesign encryption cores and data handling protocols for GB standards compliance.
Growth Catalysts
- Smart Manufacturing Deployment:Vision-based inference chips are embedding directly into inspection equipment along Shenzhen and Hangzhou production lines, eliminating cloud latency for real-time defect detection.
- Dual Carbon Policy Framework:MIIT efficiency benchmarks now gatekeep state procurement channels, redirecting volume commitments toward sub-15-watt ASIC designs that qualify for deployment subsidies.
- Automotive Pilot Programs:Intelligent vehicle development clusters around Shanghai and Beijing are generating dedicated demand for automotive-grade inference silicon with sub-10-millisecond latency thresholds.
Market Restraints
- Foundry Access Concentration:Captive domestic foundry partnerships constrain supply elasticity for fabless designers, creating allocation bottlenecks during volume ramp phases.
- GB Standards Compliance Costs:BIS-equivalent domestic encryption and data sovereignty requirements force architectural redesign cycles that extend time-to-revenue for healthcare and public safety endpoints.
- FPGA Prototyping Stickiness:Smart retail and industrial inspection workflows retain flexibility dependency on reprogrammable platforms, delaying ASIC conversion economics.
Strategic Opportunities
- Medical Edge Expansion:NMPA medical device classification rules extending to AI-enabled diagnostic equipment will determine silicon supplier qualification for hospital and clinic procurement channels.
- Tensor Processing Migration:Government-backed AI infrastructure programs are funding datacenter-to-edge TPU deployment, creating volume anchors for specialized inference architectures.
- Hybrid Cloud Edge Nodes:Training-inference convergence requirements in enterprise deployments are opening design wins for GPU accelerators with unified memory architectures.
Industry Challenges
- Verification Timeline Compression:SAMR certification requirements for information security are extending qualification periods just as automotive OEMs accelerate platform refresh cycles.
- Legacy System Integration Friction:Factory automation retrofits require protocol bridging between new inference silicon and existing PLC networks, complicating deployment engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Edge AI Processor Market |
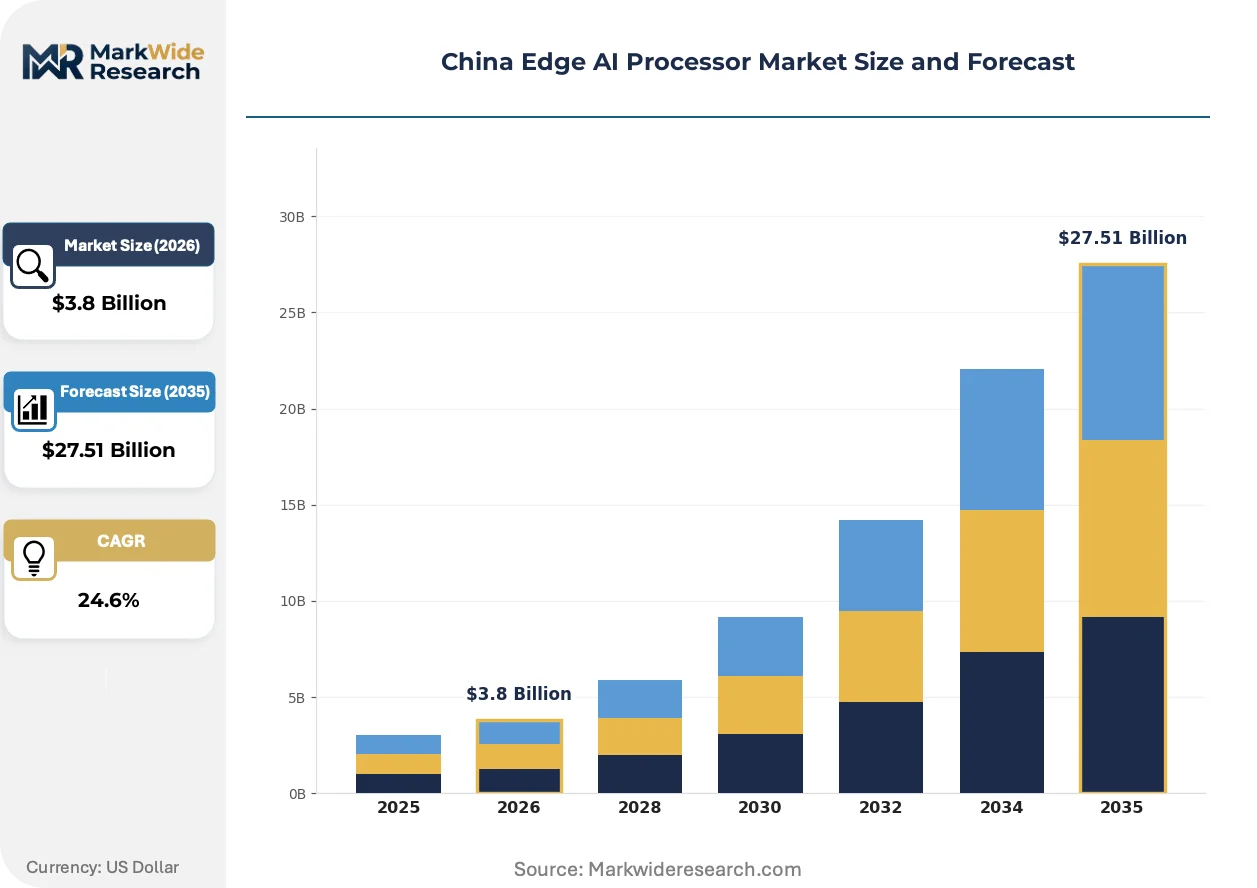
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, ASIC, CPU, GPU Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: Retail, Healthcare, Automotive, Manufacturing Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision |
| Companies Covered | Huawei HiSilicon, Cambricon Technologies, Ingenic Semiconductor, GigaDevice Semiconductor, Horizon Robotics, Intellifusion, Qualcomm Technologies, MediaTek, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Edge AI Processor Market Trends and Innovations
Architectural specialization is fragmenting the competitive map as purpose-designed automotive inference silicon overtakes general-purpose accelerators in intelligent vehicle programs, while regulatory encryption mandates force hardware-level redesigns across medical and public safety endpoints.
ASIC designs optimized for specific neural network topologies are overtaking FPGA platforms in volume manufacturing environments where mask costs amortize across million-unit automotive commitments. Tier-1 suppliers in the Yangtze River Delta are consolidating procurement around single-source inference silicon for pilot production lines. This compression is marginalizing reprogrammable alternatives in high-volume inspection and autonomous navigation subsystems.
GB standards for information security and data handling are mandating on-chip encryption modules that increase die area by 12-18% for foreign architecture suppliers seeking state procurement eligibility. Industrial automation OEMs are absorbing these costs to maintain access to smart manufacturing subsidy programs. Medical imaging equipment manufacturers face the steepest redesign cycles as NMPA extends device classification rules to edge AI diagnostic endpoints.
Automotive OEMs are consolidating silicon procurement around vertically integrated suppliers with captive foundry access, displacing multi-vendor evaluation cycles that previously characterized intelligent vehicle platform development. Direct sourcing agreements now span 36-48 month horizons with volume commitments front-loaded to secure allocation. This concentration is most visible in Beijing and Shanghai development clusters where pilot program timelines compress supplier qualification windows.
China Edge AI Processor Market Segmentation
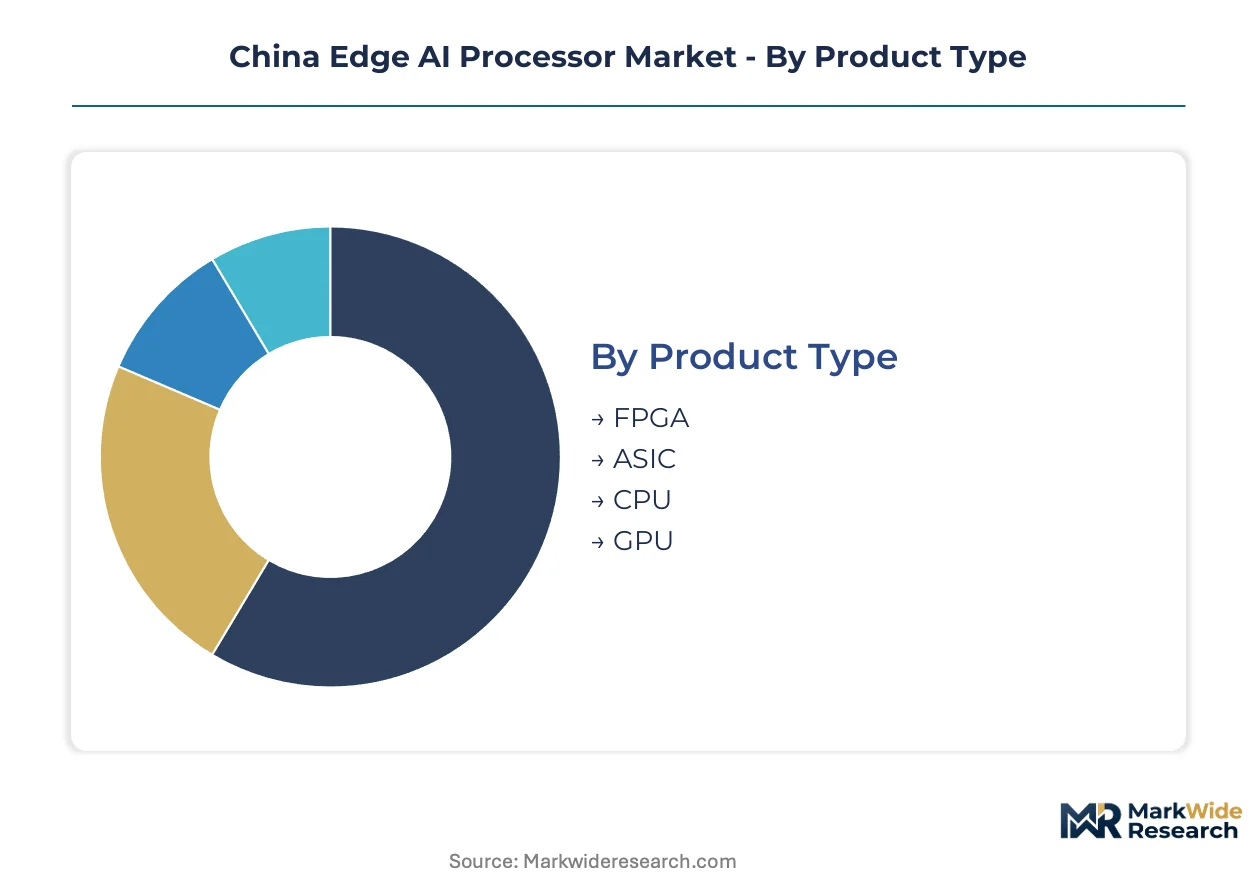
Segmentation in China's edge AI processor market reveals how architectural choices, deployment constraints, and end-use requirements fragment procurement patterns. Product type and deployment model decisions cascade through technology selection and compliance obligations, creating distinct competitive arenas with divergent margin structures.
Product Type:
ASIC designs anchor high-volume manufacturing commitments where mask costs amortize across million-unit automotive programs, while FPGA platforms retain prototyping flexibility in retail and industrial inspection workflows.
- FPGA:Reprogrammable logic arrays enable rapid iteration of neural network topologies during pilot phases. Smart retail and industrial inspection workflows in Shenzhen and Hangzhou retain flexibility dependency on these platforms, delaying ASIC conversion economics until volume commitments crystallize.
- ASIC:Purpose-built inference engines deliver sub-15-watt power envelopes with deterministic latency. Automotive OEMs around Shanghai and Beijing consolidate procurement around these designs for intelligent vehicle pilot programs, front-loading volume commitments to secure foundry allocation.
- CPU:General-purpose compute cores handle control-plane tasks and legacy protocol bridging in factory automation retrofits.
- GPU:Parallel architectures with unified memory support training-inference convergence in hybrid cloud edge nodes.
Most installed capacity flows through ASIC. Expansion is steepest in GPU.
Deployment Model:
Data sovereignty mandates and latency thresholds stratify deployment choices, with state procurement channels favoring architectures that satisfy GB standards for encryption and information security.
- On-Premises:Localized inference execution eliminates cloud dependency for real-time defect detection in smart manufacturing lines. MIIT efficiency benchmarks gatekeep access to deployment subsidies, redirecting volume toward sub-15-watt designs that qualify for state-backed programs.
- Hybrid Cloud:Unified memory architectures enable training-inference convergence across enterprise deployments. GPU accelerators compete aggressively here where workload portability between edge and cloud matters.
- Public Cloud:Shared infrastructure serves prototyping and variable-demand workloads with limited state procurement eligibility.
- Private Cloud:Dedicated resources satisfy healthcare and public safety encryption requirements under BIS-equivalent domestic standards.
On-premises captures the dominant share of state procurement. Hybrid cloud is climbing the fastest as enterprise convergence requirements mature.
End User:
Regulatory boundaries determine silicon supplier qualification, with NMPA medical device classification rules and MIIT automotive mandates creating divergent certification pathways.
- Automotive:Intelligent vehicle development clusters generate dedicated demand for automotive-grade inference silicon with sub-10-millisecond latency thresholds. Tier-1 suppliers in the Yangtze River Delta consolidate procurement around single-source designs with captive foundry access.
- Manufacturing:Vision-based inference chips embed directly into inspection equipment along Shenzhen and Hangzhou production lines. GB standards compliance for information security restructures cost-of-entry calculus for foreign architectures in these deployments.
- Healthcare:NMPA medical device classification rules extending to AI-enabled diagnostic equipment determine supplier qualification for hospital and clinic procurement.
- Retail:Smart retail workflows retain FPGA dependency for flexibility in rapidly changing consumer analytics requirements.
Manufacturing absorbs the largest silicon volume. Healthcare is gaining share fastest as NMPA regulatory clarity emerges.
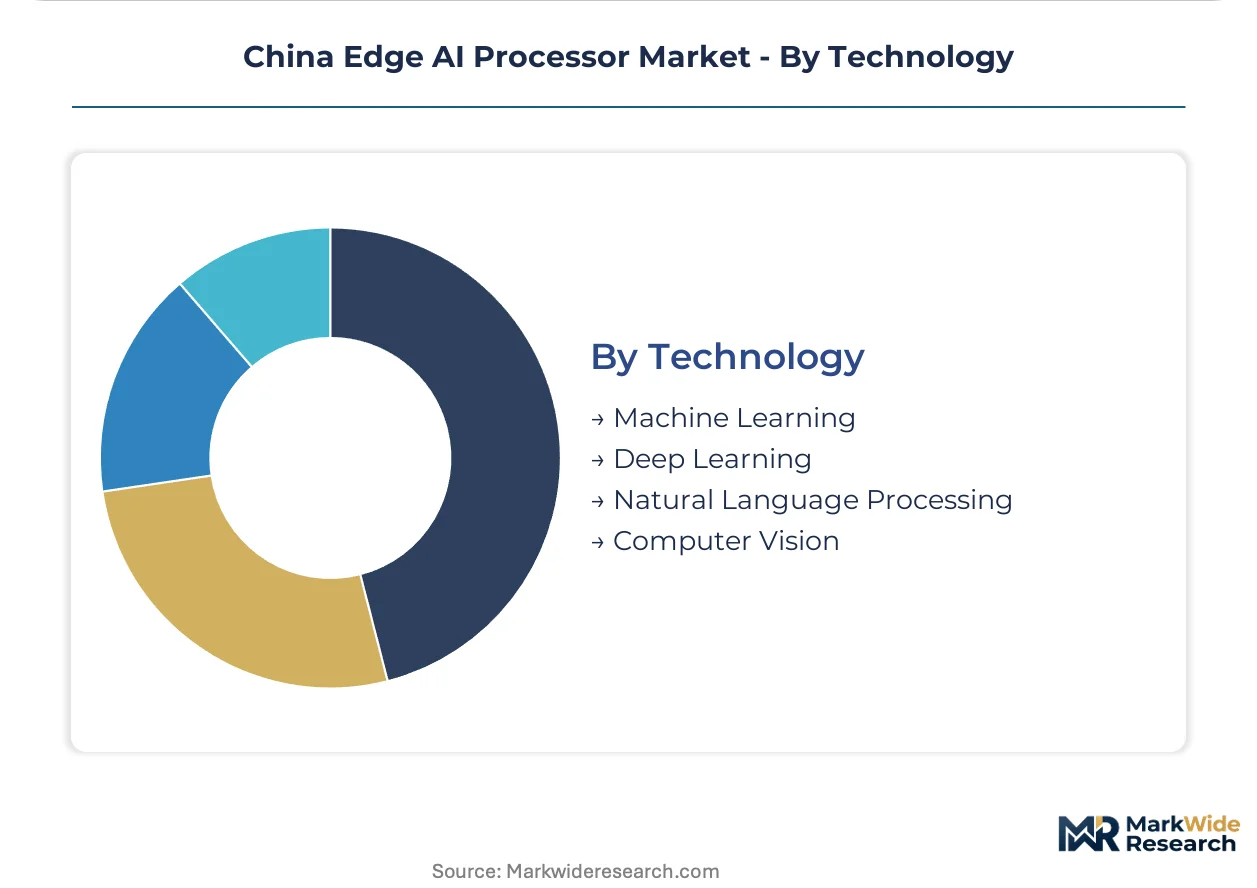
Technology:
Neural network topology specialization fragments the competitive map as purpose-designed architectures overtake general-purpose accelerators in targeted workloads.
- Computer Vision:Convolution-optimized inference engines dominate manufacturing inspection and autonomous navigation subsystems. ASIC designs command deepest margin pools where automotive OEMs justify mask costs for million-unit commitments.
- Deep Learning:Tensor processing unit migration from datacenter to edge creates volume anchors in government-backed AI infrastructure programs. Cambricon Technologies occupies this niche with specialized inference architectures.
- Machine Learning:Traditional statistical inference supports control-plane optimization in legacy factory automation systems.
- Natural Language Processing:Transformer-optimized silicon serves emerging voice-interaction endpoints in retail and healthcare settings.
Computer vision commands the largest installed base. Deep learning is expanding most quickly as TPU migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Beijing and Shanghai anchor China's edge AI processor development, with semiconductor design expertise concentrating in the Yangtze River Delta and Pearl River Delta corridors where foundry partnerships and automotive OEM clusters intersect.
Yangtze River Delta
Automotive-grade inference silicon procurement dominates demand as intelligent vehicle pilot programs accelerate around Shanghai. MIIT domestic semiconductor substitution mandates redirect volume commitments toward local suppliers with captive foundry access. Tier-1 suppliers in this cluster consolidate single-source agreements spanning 36-48 month horizons.
Pearl River Delta
Vision-based inspection equipment deployment drives ASIC volume in Shenzhen and Hangzhou smart manufacturing lines. GB standards compliance for information security restructures cost-of-entry for foreign architectures seeking state procurement eligibility. Local industrial automation OEMs absorb 12-18% die area increases for on-chip encryption modules.
Beijing-Tianjin-Hebei
Autonomous driving development clusters generate dedicated demand for sub-10-millisecond latency inference silicon. SAMR certification requirements for information security extend qualification periods as automotive OEMs accelerate platform refresh cycles. State-backed AI infrastructure programs fund datacenter-to-edge tensor processing unit migration in this corridor.
Sichuan-Chongqing
Western China manufacturing bases embed edge inference chips into medical imaging equipment as NMPA extends device classification rules to AI-enabled diagnostic endpoints. Dual carbon policy efficiency benchmarks gatekeep access to deployment subsidies for sub-15-watt designs. Local hospital procurement channels increasingly determine silicon supplier qualification.
China Edge AI Processor Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic suppliers with captive foundry partnerships. Market concentration is pronounced in automotive and industrial segments where million-unit volume commitments justify ASIC mask costs. Three archetypes dominate: captive foundry operators sustaining supply continuity, fabless specialists in automotive inference silicon, and datacenter-to-edge tensor processing migrators. Competitive moves center on 36-48 month direct sourcing agreements and architectural redesigns for GB standards compliance.
Among domestic suppliers, Huawei HiSilicon and Horizon Robotics exemplify the vertically integrated archetype with automotive-focused positioning, while Cambricon Technologies occupies the specialized inference architecture tier serving government-backed infrastructure programs. These three represent distinct strategic postures within a procurement environment restructuring around MIIT domestic substitution mandates and state procurement channel access.
| Leading Market Players |
|---|
| Huawei HiSilicon |
| Cambricon Technologies |
| Ingenic Semiconductor |
| GigaDevice Semiconductor |
| Horizon Robotics |
| Intellifusion |
| Qualcomm Technologies |
| MediaTek |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
ASIC mask cost amortization across million-unit automotive commitments simultaneously compresses per-unit economics and concentrates procurement power among vertically integrated domestic suppliers with captive foundry access. This production-method transition forces foreign architecture suppliers to absorb 12-18% die area increases for on-chip encryption modules while ceding margin to local competitors qualifying for MIIT deployment subsidies.
Pricing Analysis
Chip procurement splits between bundled long-term direct sourcing agreements and unbundled spot-market transactions for prototyping volumes. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels differentiates offerings, with GB standards compliance costs widening spreads between qualified and unqualified suppliers. Pricing pressure stems from foundry allocation bottlenecks during volume ramp phases, squeezing fabless designers most acutely. Automotive OEMs exhibit lowest price sensitivity due to 36-48 month platform lock-ins, while smart retail deployers retain flexibility-driven cost consciousness.
Supply Chain Analysis
Freight cost volatility for advanced packaging substrates compounds supply risk in a network drawing from Taiwan, South Korea, and domestic China foundry capacity. Silicon wafer supply, photoresist chemicals, and advanced packaging equipment constitute critical input dependencies. Single-source vulnerability concentrates in EUV lithography equipment access, constraining node advancement for domestic designers. Distribution runs through Tier-1 supplier consolidation in the Yangtze River Delta, with direct OEM agreements displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's edge AI processor market compounds steadily as MIIT domestic substitution mandates permanently restructure procurement channels toward local silicon suppliers. This regulatory force generates predictable volume anchors across automotive and industrial automation clusters.
For Market Incumbents: Anchor market position through 36-48 month direct sourcing agreements that lock in foundry allocation ahead of volume ramp phases. Deepen backward integration into captive packaging capabilities to insulate against substrate supply shocks. Defend against emerging fabless specialists by accelerating GB standards certification timelines for encryption module redesigns.
For New Entrants and Emerging Players: Launch via white-label partnerships with industrial automation OEMs in Shenzhen and Hangzhou to bypass entrenched automotive procurement channels. Target medical imaging equipment manufacturers awaiting NMPA regulatory clarity as the most penetrable segment. Pursue hybrid cloud edge node deployments where GPU accelerator competition remains less consolidated.
For Investors and Strategic Acquirers: Roll-up economics work for fabless automotive inference specialists because Tier-1 supplier consolidation is compressing vendor evaluation cycles and privileging scale. Five-to-ten year viability hinges on foundry partnership durability rather than architectural differentiation alone. Monitor SAMR certification timeline extensions as the critical inflection signal for supplier qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Certification Investment | On-chip encryption module redesigns unlock state procurement channel access under MIIT mandates. |
| Captive Foundry Partnership Expansion | Domestic foundry allocation agreements secure supply continuity amid export control pressures. |
| Automotive Direct Sourcing Agreement | Long-term volume commitments with Shanghai and Beijing OEM clusters amortize ASIC mask costs. |
| Medical Edge Regulatory Pre-Positioning | NMPA classification pathway investment qualifies silicon for hospital procurement channels. |
| Hybrid Cloud Edge Node Development | Unified memory architectures capture enterprise training-inference convergence requirements. |
Research Methodology
Direct dialogue with semiconductor design executives, automotive Tier-1 procurement leads, foundry operations managers, and industrial automation OEM engineering directors grounded qualitative findings. Secondary validation drew from MIIT policy filings, SAMR certification databases, NMPA medical device registration records, and customs trade data for semiconductor imports. Bottom-up and top-down triangulation cross-checked volume estimates against foundry capacity disclosures and OEM platform deployment timelines.
Bottom-up modeling segmented demand across product type, deployment model, end user, and technology dimensions, with additional granularity for regional regulatory cluster effects. Top-down constraints incorporated MIIT efficiency benchmark adoption curves and dual carbon policy subsidy allocation patterns. CAGRs derived from regression analysis of historical procurement volume against policy implementation phases, with cross-validation against automotive pilot program expansion rates and smart manufacturing line deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or foundry capacity allocation shocks. Forecasts reflect documented assumptions regarding NMPA regulatory timeline clarity and MIIT subsidy program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
Server Microprocessor Market