
 Pressure Calibration Equipment Market | 2026-2036
Pressure Calibration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Calibration Equipment Market Analytics
Equipment-as-a-service leasing models are reshaping competitive entry barriers for mid-tier calibration providers. Druck leverages its captive sensor manufacturing to control component quality and shorten lead times. Additel Corporation specializes in portable digital pressure calibrators that serve field technicians across upstream oil and gas operations. Fluke Corporation anchors its position through channel density and aftermarket service contracts that extend customer lifetime value.
Pressure calibration equipment comprises precision instruments that verify and adjust pressure measurement devices against traceable standards, typically achieving accuracies from 0.025% to 0.1% of full scale using deadweight testers, digital pressure controllers, or piston gauges to ensure compliance in safety-critical process environments. Calibration standards command premium positioning due to the capital intensity of primary reference laboratories and the regulatory burden of maintaining international traceability chains. Pneumatic technology leads in cleanroom and aerospace applications where oil-free operation prevents contamination, while electronic calibration systems represent the fastest-expanding segment as Industry 4.0 architectures demand automated data logging and cloud-connected verification workflows.
The National Institute of Standards and Technology (NIST) mandates traceability pathways that shape procurement specifications for defense and energy contractors, while the International Organization for Standardization (ISO) 17025 framework governs laboratory accreditation and cross-border acceptance of calibration certificates. The Environmental Protection Agency (EPA) enforces leak detection protocols in petroleum refining that drive recurring calibration spend on pressure-based emissions monitoring systems. Stakeholders must monitor how artificial intelligence-enabled predictive maintenance platforms alter calibration interval economics and service revenue models.
Market Dynamics
Digital calibration workflows are compressing service intervals and forcing incumbents to rebuild software competencies alongside hardware manufacturing. The displacement of mechanical-only systems creates asymmetric pressure on legacy equipment providers.
Growth Catalysts
- NIST Traceability Mandates:Defense and energy contractors in the United States must maintain documented calibration chains. This requirement locks in recurring equipment refresh cycles.
- Upstream Oil and Gas Protocol Tightening:Measurement traceability standards are hardening across exploration and production operations. Operators now specify automated calibration verification for subsea pressure monitoring.
- Industry 4.0 Integration:Cloud-connected verification workflows are pulling electronic calibration systems into smart manufacturing architectures. Data logging automation reduces manual transcription errors.
Market Restraints
- Primary Reference Laboratory Capital Intensity:Establishing deadweight tester facilities requires substantial fixed investment. This barrier protects incumbents but blocks mid-tier entrants.
- Component Supply Concentration:High-precision pressure sensors concentrate among specialized semiconductor foundries. Lead time volatility propagates through calibration equipment manufacturing.
- ISO 17025 Accreditation Burden:Cross-border certificate acceptance demands continuous laboratory compliance investment. Smaller service providers struggle with recurring audit costs.
Strategic Opportunities
- Equipment-as-a-Service Leasing:Mid-tier calibration providers are adopting subscription models to lower customer capital barriers. This channel innovation expands addressable spend among smaller maintenance shops.
- Predictive Maintenance Platform Convergence:Artificial intelligence-enabled systems are creating new calibration interval optimization services. Vendors can capture recurring software revenue alongside hardware sales.
- EPA Leak Detection Enforcement:Petroleum refining emissions monitoring mandates are expanding pressure-based sensor deployment. This regulatory tailwind sustains replacement demand in downstream operations.
Industry Challenges
- Metrology Talent Scarcity:Skilled technicians capable of maintaining primary standards are aging out of the workforce. Training pipelines have not kept pace with laboratory expansion.
- Legacy System Integration Friction:Digital calibration platforms must interface with decades-old mechanical infrastructure. Protocol translation consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Calibration Equipment Market |
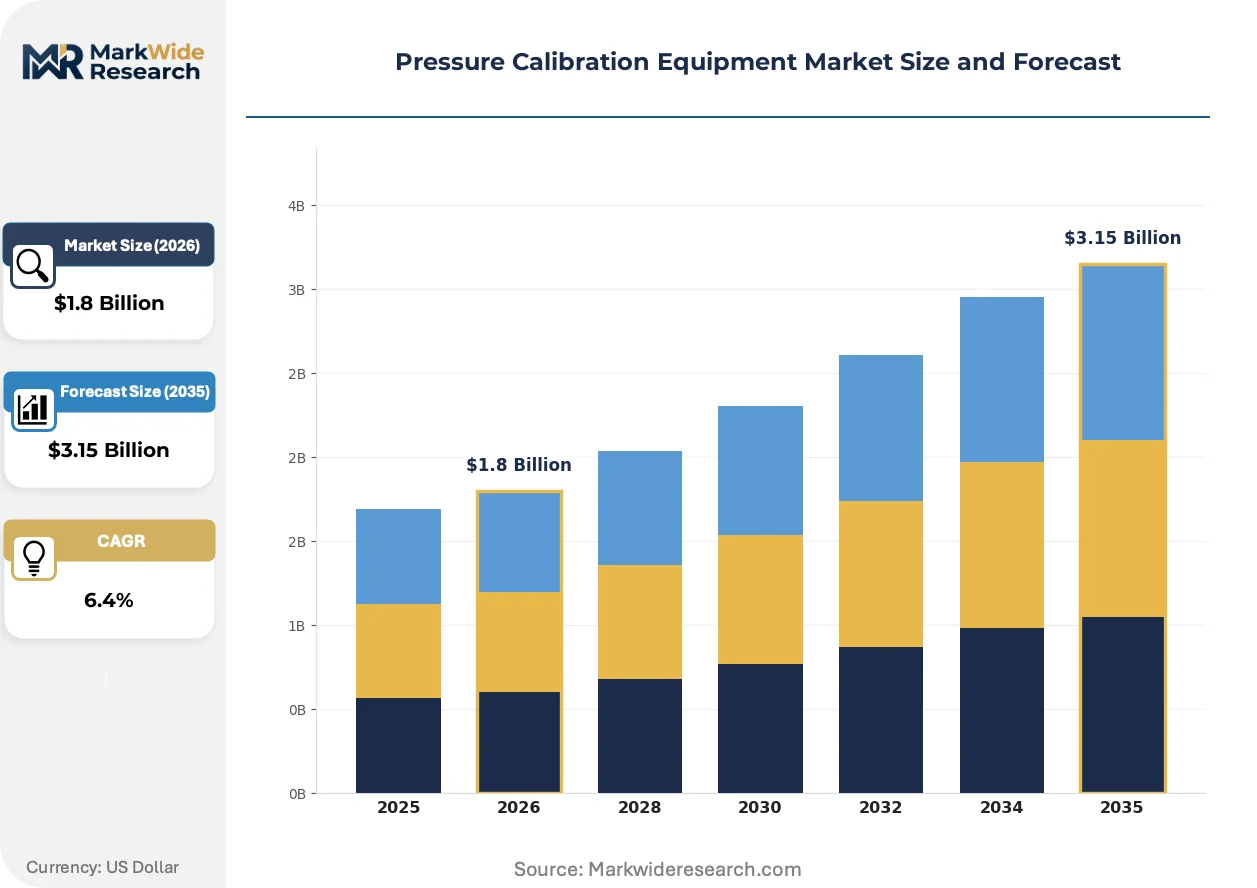
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Gauges, Digital Manometers, Test Pumps, Calibration Standards Technology: Hydraulic, Pneumatic, Electronic, Mechanical End User: Aerospace, Automotive, Manufacturing, Oil & Gas Application: Research & Development, Quality Assurance, Field Calibration, Industrial Testing |
| Companies Covered | Druck, Additel Corporation, Fluke Corporation, Omega Engineering, Ashcroft, AMETEK, Beamex, Yokogawa Electric Corporation, WIKA Alexander Wiegand SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Calibration Equipment Market Evolving Landscape
Software-defined calibration architectures are rewriting competitive boundaries between instrument manufacturers and industrial software vendors. The convergence is compressing hardware differentiation cycles.
Automated pressure controller software is virtualizing the deadweight tester workflow for field environments. Oil and gas operators are adopting these systems for offshore platform verification. The technology is virtualizing what previously required laboratory-grade physical standards, collapsing the distinction between field and reference-grade calibration.
EPA leak detection protocols are mandating continuous pressure-based emissions monitoring in petroleum refining. This enforcement is expanding sensor deployment and shortening calibration intervals. Downstream operators are responding by integrating automated verification into distributed control systems.
Service unbundling is separating hardware ownership from calibration certification. Mid-sized maintenance shops now rent reference-grade equipment rather than purchasing. This pattern is most visible in United States industrial corridors where capital efficiency pressures dominate procurement decisions.
Pressure Calibration Equipment Market Segmentation
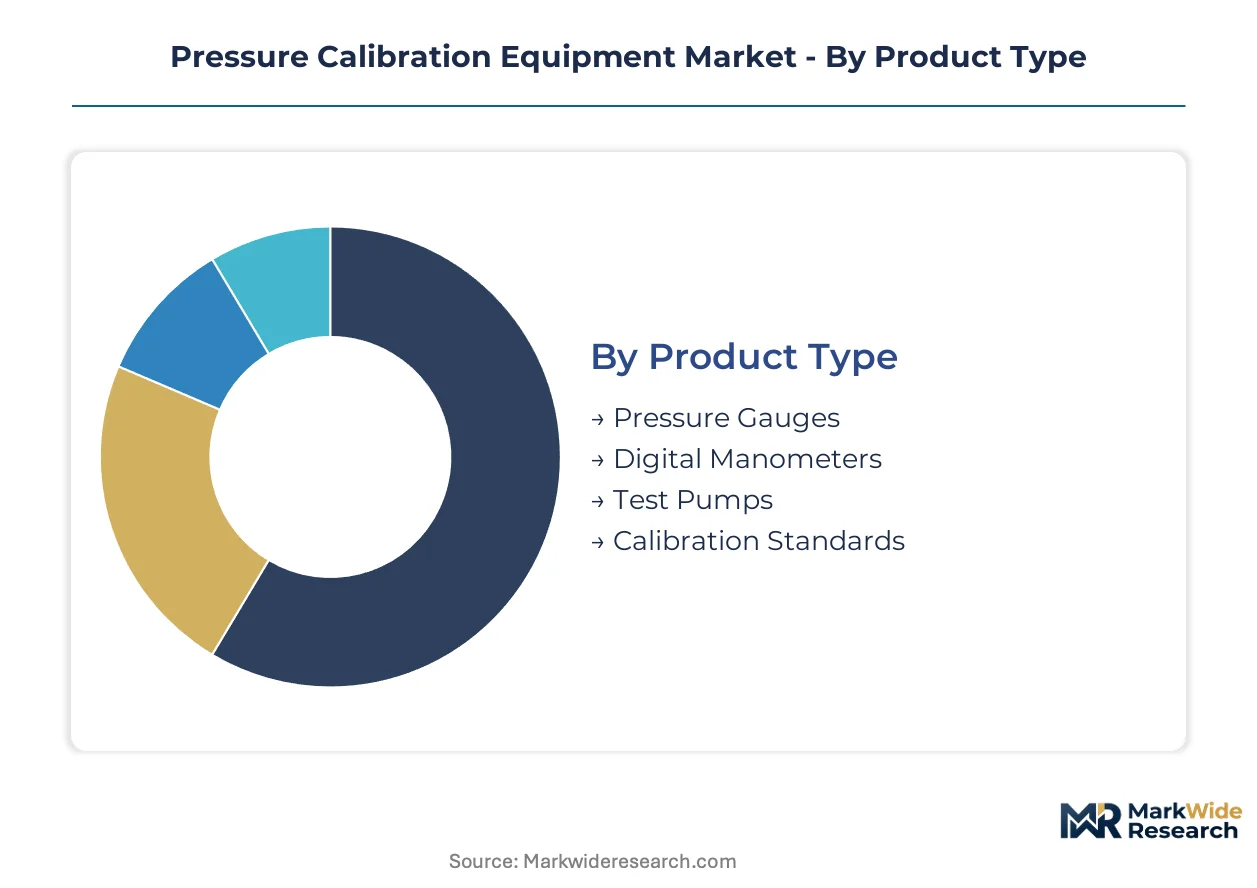
Segmentation reveals how pressure calibration equipment serves divergent precision requirements across laboratory, field, and production environments. Equipment specification varies sharply between aerospace certification workflows and upstream oil and gas maintenance protocols.
Product Type:
The use-case spectrum spans from portable field verification tools to primary laboratory reference standards with traceability chains to national metrology institutes.
- Calibration Standards:Primary reference instruments including deadweight testers and piston gauges achieve accuracies to 0.025% of full scale. Demand concentrates in United States defense contractor facilities where NIST traceability mandates lock in recurring refresh cycles for primary laboratories.
- Digital Manometers:Handheld electronic pressure indicators integrate automated data logging for field technicians. Oil and gas operators across Texas and North Dakota specify these for subsea platform verification where cloud-connected workflows reduce manual transcription errors.
- Pressure Gauges:Dial-type instruments serve general industrial monitoring with broader tolerance bands.
- Test Pumps:Portable pressure generation devices enable field calibration without external pressure sources.
Established volume favors calibration standards; emerging adoption favors digital manometers.
Technology:
Cost tier stratification separates capital-intensive primary reference systems from deployable field electronics.
- Electronic:Microprocessor-controlled calibration systems automate pressure control, measurement, and documentation through integrated software architectures. Manufacturing facilities in Germany and Japan deploy these for Industry 4.0 integration where automated verification workflows connect to enterprise quality management systems.
- Pneumatic:Oil-free pressure generation serves cleanroom and aerospace applications where contamination risks disqualify hydraulic alternatives. Semiconductor fabrication facilities in South Korea specify pneumatic systems for wafer processing environments.
- Hydraulic:High-pressure liquid-based systems dominate oil and gas wellhead testing applications.
- Mechanical:Spring-loaded and deadweight mechanical systems persist in legacy installations requiring minimal maintenance.
Electronic systems are gaining share fastest; pneumatic technology commands premium positioning in contamination-sensitive segments.
End User:
Application maturity varies across sectors with divergent regulatory intensity and safety-critical measurement requirements.
- Oil & Gas:Exploration, production, and refining operations deploy pressure calibration across wellhead monitoring, pipeline integrity testing, and emissions detection systems. EPA leak detection protocols in United States petroleum refining mandate continuous pressure-based monitoring, shortening calibration intervals and expanding replacement demand.
- Aerospace:Aircraft manufacturing and maintenance operations require traceable calibration for flight-critical pressure systems. FAA certification standards in United States commercial aviation drive laboratory-grade equipment procurement with documented uncertainty budgets.
- Automotive:Powertrain testing and fuel system validation employ mid-tier electronic calibrators.
- Manufacturing:General industrial process control represents the broadest volume base with varied precision requirements.
Oil and gas delivers the steepest expansion trajectory; aerospace maintains the most stringent specification barriers.
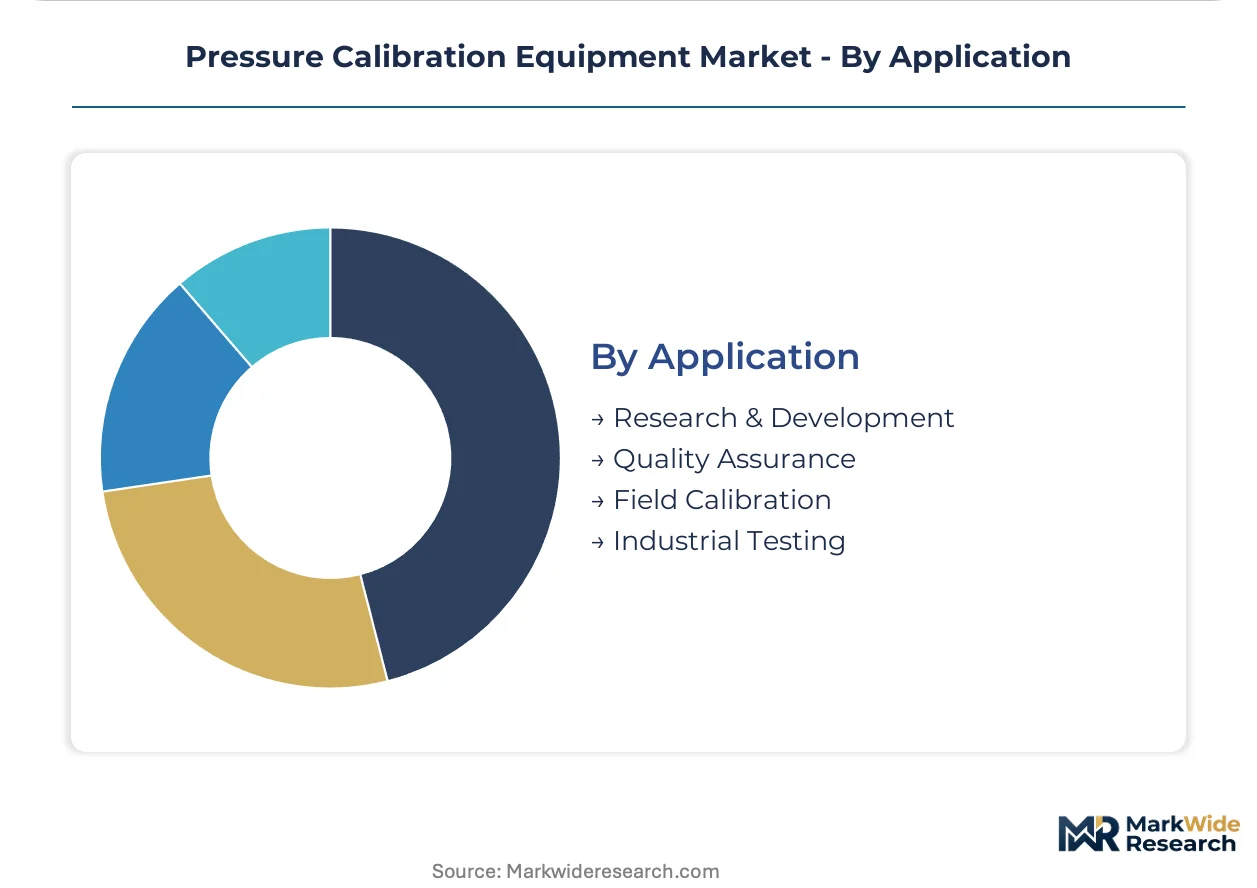
Application:
Customer type differentiation separates capital-intensive laboratory accreditation from operational field maintenance budgets.
- Field Calibration:On-site verification services eliminate equipment shipping costs and production downtime. United States industrial corridors from Houston to the Permian Basin see equipment-as-a-service leasing models proliferate among mid-tier maintenance providers seeking capital efficiency.
- Quality Assurance:Production-line verification systems integrate calibration into manufacturing execution systems. Automotive suppliers in Germany deploy automated verification stations where ISO 17025 accreditation supports cross-border certificate acceptance.
- Research & Development:Laboratory characterization of novel pressure sensors and materials requires highest-precision reference standards.
- Industrial Testing:Acceptance testing and periodic verification support asset integrity programs across process industries.
Field calibration is climbing the fastest; quality assurance anchors the revenue base through recurring certification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure calibration equipment flows disproportionately toward economies with stringent measurement traceability mandates. Import dependency concentrates in regions lacking domestic primary reference laboratory infrastructure. Export leadership clusters among manufacturers with captive sensor fabrication and NIST-traceable certification chains.
United States
Defense contractor procurement standards and EPA leak detection enforcement sustain replacement demand across petroleum refining corridors. NIST mandates documented calibration chains for energy and aerospace contractors. Houston industrial clusters deploy automated verification systems for subsea platform monitoring.
Germany
Automotive powertrain testing and Industry 4.0 manufacturing execution systems drive electronic calibration adoption. ISO 17025 accreditation requirements govern cross-border certificate acceptance for laboratory equipment. Stuttgart and Munich industrial zones integrate cloud-connected verification into quality management architectures.
China
Semiconductor fabrication expansion and petrochemical capacity growth pressure domestic calibration infrastructure. SAMR standardization initiatives align national measurement traceability with international frameworks. Yangtze River Delta fabrication facilities specify pneumatic systems for contamination-sensitive wafer processing.
Japan
Precision manufacturing and automotive supplier networks sustain demand for high-accuracy reference standards. METI industrial policy supports metrology infrastructure modernization. Nagoya industrial corridors deploy automated verification stations for production-line quality assurance.
South Korea
Memory chip fabrication and display panel manufacturing require oil-free pneumatic calibration for cleanroom environments. MFDS and national standards bodies enforce measurement traceability in medical device production. Gyeonggi-do semiconductor clusters specify electronic systems with automated data logging capabilities.
Pressure Calibration Equipment Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Primary reference laboratory equipment demands capital-intensive deadweight tester fabrication and international accreditation maintenance. Mid-tier field calibration providers compete through equipment-as-a-service leasing models that reduce customer capital barriers. Portable digital specialists target upstream oil and gas maintenance workflows with deployable verification tools. Dominant competitive moves include backward integration into sensor manufacturing and strategic expansion of aftermarket service contract portfolios.
Among sensor-integrated manufacturers, Druck exemplifies the captive component production archetype. Additel Corporation and Fluke Corporation occupy positions within the portable and channel-dense service tiers respectively. These three anchors illustrate how quality control over critical components, field-deployable form factors, and dense service networks represent alternative vectors for competitive differentiation.
| Leading Market Players |
|---|
| Druck |
| Additel Corporation |
| Fluke Corporation |
| Omega Engineering |
| Ashcroft |
| AMETEK |
| Beamex |
| Yokogawa Electric Corporation |
| WIKA Alexander Wiegand SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Houston maritime freight corridors transmit semiconductor sensor cost volatility into calibration equipment pricing tiers, concentrating margin pressure on mid-tier providers while rewarding NIST-traceable premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and ISO 17025 laboratory accreditation drive price differentiation between primary reference systems and field-deployable units. Pricing pressure stems from equipment-as-a-service leasing models that compress upfront hardware margins. Small maintenance shops exhibit highest price sensitivity; defense contractors demonstrate lowest sensitivity due to mandate-locked procurement.
Supply Chain Analysis
Specialized semiconductor foundries in Taiwan, Japan, and the United States hold concentrated capacity for high-precision pressure sensors. Manufacturing draws from silicon wafers, MEMS fabrication equipment, and hermetic packaging materials. Single-source vulnerability around MEMS sensor supply creates exposure to foundry allocation decisions. Distribution runs through authorized metrology distributors and direct OEM service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure calibration equipment functions as a service-attach business where automated verification software and cloud-connected recertification subscriptions expand faster than hardware replacement cycles.
For Market Incumbents: Pre-empt software-defined calibration entrants by deepening backward integration into sensor fabrication and securing exclusive NIST-traceable certification chains. Lock in defense contractor procurement through multi-year service contracts that bundle hardware refresh with predictive maintenance platforms. For New Entrants and Emerging Players: Mid-tier field calibration providers in United States industrial corridors represent the most penetrable entry point, particularly among Permian Basin maintenance shops seeking capital-efficient leasing alternatives. Target equipment-as-a-service models with ISO 17025 certification support to bypass primary laboratory capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized metrology divisions holding dormant NIST accreditation. Monitor EPA enforcement intensity in petroleum refining as the inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Druck's captive production shortens lead times and insulates margin from foundry allocation volatility. |
| Equipment-as-a-Service Leasing Launch | Additel's subscription models expand addressable spend among capital-constrained field maintenance providers. |
| Cloud-Connected Verification Platform | Fluke's software architecture captures recurring revenue through automated calibration interval optimization. |
| NIST-Traceable Certification Investment | Primary laboratory accreditation locks in defense contractor procurement with mandate-protected refresh cycles. |
| Predictive Maintenance Convergence | AI-enabled platforms reshape service revenue models by optimizing calibration intervals for oil and gas operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, NIST laboratory accreditation databases, EPA enforcement records, and customs trade data. Interviews with calibration laboratory directors, OEM procurement managers, aftermarket service heads, and metrology equipment distributors informed demand-side validation. Bottom-up equipment shipment analysis triangulates against top-down end-use industry spend estimates.
Forecast inputs span product type, technology architecture, end-use sector, application workflow, and regional regulatory intensity across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macro industrial production indices. Oil and gas capital expenditure patterns and EPA enforcement timelines serve as industry-specific demand drivers.
Practitioners should monitor NIST mandate expansion scope, EPA leak detection protocol tightening, and semiconductor foundry capacity allocation for early signals of forecast revision. Quarterly review of defense contractor procurement awards and ISO 17025 laboratory accreditation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
United States Borescope Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Marine Electronics Tester Market