
 Shock Testing System Market | 2026-2036
Shock Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Testing System Market Outlook
Aftermarket service revenue for calibration, fixture refurbishment, and extended warranty programs is fragmenting across the installed base of legacy shakers. Team Corporation leverages its North American service network to capture recurring contracts from aerospace primes. MB Dynamics, Inc. sustains differentiation through proprietary armature designs that reduce downtime in high-cycle automotive test cells. Dongling Technologies anchors its competitive position with cost-optimized pneumatic shaker lines that dominate mid-tier electronics factories in East Asia.
A shock testing system is electromechanical or hydraulic apparatus that subjects specimens to controlled transient acceleration pulses, typically spanning 5 g to 10,000 g with pulse durations from 0.1 ms to 30 ms, to validate structural integrity and functional survival against mechanical shock. Its primary industrial purpose is qualification testing for products that must survive transportation, deployment, or operational impact events without degradation. Electro-dynamic shakers now carry the bulk of margin pools due to their versatility across sinusoidal, random, and shock profiles in a single platform. Demand for drop test equipment is accelerating fastest among EV battery manufacturers who must replicate multi-axis crash pulses for UN 38.3 and ECE R100 certification.
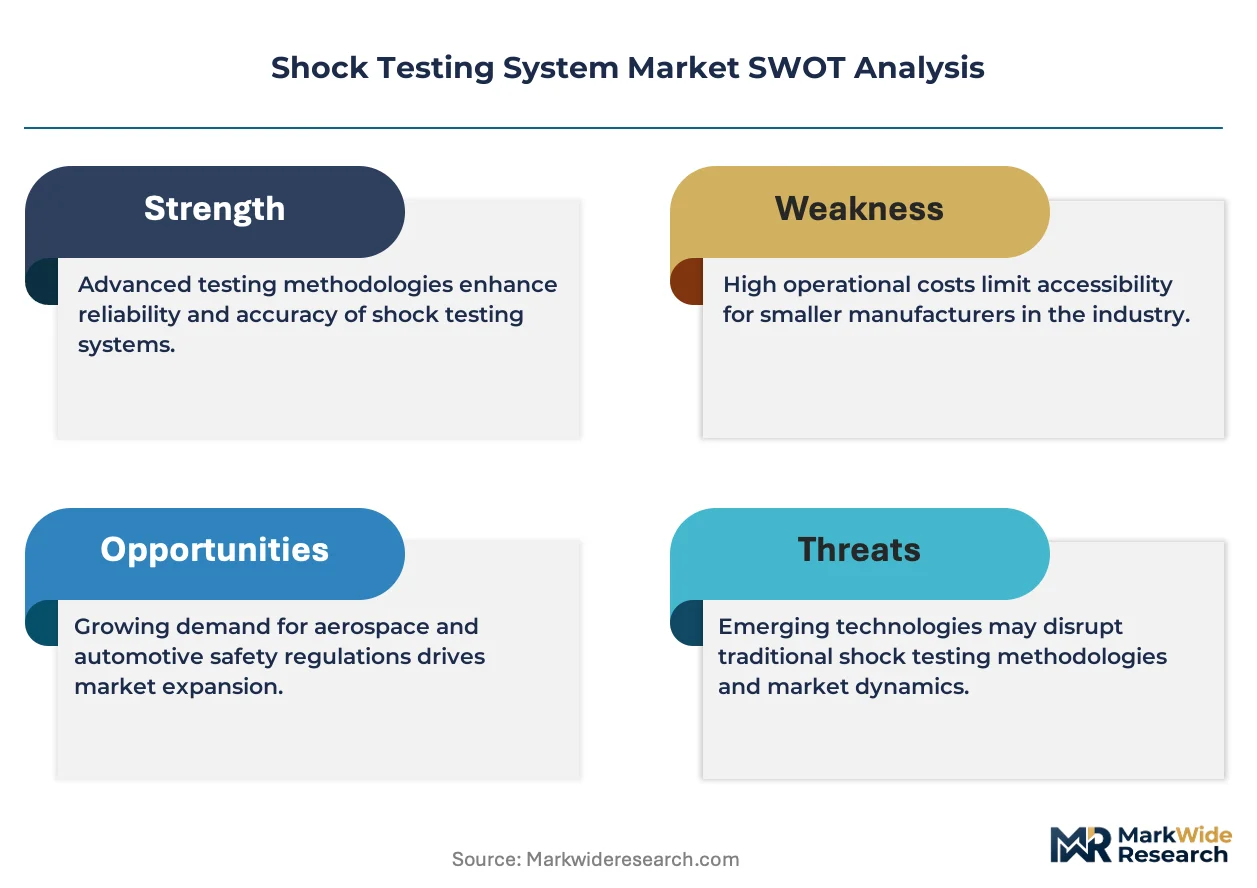
FAA airworthiness directives and EASA CS-25 certification requirements mandate shock qualification for all new aircraft systems, creating structural demand for high-force hydraulic shakers in Toulouse, Hamburg, and Wichita test facilities. MIL-STD-810H testing protocols enforced by US DoD procurement offices require defense suppliers to maintain traceable shock test records, which limits market access to vendors with accredited laboratory partnerships. Stakeholders must monitor how IEC 60068-2-27 revision timelines and emerging EU battery passport regulations reshape test specification breadth and capital expenditure cycles across their customer portfolios.
Market Dynamics
Electro-dynamic shaker platforms are consolidating test workflows across aerospace and automotive validation centers, compressing capital deployment cycles while expanding specification breadth for multi-axis pulse replication.
Growth Catalysts
- MIL-STD-810H revision cycles:US DoD procurement offices enforce traceable shock test records, mandating accredited laboratory partnerships that lock in demand for high-performance hydraulic shaker systems.
- EV battery certification:UN 38.3 and ECE R100 protocols require multi-axis crash pulse replication, accelerating capital allocation toward drop test equipment in German and Chinese validation centers.
- Satellite payload qualification:Aerospace manufacturers in Toulouse, Hamburg, and Wichita expand test protocols for avionics modules, sustaining structural demand for high-force shakers.
Market Restraints
- Armature replacement costs:High-cycle automotive test cells consume proprietary armature components every 18-24 months, creating recurring opex burdens that compress margin pools for mid-tier buyers.
- Calibration infrastructure concentration:Accredited metrology services cluster in Germany and the US, forcing East Asian electronics factories to absorb logistics costs or defer certification timelines.
- Pneumatic shaker performance ceilings:Cost-optimized pneumatic lines dominate mid-tier electronics but fail to replicate high-g pulse profiles above 2,000 g, limiting addressable market expansion.
Strategic Opportunities
- EU battery passport regulations:Emerging traceability mandates will expand test specification breadth for cell-to-pack validation, creating incremental demand for integrated shock-thermal-vibration platforms.
- Aftermarket service unbundling:Legacy shaker installed bases in North America generate fragmented demand for calibration, fixture refurbishment, and extended warranty programs outside OEM service networks.
- East Asian mid-tier electronics:Cost-optimized pneumatic shaker lines retain pricing power in factory-level quality labs underserved by electromechanical platform vendors.
Industry Challenges
- Multi-axis control system integration:Automotive test engineers face complexity combining six-degree-of-freedom shaker control with real-time crash pulse synthesis, extending commissioning timelines.
- IEC 60068-2-27 accreditation lag:Test houses pursuing revised pulse shape tolerances encounter 6-12 month laboratory audit queues, delaying contract commencement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Testing System Market |
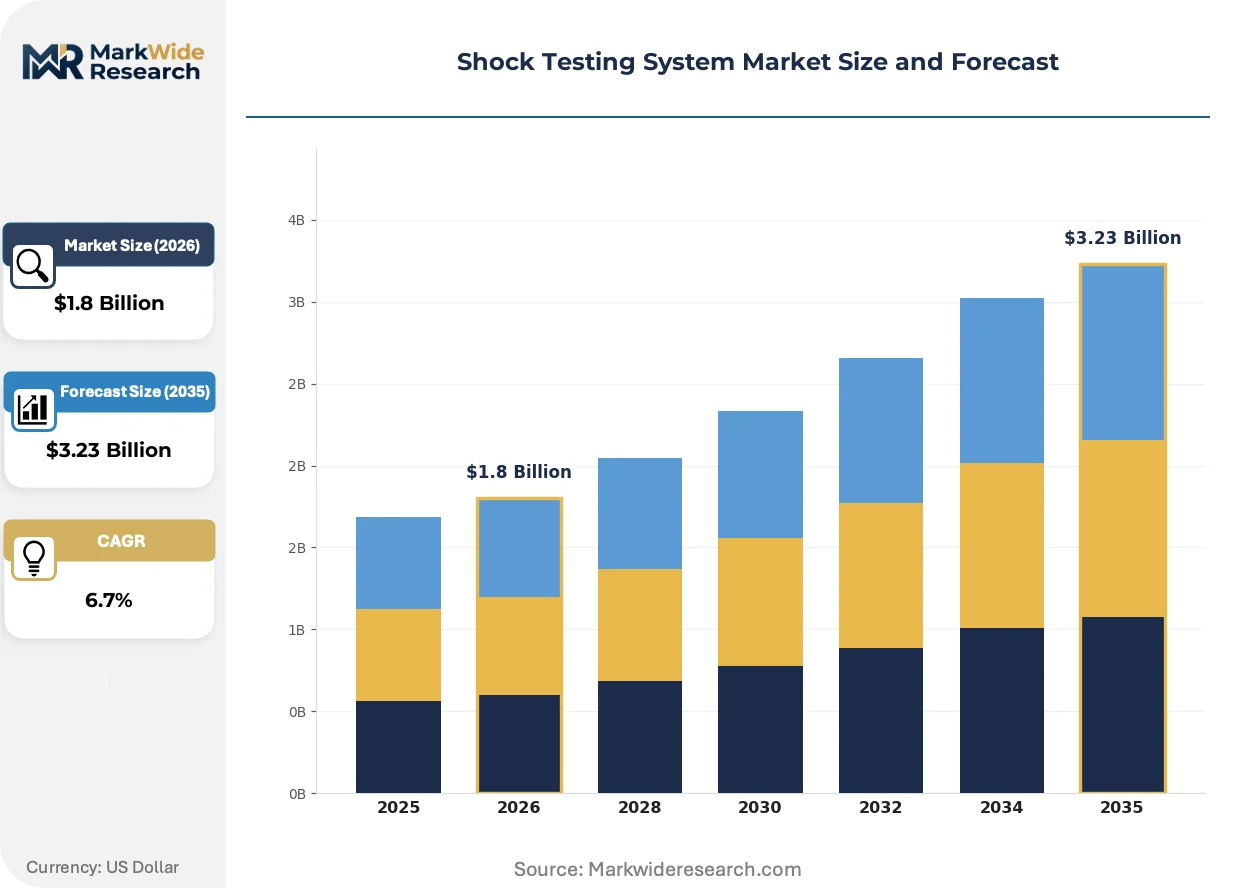
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Dynamic Shakers, Pneumatic Shakers, Hydraulic Shakers, Drop Test Equipment Application: Aerospace, Automotive, Electronics, Defense End User: Manufacturers, Research Institutions, Government Agencies, Quality Assurance Installation: On-site, In-lab, Mobile, Custom Environments |
| Companies Covered | Team Corporation, MB Dynamics, Inc., Brüel & Kjær, Dongling Technologies, Unholtz-Dickie Corporation, Lansmont Corporation, Data Physics Corporation, Labtone, Thermotron Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Testing System Market Strategic Shifts
Digital waveform synthesis and real-time feedback control are compressing test cycle durations while expanding the reproducibility of complex mechanical shock profiles across aerospace and automotive applications.
Model-based shaker control architectures that embed finite-element simulation data directly into drive signal generation are rendering obsolete legacy iterative tuning methods that required 10-15 physical test iterations. Tier-1 automotive suppliers in Stuttgart and Detroit adopt these platforms within 18-month capital cycles. The technology compresses qualification timelines from months to weeks for EV battery pack certification.
EASA CS-25 airworthiness directives and FAA parallel regulations now mandate shock qualification for all new aircraft systems including line-replaceable units and avionics racks. European aerospace primes in Toulouse and Hamburg reconfigure test floor layouts to accommodate higher-force hydraulic shakers. The regulatory pressure sustains structural demand independent of commercial aircraft production rates.
Buyer concentration among centralized validation centers is consolidating procurement authority away from distributed plant-level quality labs. Automotive OEMs in Germany now mandate corporate-level test protocol approval before regional factories issue purchase orders. This pattern concentrates vendor relationships with shaker platform manufacturers holding accredited laboratory partnerships.
Shock Testing System Market Segmentation
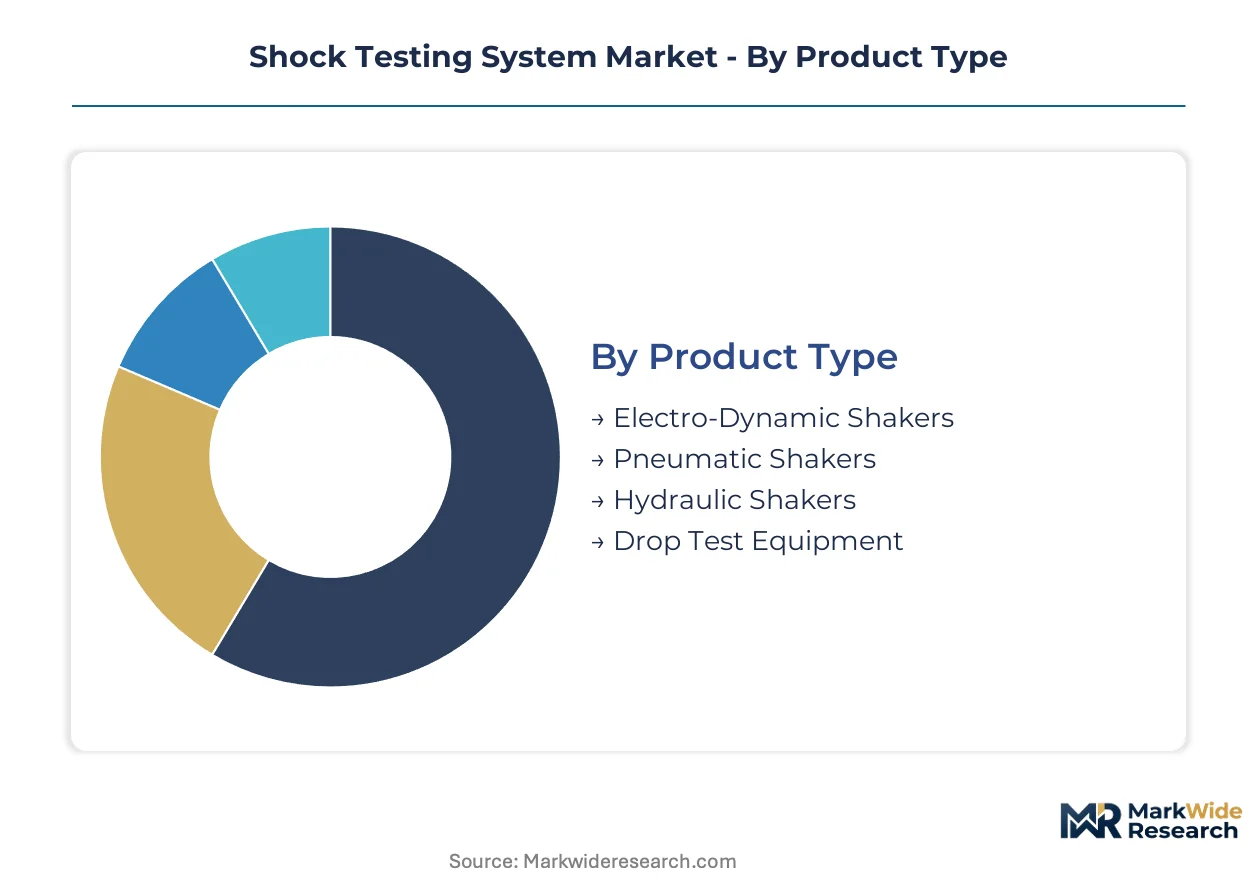
Segmentation in the shock testing system market reveals how test protocol complexity, capital intensity, and regulatory scope fragment procurement patterns across equipment types and end-use environments. Understanding these divisions exposes where margin pools concentrate versus where price competition dominates.
Product Type:
Equipment selection spans a use-case spectrum from precision aerospace qualification to high-volume factory-floor screening, with each platform carrying distinct force ranges, pulse fidelity, and lifecycle economics.
- Electro-Dynamic Shakers:These platforms generate controlled vibration and shock through electromagnetic force, delivering versatility across sinusoidal, random, and transient profiles within a single test cell. Aerospace validation centers in Toulouse and Hamburg concentrate procurement here for satellite payload qualification under EASA CS-25 mandates, absorbing premium pricing for multi-axis control capabilities.
- Hydraulic Shakers:High-force hydraulic actuators produce extreme acceleration pulses exceeding 10,000 g for structural qualification of large airframe components. Defense contractors in Wichita maintain these systems for MIL-STD-810H traceability requirements, locking in demand through accredited laboratory partnerships that limit vendor switching.
- Pneumatic Shakers:Cost-optimized air-driven systems dominate mid-tier electronics screening in East Asian factory labs where pulse requirements stay below 2,000 g.
- Drop Test Equipment:Free-fall and guided-impact rigs replicate multi-axis crash pulses for EV battery certification under UN 38.3 and ECE R100 protocols.
Established volume favors electro-dynamic shakers; emerging adoption favors drop test equipment.
Application:
Capital deployment intensity varies sharply by sector, with regulatory stringency and product liability exposure determining acceptable test equipment price points.
- Aerospace:FAA airworthiness directives and EASA certification requirements mandate shock qualification for all new aircraft systems including line-replaceable units. Test facilities in Hamburg and Wichita sustain structural demand independent of commercial aircraft production rates.
- Automotive:German OEMs operate centralized validation centers for EV battery pack certification, compressing procurement authority away from distributed plant-level quality labs. Stuttgart-based suppliers adopt model-based control architectures within 18-month capital cycles.
- Electronics:Factory-level quality labs in East Asia favor cost-optimized pneumatic screening for consumer device durability validation.
- Defense:US DoD procurement offices enforce traceable shock test records that restrict market access to vendors with accredited laboratory partnerships.
Defense and aerospace anchor revenue stability; automotive applications are expanding most quickly.
End User:
Procurement authority concentrates differently across organizational types, with centralized validation mandates reshaping vendor relationship structures.
- Manufacturers:Automotive OEMs in Germany now require corporate-level test protocol approval before regional factories issue purchase orders, consolidating vendor relationships with platform manufacturers holding accredited laboratory partnerships.
- Research Institutions:University and national laboratory facilities pursue IEC 60068-2-27 accreditation for contract testing services, encountering 6-12 month laboratory audit queues that delay capital deployment.
- Government Agencies:Defense procurement offices specify MIL-STD-810H compliance as a contract prerequisite, creating captive demand for high-performance hydraulic systems.
- Quality Assurance:Third-party test houses compete on accreditation breadth and turnaround speed for electronics and automotive supplier contracts.
Manufacturers command the largest capital budgets; quality assurance providers are gaining share fastest.
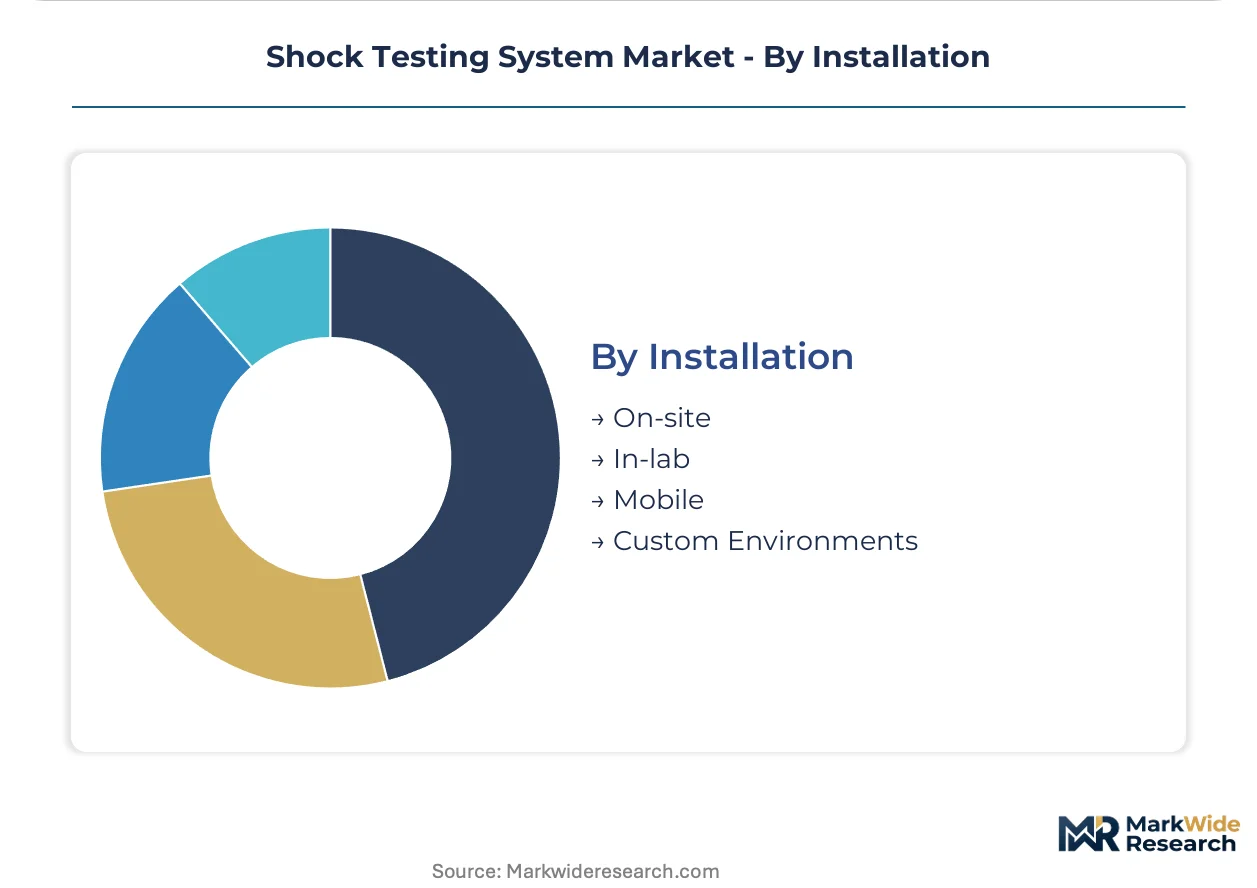
Installation:
Facility configuration options reflect trade-offs between test fidelity, operational flexibility, and infrastructure investment requirements.
- On-site:Permanent installations at manufacturing campuses support high-volume production screening with dedicated fixture sets and rapid turnaround requirements.
- In-lab:Centralized validation centers in Germany and the US concentrate accredited metrology services, forcing East Asian electronics factories to absorb logistics costs or defer certification timelines.
- Mobile:Transportable shaker platforms serve field validation requirements for defense equipment and infrastructure components where laboratory access is impractical.
- Custom Environments:Integrated shock-thermal-vibration platforms address emerging EU battery passport regulations that expand test specification breadth for cell-to-pack validation.
In-lab installations dominate revenue concentration; custom environments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German automotive OEMs absorb premium pricing for accredited validation centers, while East Asian electronics factories prioritize cost-optimized pneumatic screening. Defense procurement offices in the United States enforce MIL-STD-810H compliance regardless of cost.
United States
Defense contractors sustain demand for high-force hydraulic shakers under MIL-STD-810H traceability mandates. FAA airworthiness directives create structural pull from Wichita test facilities for satellite payload qualification. Aerospace primes lock in vendor relationships through accredited laboratory partnerships that limit supplier switching.
Germany
Automotive OEMs operate centralized validation centers for EV battery pack certification under UN 38.3 and ECE R100 protocols. KBA enforcement of transport safety regulations compresses procurement authority away from distributed plant-level quality labs. Stuttgart-based Tier-1 suppliers adopt model-based control architectures within compressed capital cycles.
China
MIIT battery safety standards and GB certification requirements accelerate capital allocation toward drop test equipment. Factory-level quality labs in East Asia favor cost-optimized pneumatic shaker lines for consumer electronics screening. Validation centers in the Yangtze River Delta concentrate demand for electromechanical platforms serving automotive export certification.
France
EASA CS-25 certification requirements sustain structural demand for high-force hydraulic shakers independent of commercial aircraft production rates. ANSM oversight of medical device transport validation creates incremental demand for precision shock testing. Toulouse aerospace primes reconfigure test floor layouts to accommodate expanded avionics qualification protocols.
Japan
METI industrial standards and JIS certification requirements anchor demand for precision electromechanical shakers in automotive and electronics applications. Kansai-based automotive suppliers maintain high-cycle test cells for component durability validation. National laboratory facilities pursue IEC 60068-2-27 accreditation for contract testing services.
Shock Testing System Market Competitive Environment
Electromechanical specialists and hydraulic system manufacturers split the market between precision versatility and extreme-force applications. The vendor base concentrates around accredited laboratory partnerships that lock in defense and aerospace contracts. Three archetypes dominate: North American service-network players, proprietary armature designers, and cost-optimized pneumatic fabricators. Competitive moves center on aftermarket service unbundling and multi-axis control system integration.
Within the North American service tier, Team Corporation exemplifies the recurring-revenue model through aftermarket calibration and extended warranty programs. MB Dynamics, Inc. occupies a position among proprietary technology specialists focused on armature durability. Dongling Technologies anchors the cost-optimized segment with pneumatic shaker lines serving mid-tier electronics factories. These three represent distinct strategic positions without overlapping customer segments.
| Leading Market Players |
|---|
| Team Corporation |
| MB Dynamics, Inc. |
| Brüel & Kjær |
| Dongling Technologies |
| Unholtz-Dickie Corporation |
| Lansmont Corporation |
| Data Physics Corporation |
| Labtone |
| Thermotron Industries |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on accredited metrology services in Germany and the United States compresses pricing power for mid-tier buyers while forcing East Asian electronics factories to absorb logistics premiums or defer certification timelines entirely. This regulatory chokepoint stratifies the market into three distinct tiers: premium electromechanical platforms commanding service-attach premiums, standard hydraulic systems locked into defense procurement cycles, and economy pneumatic lines competing on factory-floor acquisition cost.
Pricing Analysis
Aftermarket calibration and extended warranty contracts now drive lifetime value for platform vendors, with service revenue attaching at 40-60% of initial hardware value over a ten-year operational span. Pricing stratifies across premium electromechanical shakers with multi-axis control capabilities, standard hydraulic systems certified for MIL-STD-810H traceability, and economy pneumatic lines serving high-volume electronics screening. Cost compression in the pneumatic tier intensifies as Chinese factories absorb margin pressure from logistics premiums for German calibration services. Automotive OEMs in Stuttgart show the least price sensitivity, prioritizing accredited validation partnerships over acquisition cost.
Supply Chain Analysis
High-grade magnetic materials and precision-machined armature assemblies feed from specialized suppliers in Germany, Japan, and the United States, with rare-earth magnet processing concentrated in Chinese refining facilities. Critical inputs include neodymium-iron-boron magnets, aerospace-grade aluminum forgings, and proprietary armature laminations. Single-source vulnerability in accredited vibration sensor calibration creates chokepoints that extend lead times for IEC 60068-2-27 certification. Distribution runs through direct OEM relationships for large platforms and regional distributor networks for factory-floor screening equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration infrastructure and fixture refurbishment contracts are expanding faster than hardware shipments, transforming vendor economics toward recurring-revenue models. Service-attach rates for accredited metrology and extended warranty programs now determine competitive positioning more than initial equipment pricing.
For Market Incumbents: Harden accredited laboratory partnerships against emerging multi-axis control specialists by embedding finite-element simulation capabilities into standard platform offerings. Lock in defense contracts through MIL-STD-810H traceability investments that exceed audit thresholds. Vertical integration into armature manufacturing compresses replacement part margins for aftermarket competitors. For New Entrants and Emerging Players: Build out unbundled calibration services targeting legacy shaker installed bases in North America, where fragmented demand escapes OEM service networks. The most penetrable white-space sits in mobile shaker platforms for field validation of defense equipment, where laboratory access constraints create captive demand. A rental-plus-certification subscription model sidesteps capital budget friction at mid-tier electronics factories. For Investors and Strategic Acquirers: EU battery passport regulations reshape the acquisition landscape by mandating integrated shock-thermal-vibration platforms for cell-to-pack traceability. Long-term viability favors vendors with accredited laboratory partnerships spanning multiple regulatory jurisdictions. The signal to watch is KBA enforcement intensity for UN 38.3 certification, which would accelerate capital deployment cycles at German validation centers.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Partnership Expansion | MIL-STD-810H traceability mandates lock in defense contractor relationships beyond hardware replacement cycles. |
| Model-Based Control Architecture Integration | Finite-element simulation embedding compresses EV battery qualification timelines from months to weeks for Stuttgart suppliers. |
| Aftermarket Service Unbundling | Calibration and fixture refurbishment contracts capture fragmented demand outside OEM service networks in North America. |
| Mobile Platform Development | Field validation capabilities address defense equipment testing constraints where laboratory access is impractical. |
| Multi-Axis Drop Test Equipment Scale-Up | UN 38.3 and ECE R100 certification requirements accelerate capital allocation toward crash pulse replication systems. |
Study Parameters
Operator-level perspectives from validation center managers, aftermarket service directors, and defense procurement officers anchored the qualitative base. Primary interviews with aerospace test engineers at Toulouse and Hamburg facilities, automotive platform engineers in Stuttgart, and electronics quality lab supervisors in the Yangtze River Delta informed demand-side dynamics. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification databases, IEC standard revision timelines, and KBA enforcement records. Bottom-up equipment shipment estimates triangulated against top-down capital expenditure patterns at centralized validation centers.
Scenario-bracketing around regulatory revision timelines and EV certification mandate enforcement shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, application sector, end-user organization, and installation configuration, with regulatory cluster as an additional industry-specific dimension. CAGRs derived from installed base replacement cycles, accreditation audit queue durations, and capital deployment patterns at German automotive OEMs. Industry-specific forecast inputs incorporated MIL-STD-810H revision frequency and MIIT battery safety standard adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese pneumatic specialists into electromechanical platforms would shift outcomes. Cross-checking against EASA and FAA certification backlog data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Color Meter Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Battery Testing Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Telecom Testing Equipment Market
Test and Measurement
Network Tester Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market