
 Radiation Effects Testing Market | 2026-2036
Radiation Effects Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Effects Testing Market Insights
MIL-STD-883 qualification is bifurcating the vendor landscape into accredited laboratories and secondary service providers. Boeing sustains extensive in-house radiation test capacity tied to satellite and strategic missile programs. Northrop Grumman leverages captive testing infrastructure for classified payload verification. Alter Technology specializes in ESCC-qualified testing for European space agency supply chains.
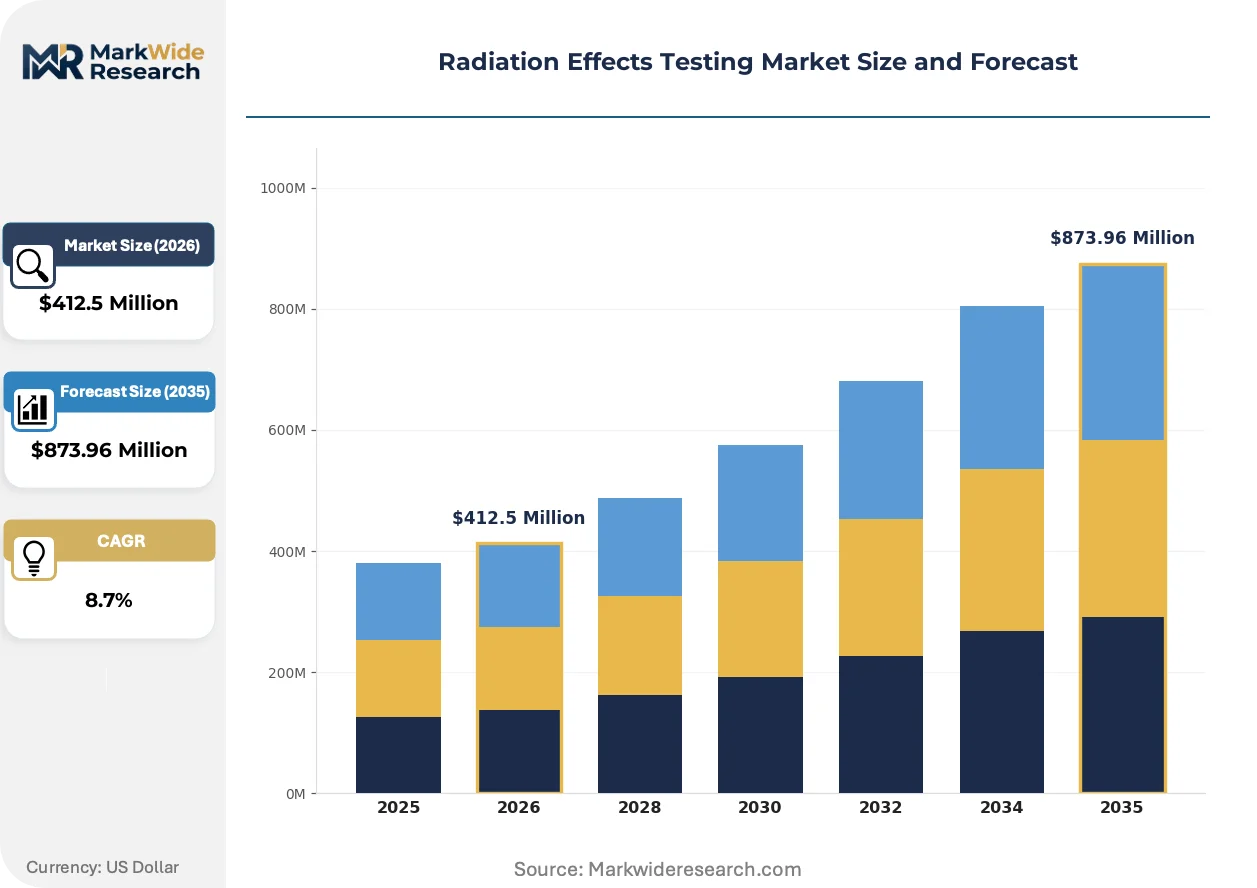
Radiation effects testing evaluates component and system behavior under ionizing and non-ionizing radiation exposure, encompassing total ionizing dose, single-event effects, and displacement damage measurements using cobalt-60 gamma sources, proton beams, and neutron facilities. The primary purpose is to validate electronic reliability for missions where radiation-induced failure carries catastrophic operational or human safety consequences. Ionizing radiation testing commands premium pricing due to accelerator facility scarcity and extended dwell times, while particle beam technology attracts investment for single-event upset characterization. Aerospace applications dominate volume, though medical device qualification for radiation therapy equipment represents an expanding margin pool.
FDA 21 CFR Part 820 quality system requirements govern medical device radiation testing documentation, while NASA-STD-8739 and ESA ECSS-Q-ST-60-02C dictate space-grade component qualification protocols. These frameworks create compliance barriers that favor established laboratories with multi-standard accreditation. Stakeholders must weigh captive facility investment against outsourced qualification as accelerator availability tightens and mission timelines compress.
Market Dynamics
Accelerator facility scarcity is compressing test queue timelines and concentrating qualification capacity among laboratories with captive cobalt-60 sources or proton beam access, forcing satellite prime contractors into multi-year capacity reservations.
Growth Catalysts
- Artemis Program Procurement:NASA's lunar infrastructure investments mandate radiation-hardened avionics qualification for crewed missions, expanding test volume for deep-space rated components.
- ESCC 22900 Harmonization:European Space Agency supply chain standardization accelerates cross-border component acceptance, reducing duplicate testing for multi-national satellite programs.
- Constellation Deployment:Commercial low-Earth orbit satellite operators require accelerated batch qualification protocols, compressing traditional test cycles for high-volume production.
Market Restraints
- Isotope Supply Concentration:Cobalt-60 source replenishment depends on a limited number of nuclear reactor facilities, creating geographic single-point vulnerabilities in gamma irradiation capacity.
- Accelerator Capital Intensity:Proton and heavy-ion beam facilities require nine-figure capital investments with decade-long construction timelines, blocking new market entry.
- MIL-STD-883 Revision Lag:Defense qualification protocol updates trail commercial space component innovation, creating compliance friction for advanced semiconductor nodes.
Strategic Opportunities
- Medical Device Expansion:FDA 21 CFR Part 820 radiation therapy equipment qualification represents an underpenetrated margin pool with less cyclical demand than aerospace.
- India Space Program Growth:ISRO's increased launch cadence and indigenous satellite manufacturing create demand for domestic radiation test infrastructure.
- Digital Twin Integration:Convergence of radiation transport simulation software with physical test validation reduces required beam time and accelerates qualification cycles.
Industry Challenges
- Radiation Effects Engineering Talent:The specialized skill set combining semiconductor physics, nuclear engineering, and mission assurance expertise faces generational replacement gaps.
- Multi-Standard Accreditation Burden:Laboratories must simultaneously maintain MIL-STD-883, ESCC 22900, and NASA-STD-8739 compliance, multiplying audit and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Effects Testing Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Thermal Testing, Electrical Testing, Ionizing Radiation Testing, Non-Ionizing Radiation Testing Application: Aerospace, Defense, Medical Devices, Nuclear Power End User: Manufacturers, Research Institutions, Government Agencies, Quality Control Labs Technology: Particle Beam, Gamma Radiation, X-ray Technology, Neutron Testing |
| Companies Covered | Spirit Electronics, Boeing, Radiation Test Solutions, Applied Technical Services, CERAP Prevention, VPT Rad, Space Talos, Northrop Grumman, Alter Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Effects Testing Market Trends and Innovations
Test methodology is bifurcating between legacy accelerator-based qualification and simulation-augmented protocols that reduce physical irradiation requirements. Laboratories are investing in computational capabilities alongside beam infrastructure.
Heavy-ion microbeam technology is decomposing traditional bulk irradiation approaches by enabling single-event effect mapping at the device level. Satellite component suppliers are adopting microbeam protocols to reduce total ionizing dose exposure during characterization. This precision approach is decomposing the economics of batch testing, favoring laboratories with specialized beamline configurations over general-purpose gamma facilities.
REACH substance restrictions on hazardous materials are reshaping radiation source handling protocols across European test facilities. ECHA registration requirements for cobalt-60 transport and storage have increased operational compliance costs. Aerospace component manufacturers with European supply chain exposure are consolidating qualification programs at ESCC-accredited laboratories with established chemical safety infrastructure.
Long-term capacity reservation contracts are displacing spot-market test scheduling among prime satellite contractors. Boeing and Northrop Grumman have secured multi-year beam time allocations at domestic accelerator facilities. This contractual shift is most visible in United States defense procurement, where mission timeline certainty outweighs per-test pricing flexibility.
Radiation Effects Testing Market Segmentation
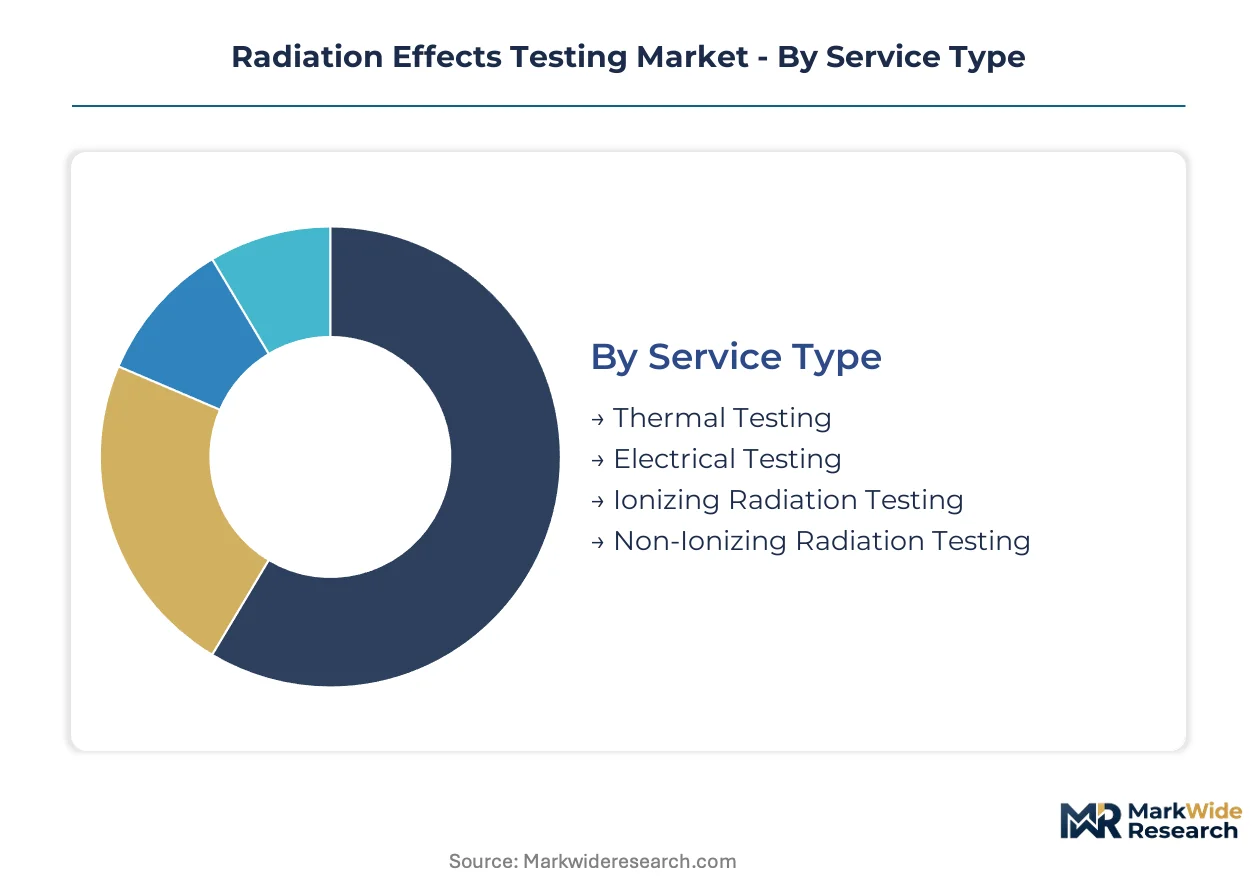
Radiation effects testing markets fragment across multiple dimensions that dictate facility investment, accreditation requirements, and customer relationships. Service type determines capital intensity and regulatory scope, while application verticals impose distinct qualification protocols and timeline pressures.
Service Type:
Ionizing radiation testing concentrates in domestic US and European facilities with captive accelerator infrastructure, while thermal and electrical testing distributes more broadly across export-capable laboratories in Asia-Pacific.
- Ionizing Radiation Testing:Deploys cobalt-60 gamma sources, proton beams, and heavy-ion accelerators to measure total ionizing dose and single-event effects in semiconductor devices. Demand clusters at NASA Artemis suppliers and ESA-contracted component vendors in the United States and France, constrained by reactor isotope supply bottlenecks.
- Non-Ionizing Radiation Testing:Evaluates electromagnetic interference and radio frequency exposure using anechoic chambers and signal generators. Medical device manufacturers in the United States drive volume under FDA 21 CFR Part 820 documentation requirements, with faster turnaround cycles than aerospace qualification.
- Thermal Testing:Simulates temperature cycling and thermal vacuum conditions for space-rated components. Laboratories in Japan and South Korea export services to satellite constellation operators seeking accelerated batch protocols.
- Electrical Testing:Characterizes parametric drift and functional degradation under bias conditions. Research institutions in Germany and the United Kingdom contract for parametric screening ahead of full radiation qualification.
Ionizing radiation testing holds the largest share; momentum sits with non-ionizing radiation testing as medical device qualification expands.
Application:
Aerospace and defense applications command premium pricing tiers tied to mission assurance requirements, while medical devices and nuclear power offer volume scale with shorter contract durations.
- Aerospace:Satellite component qualification for geostationary and low-Earth orbit missions demands MIL-STD-883 and ESCC 22900 compliance. Boeing and Northrop Grumman reserve multi-year capacity at domestic US accelerator facilities, compressing availability for secondary contractors.
- Defense:Strategic missile and payload verification requires classified testing infrastructure with restricted facility access. The United States Department of Defense mandates radiation-hardened avionics for nuclear command-and-control systems, sustaining dedicated test queues.
- Medical Devices:Radiation therapy equipment and implantable electronics require FDA 21 CFR Part 820 quality system documentation. Siemens Healthineers and Varian Medical Systems contract for sterilization validation and device hardness verification.
- Nuclear Power:Instrumentation and control system qualification for reactor environments uses neutron and gamma exposure protocols. France's EDF and the United States' reactor operators sustain steady demand for safety-related component testing.
Aerospace dominates revenue concentration; medical devices are gaining share fastest as therapy equipment markets expand.
End User:
Government agencies anchor long-term capacity contracts, while manufacturers and quality control labs drive spot-market pricing volatility.
- Government Agencies:NASA, ESA, and defense procurement offices mandate standardized qualification protocols for mission-critical components. Multi-year funding cycles enable advance reservations at scarce accelerator facilities.
- Manufacturers:Semiconductor foundries and satellite component suppliers require batch qualification for high-volume production. SpaceX and Amazon's Project Kuiper compress traditional test timelines for constellation deployment schedules.
- Research Institutions:Universities and national laboratories conduct fundamental radiation effects research and method development. MIT Lincoln Laboratory and Germany's Fraunhofer institutes maintain in-house beamline access.
- Quality Control Labs:Third-party accreditation bodies verify supplier compliance for prime contractor acceptance. ESCC-accredited laboratories in Spain and Italy consolidate European supply chain testing.
Government agencies hold the largest share; manufacturers are expanding most quickly as commercial space production scales.
Technology:
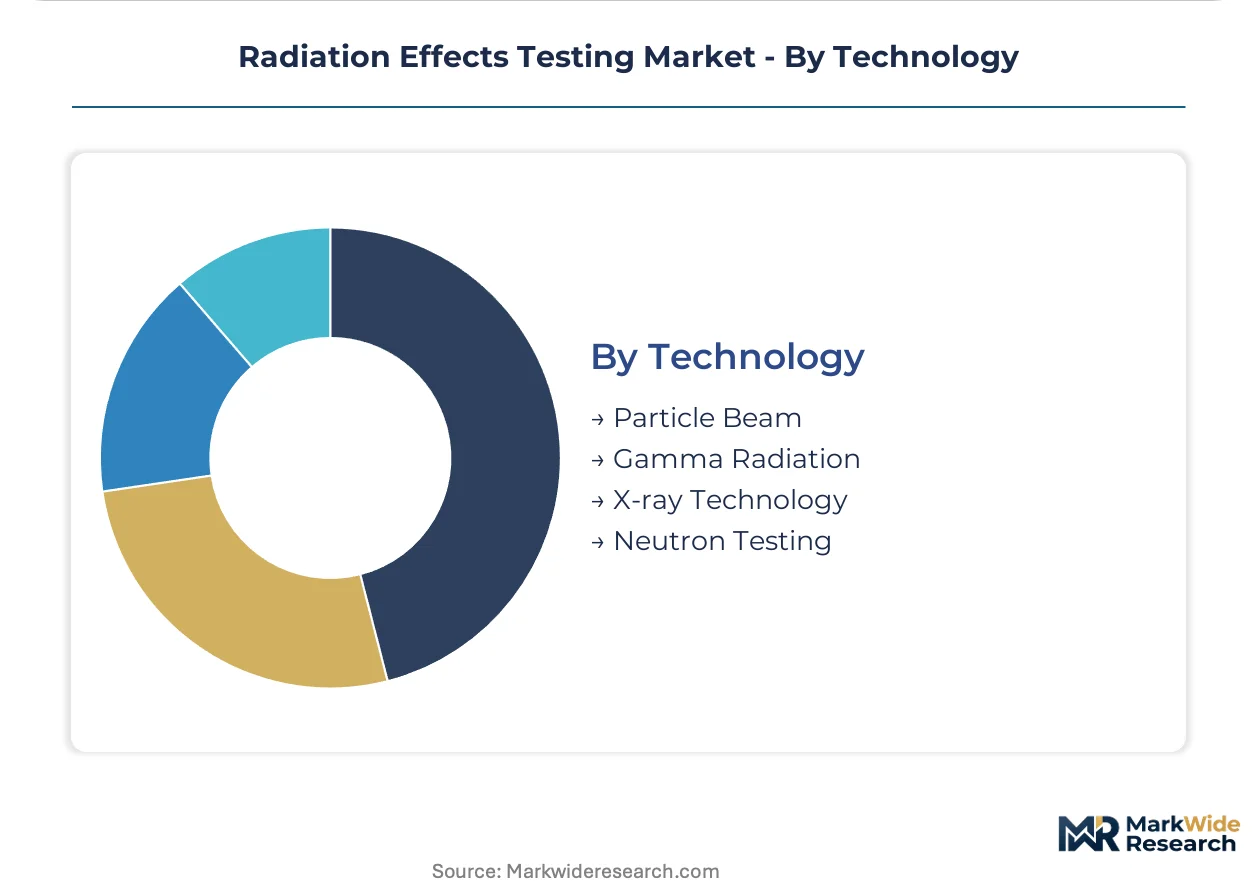
Particle beam infrastructure concentrates at national laboratories and defense-funded facilities, while gamma radiation distributes across commercial service providers.
- Particle Beam:Proton and heavy-ion accelerators enable single-event upset characterization with precise linear energy transfer control. Lawrence Berkeley National Laboratory and Texas A&M University Cyclotron Institute serve US aerospace primes.
- Gamma Radiation:Cobalt-60 sources provide uniform total ionizing dose exposure for batch component screening. Canada's Nordion and Russia's Rosatom control isotope supply chains for global source replenishment.
- X-ray Technology:High-energy X-ray systems offer intermediate dose rates for medical device and industrial qualification. Japanese manufacturers deploy compact X-ray facilities for electronics hardness screening.
- Neutron Testing:Reactor-based and accelerator-driven neutron sources measure displacement damage in power electronics. Sandia National Laboratories maintains specialized capabilities for defense applications.
Gamma radiation holds the largest share; particle beam shows the steepest expansion trajectory as single-event effect characterization demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement mandates and space agency infrastructure investments are concentrating radiation effects testing capacity in jurisdictions with established accelerator facilities and defense contracting ecosystems.
United States
NASA Artemis program investments and Department of Defense satellite resilience directives sustain multi-year capacity reservations at domestic accelerator facilities. MIL-STD-883 qualification requirements govern defense procurement protocols for strategic missile and payload verification. Texas A&M University Cyclotron Institute and Lawrence Berkeley National Laboratory anchor proton and heavy-ion beam access for aerospace primes.
France
European Space Agency supply chain standardization and ESCC 22900 harmonization accelerate cross-border component acceptance for multi-national satellite programs. ECHA registration requirements for cobalt-60 transport and storage reshape radiation source handling protocols. Toulouse and Paris-Saclay clusters concentrate ESCC-accredited laboratories with established chemical safety infrastructure.
Germany
REACH substance restrictions on hazardous materials and ECHA compliance frameworks elevate operational costs for gamma irradiation facilities. Fraunhofer institutes maintain in-house beamline access for fundamental radiation effects research. Bavaria and North Rhine-Westphalia host research institutions contracting for parametric screening ahead of full radiation qualification.
Japan
METI industrial policy supports domestic satellite component manufacturing and indigenous space program expansion. High-energy X-ray systems offer intermediate dose rates for medical device and industrial qualification. Tokyo and Osaka metropolitan areas deploy compact X-ray facilities for electronics hardness screening with faster turnaround cycles than aerospace protocols.
India
ISRO increased launch cadence and indigenous satellite manufacturing create demand for domestic radiation test infrastructure. BIS standardization frameworks for space-grade components remain under development relative to mature NATO-aligned protocols. Bengaluru and Hyderabad clusters concentrate emerging test capacity serving commercial constellation operators.
Radiation Effects Testing Market Competitive Landscape
Listed leaders compete with private specialists across facility ownership models, creating a tiered structure where captive aerospace infrastructure dominates premium qualification queues. Defense primes and commercial laboratories bifurcate the vendor landscape through divergent capital deployment strategies. Three archetypes prevail: vertically integrated aerospace conglomerates with in-house accelerator access, ESCC-accredited European specialists serving agency supply chains, and independent third-party laboratories competing on turnaround speed. Capacity reservation contracts and multi-standard accreditation investments constitute the dominant competitive moves, compressing spot-market availability for secondary contractors.
Within the aerospace conglomerate tier, Boeing and Northrop Grumman exemplify captive infrastructure strategies through extensive in-house radiation test capacity tied to satellite and strategic missile programs. Alter Technology occupies a specialist position as an ESCC-qualified testing provider for European space agency supply chains. These three entities anchor distinct competitive vectors: domestic defense procurement integration, classified payload verification protocols, and cross-border component standardization.
| Leading Market Players |
|---|
| Spirit Electronics |
| Boeing |
| Radiation Test Solutions |
| Applied Technical Services |
| CERAP Prevention |
| VPT Rad |
| Space Talos |
| Northrop Grumman |
| Alter Technology |
| Others |
Pricing and Supply Chain Analysis
Cobalt-60 source replenishment shifting from Canadian to Russian reactor output is redrawing isotope procurement geography while compressing gamma irradiation pricing power at European test facilities bound by ECHA transport restrictions.
Pricing Analysis
Certification level — MIL-STD-883, ESCC 22900, NASA-STD-8739 — creates the primary spread between accredited laboratories and secondary service providers. Three-tier pricing structure across mission-assurance premium, standard qualification, and economy screening levels dominates contract structures. Cost compression in standard-tier batch testing is intensifying because commercial constellation operators compress traditional test cycles. Government agencies exhibit lowest price sensitivity due to multi-year funding cycles, while commercial satellite component suppliers face acute margin pressure from accelerated deployment schedules.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites cobalt-60 source security planning at gamma irradiation facilities dependent on Russian Rosatom and Canadian Nordion isotope supply chains. Test capacity draws from United States, France, and Germany for ionizing radiation infrastructure, while thermal and electrical testing sources from Japan and South Korea. Single-source vulnerability concentrates in reactor-based isotope production for gamma sources. Distribution runs through long-term capacity reservation contracts displacing spot-market scheduling among prime satellite contractors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive story where multi-standard accreditation entrenchment creates prohibitive switching costs for customers and barrier-to-entry for new laboratories.
For Market Incumbents: Secure multi-year beam time allocations at domestic accelerator facilities before commercial constellation operators exhaust remaining spot-market availability. Deepen backward integration into cobalt-60 source procurement through direct reactor partnerships, mitigating Rosatom supply concentration risk. Prioritize ESCC 22900 and NASA-STD-8739 dual-accreditation investment to capture cross-border European supply chain consolidation. For New Entrants and Emerging Players: Differentiate on digital twin integration capabilities that reduce required physical beam time for single-event effect characterization. Target medical device qualification under FDA 21 CFR Part 820 as the most penetrable vertical, offering faster turnaround cycles than aerospace protocols with less cyclical demand. Pursue hospital system partnerships with Siemens Healthineers and Varian Medical Systems as anchor customers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European test laboratory specialists holding ESCC accreditation but lacking proton beam infrastructure. Long-term viability hinges on accelerator facility scarcity deepening over the projection horizon. Watch ISRO domestic capacity buildout as inflection indicator for India market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator Capacity Reservation | Multi-year beam time contracts at Texas A&M and Lawrence Berkeley secure qualification queues for Artemis suppliers. |
| Digital Twin Integration | Convergence of radiation transport simulation with physical validation reduces cobalt-60 dwell time for satellite primes. |
| ESCC Accreditation Investment | Cross-border component standardization under ESA supply chain protocols consolidates testing at Toulouse and Paris-Saclay clusters. |
| Medical Device Vertical Expansion | FDA 21 CFR Part 820 qualification services diversify revenue beyond cyclical aerospace procurement. |
| Isotope Supply Backward Integration | Direct reactor partnerships with Nordion or Rosatom mitigate geographic single-point vulnerability in gamma source replenishment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with radiation effects engineers, mission assurance directors at satellite primes, accelerator facility operators, and medical device regulatory affairs leads; and secondary validation against NASA procurement databases, ESA contract award notices, FDA 510(k) radiation therapy equipment filings, and reactor isotope production records from IAEA nuclear research databases. Bottom-up facility capacity modeling triangulated against top-down aerospace and defense procurement budget analysis.
Across the analysis window, the analytical framework modeled service type, application vertical, end-user category, and technology platform segmentation dimensions. CAGRs were derived from accelerator facility utilization rates, constellation deployment schedules, and medical device qualification pipeline data. Industry-specific forecast inputs included Artemis program component procurement timelines and ISRO launch cadence projections.
Material uncertainties — reactor isotope supply disruptions, MIL-STD-883 revision lag against advanced semiconductor nodes, and REACH substance restriction scope expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding accelerator construction timelines and agency funding continuity. Practitioners should keep alternative scenarios live as cobalt-60 source geography and European chemical safety enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Volte Testing Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Color Meter Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Production Testing Market
Test and Measurement
Bit Error Rate Tester Market