
 X-Ray Inspection System Market | 2026-2036
X-Ray Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Inspection System Market Intelligence
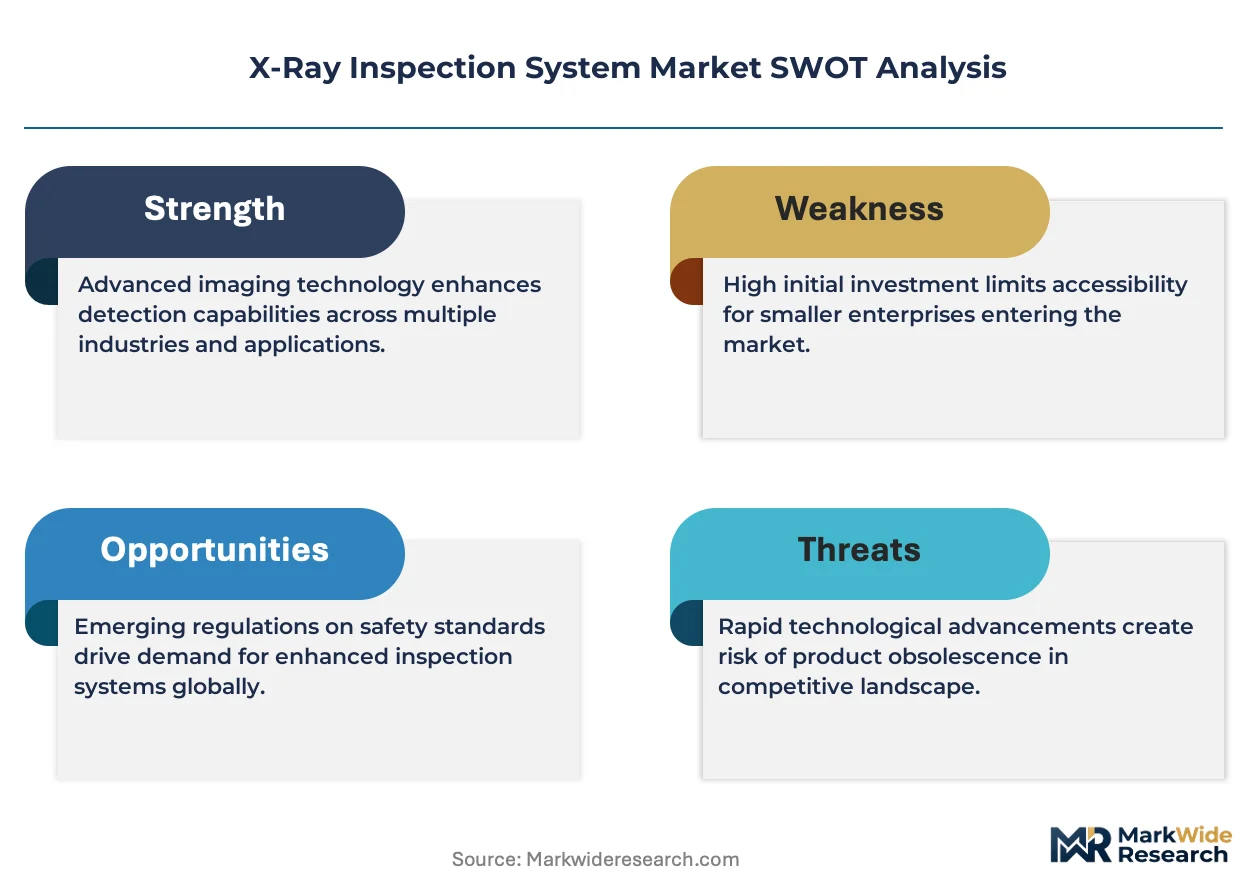
EU MDR is rebalancing the cost-of-entry calculus for X-ray inspection systems sold into European healthcare channels, forcing manufacturers to recertify legacy platforms under stricter clinical validation protocols. Nordson Corporation leverages its adhesive dispensing heritage to anchor inline inspection workflows in semiconductor packaging facilities. Mettler Toledo sustains dominance in pharmaceutical checkweighing-integrated X-ray lines through precision sensor calibration. YXLON International GmbH specializes in high-resolution computed tomography systems for aerospace turbine blade inspection, competing on defect detectability thresholds below 50 microns.
An X-ray inspection system generates ionizing radiation to penetrate opaque materials and capture internal structural images through differential absorption, with tube voltages typically spanning 20 kV to 450 kV depending on material density and penetration depth. These systems perform non-destructive evaluation of solder joints, castings, composite laminates, and packaged pharmaceuticals without sectioning or destroying the subject. Fixed X-ray systems occupy the largest installed base in automated manufacturing lines, while computed tomography systems represent the fastest-expanding segment as additive manufacturing and battery cell production demand volumetric defect mapping rather than planar projection. Digital radiography systems with flat panel detectors are displacing legacy film and computed radiography in security screening applications, concentrating margin pools in detector panel supply chains.
FDA 21 CFR Part 1020 governs diagnostic X-ray system performance standards in the United States, while the EU AI Act imposes conformity requirements on automated defect classification algorithms deployed in European manufacturing environments. China's NMPA and GB standards mandate type testing for medical X-ray equipment, creating parallel certification tracks for vendors serving both clinical and industrial end users. Stakeholders must monitor how divergent regulatory timelines for AI-enabled inspection software reshape product development roadmaps and geographic rollout sequencing.
Market Dynamics
Computed tomography systems are electrifying quality assurance workflows as battery cell manufacturers and aerospace suppliers demand volumetric defect mapping beyond planar radiography. This shift from 2D projection to 3D reconstruction is compressing inspection cycle times while raising capital intensity thresholds for equipment procurement.
Growth Catalysts
- EU MDR validation protocols:European healthcare systems now mandate stricter clinical evidence for non-destructive testing equipment, creating replacement demand for legacy platforms that cannot meet enhanced safety documentation requirements.
- Shenzhen-Dongguan electronics clusters:PCB assembly lines across China's Pearl River Delta now require 100% X-ray coverage for solder joint integrity, pulling inline automated systems into high-volume manufacturing environments.
- Void detection in advanced packaging:Semiconductor facilities in Taiwan and South Korea are scaling automated inline inspection for flip-chip and 3D-IC solder interconnects as node shrinkage intensifies reliability requirements.
Market Restraints
- Tungsten supply concentration:X-ray tube anode manufacturing depends on concentrated tungsten processing capacity, exposing system costs to raw material volatility and geopolitical supply disruptions.
- FDA 21 CFR Part 1020 compliance costs:Diagnostic equipment sold into US clinical channels faces extensive performance testing and quality system documentation, extending product development timelines and raising entry barriers.
- Flat panel detector oligopoly:Digital radiography migration concentrates margin capture among a handful of detector panel suppliers, compressing system integrator profitability and limiting sourcing flexibility.
Strategic Opportunities
- Additive manufacturing qualification:Aerospace and medical implant producers require CT-based porosity mapping for powder-bed fusion parts, opening inspection-as-a-service revenue models.
- EU AI Act algorithmic conformity:Automated defect classification software deployed in European manufacturing environments now falls under specific conformity assessment procedures, creating first-mover advantage for compliant vendors.
- India pharmaceutical packaging lines:Domestic formulation facilities are upgrading from manual sampling to 100% inline inspection for foreign object detection, supported by PLI scheme capital subsidies.
Industry Challenges
- Radiation safety officer certification:Industrial facilities face acute shortages of qualified personnel capable of managing shielding design, dosimetry programs, and regulatory reporting for ionizing equipment.
- Legacy system integration:Manufacturing execution systems in mature electronics facilities often lack native connectivity protocols for modern CT inspection metadata, forcing expensive middleware development.
- Dual certification complexity:Vendors serving both clinical and industrial end users must maintain parallel quality systems for FDA, NMPA, and ISO 13485 tracks, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Inspection System Market |
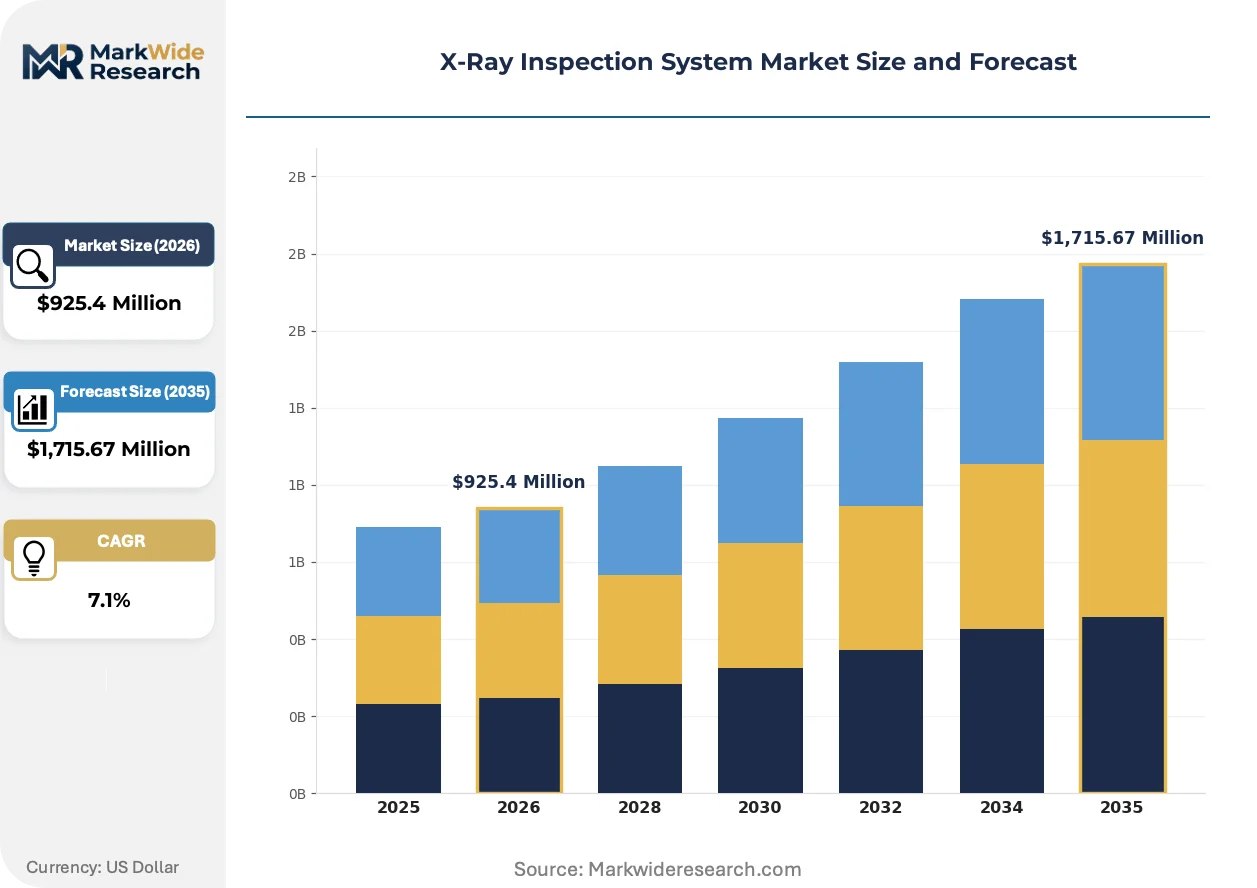
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,715.67 Million |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed X-Ray Systems, Portable X-Ray Systems, Computed Tomography Systems, Digital Radiography Systems Application: Quality Control, Security Screening, Materials Inspection, Medical Diagnosis End User: Aerospace, Automotive, Healthcare, Manufacturing Technology: Linear Array, Area Array, CCD, Flat Panel Detector |
| Companies Covered | Nordson Corporation, Mettler Toledo, North Star Imaging Inc., Nikon Metrology, Inc., YXLON International GmbH, Viscom AG, Comet Group, Nikon Corporation, VisiConsult X-ray Systems & Solutions GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Inspection System Market Strategic Shifts & Innovations
Artificial intelligence inference at the inspection edge is compressing defect classification latency from seconds to milliseconds. This acceleration is reshaping competitive positioning around software-defined system architectures rather than hardware specifications alone.
Sub-50-micron resolution CT systems are electrifying turbine blade and battery electrode inspection workflows. Rolls-Royce and Safran now mandate volumetric porosity mapping for single-crystal casting acceptance. The structural consequence is a bifurcation between premium CT platforms and commodity radiography systems, with mid-range product categories losing share.
China's NMPA and GB standards are tightening type testing requirements for medical X-ray equipment sold domestically. Industrial vendors attempting to serve both clinical and non-clinical end users must now navigate divergent technical documentation tracks. Semiconductor packaging facilities in Taiwan are responding by segregating product lines earlier in development to avoid cross-contamination of regulatory files.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into inspection-as-a-service offerings. Electronics manufacturers in South Korea now prefer per-scan pricing over capital ownership, transferring utilization risk to equipment vendors. This shift is most visible in smartphone assembly lines where product mix volatility makes fixed asset commitment uneconomical.
X-Ray Inspection System Market Segmentation
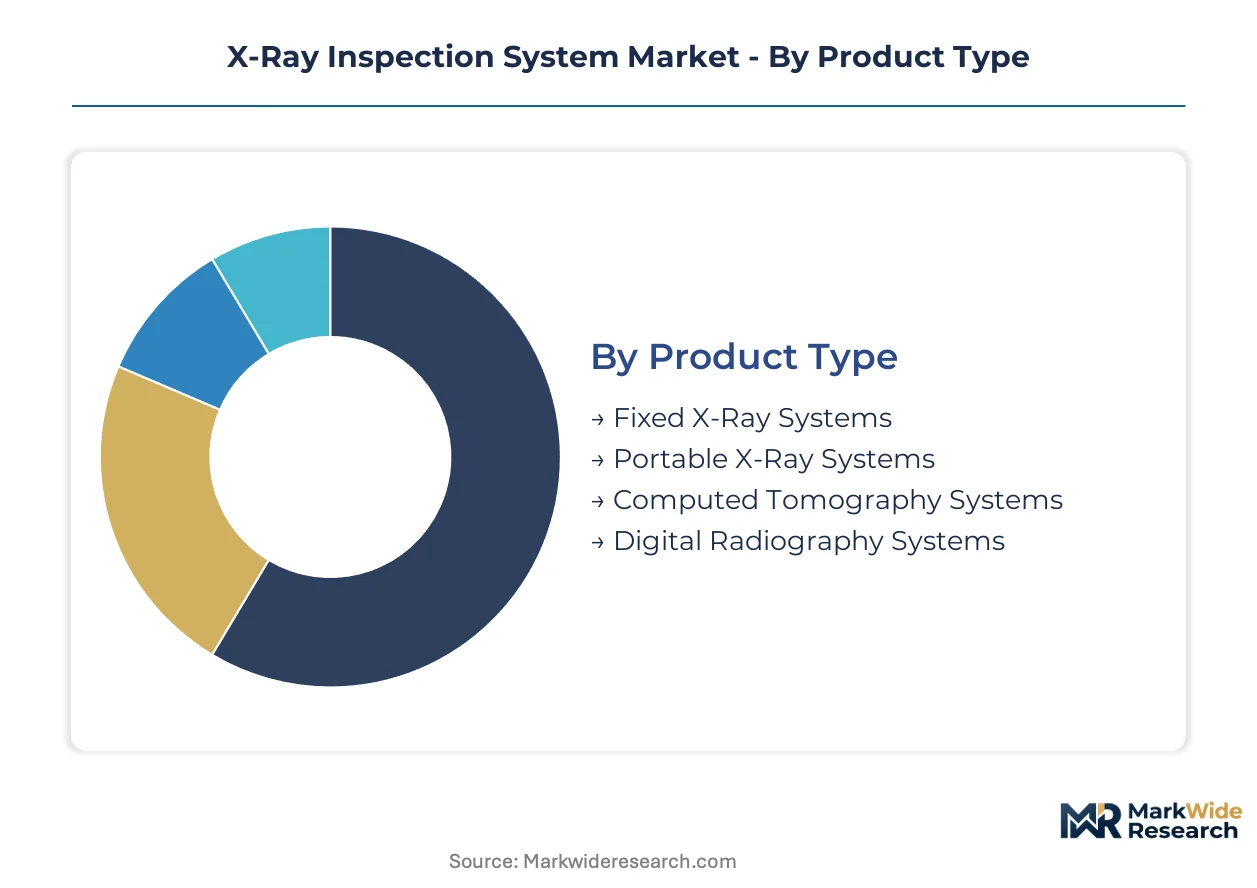
X-ray inspection systems fragment across multiple technical dimensions that determine procurement priorities and vendor selection criteria. Capital intensity, regulatory compliance burden, and integration complexity vary dramatically between fixed manufacturing lines and portable field deployments.
Product Type:
Capital intensity separates installation-grade systems from mobile units, with volumetric imaging platforms commanding premium pricing and extended deployment cycles.
- Fixed X-Ray Systems:Stationary cabinet or tunnel configurations integrate into automated production lines with conveyor-fed part handling and programmable inspection routines. Shenzhen-Dongguan electronics clusters pull these systems for 100% solder joint coverage in high-volume PCB assembly, though shielding requirements and radiation safety officer certification extend commissioning timelines.
- Computed Tomography Systems:Rotating gantry architectures reconstruct volumetric datasets from hundreds of angular projections, enabling porosity mapping in additive manufacturing and battery electrode inspection. Aerospace suppliers now mandate CT-based acceptance for single-crystal turbine castings as defect detectability thresholds compress below 50 microns.
- Portable X-Ray Systems:Battery-powered field units with flexible positioning arms serve pipeline weld inspection and structural integrity assessments where part transport is impractical.
- Digital Radiography Systems:Flat panel detector architectures displace film and computed radiography in security screening applications, concentrating supply chain leverage among specialized detector manufacturers.
Most installed capacity flows through Fixed X-Ray Systems. Expansion is steepest in Computed Tomography Systems.
Application:
End-use requirements dictate resolution specifications, throughput demands, and algorithmic sophistication, creating divergent product development roadmaps.
- Quality Control:Inline automated inspection for solder voids, casting porosity, and composite delamination dominates manufacturing floor deployments. Semiconductor packaging facilities in Taiwan scale these applications for flip-chip interconnect validation as node shrinkage intensifies reliability requirements.
- Security Screening:High-throughput baggage and cargo inspection at airports and ports drives demand for dual-energy discrimination and automated threat recognition algorithms.
- Materials Inspection:Non-destructive evaluation of welds, forgings, and composite laminates serves structural integrity verification without destructive sectioning.
- Medical Diagnosis:Diagnostic imaging applications fall under FDA 21 CFR Part 1020 in the United States and EU MDR validation protocols in Europe, imposing distinct clinical evidence requirements.
Quality Control absorbs the largest equipment spend. Security Screening is gaining share fastest as airport infrastructure modernization accelerates.
End User:
Customer sophistication and procurement authority vary sharply between regulated healthcare systems and discrete manufacturing operations.
- Manufacturing:Electronics assembly, automotive powertrain production, and pharmaceutical packaging lines drive volume procurement with emphasis on throughput and total cost of ownership metrics.
- Aerospace:Prime contractors and tier suppliers impose stringent acceptance protocols for turbine blades, structural castings, and composite primary structures, often mandating CT-based volumetric documentation.
- Automotive:Battery cell manufacturers and electric drivetrain suppliers deploy inspection for electrode alignment, weld penetration, and thermal runaway prevention.
- Healthcare:Hospital systems and diagnostic imaging centers operate under NMPA type testing requirements in China and FDA quality system regulations in the United States, fragmenting vendor certification tracks.
Manufacturing channels move the highest unit volumes. Aerospace commands the steepest average selling prices.
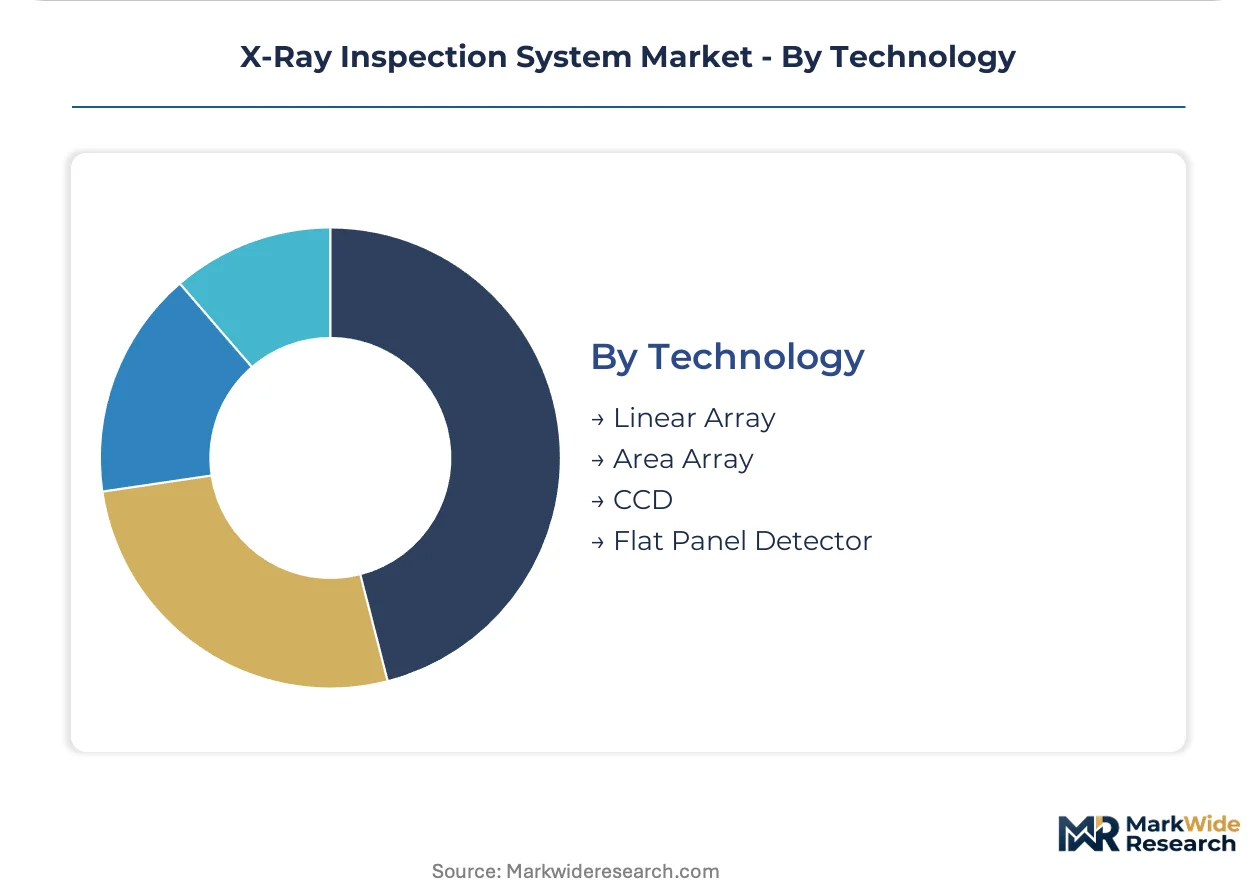
Technology:
Detector architecture determines image quality, acquisition speed, and system cost structure, with flat panel technologies displacing legacy alternatives.
- Flat Panel Detector:Amorphous silicon or CMOS active matrix arrays enable direct digital radiography with high detective quantum efficiency and rapid frame rates. Supply concentrates among a handful of specialized manufacturers, compressing system integrator margins.
- Area Array:Two-dimensional detector configurations capture full-field images in single exposures, accelerating inspection cycle times for electronics assembly applications.
- Linear Array:Single-row detector scanning architectures serve conveyor-based inspection with reduced detector cost but extended acquisition times.
- CCD:Charge-coupled device detectors persist in specialized microscopy and low-light applications though CMOS alternatives erode their position.
Flat Panel Detector technology anchors new system designs. Area Array configurations are climbing fastest in electronics manufacturing deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation safety officer certification shortages in industrial corridors are reshaping deployment timelines across major manufacturing geographies. Qualified personnel gaps in shielding design and dosimetry programs extend commissioning cycles and inflate operational costs for facilities adopting ionizing inspection equipment.
United States
Aerospace prime contractors in Connecticut and Washington State mandate sub-50-micron CT resolution for single-crystal turbine blade acceptance. FDA 21 CFR Part 1020 compliance costs extend product development timelines for diagnostic equipment channels. The Pacific Northwest battery cell manufacturing corridor pulls volumetric inspection systems for electrode alignment verification.
Germany
Automotive powertrain suppliers in Baden-Württemberg deploy inline X-ray for electric drivetrain weld penetration validation. The EU AI Act imposes conformity assessment procedures on automated defect classification algorithms deployed in manufacturing environments. Bavaria's aerospace cluster concentrates CT system procurement for turbine casting porosity mapping.
China
Electronics contract manufacturers in Shenzhen and Dongguan require 100% solder joint inspection coverage in high-volume PCB assembly lines. NMPA type testing mandates parallel certification tracks for vendors serving both clinical and industrial end users. Yangtze River Delta pharmaceutical packaging facilities upgrade from manual sampling to inline foreign object detection systems.
South Korea
Semiconductor packaging facilities scale automated inline inspection for flip-chip and 3D-IC solder interconnect void detection. MFDS pharmaceutical regulations align with international GMP standards for packaging line validation. Seoul Capital Area electronics manufacturers prefer per-scan pricing models over capital ownership for smartphone assembly inspection.
India
Domestic pharmaceutical formulation facilities upgrade packaging lines for 100% foreign object detection coverage. PLI scheme capital subsidies accelerate inline inspection adoption in contract manufacturing organizations. Maharashtra and Gujarat clusters concentrate equipment procurement for export-oriented generic drug packaging operations.
X-Ray Inspection System Market Key Industry Players
The competitive structure tilts toward precision instrumentation conglomerates with adjacent metrology expertise. Consolidation patterns favor vendors possessing captive detector supply relationships or adhesive dispensing heritage that anchors inline manufacturing workflows. Three archetypes dominate: diversified measurement technology groups, specialized non-destructive testing houses, and semiconductor process equipment integrators. Strategic moves concentrate on algorithmic conformity certification for EU AI Act compliance and service contract unbundling into inspection-as-a-service revenue models.
Among German-based precision specialists, YXLON International GmbH and Viscom AG occupy positions in high-resolution computed tomography and inline electronics inspection respectively. Nordson Corporation represents the adhesive dispensing heritage archetype leveraging manufacturing workflow integration. These three exemplify how regulatory specialization and application-specific algorithm development differentiate positioning as automated defect classification becomes a conformance requirement rather than optional feature.
| Leading Market Players |
|---|
| Nordson Corporation |
| Mettler Toledo |
| North Star Imaging Inc. |
| Nikon Metrology, Inc. |
| YXLON International GmbH |
| Viscom AG |
| Comet Group |
| Nikon Corporation |
| VisiConsult X-ray Systems & Solutions GmbH |
| Others |
Cost & Logistics Intelligence
Captive flat panel detector production anchors pricing power for integrated system vendors while compressing margins for pure-play integrators dependent on external sourcing. This upstream control over the highest-value subsystem allows vertically positioned manufacturers to defend premium positioning in CT platforms while forcing competitors toward inspection-as-a-service models to recover profitability.
Pricing Analysis
Service unbundling splits the market between capital-sale systems and per-scan revenue models. Three-tier pricing structure across premium CT, standard fixed systems, and economy portable units reflects detector resolution and algorithmic sophistication. Price differentiation centers on EU AI Act certification status and radiation safety documentation depth. Cost compression in mid-range fixed systems intensifies as South Korean electronics manufacturers demand per-scan pricing, transferring utilization risk to vendors. Pharmaceutical packaging lines in India exhibit highest price sensitivity due to PLI subsidy dependency, while aerospace prime contractors in Connecticut and Bavaria accept premium positioning for sub-50-micron CT resolution.
Supply Chain Analysis
Freight costs for tungsten anode assemblies and flat panel detector substrates concentrate supply chain leverage in East Asian logistics corridors. Tungsten processing capacity clusters in China, Vietnam, and Russia, exposing X-ray tube manufacturing to raw material volatility. System assembly draws from Taiwanese semiconductor packaging equipment ecosystems and German precision motion control suppliers. Single-source vulnerability in amorphous silicon detector substrates threatens production continuity for digital radiography platforms. Distribution runs through direct OEM sales for large aerospace accounts and regional system integrators for mid-market electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in X-ray inspection systems rests on algorithmic differentiation and service revenue conversion rather than hardware cost-down alone. The shift from capital equipment to inspection-as-a-service models captures recurring revenue streams while deflecting price pressure on system sales.
For Market Incumbents: Deploy EU AI Act algorithmic conformity certification as a defensive moat against unqualified entrants. Lock in exclusive flat panel detector supply agreements to preserve margin structure against commoditization. Counter the threat of per-scan pricing models by acquiring regional service capabilities in South Korea and India where capital ownership preferences are weakest.
For New Entrants and Emerging Players: Mid-tier contract electronics manufacturers in Vietnam and Mexico represent underserved buyer archetypes seeking automated solder inspection without aerospace-grade certification overhead. White-space targets include battery electrode inspection for emerging cell producers outside China and pharmaceutical packaging lines in Southeast Asia upgrading from manual sampling. A software-first go-to-market angle leveraging cloud-based defect classification bypasses capital-intensive detector manufacturing.
For Investors and Strategic Acquirers: Roll-up economics work for specialized CT service providers because customer concentration among aerospace primes creates predictable contract visibility. Five-to-ten year viability favors vendors with captive detector relationships and installed base conversion to recurring revenue. The signal to watch is tungsten supply agreement renegotiations indicating which integrators have secured upstream protection against raw material volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithmic Conformity Certification | Creates regulatory moat for automated defect classification software deployed in European manufacturing environments. |
| Flat Panel Detector Supply Agreement | Secures margin protection against oligopolistic pricing from specialized amorphous silicon substrate manufacturers. |
| Inspection-as-a-Service Model Launch | Captures recurring revenue from South Korean smartphone assembly lines preferring per-scan pricing over capital commitment. |
| Tungsten Anode Backward Integration | Reduces exposure to concentrated Vietnamese and Chinese raw material processing capacity. |
| Radiation Safety Training Program Development | Addresses acute certification shortages extending commissioning timelines in industrial corridors. |
Research Approach
Coverage spans the United States, Germany, China, South Korea, and India, with primary inputs from each geography weighted by installed equipment base. The analysis combines structured interviews with quality control directors at semiconductor packaging facilities, biomedical engineers in hospital purchasing committees, and aftermarket service heads at system integrators with secondary validation from FDA 510(k) filings, NMPA type testing registrations, and EU MDR technical documentation databases. Bottom-up equipment shipment tracking and top-down manufacturing value-added estimates were triangulated to anchor market sizing.
Granularity-level modeling disaggregated revenue across fixed systems, computed tomography platforms, portable units, and digital radiography architectures, with further segmentation by flat panel versus linear array detector technology. End-use splits incorporated quality control, security screening, materials inspection, and medical diagnosis channels. CAGRs across the projection horizon derived from equipment replacement cycles in aerospace turbine blade inspection and ramp rates for battery electrode volumetric mapping. Forecast inputs included PLI scheme disbursement schedules in India and MFDS pharmaceutical packaging line validation timelines in South Korea.
Inputs from hospital procurement databases and semiconductor capital expenditure disclosures were available through the study window; gaps in privately held contract electronics manufacturer inspection budgets introduce uncertainty bands around China volume estimates. Forecasts reflect assumptions regarding EU MDR recertification deadlines and tungsten supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
DSL Tester Market
Test and Measurement
Leak Testing Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Ultrasonic Testing Equipment Market