
 Immunodiagnostics Market | 2026-2036
Immunodiagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Immunodiagnostics Market Intelligence
The shift towards high-sensitivity, multiplexed assays is unwinding the market’s reliance on single-analyte, low-throughput systems. F. Hoffmann-La Roche Ltd leverages its integrated diagnostics and pharmaceuticals portfolio, particularly in oncology. Abbott sustains a dominant position in infectious disease testing and point-of-care solutions. Siemens Healthineers competes with large-scale automated immunoassay platforms for central laboratories.
Immunodiagnostics are biochemical tests that utilize antigen-antibody reactions to detect and quantify specific analytes in a biological sample. These assays measure biomarkers for disease diagnosis by exploiting the high specificity of antibody binding, often using enzymatic or luminescent reporters. While the infectious disease detection application continues to hold the largest share, oncology screening is expanding rapidly. Technologically, mature enzyme-linked immunosorbent assay (ELISA) platforms coexist with faster-growing, high-sensitivity chemiluminescence immunoassay (CLIA) systems.
Regulatory frameworks from the US FDA, Europe's CE-IVDR system, and China's NMPA create stringent market access pathways. These bodies mandate rigorous clinical performance data and quality system compliance, influencing product design and development timelines. Stakeholders must now decide whether to invest in decentralized point-of-care platforms or focus on consolidating high-throughput central laboratory automation.
Market Dynamics
The central dynamic in the immunodiagnostics market is the strategic tension between consolidating high-throughput automation in central laboratories and the simultaneous push towards decentralized, rapid testing at the point of care, driven by advancements in assay sensitivity.
Growth Catalysts
- Public Health Investment:National health initiatives, particularly in China, are accelerating the build-out of modern diagnostic laboratory infrastructure, creating a substantial demand pull for automated immunoassay systems.
- Oncology Screening Expansion:The increasing clinical use of immunodiagnostic biomarkers for early cancer detection and monitoring significantly expands the addressable patient population beyond traditional infectious disease testing.
- Technological Advancement:The transition from traditional ELISA to high-sensitivity chemiluminescence immunoassay (CLIA) and multiplexed platforms enables superior analytical performance, which is a requirement for new clinical applications.
Market Restraints
- Regulatory Hurdles:Stringent pre-market approval processes from bodies like the US FDA and Europe's CE-IVDR system mandate extensive clinical validation, increasing development costs and timelines for new assays.
- High Platform Costs:The significant capital investment required for large-scale automated immunoassay platforms creates a barrier to adoption for smaller laboratories and healthcare facilities in resource-limited settings.
- Reimbursement Uncertainty:Inconsistent or low reimbursement rates for novel diagnostic biomarkers in some healthcare systems can limit clinical uptake and disincentivize manufacturer investment in new test development.
Strategic Opportunities
- Point-of-Care Expansion:Developing and commercializing CLIA-based, portable immunoassay systems for decentralized settings like physician offices and outpatient clinics addresses the need for rapid, actionable results.
- Neurodegenerative Disease Diagnostics:The development of novel immunoassays for biomarkers associated with diseases like Alzheimer's and Parkinson's represents a significant, untapped clinical and commercial opportunity.
- Latin American Market Entry:Brazil and Mexico exhibit growing healthcare expenditures and a need to modernize diagnostic capabilities, offering a significant growth runway for established immunoassay platform providers.
Industry Challenges
- Skilled Labor Scarcity:A shortage of qualified medical laboratory scientists and technicians capable of operating and maintaining increasingly complex, high-throughput automated analyzers constrains testing capacity.
- Data Management Complexity:Integrating the massive data output from high-throughput multiplex platforms with existing hospital Laboratory Information Systems (LIS) presents significant technical and interoperability challenges.
- Supply Chain Resilience:The reliance on a concentrated group of suppliers for critical reagents, such as high-affinity monoclonal antibodies and specialized enzymes, creates vulnerability to supply disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunodiagnostics Market |
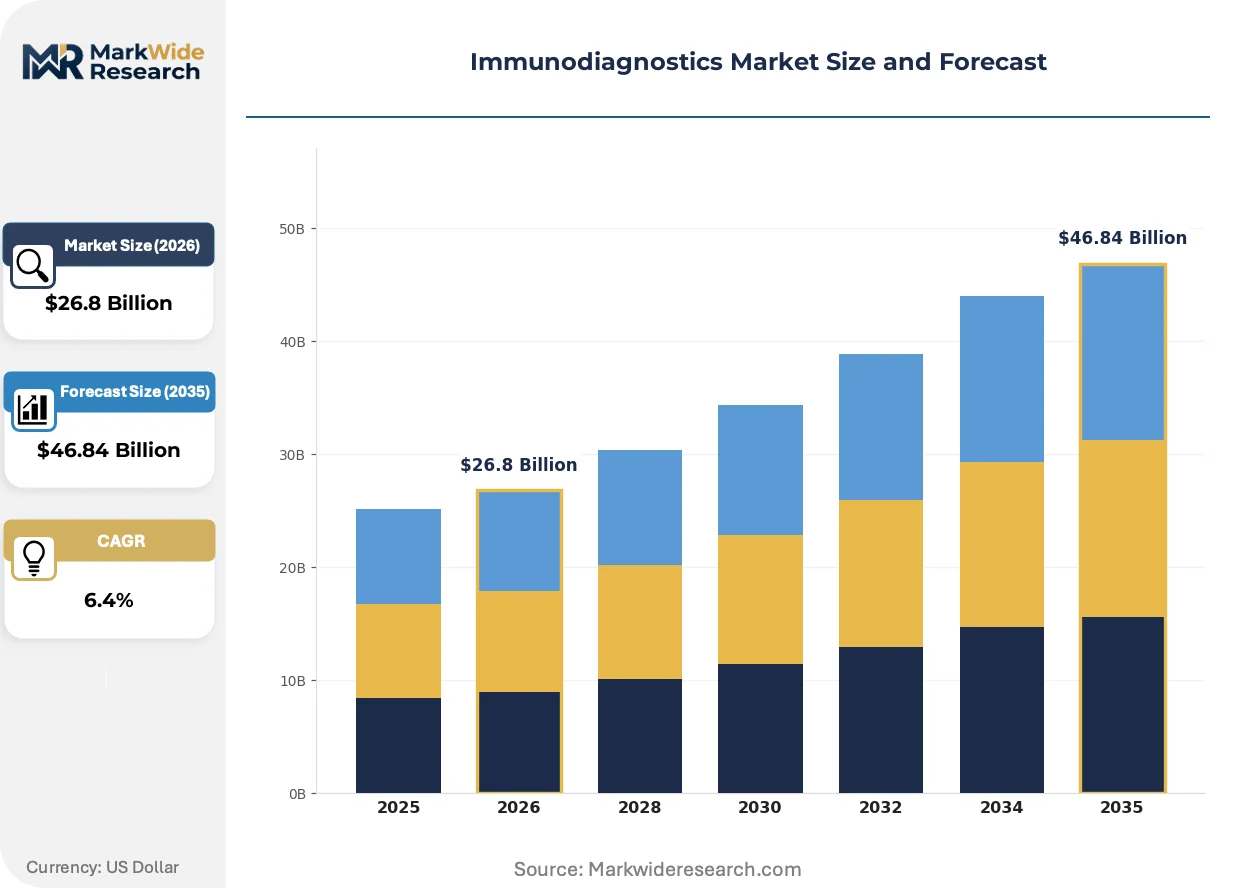
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibody Reagents, Immunoassay Kits, Immunosensors, Diagnostic Instruments, Immunochromatographic Tests Technology: Enzyme-linked Immunosorbent Assay, Chemiluminescence Immunoassay, Fluorescence Immunoassay, Radioimmunoassay, Immunofluorescence Assay Application: Infectious Disease Detection, Autoimmune Disorders, Oncology Screening, Allergy Testing, Transplant Compatibility End User: Diagnostic Laboratories, Research Institutes, Point-of-Care Centers, Blood Banks, Pharmaceutical Companies |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, DiaSorin S.p.A, Thermo Fisher Scientific, Danaher Corporation, Siemens Healthineers, Beckman Coulter, Bio-Rad Laboratories, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunodiagnostics Market Strategic Shifts & Innovations
The convergence of microfluidics with ultrasensitive detection chemistries is enabling a new generation of diagnostic instruments. This evolution is fundamentally altering where and how immunodiagnostic testing is performed, shifting capabilities from centralized facilities to near-patient environments.
Lab-on-a-chip platforms integrate sample processing, reagent mixing, and signal detection onto a single microfluidic cartridge. These systems are seeing rapid evaluation and adoption in point-of-care settings, including emergency departments and specialized clinics. This technology is miniaturizing complex immunoassay protocols, allowing for rapid, automated analysis outside the traditional central laboratory.
Europe's In Vitro Diagnostic Regulation (CE-IVDR) has substantially elevated the requirements for clinical evidence and post-market surveillance. This regulatory shift forces manufacturers to generate more rigorous performance and safety data for all immunoassays sold in the EU. Consequently, companies are dedicating significant resources to compliance, with some legacy products being retired due to the high cost of re-validation.
A notable shift in acquisition models is occurring, with healthcare providers preferring reagent rental agreements over outright capital purchases of large analyzers. This model lowers the upfront financial barrier for laboratories, tying costs directly to testing volume and aligning provider incentives with instrument utilization. The trend is most advanced in the mature diagnostic markets of the United States and Germany.
Immunodiagnostics Market Segmentation
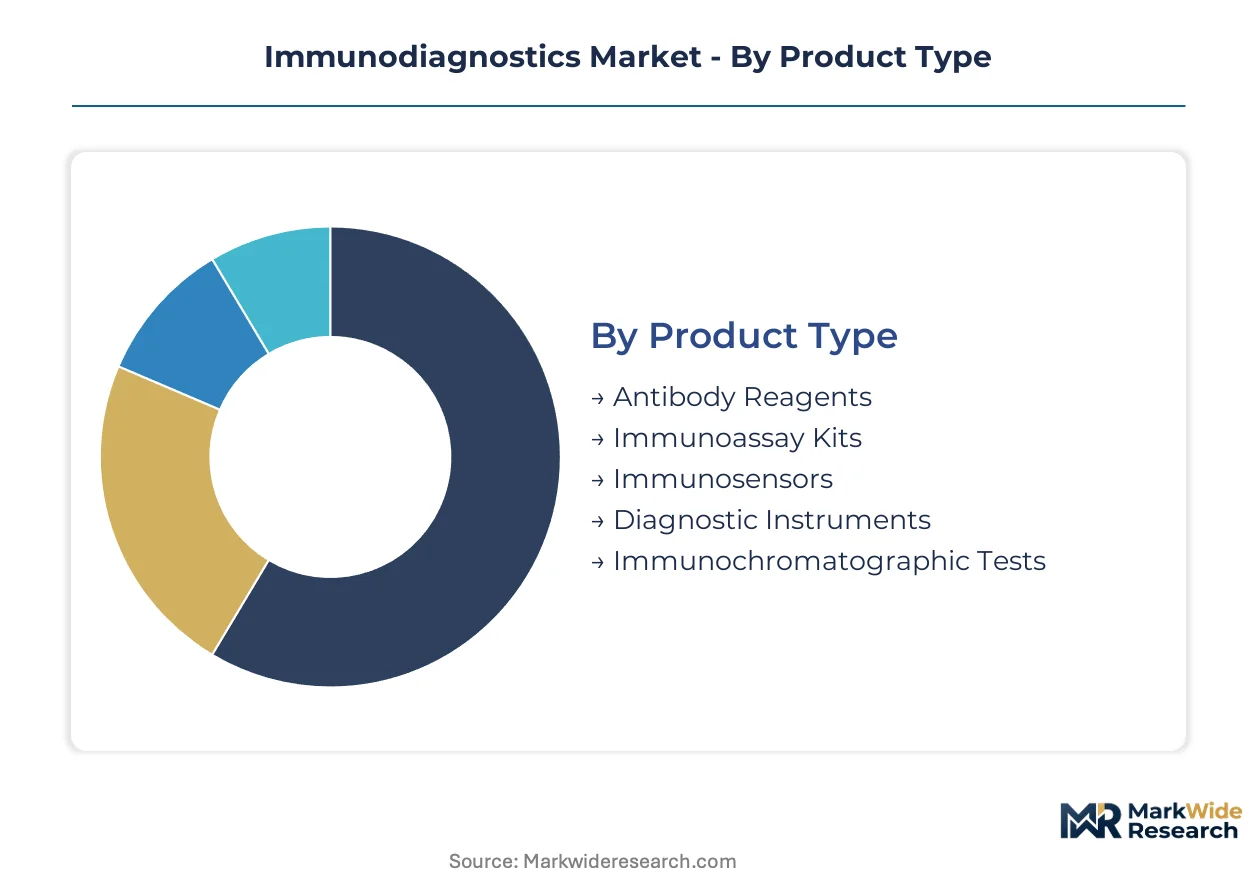
The Immunodiagnostics Market segments across diverse product types, technologies, applications, and end-users. Understanding these divisions reveals varying adoption rates and strategic investment areas. Each segment reflects distinct operational complexities and clinical utility requirements, influencing market development and competitive dynamics.
Product Type:
The market for immunodiagnostics products exhibits a varied geographic footprint, with some components seeing widespread international distribution while others remain more localized in production or primary consumption.
- Immunoassay Kits:These kits contain all necessary reagents for performing specific immunoassay tests, widely adopted in clinical laboratories globally for diverse biomarker detection. Demand concentrates in established healthcare systems like the United States and Germany due to high testing volumes.
- Diagnostic Instruments:Automated and semi-automated systems designed to process immunoassay kits, providing high throughput and standardized results in central laboratories. Asia-Pacific countries, particularly China, are driving significant instrument adoption through infrastructure build-out.
- Antibody Reagents:Purified antibodies and antigens used as critical components in developing and performing various immunodiagnostic assays.
- Immunosensors:Devices integrating biological recognition elements with transducers for real-time, label-free detection of analytes, often used in point-of-care settings.
- Immunochromatographic Tests:Lateral flow assays providing rapid, qualitative or semi-quantitative results, frequently employed for infectious disease screening in resource-limited regions.
Diagnostic Instruments commands the established base. The steepest expansion runs through Immunosensors.
Technology:
Technology segments within immunodiagnostics span a wide maturity spectrum, from established methodologies to advanced, high-sensitivity platforms gaining rapid clinical traction.
- Chemiluminescence Immunoassay:This highly sensitive method uses chemical reactions to emit light, enabling precise quantification of analytes at low concentrations. CLIA platforms are displacing older technologies in central laboratories due to superior analytical performance.
- Enzyme-linked Immunosorbent Assay:ELISA is a well-established, versatile plate-based assay technique for detecting and quantifying soluble substances such as peptides, proteins, antibodies, and hormones. Its cost-effectiveness sustains its use in many diagnostic and research settings.
- Fluorescence Immunoassay:This method employs fluorescent labels for detection, offering high sensitivity and multiplexing capabilities, particularly in automated systems.
- Radioimmunoassay:A highly sensitive immunoassay technique using radioactive isotopes as labels, primarily used for research and specialized clinical applications due to regulatory and safety concerns.
- Immunofluorescence Assay:This technique uses fluorescently labeled antibodies to detect specific antigens in cells or tissues, widely applied in autoimmune disease diagnosis.
ELISA platforms maintain significant market presence. Chemiluminescence Immunoassay systems are capturing increasing share through superior performance.
Application:
Application areas define the clinical utility of immunodiagnostics, ranging from widespread screening programs to specialized disease management protocols.
- Infectious Disease Detection:This segment includes tests for a broad range of pathogens, such as HIV, hepatitis viruses, and respiratory viruses, representing a foundational and high-volume application. Demand remains consistently strong across all global regions due to ongoing public health needs.
- Oncology Screening:Immunodiagnostics for cancer biomarkers aid in early detection, prognosis, and monitoring treatment response, significantly improving patient outcomes. This application is expanding rapidly in developed economies due to aging populations and increased screening initiatives.
- Autoimmune Disorders:Assays designed to detect autoantibodies and other biomarkers associated with conditions like rheumatoid arthritis and lupus.
- Allergy Testing:Immunodiagnostic tests identify specific IgE antibodies to various allergens, assisting in the diagnosis and management of allergic reactions.
- Transplant Compatibility:These tests assess compatibility between donor and recipient tissues, crucial for minimizing rejection in organ transplantation procedures.
Infectious Disease Detection holds the dominant share. Oncology Screening applications are experiencing substantial growth.
End User:
End-user segments reflect diverse operational environments and patient care models, from centralized high-volume testing to decentralized rapid diagnostics.
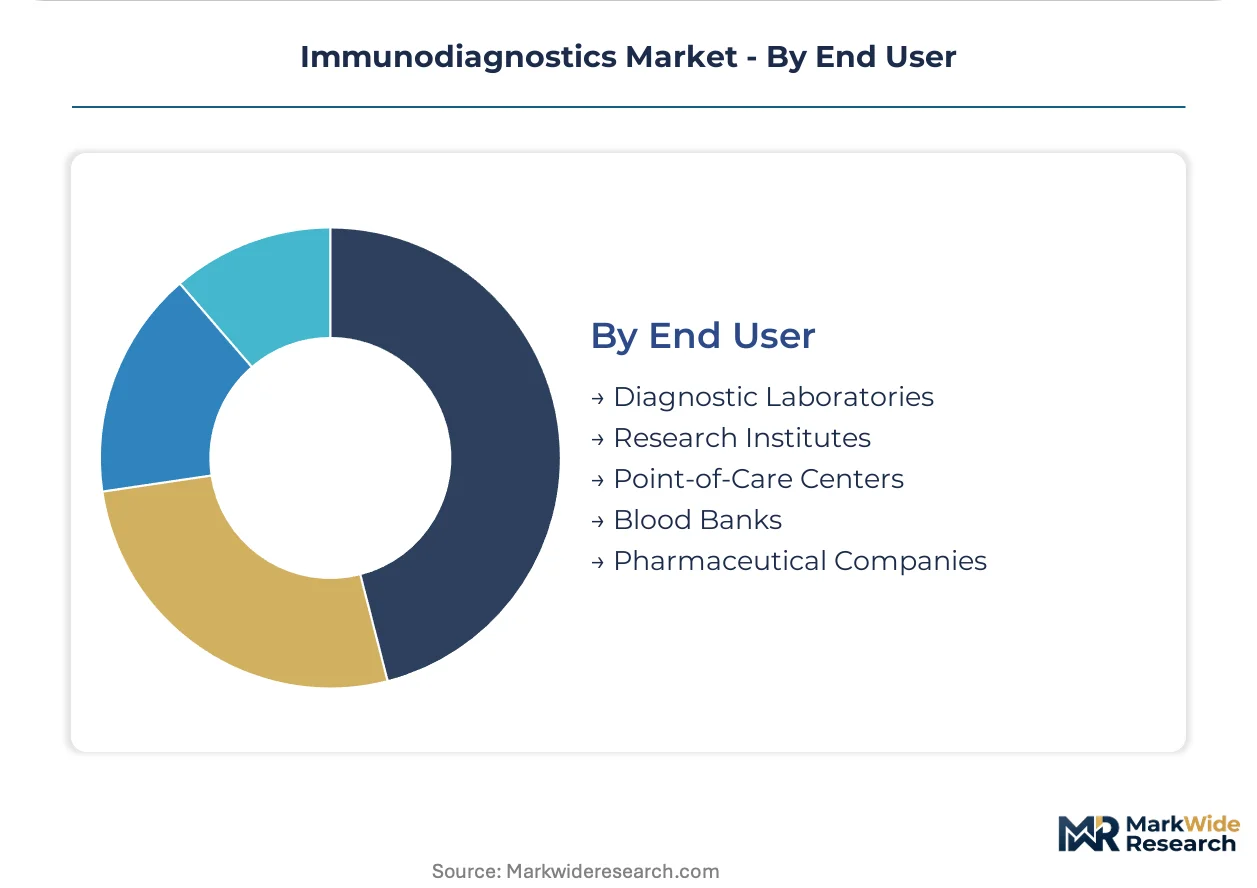
- Diagnostic Laboratories:Centralized facilities equipped with high-throughput automated immunoassay platforms, processing large volumes of samples for various clinical tests. These laboratories form the backbone of diagnostic services in most healthcare systems.
- Point-of-Care Centers:Settings like physician offices, emergency departments, and outpatient clinics where rapid diagnostic tests are performed near the patient, enabling quicker clinical decisions. The push for decentralized testing drives expansion in this segment.
- Research Institutes:Academic and commercial research entities utilizing immunoassays for biomarker discovery, drug development, and disease mechanism studies.
- Blood Banks:Facilities that collect, process, and store blood, relying on immunoassays for screening donated blood for infectious agents.
- Pharmaceutical Companies:Organizations using immunodiagnostics for drug discovery, clinical trials, and companion diagnostics development.
Diagnostic Laboratories represent the largest user base. Point-of-Care Centers are driving significant demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity in the immunodiagnostics market varies significantly across geographies, with established economies exhibiting lower price sensitivity for advanced platforms. Conversely, developing nations often prioritize cost-effectiveness and accessibility in their procurement decisions. This dichotomy shapes regional investment patterns and product adoption strategies. Countries with robust healthcare budgets invest in high-throughput automation.
United States
Demand for oncology screening and high-sensitivity CLIA platforms drives market expansion. The US FDA mandates rigorous clinical performance data for new diagnostic assays. Major biotechnology hubs like Boston and San Francisco foster innovation in novel immunoassay development.
Germany
An aging population and established healthcare infrastructure generate consistent demand for advanced diagnostic instruments. Europe's CE-IVDR system requires extensive post-market surveillance for all in-vitro diagnostics. The Munich region is a significant center for medical technology research and manufacturing.
China
Government investment in diagnostic laboratory infrastructure and public health initiatives fuels substantial demand for automated immunoassay systems. The NMPA regulates market access, emphasizing local production and technology transfer. Shanghai's biomedical industry cluster attracts significant investment in diagnostic manufacturing.
Japan
An emphasis on early disease detection and an aging demographic sustain demand for sophisticated immunodiagnostic technologies. The PMDA oversees product approvals, focusing on safety and efficacy for medical devices. Tokyo's research institutions collaborate on advanced biomarker discovery and assay development.
Brazil
Growing healthcare expenditures and a need to modernize diagnostic capabilities expand the addressable market for immunoassay platform providers. ANVISA regulates diagnostic products, aiming to improve public health standards. São Paulo hosts a developing medical device industry with increasing local manufacturing capabilities.
Immunodiagnostics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the immunodiagnostics market, creating a dynamic competitive environment. The landscape features a mix of established multinational corporations and specialized diagnostic firms operating across various scales. These entities can be broadly categorized into integrated diagnostics providers, high-throughput automation specialists, and point-of-care solution innovators, each pursuing distinct market penetration strategies. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants seeking to expand their presence and capabilities.
Integrated diagnostics providers, exemplified by F. Hoffmann-La Roche Ltd, leverage their broad portfolios across pharmaceuticals and diagnostics to offer comprehensive solutions for patient management. Abbott occupies a strong position in infectious disease testing and point-of-care solutions, representing a focus on decentralized diagnostics and rapid results in diverse clinical settings. Siemens Healthineers, a German-based entity, anchors the high-throughput central laboratory automation segment with its large-scale platforms, serving the needs of major diagnostic laboratories globally and emphasizing operational efficiency.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| DiaSorin S.p.A |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens Healthineers |
| Beckman Coulter |
| Bio-Rad Laboratories |
| QIAGEN |
Cost & Logistics Intelligence
Reagent rental agreements, a prevalent contract structure in immunodiagnostics, lock in both instrument supply and predictable testing costs for laboratories. This model aligns manufacturer revenue with instrument utilization, shifting capital expenditure to operational expenditure.
Pricing Analysis
Europe's CE-IVDR system dictates the pricing tier structure for new immunodiagnostic assays, requiring extensive validation that increases development costs. Hybrid pricing models, combining instrument placement with per-test reagent fees, are common. Price differentiation stems from assay sensitivity and regulatory approval status. Pricing softness runs through mature ELISA platforms due to generic competition. Diagnostic laboratories exhibit lower price sensitivity for high-throughput CLIA systems, while point-of-care centers prioritize cost-effectiveness for rapid tests.
Supply Chain Analysis
Container availability issues on key trans-Pacific trade lanes impact the timely delivery of automated immunoassay platforms. Supply concentration for critical reagents, such as high-affinity monoclonal antibodies and specialized enzymes, centers in the United States and Germany. The industry depends on these specialized biological inputs, creating single-source vulnerability for some manufacturers. Distribution runs through a network of direct sales forces and specialized medical device distributors to diagnostic laboratories and point-of-care centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunodiagnostics market requires a strategic substitution defense as incumbents navigate the threat of advanced molecular diagnostics. Nucleic acid amplification tests (NAATs) offer a higher sensitivity alternative for some infectious disease detection, challenging traditional immunoassay dominance.
For Market Incumbents: Fortify core market share through continuous investment in high-sensitivity CLIA platforms and multiplexed assays. Acquire smaller firms specializing in microfluidics to counter the threat from lab-on-a-chip technologies. Leverage vertical integration into critical reagent manufacturing to mitigate supply chain disruptions. Prioritize R&D in neurodegenerative disease biomarkers, expanding beyond traditional infectious disease and oncology applications.
For New Entrants and Emerging Players: Anchor in underserved point-of-care settings with portable, CLIA-based immunoassay systems. Target the Latin American market, specifically Brazil and Mexico, due to growing healthcare expenditures and modernization needs. The most penetrable application remains rapid infectious disease screening in decentralized environments. A direct-to-clinic sales model, emphasizing ease of use and rapid results, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated diagnostics providers offering comprehensive instrument and reagent contracts. Long-term viability rests on platforms adaptable to emerging biomarker discovery and personalized medicine. Acquisition targets should include specialists in novel immunosensor technologies or advanced data analytics for diagnostic insights. The signal to watch is regulatory approval of new neurodegenerative disease biomarkers, indicating a significant market expansion opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Acceleration | Expedites market access for novel assays under stringent regulatory frameworks like CE-IVDR. |
| Point-of-Care Platform Development | Captures demand for rapid, decentralized testing in physician offices and emergency departments. |
| Multiplexed Assay Integration | Enhances diagnostic efficiency by simultaneously detecting multiple analytes from a single patient sample. |
| Supply Chain Diversification | Reduces vulnerability to critical reagent shortages and geopolitical trade disruptions. |
| Strategic Partnerships with Pharma | Facilitates co-development of companion diagnostics for new therapeutic drugs. |
Research Approach
A spread of perspectives from laboratory directors, R&D scientists, regulatory affairs specialists, and hospital procurement managers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were validated against extensive secondary research. Secondary sources included US FDA guidance documents, Europe's CE-IVDR technical specifications, NMPA product registrations, and medical technology association reports. This approach ensured robust bottom-up and top-down triangulation of market data.
Market segmentation dimensions modeled included product type, technology, application, end-user, and key regional healthcare expenditures. The analytical framework projected demand across the analysis window by correlating historical growth with future technological adoption rates. Compound Annual Growth Rates were derived from a weighted average of segment-specific expansion trajectories. Forecast inputs integrated public health spending trends and new biomarker discovery rates for oncology.
Material uncertainties — including unforeseen pandemics or significant shifts in global trade policies — sit outside the modeled envelope. Forecasts reflect assumptions regarding consistent regulatory pathways and sustained investment in diagnostic infrastructure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Glucose Biosensors Market