
 Hepatitis B Diagnostic Tests Market | 2026-2036
Hepatitis B Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis B Diagnostic Tests Market Outlook
Hospital laboratories are unwinding their historical dominance over hepatitis B testing volumes as blood banks and diagnostic centers gain procurement share. Abbott Laboratories leverages its integrated immunoassay platform to sustain dominance in high-throughput laboratory settings. Bio-Rad Laboratories specializes in blood screening nucleic acid testing, occupying a defensible position in transfusion safety workflows. Siemens Healthineers competes through automated analyzer ecosystems that extend workflow efficiency across hospital networks.
Hepatitis B diagnostic tests detect viral antigens, antibodies, or nucleic acid sequences in human serum or plasma samples, typically requiring sensitivity thresholds below 0.05 IU/mL for nucleic acid amplification methods to meet transfusion safety standards. These tests serve commercial purposes spanning clinical diagnosis, blood donor screening, and epidemiological surveillance. Molecular tests powered by PCR technology are capturing the fastest expansion as laboratories upgrade from serological to nucleic acid confirmation protocols. ELISA-based serological tests retain the largest volume base but face margin compression from commoditization in price-sensitive procurement environments.
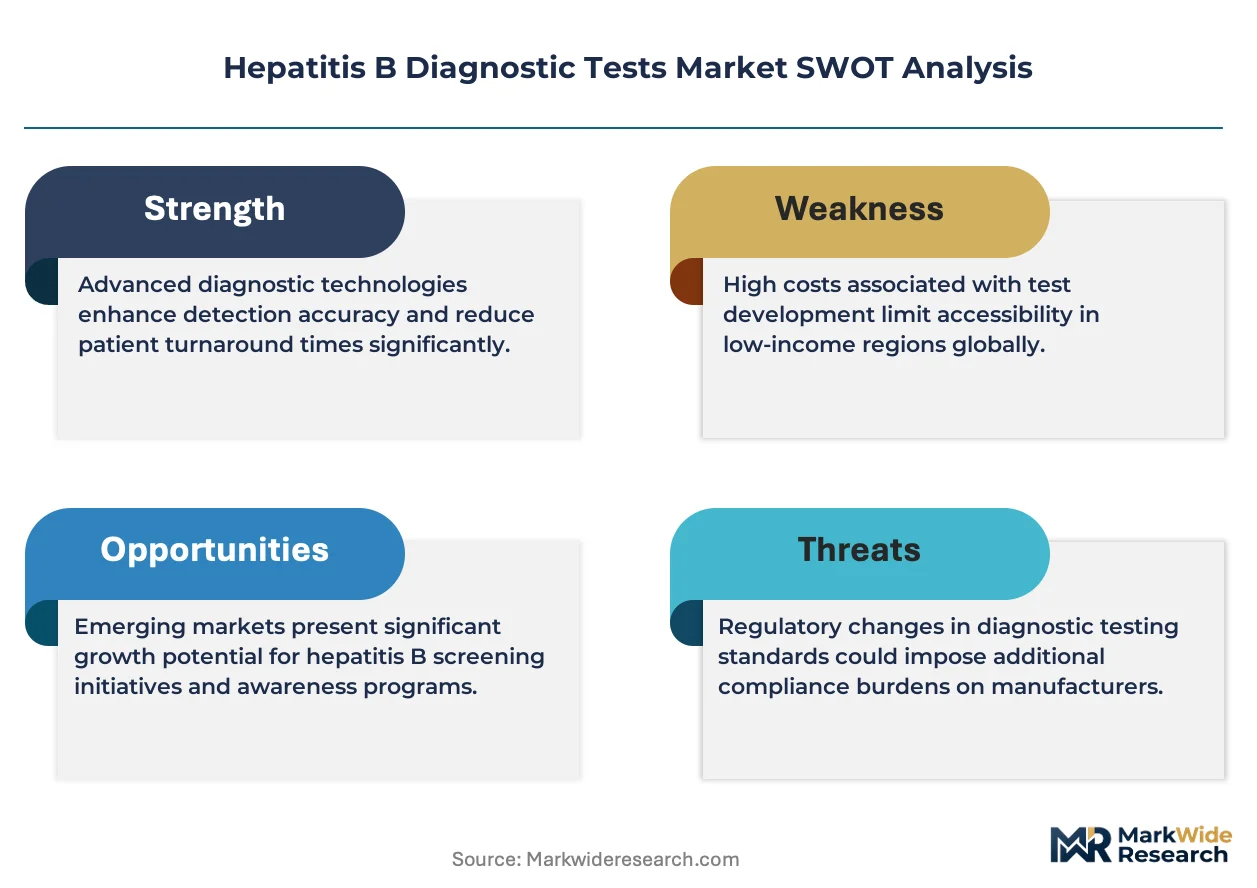
FDA blood screening regulations and WHO prequalification standards shape product approval pathways and eligibility for public health procurement tenders across multiple geographies. EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for CE-marked hepatitis B assays entering European distribution channels. China's NMPA and India's CDSCO maintain distinct approval frameworks that delay market access for multinational manufacturers lacking local clinical trial data. Stakeholders must monitor evolving nucleic acid testing mandates in blood safety protocols and calibrate R&D investment between automated laboratory platforms and decentralized point-of-care formats.
Market Dynamics
Nucleic acid testing technology is compressing serological test margins as blood banks and transfusion centers mandate PCR-based confirmation protocols for donor screening safety standards.
Growth Catalysts
- WHO prequalification standards:Blood banks in emerging economies prioritize WHO-prequalified assays for procurement eligibility, expanding addressable demand for certified manufacturers.
- Transfusion safety protocols:Regulatory bodies across multiple geographies now mandate nucleic acid testing for blood donor screening, creating replacement demand from legacy ELISA workflows.
- China, India, Brazil cluster:These three markets concentrate hepatitis B burden and diagnostic infrastructure investment, driving volume expansion for localized test distribution.
Market Restraints
- Reagent cost volatility:PCR master mixes and proprietary enzymes face input cost pressure from concentrated specialty chemical suppliers in Germany and Switzerland.
- Regulatory friction:China's NMPA and India's CDSCO require local clinical trial data for approval, delaying market access for manufacturers lacking regional study infrastructure.
- Technical limitation:Point-of-care nucleic acid platforms struggle to achieve sub-0.05 IU/mL sensitivity thresholds without laboratory-grade thermal cycling equipment.
Strategic Opportunities
- Brazil's public health expansion:ANVISA regulatory harmonization with WHO standards creates procurement pathway for prequalified molecular diagnostics in national blood programs.
- Decentralized testing convergence:Isothermal amplification technologies paired with smartphone-connected readers enable clinic-based nucleic acid testing outside centralized laboratories.
- EMA MDR transition:Stricter clinical evidence requirements for CE-marked assays create competitive moat for manufacturers with robust performance documentation.
Industry Challenges
- Molecular diagnostics skill gap:Laboratory technicians require specialized training in nucleic acid extraction, contamination control, and amplification curve interpretation.
- Instrument-platform lock-in:Closed-system analyzer ecosystems create switching costs for blood banks seeking to migrate between competing automated platforms.
- Legacy serology integration:Hospital laboratories face workflow friction when layering molecular confirmation testing atop existing ELISA-based screening infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis B Diagnostic Tests Market |
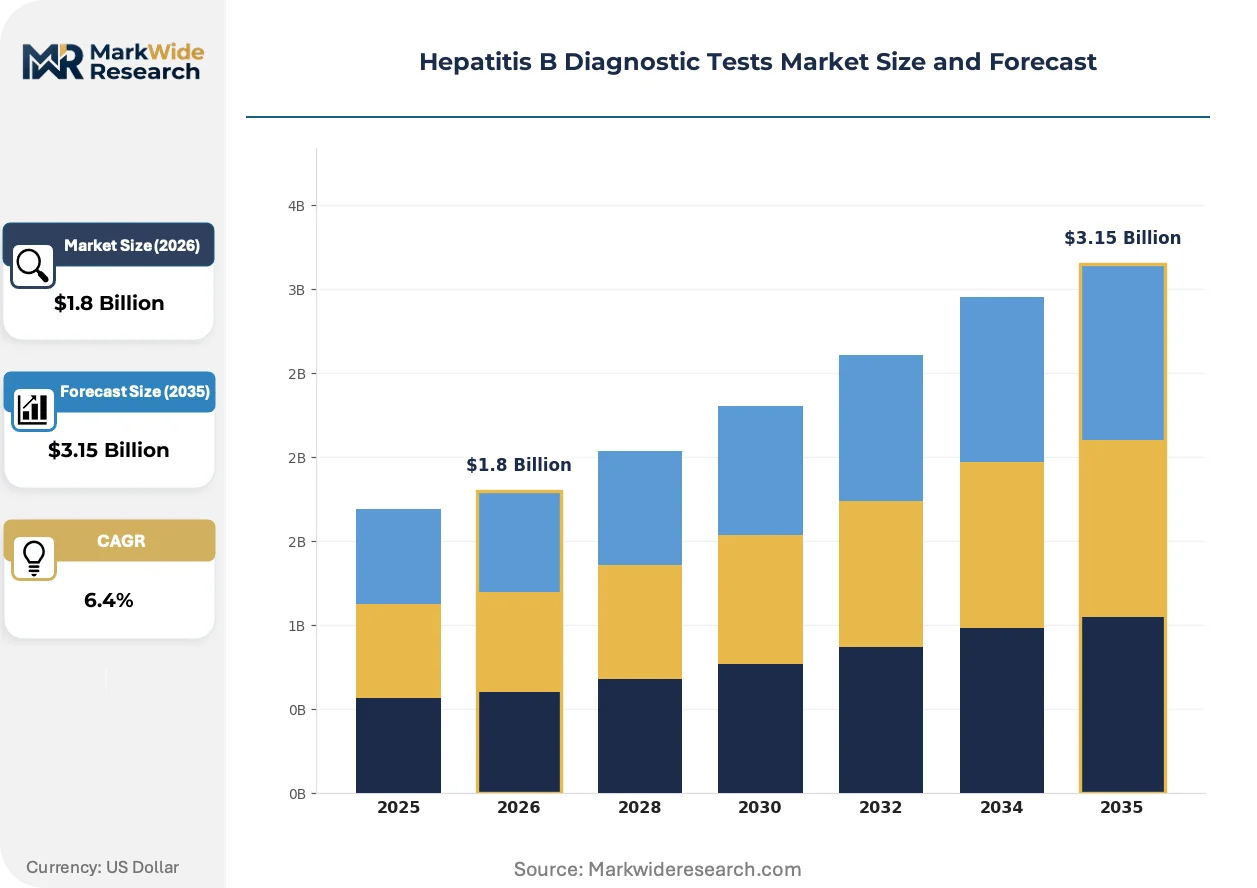
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serological Tests, Molecular Tests, Rapid Tests, Point-of-Care Tests Technology: ELISA, PCR, Lateral Flow, Hybrid Capture Application: Blood Screening, Laboratory Testing, Home Testing, Diagnostic Centers End User: Clinics, Hospitals, Blood Banks, Research Laboratories |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Siemens Healthineers, Bio-Rad Laboratories, DiaSorin, bioMérieux, QIAGEN, Hologic, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis B Diagnostic Tests Market Strategic Shifts
Automation and miniaturization are reconfiguring hepatitis B diagnostic workflows, compressing turnaround times while expanding test access beyond centralized laboratory settings.
Digital PCR platforms are supplanting quantitative real-time PCR as the reference standard for viral load monitoring in transplant centers and specialized hepatology units. These systems partition samples into thousands of micro-reactions, enabling absolute quantification without standard curve dependency. Blood banks in Japan and South Korea are adopting digital PCR for resolved sample discrepancies, compressing confirmatory testing timelines from days to hours.
EMA's In Vitro Diagnostic Regulation now enforces stricter clinical evidence requirements for hepatitis B assays seeking CE marking, mandating expanded analytical and clinical validation studies. Manufacturers must demonstrate performance across diverse epidemiological populations, elevating documentation costs for market entry. European hospital laboratories are prioritizing suppliers with established MDR technical files, consolidating procurement around compliant vendors.
Blood bank procurement committees now unbundle instrument placement from reagent supply contracts, reversing historical bundled pricing structures. Diagnostic centers in India and Brazil negotiate standalone reagent pricing after initial analyzer installation, compressing supplier margins on consumables. This disintermediation is most visible in public tender environments where transparency mandates require line-item cost disclosure.
Hepatitis B Diagnostic Tests Market Segmentation
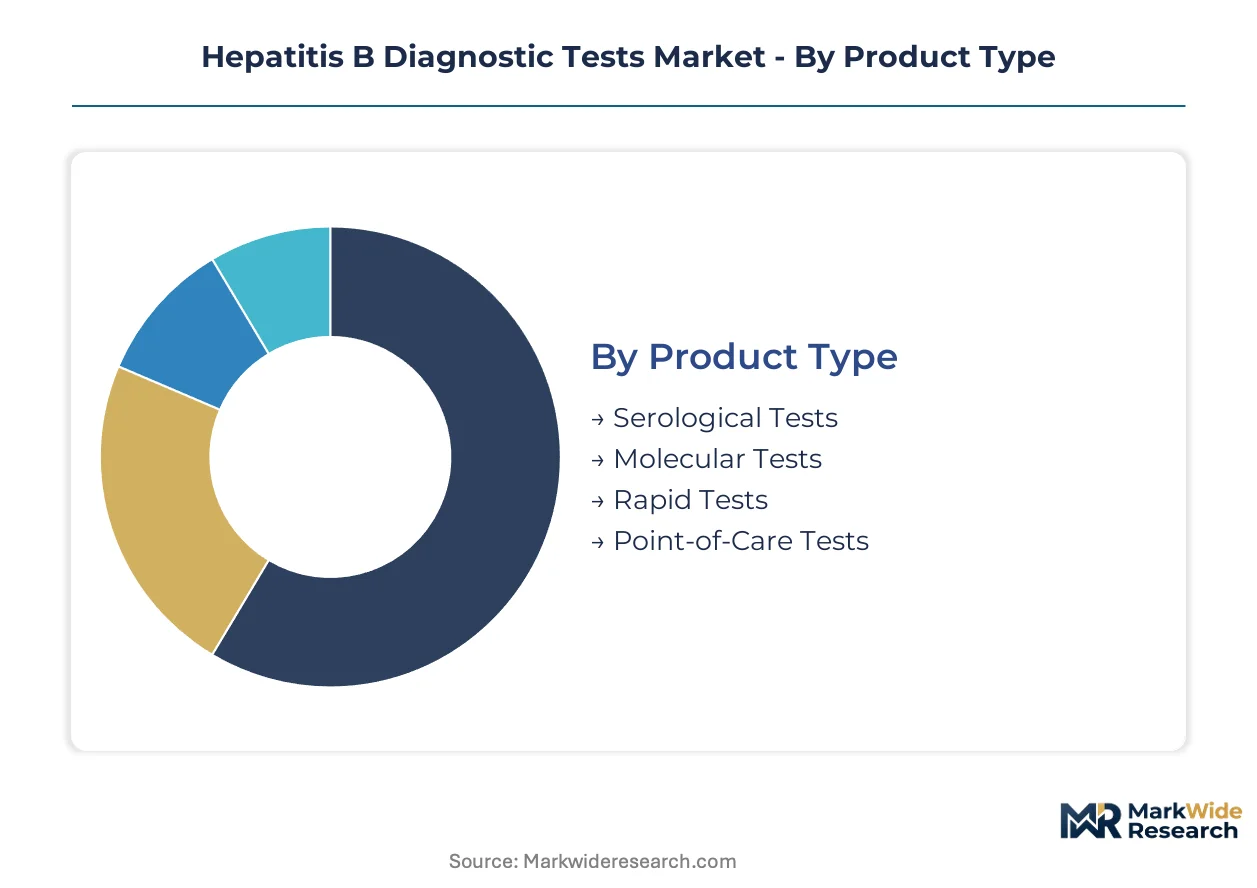
Segmentation in hepatitis B diagnostics reveals how regulatory requirements and testing workflows fragment procurement decisions across different buyer archetypes. Blood banks, hospital laboratories, and decentralized clinics each demand distinct performance specifications, sensitivity thresholds, and automation capabilities that reshape vendor positioning.
Product Type:
Regulatory differentiation separates serological assays from molecular platforms through WHO prequalification pathways and transfusion safety mandates.
- Serological Tests:ELISA-based immunoassays detect hepatitis B surface antigens and antibodies in serum or plasma samples. Blood banks in India and Brazil deploy these for initial donor screening before nucleic acid confirmation. Sensitivity limitations below 0.05 IU/mL are driving replacement demand in high-safety environments.
- Molecular Tests:PCR and nucleic acid amplification technologies identify viral DNA with quantitative precision. Blood banks across China mandate these for donor screening compliance with national transfusion safety protocols. Digital PCR platforms are displacing real-time PCR in specialized hepatology centers requiring absolute viral load quantification.
- Rapid Tests:Lateral flow immunochromatographic assays deliver results within 15-20 minutes without laboratory infrastructure.
- Point-of-Care Tests:Isothermal amplification technologies paired with portable readers enable nucleic acid detection outside centralized laboratories.
Serological tests handle the majority of throughput; molecular tests are the fastest mover on share.
Technology:
Cost tier stratification aligns with automation intensity and reagent complexity across laboratory workflows.
- ELISA:Enzyme-linked immunosorbent assays dominate high-volume screening with established automation on integrated analyzer platforms. Hospital laboratories in Brazil rely on ELISA for cost-efficient batch processing despite margin compression from commoditized reagent pricing.
- PCR:Polymerase chain reaction amplification achieves sub-0.05 IU/mL sensitivity required for blood donor safety standards. Blood banks in China and South Korea are upgrading from serological to PCR-based confirmation protocols under regulatory mandates.
- Lateral Flow:Immunochromatographic strips enable visual result interpretation without instrumentation.
- Hybrid Capture:Signal amplification technology bridges sensitivity gaps between serology and PCR for medium-complexity laboratories.
ELISA commands the highest absolute volumes; PCR is climbing the fastest on procurement share.
Application:
Customer type fragmentation separates centralized laboratory buyers from decentralized screening programs with divergent throughput requirements.
- Blood Screening:Donor testing protocols demand the most stringent sensitivity thresholds and regulatory documentation. Blood banks across China, India, and Brazil concentrate procurement volume for nucleic acid testing platforms under WHO prequalification standards.
- Laboratory Testing:Hospital and reference laboratories perform diagnostic confirmation and viral load monitoring. Automated analyzer ecosystems in Japan and South Korea integrate hepatitis B assays into broader infectious disease testing workflows.
- Home Testing:Self-collection kits with mail-in laboratory processing expand access beyond clinical settings.
- Diagnostic Centers:Independent testing facilities compete on turnaround time and pricing for routine screening.
Blood screening concentrates the highest-value procurement; home testing is gaining share fastest among non-clinical channels.
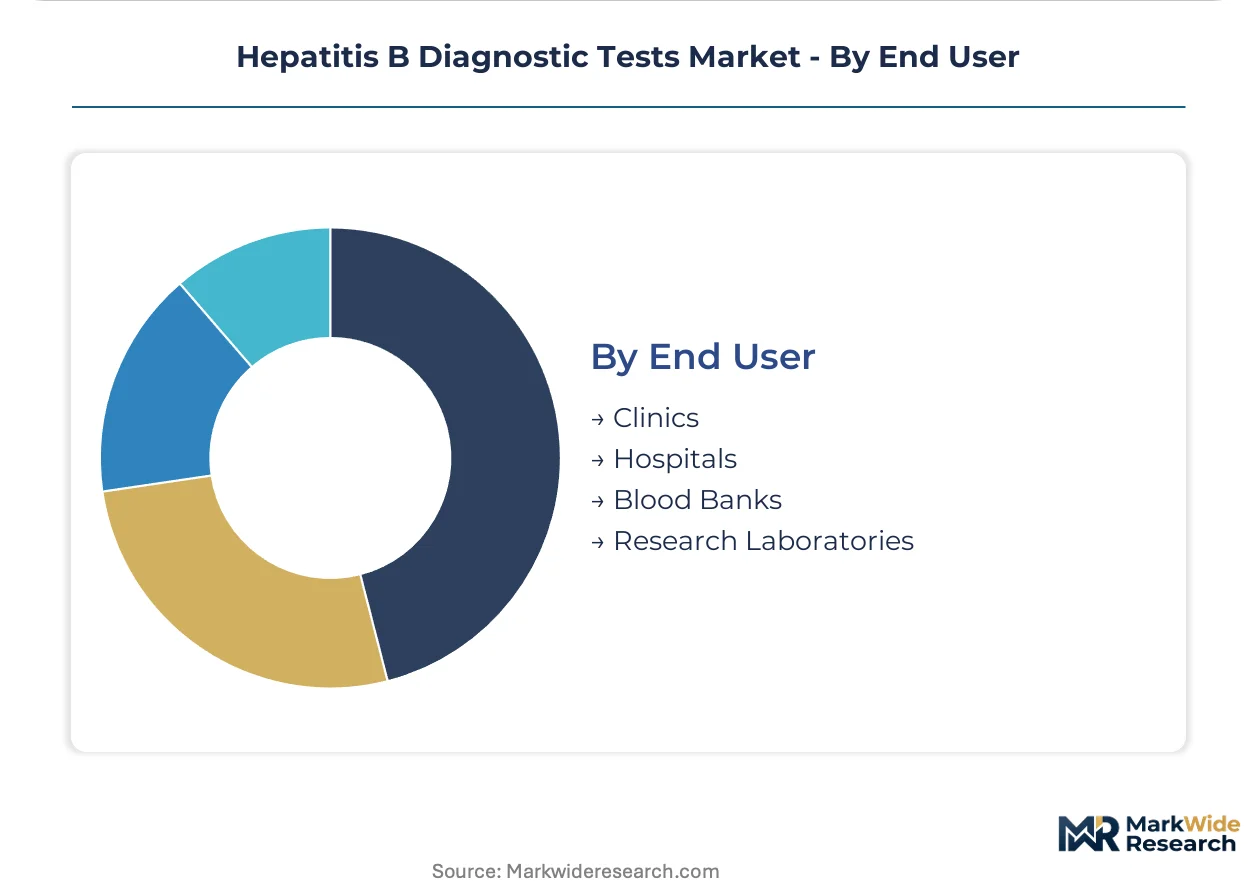
End User:
Supply concentration among blood safety programs creates procurement leverage distinct from clinical diagnostic workflows.
- Blood Banks:National transfusion services aggregate the largest test volumes with standardized procurement specifications. China's centralized blood management system and Brazil's ANVISA-regulated programs mandate nucleic acid testing technology upgrades.
- Hospitals:Integrated health networks prioritize automated analyzer platforms that consolidate hepatitis B testing with broader infectious disease menus. Siemens Healthineers and Abbott Laboratories compete through ecosystem lock-in across hospital procurement committees.
- Clinics:Primary care facilities require rapid turnaround for patient management decisions.
- Research Laboratories:Academic and pharmaceutical research programs drive demand for novel biomarker assays and digital PCR quantification.
Blood banks dominate procurement scale; clinics are expanding fastest as decentralized testing infrastructure deploys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blood banks concentrate procurement volume in China, India, and Brazil as these markets expand nucleic acid testing infrastructure for transfusion safety compliance. Diagnostic infrastructure investment flows toward markets with high hepatitis B prevalence and evolving regulatory mandates.
China
China's centralized blood management system aggregates the largest national test volumes for hepatitis B screening among emerging economies. NMPA mandates nucleic acid testing protocols for all donor blood units, driving replacement demand from legacy serological workflows. Beijing and Shanghai house the primary reference laboratories validating molecular diagnostic platforms for national distribution.
India
India's blood bank network spans over 3,000 licensed centers requiring upgraded screening technology under CDSCO guidance. CDSCO requires local clinical trial data for assay approval, delaying market access for manufacturers lacking regional study infrastructure. Maharashtra and Gujarat concentrate private diagnostic chains investing in automated analyzer platforms.
Brazil
Brazil's ANVISA-regulated national blood program mandates nucleic acid testing alignment with WHO prequalification standards. ANVISA regulatory harmonization creates procurement pathways for prequalified molecular diagnostics in public health expansion. São Paulo and Rio de Janeiro anchor the southeastern industrial corridor where transfusion service consolidation accelerates.
United States
United States hospital laboratories sustain demand for integrated immunoassay platforms serving diagnostic confirmation and viral load monitoring. FDA blood screening regulations enforce stringent sensitivity thresholds for nucleic acid amplification methods in donor testing. The Boston-Cambridge biotechnology cluster and San Diego research corridor drive digital PCR platform development for specialized hepatology applications.
Germany
German hospital networks prioritize automated analyzer ecosystems consolidating hepatitis B testing within broader infectious disease menus. EMA's In Vitro Diagnostic Regulation enforces expanded clinical validation requirements for CE-marked assays entering European distribution. The Rhine-Ruhr industrial region and Munich metropolitan area concentrate reference laboratories adopting digital PCR for absolute viral load quantification.
Hepatitis B Diagnostic Tests Market Competitive Environment
Player mix skews toward diversified diagnostics conglomerates with integrated platform ecosystems rather than standalone assay specialists. Market structure concentrates procurement influence among blood bank networks and hospital laboratory chains with standardized specifications. Strategic archetypes divide between automated platform vendors, nucleic acid testing specialists, and rapid point-of-care developers. Competitive moves center on analyzer placement contracts with reagent supply lock-in and regulatory prequalification certification for emerging market tenders.
Among diversified diagnostics conglomerates, Abbott Laboratories, F. Hoffmann-La Roche, and Siemens Healthineers occupy positions exemplifying the automated platform archetype. These entities represent the scale-driven tier where instrument ecosystem integration determines procurement committee decisions. Nucleic acid testing specialists such as Bio-Rad Laboratories and QIAGEN sit within a distinct tier focused on molecular workflow solutions for transfusion safety applications. The competitive terrain rewards manufacturers balancing high-throughput laboratory automation with emerging market accessibility under WHO prequalification pathways.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| DiaSorin |
| bioMérieux |
| QIAGEN |
| Hologic |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification standards simultaneously gate supplier eligibility and stratify price tiers across hepatitis B diagnostic procurement, compressing margins for uncertified manufacturers while embedding certification premiums into contract structures. Blood bank tenders in China, India, and Brazil now unbundle instrument placement from reagent supply, forcing standalone pricing transparency that erodes historical bundled-margin capture.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate reagent supply agreements between blood banks and molecular diagnostics suppliers. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified PCR platforms from CE-marked mid-tier systems and unbranded ELISA consumables. Cost compression in standard-tier serological reagents is intensifying because Indian and Brazilian procurement committees now mandate line-item cost disclosure in public tenders. Blood banks exhibit the highest price sensitivity due to volume aggregation and regulatory compliance mandates, while research laboratories demonstrate the lowest sensitivity given digital PCR's irreplaceable quantification precision.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints on transpacific routes are elevating inbound logistics costs for thermal cycler instruments and PCR master mix components. Supply concentrates in Germany, Switzerland, and the United States for specialty enzymes and fluorescent probe chemistries; China and South Korea for analyzer hardware fabrication. Raw material dependencies center on Taq polymerase enzymes, oligonucleotide primers, and optical-grade plastics for microplate manufacturing. Single-source vulnerability in German and Swiss specialty chemical suppliers creates concentration risk for nucleic acid test reagent production. Distribution runs through regional diagnostic distributors with cold-chain capabilities, consolidating around blood bank networks and hospital laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hepatitis B diagnostics operates as a defensive-moat market where regulatory entrenchment—specifically WHO prequalification and national blood safety mandates—creates durable switching costs that protect incumbent positions against price-based disruption.
For Market Incumbents: Consolidate analyzer ecosystem lock-in through extended service contracts and reagent supply exclusivity clauses that raise migration costs for blood banks. Prioritize certification investment in Brazil's ANVISA harmonization pathway and India's CDSCO clinical trial infrastructure to preempt emerging entrant access. Vertical integration into specialty enzyme production reduces exposure to German and Swiss supplier concentration. For New Entrants and Emerging Players: Differentiate on isothermal amplification platforms that bypass thermal cycler infrastructure requirements for clinic-based deployment. Target decentralized diagnostic centers in India's Maharashtra and Gujarat corridors where automated analyzer penetration remains incomplete. Pursue white-label manufacturing partnerships with established distributors to circumvent direct regulatory approval timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-care molecular diagnostics as smartphone-connected reader platforms reduce instrument placement costs. Viability over the five-to-ten-year horizon hinges on regulatory prequalification portfolio breadth rather than single-assay dominance. Acquisition targets should display established WHO prequalification dossiers and emerging market tender track records. The signal to watch is ANVISA regulatory harmonization velocity with WHO standards as a proxy for Brazilian public health procurement accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks tender eligibility in China, India, and Brazil blood bank procurement. |
| Isothermal Amplification Platform Launch | Enables clinic-based nucleic acid testing outside centralized laboratory infrastructure. |
| Reagent Supply Contract Unbundling | Responds to transparency mandates in Indian and Brazilian public tender environments. |
| Digital PCR Reference Standard Adoption | Captures transplant center and hepatology unit viral load monitoring demand in Japan and South Korea. |
| Specialty Enzyme Backward Integration | Reduces input cost volatility from concentrated German and Swiss chemical suppliers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with blood bank procurement directors, hospital laboratory managers, diagnostic distributor executives, and regulatory affairs specialists; and secondary validation through WHO prequalification listings, FDA blood screening guidance documents, NMPA approval databases, and CDSCO clinical trial registries. Bottom-up triangulation across instrument placement records and reagent consumption estimates converged with top-down market sizing from national transfusion service reports.
Across the analysis window, forecasts model product type segmentation between serological and molecular platforms, technology tier stratification across ELISA and PCR modalities, and application fragmentation among blood screening, laboratory testing, and point-of-care deployment. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation timelines and blood safety protocol upgrade cycles. Forecast inputs incorporate nucleic acid testing mandate adoption curves and digital PCR platform displacement rates in specialized hepatology centers.
The analysis sits within stated boundaries; outcomes outside sustained WHO prequalification pathway access and stable specialty chemical supply from German and Swiss manufacturers would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization velocity and blood bank infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Semen Analysis Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Antibody Testing Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Antigen Skin Test Market