
 Lower Respiratory Tract Infection Treatment Market | 2026-2036
Lower Respiratory Tract Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lower Respiratory Tract Infection Treatment Market Foresight
Hospital procurement for lower respiratory tract infection therapies is pivoting from volume-based purchasing toward outcome-linked contracts that reward reduced readmission rates. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum antibiotics across integrated delivery networks. GlaxoSmithKline plc anchors its position through inhaled corticosteroid portfolios that dominate respiratory formularies. AstraZeneca plc differentiates via biologic-antibiotic combinations targeted at resistant Pseudomonas infections.
Lower respiratory tract infection treatment encompasses pharmaceutical interventions targeting pneumonia, bronchitis, and bronchiolitis, with formulations typically combining beta-lactam antibiotics, macrolides, or neuraminidase inhibitors engineered for alveolar penetration and sustained pulmonary deposition. The primary purpose is to reduce mortality from acute bacterial and viral lung infections while preventing progression to sepsis or respiratory failure. Antibiotics occupy the largest revenue share within product type segmentation, though antivirals represent the fastest-expanding margin pool as novel polymerase inhibitors gain formulary access. Inhalation delivery commands premium positioning due to direct lung targeting and reduced systemic toxicity, while intravenous administration retains dominance in intensive care settings where bioavailability demands override convenience considerations.
FDA antimicrobial development incentives and EMA's PRIME designation framework accelerate market entry for therapies addressing resistant pathogens, compressing traditional review timelines. WHO Essential Medicines List revisions and national stewardship mandates in Germany and Japan restrict empirical broad-spectrum use, redirecting demand toward pathogen-directed diagnostics and narrow-spectrum alternatives. Stakeholders must monitor evolving resistance surveillance data and payer willingness to reimburse premium therapies against generic backbone regimens.
Market Dynamics
Hospital procurement contracts for lower respiratory therapies now tie payment to measurable patient outcomes rather than treatment volume, forcing manufacturers to demonstrate reduced readmission rates and shorter intensive care stays.
Growth Catalysts
- FDA antimicrobial development incentives:The FDA's Qualified Infectious Disease Product designation compresses review timelines for novel antivirals targeting resistant Pseudomonas strains. Manufacturers gain priority review vouchers and extended market exclusivity.
- Japan's elderly pneumonia burden:Japan's aging demographic generates concentrated demand for nebulized biologics in long-term care facilities. METI reimbursement reforms favor pathogen-directed therapy over empirical broad-spectrum regimens.
- Polymerase inhibitor platforms:Next-generation neuraminidase inhibitors engineered for alveolar penetration are displacing legacy oral antivirals in German hospital formularies. Direct lung targeting reduces systemic toxicity profiles.
Market Restraints
- Active pharmaceutical ingredient concentration:Beta-lactam antibiotic precursors concentrate in Chinese manufacturing clusters. Supply disruptions propagate through integrated delivery networks within 60-90 days.
- EMA stewardship mandates:The EMA's restricted empirical broad-spectrum use guidelines reduce volume pull for legacy macrolide combinations. Narrow-spectrum alternatives require companion diagnostic infrastructure.
- Generic backbone erosion:Patent-expired cephalosporins and penicillins commoditize standard-of-care pneumonia treatment. Premium-priced biologics face reimbursement resistance without mortality benefit demonstration.
Strategic Opportunities
- India's underpenetrated nebulized delivery:India's tier-two hospital networks lack respiratory therapy infrastructure. Partnerships with domestic distributors unlock volume in bronchitis and bronchiolitis segments.
- Biologic-antibiotic convergence:Monoclonal antibody combinations targeting resistant gram-negative pathogens address unmet need in ventilator-associated pneumonia. Development partnerships compress clinical trial timelines.
- EMA PRIME designation acceleration:The PRIME framework grants early and enhanced dialogue access for therapies addressing antimicrobial resistance. Eligible products receive accelerated assessment and conditional marketing authorization pathways.
Industry Challenges
- Respiratory formulation expertise scarcity:Pulmonary drug delivery engineering requires specialized aerosol science capabilities. Pharmaceutical manufacturers compete with medical device firms for limited talent pools in Germany and the United States.
- Companion diagnostic integration complexity:Pathogen-directed therapy deployment demands real-time PCR and rapid antigen testing infrastructure. Hospital laboratory capital constraints delay formulary adoption of narrow-spectrum alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lower Respiratory Tract Infection Treatment Market |
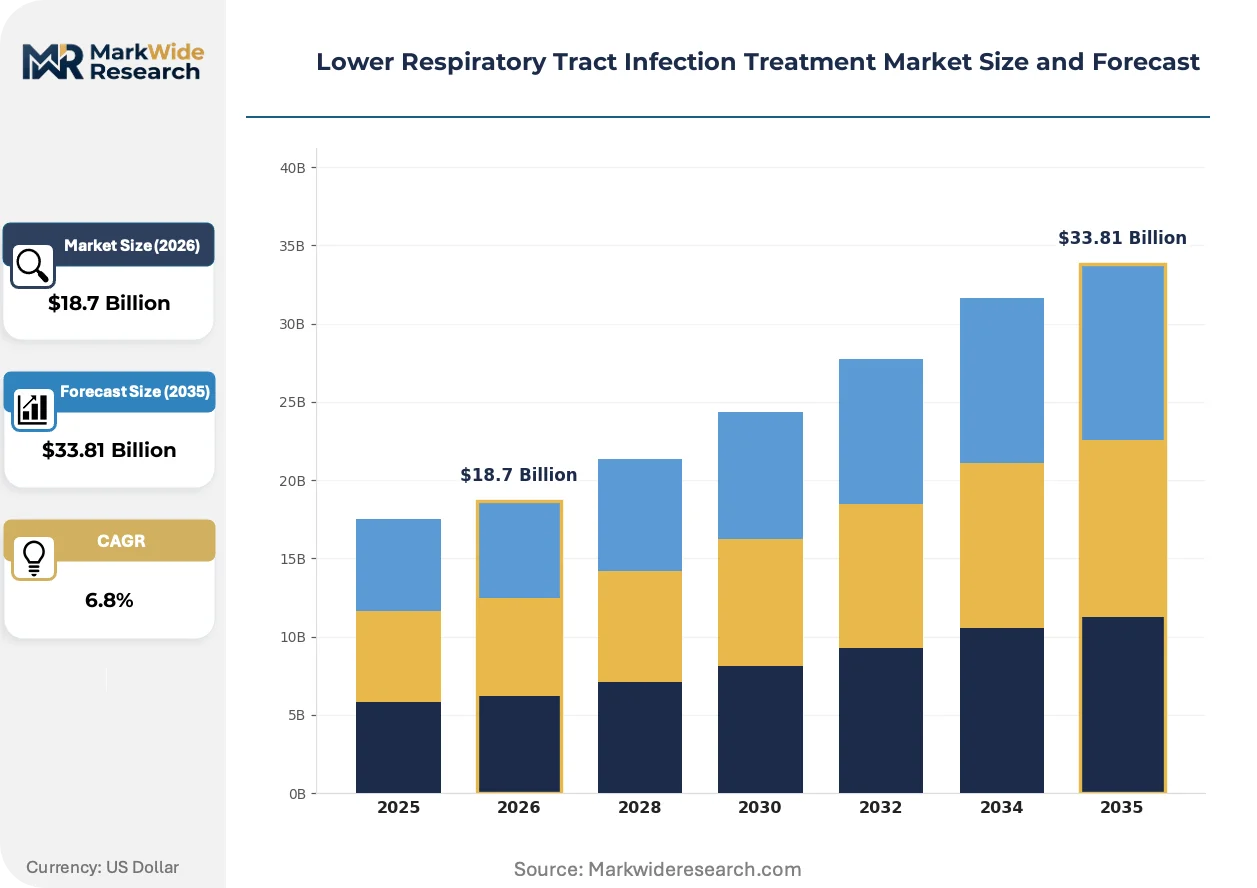
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Corticosteroids, Mucolytics Delivery Mode: Inhalation, Oral, Intravenous, Intramuscular End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Abbott Laboratories, AstraZeneca plc, GlaxoSmithKline plc, Pfizer Inc., Merck & Co., Boehringer Ingelheim GmbH, Novartis AG, F. Hoffmann-La Roche Ltd., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lower Respiratory Tract Infection Treatment Market Shifts & Advancements
Nebulized biologic delivery and rapid pathogen identification are compressing treatment timelines while reshaping how hospitals evaluate respiratory therapy value. These shifts favor precision over empirical approaches.
Polymerase inhibitors engineered for sustained pulmonary deposition are overtaking oral neuraminidase inhibitors in Japanese and German intensive care settings. Critical care physicians prioritize direct alveolar concentration over systemic bioavailability. This technology is compressing viral clearance timelines and reducing progression to mechanical ventilation.
REACH antimicrobial resistance surveillance requirements in Europe now mandate pharmaceutical manufacturers submit resistance monitoring data as a condition of market authorization. The EMA links post-market surveillance obligations to renewal applications. Inhaled antibiotic portfolios face heightened scrutiny for resistance selection pressure documentation.
Hospital pharmacy committees now unbundle device and drug procurement for respiratory therapies, selecting nebulizer platforms independently from pharmaceutical formularies. Device-agnostic drug formulations gain preference over closed-system combinations. This pattern concentrates in United States integrated delivery networks where standardization across member hospitals reduces total cost of ownership.
Lower Respiratory Tract Infection Treatment Market Segmentation
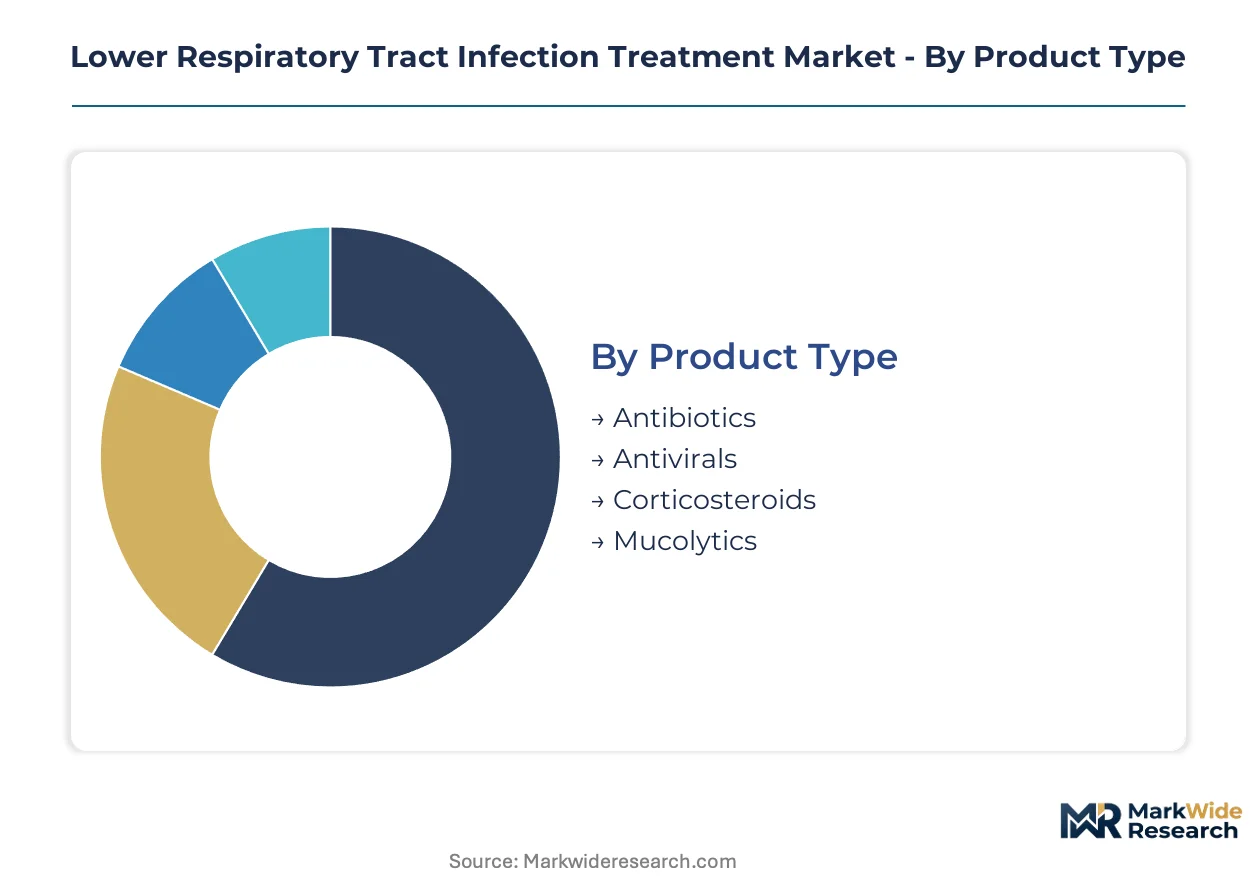
Segmentation in lower respiratory tract infection treatment reveals how regulatory pathways, delivery complexity, and patient acuity stratify commercial opportunity. Each dimension carries distinct certification burdens and reimbursement profiles that shape manufacturer prioritization.
Product Type:
Antibiotics require QIDP designation from the FDA and EMA's PRIME eligibility for expedited review, while antivirals face heightened resistance surveillance obligations under REACH. Corticosteroids and mucolytics navigate less stringent pathways but encounter formulary scrutiny for combination therapy positioning.
- Antibiotics:Beta-lactam, macrolide, and cephalosporin formulations engineered for alveolar penetration dominate hospital procurement. Demand concentrates in United States integrated delivery networks where value-based contracts reward reduced readmission rates for pneumonia patients.
- Antivirals:Neuraminidase and polymerase inhibitors targeting viral replication machinery represent the fastest-expanding margin pool. German and Japanese intensive care units absorb premium-priced nebulized antivirals that compress mechanical ventilation timelines.
- Corticosteroids:Inhaled formulations modulate inflammatory response in bronchitis and bronchiolitis. Long-term care facilities in Japan drive volume for nebulized corticosteroid maintenance therapy.
- Mucolytics:Agents reducing sputum viscosity support airway clearance in chronic bronchitis. Homecare adoption lags due to reimbursement fragmentation across European markets.
Leading the category by volume: Antibiotics. Growing fastest: Antivirals.
Delivery Mode:
Cost tiers separate inhalation systems commanding premium positioning from commoditized oral and injectable routes. Device-agnostic formulations now gain preference over closed-system combinations in United States procurement.
- Inhalation:Nebulized and dry-powder delivery achieves direct lung targeting with reduced systemic toxicity. Japanese long-term care facilities and German hospital networks absorb premium-priced biologic inhalation therapies.
- Oral:Tablets and capsules dominate outpatient bronchitis management where convenience overrides bioavailability demands. Generic macrolide erosion pressures margin in this tier.
- Intravenous:Infusion therapy retains dominance in intensive care settings where bioavailability demands override all other considerations. United States hospitals standardize IV antibiotic protocols across member networks.
- Intramuscular:Depot formulations support transition from acute to subacute care in rehabilitation settings. Adoption concentrates where patient compliance with oral regimens proves unreliable.
Widest installed base: Intravenous. Steepest expansion trajectory: Inhalation.
End User:
Customer type determines reimbursement complexity and outcome measurement rigor. Hospitals face the most stringent value-based contracting requirements, while homecare navigates fragmented payer landscapes.
- Hospitals:Acute care institutions drive demand for IV antibiotics and nebulized antivirals in pneumonia and ventilator-associated infection protocols. United States integrated delivery networks now unbundle device and drug procurement.
- Clinics:Outpatient facilities manage bronchitis and mild pneumonia with oral antibiotic regimens. German ambulatory care networks favor pathogen-directed therapy over empirical broad-spectrum use.
- Homecare:Subacute and chronic respiratory support requires nebulized maintenance therapy. Japan's aging demographic generates concentrated demand for home-based nebulized biologics.
- Rehabilitation Centers:Post-acute facilities bridge hospital discharge and home recovery with stepped-down antibiotic and mucolytic protocols. METI reimbursement reforms in Japan favor site-of-care optimization.
Highest revenue concentration: Hospitals. Fastest policy-driven shift: Homecare.
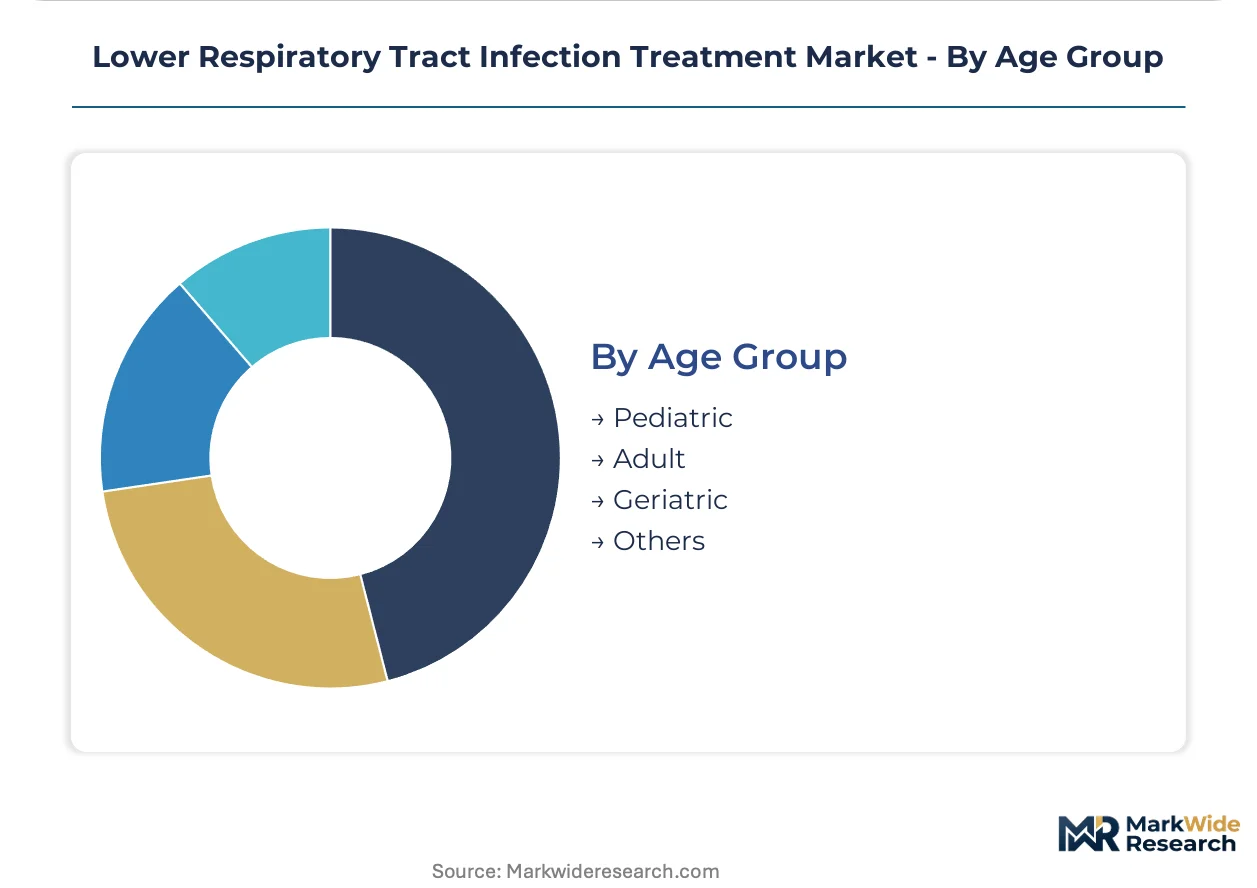
Age Group:
Patient maturity stratifies dosing complexity, formulation preference, and regulatory trial requirements. Pediatric and geriatric segments demand specialized pharmacokinetic data and age-appropriate delivery systems.
- Pediatric:Formulations require weight-based dosing and palatability engineering for bronchiolitis and childhood pneumonia. Nebulized delivery dominates where cooperation with oral regimens proves challenging.
- Adult:Standard-dose antibiotics and antivirals address community-acquired pneumonia and acute bronchitis in working-age populations. Oral compliance drives preference in this segment.
- Geriatric:Polypharmacy interactions and reduced renal clearance necessitate dose-adjusted regimens for pneumonia prevention and treatment. Japan's elderly pneumonia burden concentrates demand for nebulized biologics in long-term care.
- Others:Immunocompromised and cystic fibrosis populations require specialized biologic-antibiotic combinations. Companion diagnostic integration complexity delays formulary adoption in this niche.
Largest addressable population: Adult. Most specialized development requirements: Geriatric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces anchor global antibiotic supply chains. Hospital procurement patterns diverge sharply between mature markets absorbing premium biologics and emerging economies prioritizing generic backbone regimens.
United States
Integrated delivery networks in Texas and Florida drive demand for nebulized antiviral combinations in pneumonia protocols. FDA Qualified Infectious Disease Product designation accelerates review timelines for therapies targeting resistant Pseudomonas strains. Boston's biotech corridor concentrates development partnerships for monoclonal antibody-antibiotic convergence.
Germany
EMA stewardship mandates in Bavaria and North Rhine-Westphalia redirect empirical broad-spectrum use toward pathogen-directed diagnostics. REACH antimicrobial resistance surveillance requirements link post-market obligations to renewal applications. The Rhine-Main cluster houses rapid PCR infrastructure supporting narrow-spectrum formulary adoption.
Japan
Long-term care facilities in Kanto and Kansai regions absorb premium-priced nebulized biologics for elderly pneumonia prevention. METI reimbursement reforms favor site-of-care optimization and pathogen-directed therapy over empirical regimens. Tokyo's medical device corridor advances aerosol delivery engineering for geriatric populations.
India
Tier-two hospital networks in Maharashtra and Karnataka lack respiratory therapy infrastructure for nebulized delivery. CDSCO accelerated approval pathways for generic polymerase inhibitors compress market entry timelines. The Hyderabad-Visakhapatnam corridor concentrates API manufacturing for beta-lactam antibiotic precursors.
United Kingdom
NHS England value-based procurement ties respiratory therapy payment to reduced readmission metrics in London and Midlands trusts. NICE technology appraisals scrutinize premium biologic mortality benefits against generic cephalosporin backbones. The Cambridge-Oxford arc concentrates companion diagnostic development for pathogen-directed stewardship.
Lower Respiratory Tract Infection Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biologic-antibiotic convergence and device-agnostic formulation development. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with integrated respiratory portfolios, mid-cap specialists in pulmonary delivery engineering, and generic manufacturers competing on API cost position. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships compressing clinical trial timelines for resistant pathogen indications.
Within the multinational tier, Pfizer Inc. and GlaxoSmithKline plc exemplify scale-driven positioning across integrated delivery networks. AstraZeneca plc occupies a specialized position in biologic-antibiotic combinations targeting resistant gram-negative infections. Among European-based developers, Boehringer Ingelheim GmbH represents the mid-cap specialist archetype in inhaled corticosteroid portfolios. These entities anchor competitive dynamics through manufacturing scale, formulary relationships, and respiratory formulation expertise rather than through interchangeable commodity supply.
| Leading Market Players |
|---|
| Abbott Laboratories |
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Merck & Co. |
| Boehringer Ingelheim GmbH |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
API precursor spot indices for beta-lactam intermediates cascade through three pricing tiers in lower respiratory tract infection therapies, concentrating margin in nebulized biologics while commoditizing oral generic backbones. Supply concentration in Chinese manufacturing clusters amplifies this stratification, forcing procurement managers to balance cost containment against single-source vulnerability.
Pricing Analysis
Service bundling separates device-inclusive contracts from unbundled drug-only procurement in United States integrated delivery networks. Three-tier pricing structure across premium nebulized biologics, standard IV antibiotics, and economy oral generics reflects formulation complexity and regulatory certification intensity. Price differentiation hinges on FDA QIDP designation and companion diagnostic integration, with premium tiers absorbing resistance surveillance compliance costs. Cost compression in the oral generic tier intensifies as Indian manufacturers expand cephalosporin capacity, while hospital pharmacy committees exhibit lowest price sensitivity for ICU-directed nebulized antivirals that compress ventilation timelines.
Supply Chain Analysis
Specialized aerosol engineering talent scarcity in Germany's Rhine-Main corridor and Massachusetts constrains respiratory formulation capacity expansion. Active pharmaceutical ingredient manufacturing anchors in Zhejiang and Jiangsu provinces of China, with secondary concentration in Hyderabad-Visakhapatnam for beta-lactam precursors. Raw material dependencies center on purified terephthalic acid for polymer packaging, specialty gases for sterile manufacturing, and fermentation-derived antibiotic intermediates. Single-source vulnerability pervades nebulizer device component supply, particularly precision nozzles and piezoelectric elements. Distribution runs through hospital GPO contracts in the United States, regional pharmaceutical wholesalers in Europe, and government tenders in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into active pharmaceutical ingredient supply and companion diagnostic development defines competitive positioning in lower respiratory tract infection therapies, with backward control over fermentation capacity emerging as the decisive upstream lever.
For Market Incumbents: Deepen captive supply of beta-lactam precursors through partnerships with Indian API manufacturers, insulating against Zhejiang cluster disruption. Fortify nebulized formulation expertise through targeted recruitment from Germany's medical device corridor, countering mid-cap specialist encroachment. Prioritize EMA PRIME designation pathways to compress review timelines for resistant pathogen indications, defending premium positioning against generic backbone erosion. For New Entrants and Emerging Players: Distributor networks in India's tier-two hospital infrastructure offer the most penetrable channel for nebulized delivery systems lacking respiratory therapy infrastructure. Biologic-antibiotic convergence for ventilator-associated pneumonia represents underserved white space with compressed clinical trial potential. Pursue CDSCO accelerated approval for generic polymerase inhibitors, leveraging Hyderabad manufacturing proximity to undercut innovator pricing in bronchitis segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap pulmonary delivery specialists with EMA REACH compliance infrastructure in Germany's industrial belt. Five-to-ten year viability hinges on pathogen-directed therapy adoption rates and stewardship mandate enforcement intensity. Monitor Japan METI reimbursement reform implementation velocity as the critical inflection signal for nebulized biologic volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Designation Pursuit | Accelerated assessment compresses timelines for resistant Pseudomonas therapies targeting German hospital formularies. |
| Backward Integration into API Supply | Captive fermentation capacity insulates against Zhejiang cluster disruption and secures beta-lactam precursor availability. |
| Companion Diagnostic Development | Real-time PCR integration enables pathogen-directed stewardship compliance under EMA restricted empirical use guidelines. |
| Nebulized Formulation Partnership | Device-agnostic biologic engineering unlocks United States IDN procurement unbundling trends. |
| India Distribution Channel Expansion | Tier-two hospital network partnerships address respiratory therapy infrastructure gaps in Maharashtra and Karnataka. |
Research Methodology
Multi-period observation of FDA QIDP designations, EMA PRIME eligibility decisions, and hospital formulary adoption timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov protocols, and WHO Essential Medicines List revision records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Segment-weighting approaches distributed value across antibiotics, antivirals, corticosteroids, and mucolytics by delivery mode and end-user acuity. Treatment line, administration route, patient population, and regional regulatory cluster dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical approval-to-adoption curves, resistance surveillance trend extrapolation, and reimbursement policy trajectory analysis. Forecast inputs incorporated polymerase inhibitor pipeline advancement rates and nebulized biologic manufacturing capacity expansion schedules.
Caveats apply where EMA stewardship mandate enforcement intensity, API supply disruption frequency, or companion diagnostic infrastructure deployment could materially shift the outlook. Resistance surveillance data quality and payer willingness to reimburse premium therapies against generic backbones introduce uncertainty bands. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Lung Injury Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Respiratory Measurement Devices Market