
 US Revenue Cycle Management Market | 2026-2036
US Revenue Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Revenue Cycle Management Market Intelligence
Cloud-native architecture is redrawing competitive boundaries in US Revenue Cycle Management. Epic Systems Corporation anchors its position through deep EHR integration that locks in captive hospital workflows. Optum leverages its payer-provider convergence model to control total cost-of-care data streams. athenahealth specializes in multi-specialty physician practice automation, sustaining margin density through network-effect scale.
Revenue Cycle Management denotes the financial process that healthcare providers use to track patient care episodes from registration and appointment scheduling through final payment, encompassing patient eligibility verification, charge capture, medical coding, claims submission, payment posting, and denial management. Software dominates product-type value capture, while cloud-based deployment is displacing on-premise installations as health systems prioritize interoperability and remote workforce enablement. Services and consulting segments retain sticky revenue from legacy system migrations and compliance remediation, though analytics represents the fastest-expanding margin pool as predictive denial modeling matures.
CMS price transparency rules, the No Surprises Act, and HIPAA security requirements collectively elevate compliance spending and platform consolidation decisions. The Office of the National Coordinator for Health IT pushes interoperability standards that reshape vendor certification and data-exchange obligations. Stakeholders must monitor whether federal enforcement of surprise billing arbitration timelines forces workflow redesigns or vendor substitutions.
Market Dynamics
Federal price transparency mandates and surprise billing arbitration rules are forcing health systems to rebuild patient financial workflows from registration through collections, compressing vendor switching timelines and consolidating purchasing authority.
Growth Catalysts
- The No Surprises Act:Independent dispute resolution requirements create urgent demand for automated arbitration documentation and patient notification systems.
- Cloud-native platforms:Health systems in Texas and Florida are replacing fragmented billing modules with unified SaaS architectures that enable remote revenue operations.
- Charge capture automation:Computer-assisted coding is reducing leakage from missed clinical documentation in high-acuity service lines.
Market Restraints
- Legacy system entrenchment:Decades-old patient accounting systems in large hospital systems resist API-based interoperability, trapping data in proprietary formats.
- Specialized talent scarcity:Certified medical coders and denial management analysts command premium wages that strain mid-sized practice operating margins.
- CMS certification delays:New platform modules face extended testing cycles for HIPAA security and interoperability compliance before production deployment.
Strategic Opportunities
- Patient self-service portals:Real-time cost estimation and payment plan enrollment are capturing previously written-off bad debt in ambulatory networks.
- Prior authorization automation:AI-driven clinical validation is reducing administrative burden in specialty pharmacy and advanced imaging prior to service delivery.
- Telehealth billing integration:Cross-state licensure and place-of-service coding complexity creates whitespace for platforms that automate multi-jurisdictional claims.
Industry Challenges
- Interoperability fragmentation:Health systems struggle to synchronize patient financial data across EHR, practice management, and payer portal environments without manual reconciliation.
- Denial appeal workforce gaps:Complex clinical denial categories require specialized nursing and coding expertise that resists automation and scales poorly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Revenue Cycle Management Market |
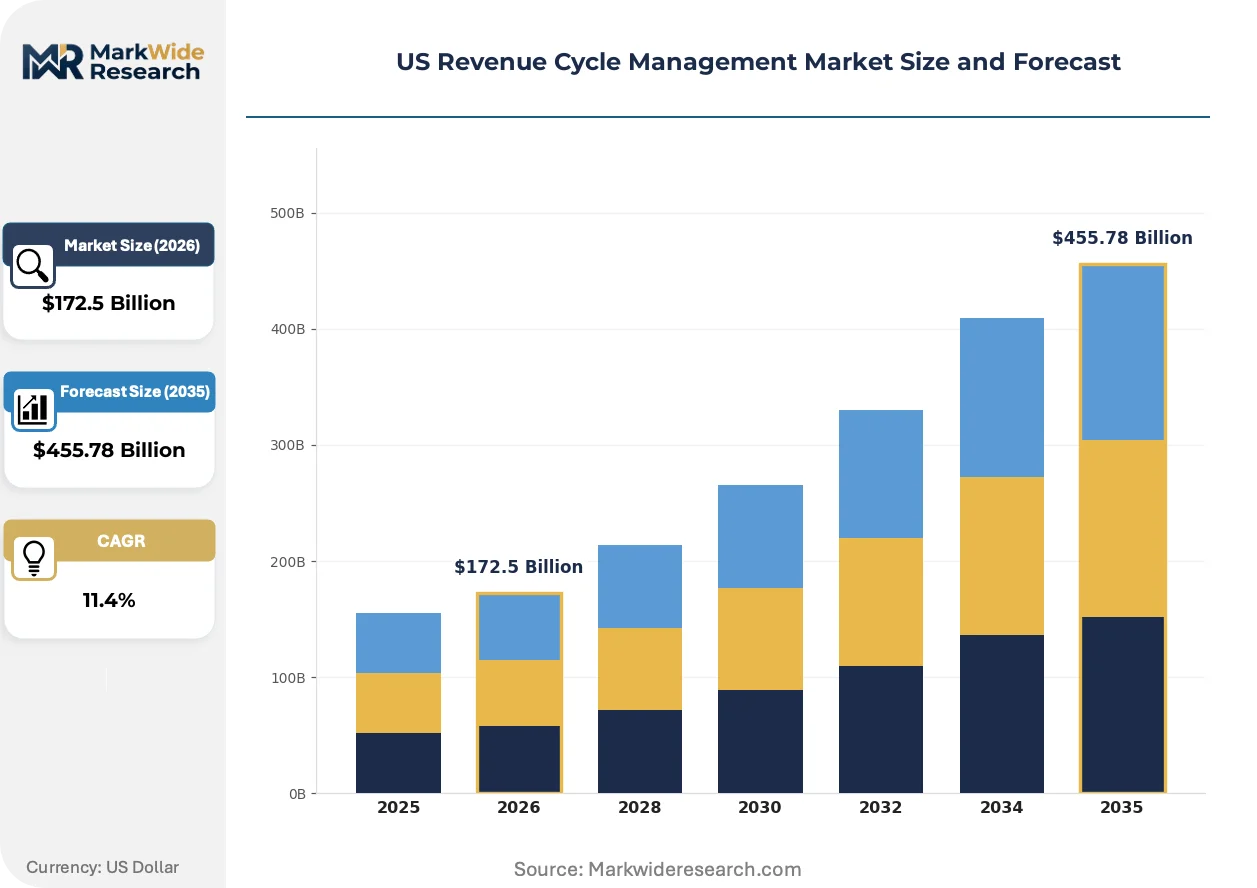
| Market Size in 2026 | $172.5 Billion |
| Market Size in 2035 | $455.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Consulting, Analytics End User: Hospitals, Clinics, Physician Practices, Ambulatory Centers Deployment: On-Premise, Cloud-Based, Hybrid, Remote Functionality: Billing, Coding, Audit, Payments |
| Companies Covered | Change Healthcare, Epic Systems Corporation, R1 RCM, McKesson Corporation, SSI Group, athenahealth, Optum, Veradigm, Oracle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Revenue Cycle Management Market Strategic Shifts & Innovations
Automation is penetrating deeper into clinical-to-financial workflows, with machine learning models now predicting denial probability before claim submission and real-time eligibility verification replacing batch processing.
Robotic process automation is supplanting manual data entry in patient access and billing operations. Large health systems in California and New York are deploying software bots for eligibility verification and payment posting at scale. This shift is compressing cost-per-transaction metrics and forcing legacy outsourcers to reprice service contracts or lose renewals.
CMS price transparency rules now require machine-readable files for all shoppable services and good faith estimates for uninsured patients. Hospitals must publish negotiated rates and derived amounts, exposing previously confidential payer contracts. Ambulatory surgery centers and imaging centers are responding fastest, using transparency as a patient acquisition tool.
Patients are demanding consumer-grade financial experiences modeled on retail and banking applications. Mobile-first payment platforms with personalized plan options are replacing paper statements and call center collections in metropolitan health systems. This behavioral shift is most pronounced in Florida and Texas markets where high-deductible plan penetration concentrates financial risk on patients.
US Revenue Cycle Management Market Segmentation
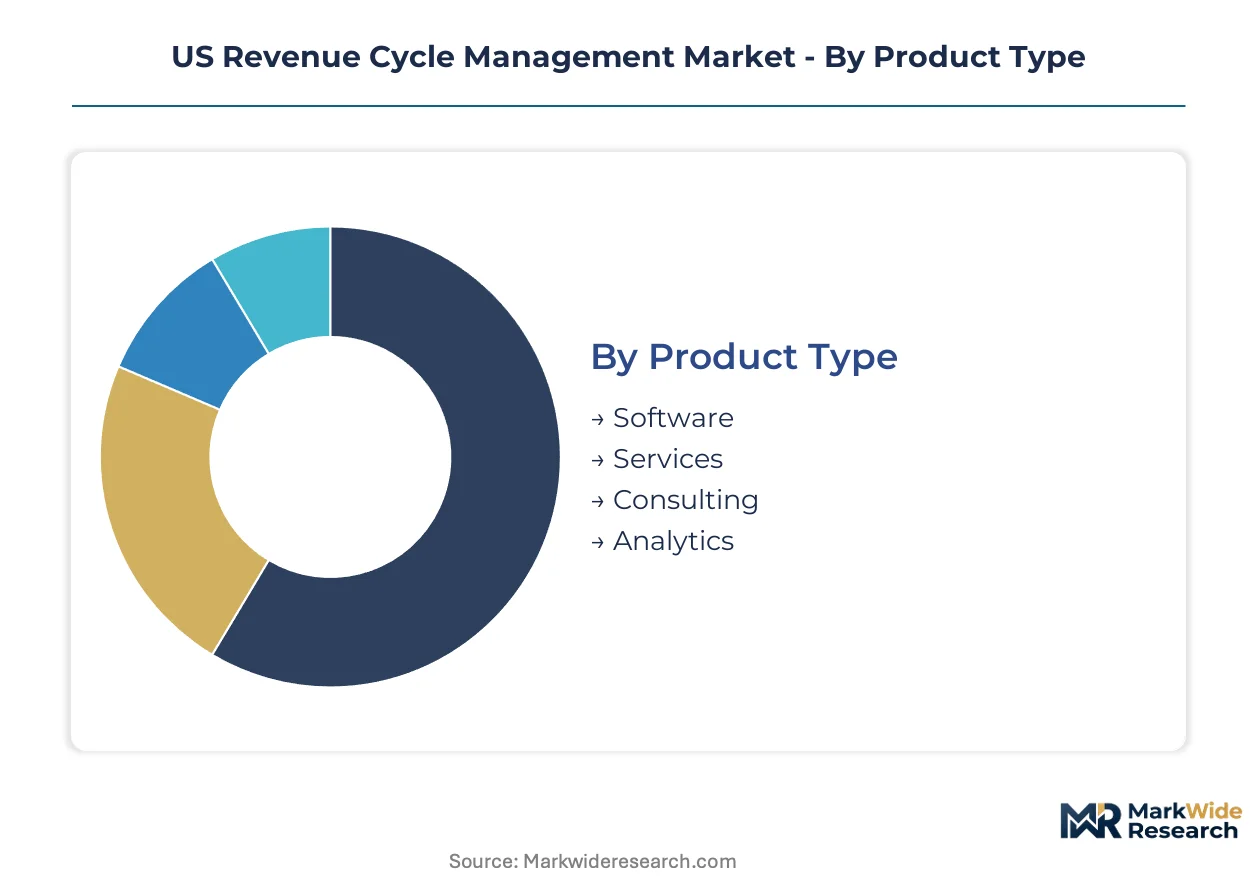
RCM purchasing decisions split sharply between capital-intensive health systems seeking unified platforms and ambulatory networks prioritizing modular, SaaS-based point solutions. Understanding these segment boundaries clarifies why vendor consolidation accelerates in some channels while fragmentation persists in others.
Product Type:
Software flows through direct enterprise sales to large health systems, while services and consulting reach mid-market buyers via value-added resellers and system integrators.
- Software:Cloud-native platforms with embedded AI for denial prediction and automated coding now anchor hospital IT budgets. Texas and Florida health systems are replacing legacy patient accounting modules with integrated suites that consolidate registration, eligibility, and claims management into single vendor relationships.
- Services:Outsourced revenue operations including eligibility verification, payment posting, and denial appeals. Demand concentrates among physician practices in high-deductible plan markets where in-house staffing costs exceed outsourced per-transaction pricing.
- Consulting:Legacy system migration and compliance remediation for HIPAA security and CMS interoperability mandates. Engagements typically precede software procurement decisions.
- Analytics:Predictive models for charge capture leakage and payer contract performance. This segment is expanding most quickly as health systems seek to quantify ROI from RCM investments.
Software dominates installed base. Analytics is where expansion concentrates.
End User:
Cost tier segmentation reveals acute divergence: hospitals absorb platform premiums for integration depth while ambulatory buyers optimize for per-provider subscription economics.
- Hospitals:Integrated delivery networks and academic medical centers requiring enterprise-scale platforms with multi-entity consolidation and Epic EHR interoperability. These buyers drive vendor consolidation through multi-year, eight-figure contracts.
- Clinics:Federally qualified health centers and community clinics with constrained IT budgets. Demand concentrates on Medicaid eligibility automation and sliding-fee scale management in states with high uninsured populations.
- Physician Practices:Multi-specialty groups of 50-500 providers represent the most contested segment. athenahealth and Optum compete aggressively here with cloud-native practice management bundled with RCM.
- Ambulatory Centers:Surgery centers and imaging facilities responding fastest to CMS price transparency mandates. These buyers prioritize patient self-service portals and real-time cost estimation as competitive differentiation tools.
Hospitals anchor vendor revenue. Ambulatory centers are gaining share fastest.
Deployment:
Volume patterns show cloud-based deployments scaling linearly with ambulatory network expansion while on-premise installations correlate with legacy EHR footprints.
- On-Premise:Legacy patient accounting systems in large hospital systems with decade-old Epic or Cerner implementations. These installations resist API-based interoperability, trapping data in proprietary formats and delaying cloud migration timelines.
- Cloud-Based:SaaS architectures enabling remote revenue operations and rapid scaling across multi-state ambulatory networks. Texas and Florida health systems are replacing fragmented billing modules with unified cloud platforms.
- Hybrid:Core financial systems remaining on-premise while patient-facing modules shift to cloud. This configuration satisfies HIPAA security requirements for protected health information while enabling consumer-grade payment experiences.
- Remote:Fully distributed revenue cycle teams accessing cloud platforms from home-based workstations. Deployment accelerated post-pandemic and now standard for coding and denial management functions.
On-Premise retains legacy lock-in. Cloud-Based shows the steepest expansion trajectory.
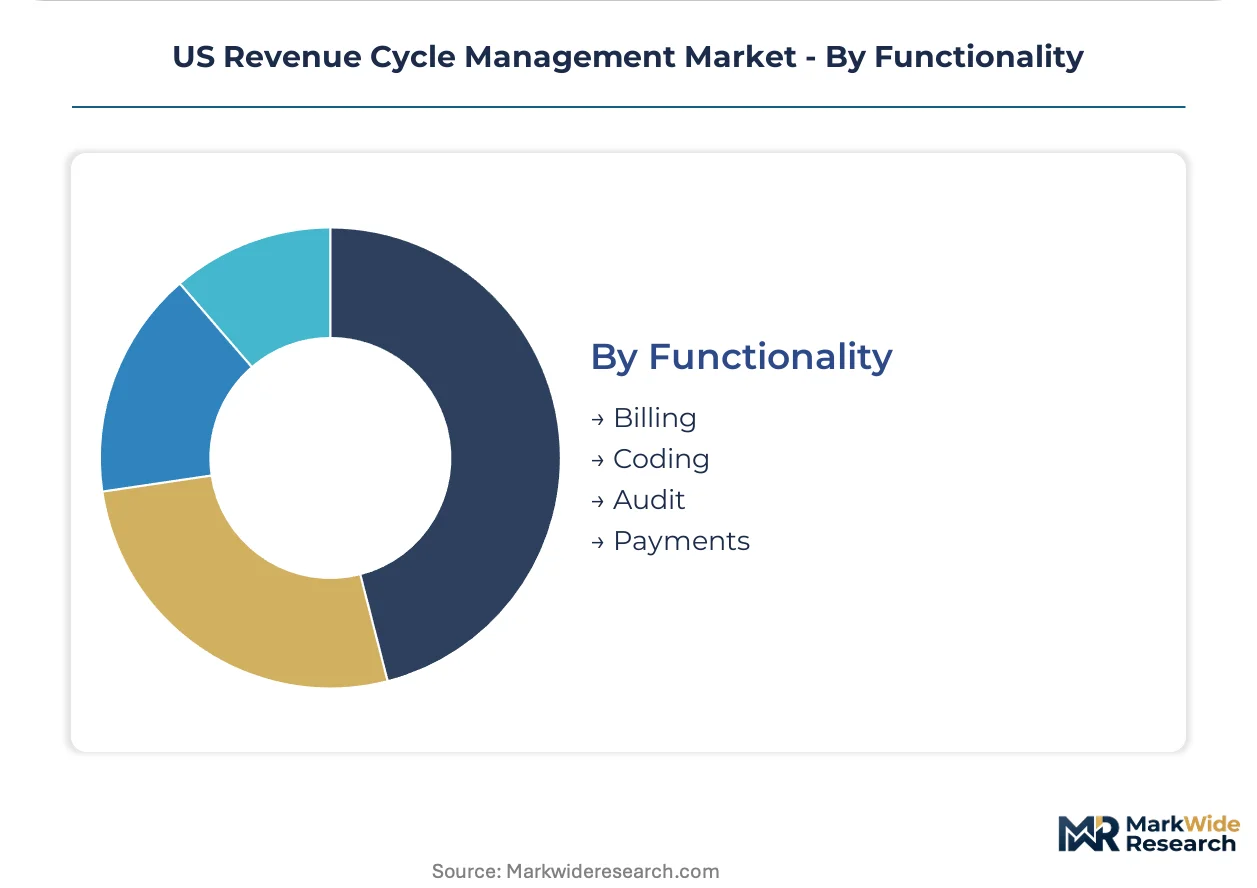
Functionality:
Margin concentration follows workflow automation potential: billing and coding capture the highest platform valuations while audit functions remain services-heavy.
- Billing:Patient financial engagement through registration, eligibility verification, and collections. Real-time cost estimation and payment plan enrollment are capturing previously written-off bad debt in high-deductible markets.
- Coding:Computer-assisted coding and clinical documentation integrity. Machine learning models now predict denial probability before claim submission, reducing leakage from missed documentation in high-acuity service lines.
- Audit:Compliance validation for CMS price transparency, No Surprises Act, and HIPAA security requirements. Services-heavy segment with sticky revenue from remediation engagements.
- Payments:Payment posting, reconciliation, and patient collections. Mobile-first platforms with personalized plan options are replacing paper statements in metropolitan health systems.
Billing and coding dominate platform R&D investment. Payments functionality is where vendor differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Revenue Cycle Management Market demonstrates pronounced regional variation, with domestic demand patterns shaped by state-level health system consolidation, Medicaid expansion status, and ambulatory network density rather than cross-border trade flows.
Texas
Hospital system consolidation and ambulatory network expansion are accelerating RCM platform procurement across the state. The Texas Department of Insurance enforces balance billing protections that align with federal No Surprises Act requirements, driving demand for automated arbitration documentation. Dallas-Fort Worth and Houston medical centers are replacing fragmented billing modules with unified cloud-native architectures.
Florida
High-deductible plan penetration concentrates financial risk on patients, intensifying demand for consumer-grade payment portals and real-time cost estimation tools. State Medicaid managed care contracts require enhanced eligibility verification workflows that vendors must certify annually. South Florida health systems and Tampa Bay ambulatory surgery centers lead adoption of patient self-service revenue technologies.
California
Large integrated delivery networks deploy robotic process automation for eligibility verification and payment posting at scale. The California Department of Managed Health Care imposes strict prompt-pay regulations that compress claims processing timelines and elevate denial management urgency. Los Angeles and San Francisco Bay Area systems pioneer machine learning models for pre-submission denial prediction.
New York
Academic medical centers anchor enterprise RCM spending with multi-year, eight-figure platform contracts. State surprise billing legislation predated federal action, creating mature compliance frameworks that vendors must navigate. The New York City metropolitan corridor concentrates Epic EHR interoperability requirements that lock in captive hospital workflows.
Illinois
Chicago-based health systems drive hybrid deployment models, maintaining core financial systems on-premise while shifting patient-facing modules to cloud. The Illinois Department of Healthcare and Family Services mandates real-time Medicaid eligibility verification that shapes vendor selection criteria. Midwest physician practice management consolidation is concentrating purchasing authority among fewer buyers.
US Revenue Cycle Management Market Key Industry Players
Concentration sits with integrated health IT conglomerates and specialized revenue cycle pure-plays that have achieved scale through payer-provider convergence or network-effect automation. The vendor base stratifies into three tiers: enterprise platforms with deep EHR integration, multi-specialty physician practice specialists, and modular point-solution providers. Dominant competitive moves include vertical integration of payer data assets and cloud-native platform consolidation that displaces legacy patient accounting systems.
Within the enterprise platform tier, Epic Systems Corporation and Oracle exemplify archetypes anchored by EHR-captive workflows and database-centric infrastructure respectively. Optum occupies a position representing payer-provider convergence models that control total cost-of-care data streams. athenahealth sits within the physician practice automation specialist category, sustaining margin density through SaaS network effects rather than installed-base lock-in.
| Leading Market Players |
|---|
| Change Healthcare |
| Epic Systems Corporation |
| R1 RCM |
| McKesson Corporation |
| SSI Group |
| athenahealth |
| Optum |
| Veradigm |
| Oracle |
| Others |
Cost & Logistics Intelligence
HIPAA security certification and CMS interoperability mandates gate vendor qualification while simultaneously enabling price differentiation between compliant and non-compliant platform tiers. Health systems in Texas and Florida concentrate purchasing authority among fewer buyers, amplifying procurement leverage over RCM vendors and compressing margin structures for mid-tier providers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing across the US Revenue Cycle Management landscape. Three-tier pricing structure across enterprise, mid-market, and ambulatory levels reflects deployment complexity and integration depth with Epic or Cerner EHR systems. Pricing pressure stems from cloud-native entrants undercutting legacy on-premise maintenance contracts. Mid-sized physician practices exhibit highest price sensitivity, while academic medical centers absorb premiums for captive workflow integration.
Supply Chain Analysis
Implementation lead times for cloud-native platforms have compressed from eighteen months to six months as vendor capacity scales. Software development concentrates in the United States, with specialized coding talent pools in India and the Philippines supporting back-office automation modules. Cloud infrastructure draws from hyperscaler data centers in Virginia, Oregon, and Ohio. Single-source vulnerability sits with Epic Systems Corporation's proprietary interoperability protocols that resist API standardization. Distribution runs through direct enterprise sales teams and value-added resellers serving ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-native revenue cycle platforms that bypass legacy EHR integration requirements entirely. Defense requires consolidation moves that lock in data network effects before alternative architectures achieve scale.
For Market Incumbents: Fortify installed-base retention by embedding predictive denial analytics deeper into clinical workflows, creating switching costs that rival Epic's EHR lock-in. Acquire specialized prior authorization automation firms to neutralize emerging AI-native entrants threatening the physician practice segment. Prioritize backward integration into payer data streams through exclusive total cost-of-care contracts with Optum-style convergence models.
For New Entrants and Emerging Players: ONC Health IT certification fast-tracks market access for interoperability-compliant platforms, bypassing the extended testing cycles that trap legacy vendors. Target ambulatory surgery centers in Florida and Texas, where price transparency mandates have created urgent demand for patient self-service revenue technologies unmet by hospital-centric incumbents. Lead with real-time cost estimation modules that convert compliance spending into patient acquisition tools.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native RCM deployments as SaaS economics replace on-premise infrastructure investments. Acquisition targets should display network-effect scale in multi-specialty physician practices or captive payer data relationships. Monitor CMS enforcement timelines for surprise billing arbitration as the signal indicating workflow redesign spending inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Texas health systems replace fragmented billing modules with unified SaaS architectures enabling remote revenue operations. |
| Prior Authorization Automation | AI-driven clinical validation reduces administrative burden in specialty pharmacy and advanced imaging workflows. |
| Patient Self-Service Portal Deployment | Florida ambulatory centers capture previously written-off bad debt through real-time cost estimation and payment plan enrollment. |
| Payer Data Integration | Optum-style convergence models control total cost-of-care data streams that anchor long-term platform contracts. |
| Compliance-First Product Development | No Surprises Act arbitration documentation modules differentiate vendors in CMS certification-driven procurement cycles. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital revenue cycle executives, ambulatory network IT directors, medical coding operations managers, and payer contract specialists. Secondary validation drew from CMS Medicare cost reports, ONC Health IT certification databases, hospital procurement disclosures, and GPO contract repositories. Bottom-up transaction modeling triangulated against top-down health system IT spending benchmarks.
Across the analysis window, forecast outputs reflect segmented modeling across deployment architecture, end-user scale tier, and functionality module. CAGRs were derived from elasticity-adjusted adoption curves calibrated to cloud migration patterns in Texas and Florida health systems. Segment-level projections incorporated HIPAA compliance spending trajectories and No Surprises Act implementation timelines as demand shifters.
Decision-makers should treat outputs as directional under assumptions of continued CMS enforcement intensity and stable cloud infrastructure pricing; material deviation would warrant model refresh. Specific risk factors include federal arbitration timeline acceleration, legacy EHR vendor API policy reversals, and hyperscaler cost inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Secure Messaging in Healthcare Market