
 North America Point of Care Diagnostics Market | 2026-2036
North America Point of Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Point of Care Diagnostics Market Analytics
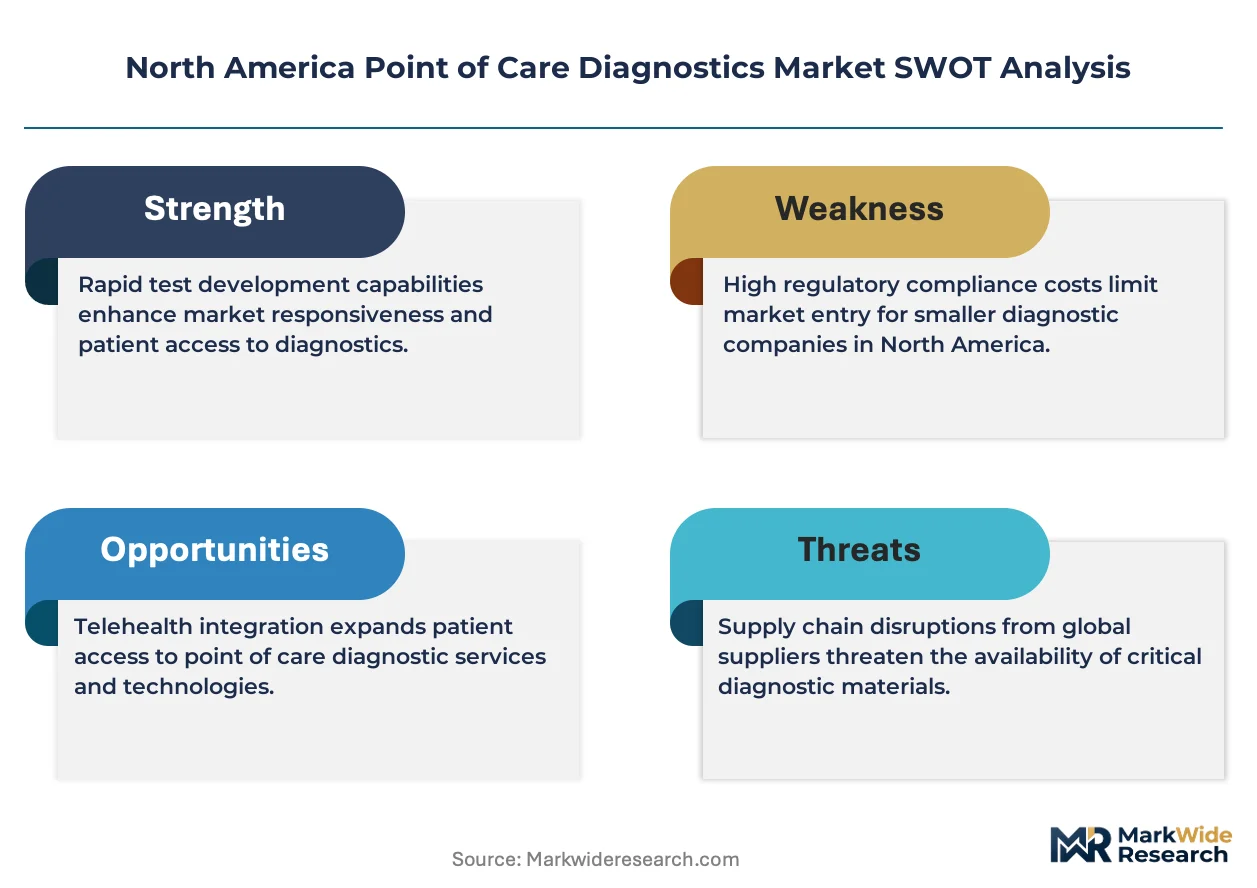
Asset-light leasing models for diagnostic instrument placement are tilting competitive dynamics toward firms with balance-sheet flexibility. Abbott leverages extensive instrument-installation networks to sustain recurring consumable revenue across ambulatory sites. Siemens Healthineers anchors its position through integrated informatics that tie point-of-care results into enterprise laboratory systems. QuidelOrtho Corporation specializes in respiratory and infectious disease panels that dominate seasonal testing workflows in urgent care settings.
Point of care diagnostics encompass portable analytical systems designed to deliver clinical test results at or near the patient location, typically requiring sample volumes under 500 microliters and turnaround times below 30 minutes for glucose, cardiac marker, or infectious disease assays. These devices serve the primary purpose of accelerating clinical decision-making while reducing central laboratory logistics burdens. Immunoassay platforms occupy the largest installed base due to proven reliability in cardiac and metabolic panels, though molecular diagnostics represents the fastest-expanding technology segment as PCR-miniaturization and isothermal amplification methods penetrate CLIA-waived environments. Home care end users generate expanding demand for connected glucose meters and pregnancy tests with smartphone integration, while hospital point-of-care programs remain the deepest margin pool through high-volume contractual purchasing.
FDA oversight through the CLIA waiver program and the In Vitro Diagnostics Regulation framework shapes product development priorities and market access timelines for manufacturers seeking placement in non-laboratory settings. Health Canada and the EPA jointly influence environmental and safety standards for reagent disposal and instrument materials used in distributed testing locations. Stakeholders must monitor evolving reimbursement determinations from CMS and provincial health authorities as these decisions directly determine which test categories achieve sustainable volume penetration outside traditional laboratory economics.
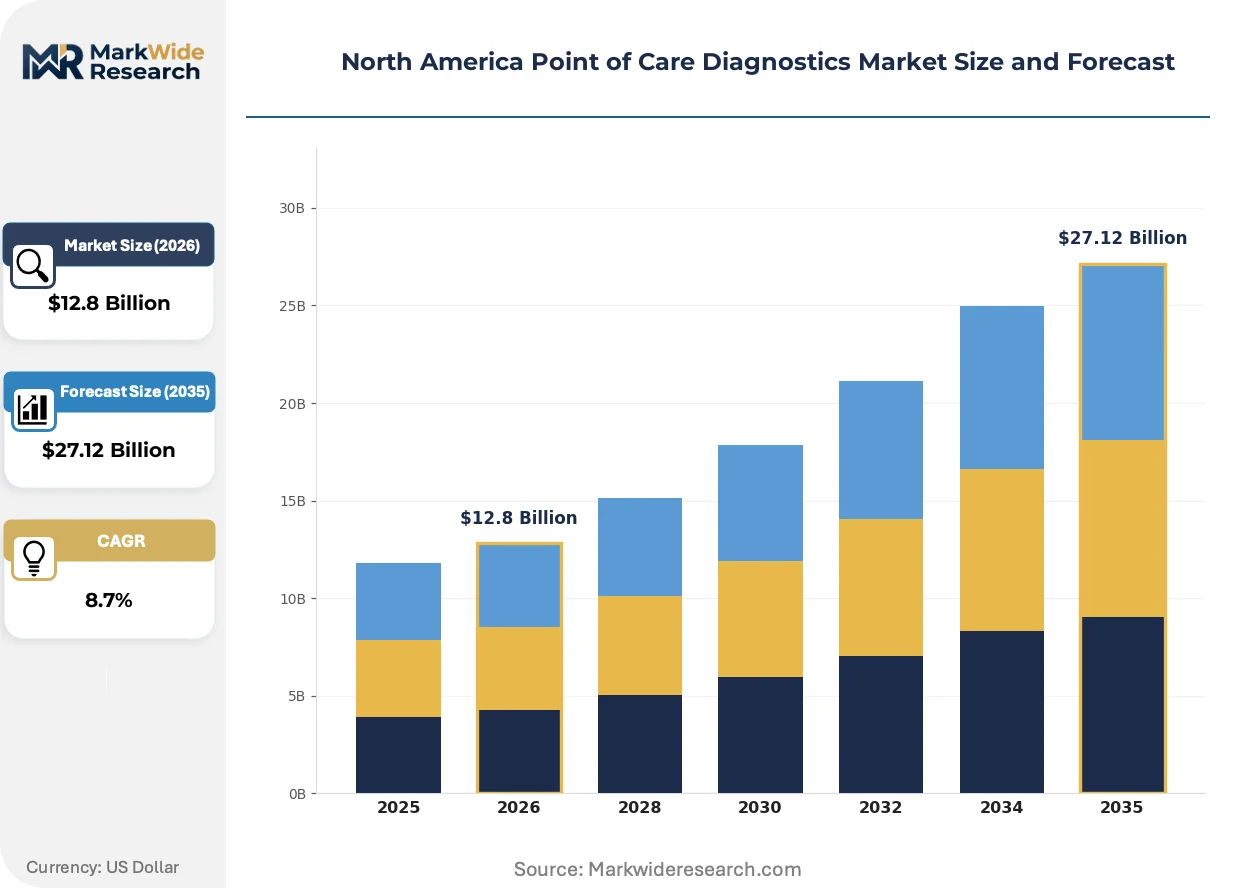
Market Dynamics
Decentralized testing infrastructure expansion across United States and Canadian hospital networks is compressing traditional central laboratory workflows while elevating instrument placement density as the primary competitive battleground.
Growth Catalysts
- CLIA waiver pathway acceleration:FDA streamlined molecular assay clearances are collapsing time-to-market for PCR-miniaturized platforms entering urgent care environments.
- Texas and Florida urgent care density:Retail clinic chain expansion in these states is generating concentrated instrument demand for respiratory and cardiac marker testing.
- Isothermal amplification maturation:LAMP and RPA chemistries are penetrating non-laboratory settings without thermal cycler infrastructure requirements.
Market Restraints
- Reagent cold chain fragility:Temperature-sensitive molecular assay components face spoilage risk in distributed ambulatory sites lacking pharmacy-grade refrigeration.
- CMS reimbursement compression:Medicare fee schedule adjustments for waived tests are squeezing margin pools for high-volume hospital point-of-care programs.
- Competing laboratory centralization:Health system consolidation is reabsorbing some testing volume into core labs through pneumatic tube and automation investments.
Strategic Opportunities
- Ontario provincial procurement:Canada's decentralized health authority structure creates entry points for multi-site instrument leasing contracts outside US competitive intensity.
- Home care connectivity integration:Smartphone-linked glucose meters and pregnancy tests are opening direct-to-patient revenue streams bypassing traditional hospital purchasing.
- EPA reagent disposal standards:Environmental compliance requirements for distributed testing locations favor vendors with pre-validated waste management protocols.
Industry Challenges
- CLIA personnel certification gaps:Waived testing site supervisors require specific training credentials that urgent care staff turnover erodes.
- Enterprise LIS integration complexity:Point-of-care result transmission into Cerner and Epic systems demands custom HL7 interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Point of Care Diagnostics Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Infectious Disease Tests, Pregnancy Tests, Cholesterol Tests Technology: Immunoassays, Molecular Diagnostics, Microfluidics, Optical Technologies End User: Hospitals, Urgent Care Centers, Home Care, Laboratories Application: Blood Testing, Disease Screening, Monitoring, Rapid Diagnosis |
| Companies Covered | Abbott, BD, Siemens Healthineers, bioMérieux, F. Hoffmann-La Roche, Danaher Corporation, QuidelOrtho Corporation, Thermo Fisher Scientific, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Point of Care Diagnostics Market Evolving Landscape
Connectivity architecture and regulatory pathway engineering are overtaking raw analytical performance as the primary vectors of product differentiation in point-of-care diagnostics.
Miniaturized PCR platforms are migrating from reference laboratory environments into CLIA-waived urgent care settings. Abbott and Cepheid instrument footprints now dominate Texas and Florida retail clinic chains. This technology diffusion is collapsing the historical separation between molecular accuracy and waived-test accessibility.
Health Canada and EPA joint oversight of reagent disposal and instrument materials is elevating environmental compliance to a procurement gate. Manufacturers must now pre-validate end-of-life protocols before provincial health authority contract eligibility. Ontario and British Columbia purchasing committees are weighting sustainability documentation in competitive bid scoring.
Ambulatory site managers are consolidating instrument vendors to reduce training burden and service contract fragmentation. Multi-assay platforms from single suppliers are displacing best-of-breed device accumulation in hospital-affiliated urgent care networks. This vendor concentration is most visible in Florida's large health system point-of-care programs.
North America Point of Care Diagnostics Market Segmentation
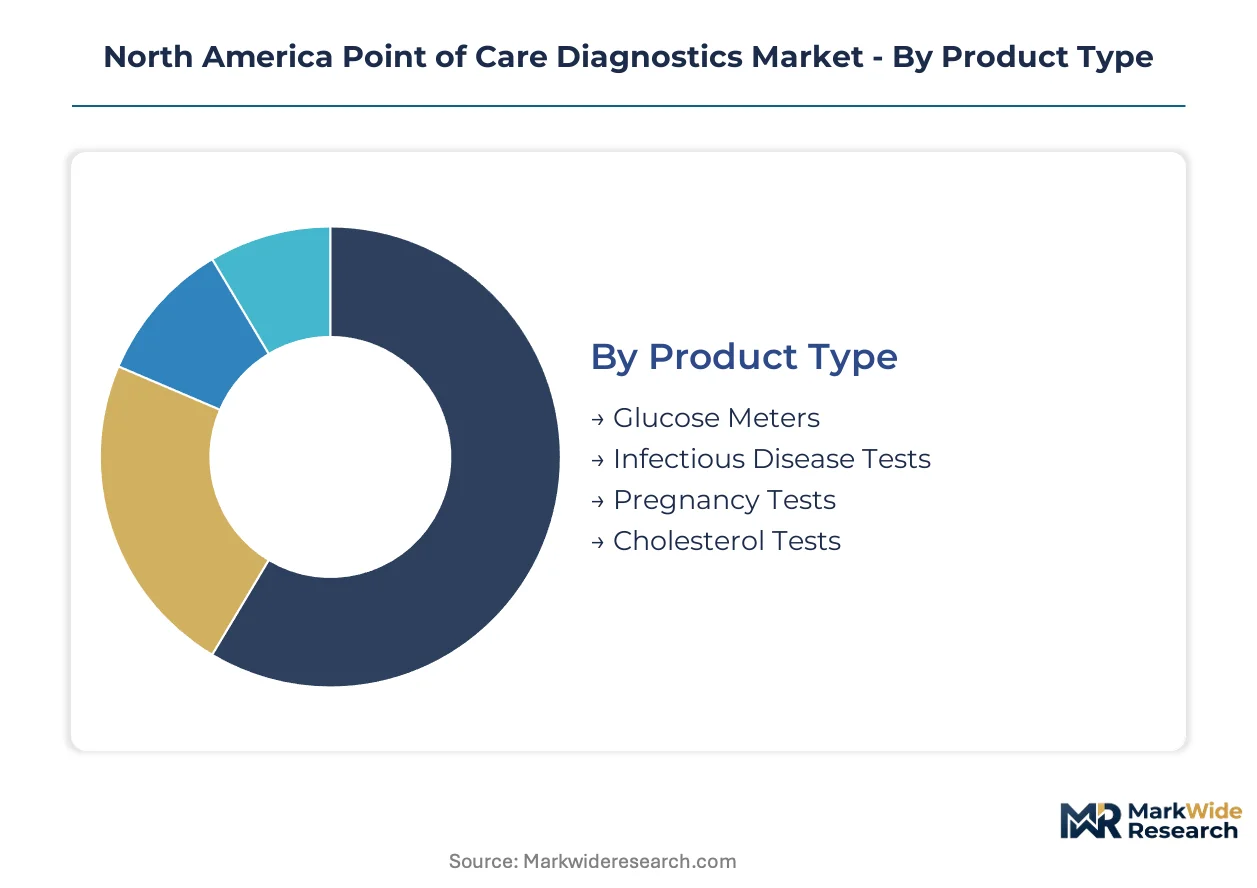
Point of care diagnostics in North America fragment across four intersecting dimensions that determine purchasing authority, margin structure, and regulatory pathway. Product type and technology choices cascade into end-user deployment patterns and application workflows, creating distinct competitive arenas with divergent growth trajectories.
Product Type:
Use-case spectrum spans chronic disease management at home through acute infectious disease triage in ambulatory settings, with each product category commanding different reimbursement codes and consumable economics.
- Glucose Meters:Connected devices with sub-5 microliter sample requirements dominate home care deployment through Medicare Part B durable medical equipment channels. Texas and Florida Medicare Advantage plans are driving meter replacement cycles through outcomes-based contracting with retail pharmacy chains.
- Infectious Disease Tests:Respiratory panels and SARS-CoV-2 multiplex assays concentrate in urgent care networks across Ontario and Quebec, where provincial procurement favors CLIA-waived platforms with 15-minute turnaround. Cold chain requirements for reagent stability constrain placement in sites lacking pharmacy-grade refrigeration.
- Pregnancy Tests:Smartphone-integrated digital readers are displacing traditional lateral flow strips in direct-to-consumer channels, with Health Canada Class II clearance enabling cross-border e-commerce fulfillment.
- Cholesterol Tests:Lipid panel cartridges for CLIA-waived environments serve employer wellness programs and retail clinic chains operating in California and Illinois, where occupational health mandates drive screening volume.
The dominant share belongs to Glucose Meters, while Infectious Disease Tests is closing the gap fastest.
Technology:
Cost tier stratification separates established immunoassay platforms from capital-intensive molecular miniaturization, with microfluidics bridging the gap through cartridge-based automation.
- Immunoassays:Lateral flow and sandwich ELISA architectures power cardiac marker and metabolic panels with proven stability in uncontrolled temperature environments. Hospital point-of-care programs in Michigan and Pennsylvania standardize on these platforms for high-volume contractual purchasing.
- Molecular Diagnostics:PCR-miniaturization and isothermal amplification methods are penetrating CLIA-waived urgent care settings without thermal cycler infrastructure. FDA streamlined clearances for Abbott and Cepheid systems are compressing time-to-market for respiratory and sexually transmitted infection panels.
- Microfluidics:Lab-on-a-chip cartridges integrate sample preparation with detection for blood gas and electrolyte analysis in emergency departments. California health system consolidation is driving multi-site standardization on single-vendor microfluidic platforms to reduce training burden.
- Optical Technologies:Spectroscopic and fluorometric detection methods serve specialized coagulation and hemoglobin testing in hematology-oncology infusion centers across Massachusetts and New York.
Immunoassays retain the deepest installed base, though Molecular Diagnostics exhibits the steepest expansion trajectory as waived PCR platforms proliferate.
End User:
Customer type determines purchasing process complexity, with hospitals running competitive tenders through group purchasing organizations while home care bypasses institutional procurement entirely.
- Hospitals:Point-of-care programs within acute care facilities generate the deepest margin pools through high-volume contractual purchasing integrated with enterprise laboratory information systems. Cerner and Epic HL7 interface requirements favor vendors with pre-built connectivity modules.
- Urgent Care Centers:Retail clinic chains in Texas, Florida, and Arizona are expanding instrument placement density for respiratory and cardiac marker testing, with seasonal demand spikes driving consumable revenue concentration.
- Home Care:Direct-to-patient glucose meters and pregnancy tests with smartphone integration are opening revenue streams outside traditional hospital purchasing, though CMS reimbursement compression constrains sustainable volume for waived test categories.
- Laboratories:Reference labs are deploying point-of-care platforms as satellite collection sites to defend against decentralized testing erosion, particularly in Ontario where provincial health authority structure creates multi-site leasing opportunities.
Hospitals command the largest revenue concentration, yet Home Care is gaining share fastest through connected device penetration.
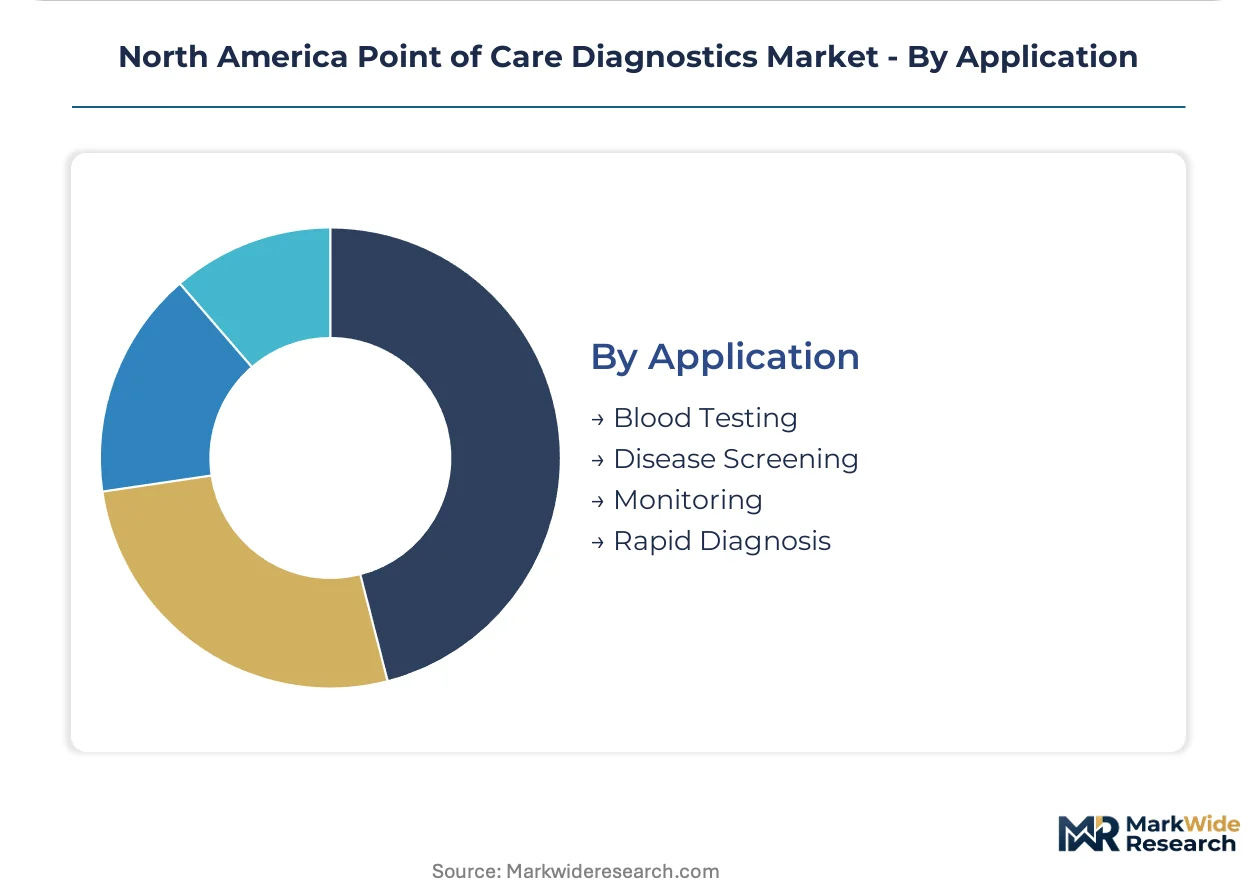
Application:
Volume concentration varies by clinical workflow urgency, with rapid diagnosis commanding premium placement in emergency settings while monitoring generates recurring consumable streams in chronic disease management.
- Blood Testing:Glucose, hemoglobin, and coagulation assays require minimal sample volume and deliver results within 60 seconds, serving perioperative and anticoagulation clinic workflows in Ohio and North Carolina hospital networks.
- Disease Screening:Infectious disease and cardiac marker panels enable same-visit clinical decision-making in urgent care environments, with CLIA waiver pathways determining which test categories achieve sustainable penetration outside central laboratory economics.
- Monitoring:Therapeutic drug monitoring and glycemic control applications generate recurring cartridge revenue through long-term patient relationships in endocrinology and transplant clinics across British Columbia and Alberta.
- Rapid Diagnosis:Strep A, influenza, and COVID-19 multiplex assays support antibiotic stewardship and isolation protocols in pediatric and emergency department settings, with turnaround time under 20 minutes driving competitive differentiation.
Blood Testing holds the dominant position, while Rapid Diagnosis is expanding most quickly through infectious disease panel proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA streamlined clearance pathways and provincial procurement decentralization are accelerating instrument placement across hospital networks and urgent care chains.
United States
Texas and Florida urgent care density drives concentrated demand for respiratory and cardiac marker testing platforms. CMS reimbursement determinations for waived test categories directly shape sustainable volume penetration outside traditional laboratory economics. Hospital systems in Michigan and Pennsylvania standardize on multi-assay platforms to reduce training burden and service contract fragmentation.
Canada
Ontario provincial procurement creates entry points for multi-site instrument leasing contracts through decentralized health authority structures. Health Canada and EPA joint oversight elevates environmental compliance to a procurement gate for reagent disposal protocols. British Columbia purchasing committees weight sustainability documentation in competitive bid scoring for distributed testing locations.
Mexico
Border state health infrastructure investments expand point-of-care deployment for infectious disease screening in maquiladora corridor clinics. Federal health secretariat regulations align with FDA CLIA waiver standards to facilitate cross-border instrument certification. Mexico City metropolitan hospitals anchor demand for connected glucose meters and pregnancy tests with smartphone integration.
North America Point of Care Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument placement and consumable revenue streams. The vendor base clusters around three strategic archetypes: diversified conglomerates with extensive installation networks, molecular diagnostics specialists with miniaturized PCR platforms, and integrated informatics providers tying point-of-care results into enterprise laboratory systems. Dominant competitive moves include asset-light leasing model expansion and pre-built HL7 connectivity module development for Cerner and Epic integration.
Within the diversified conglomerate tier, Abbott and Siemens Healthineers occupy positions defined by balance-sheet flexibility and instrument-installation density. QuidelOrtho Corporation exemplifies the molecular diagnostics specialist archetype, anchoring respiratory and infectious disease panel penetration in seasonal testing workflows. These three entities collectively represent the competitive intensity shaping urgent care network procurement decisions across Texas, Florida, and Ontario.
| Leading Market Players |
|---|
| Abbott |
| BD |
| Siemens Healthineers |
| bioMérieux |
| F. Hoffmann-La Roche |
| Danaher Corporation |
| QuidelOrtho Corporation |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Others |
Value Network & Pricing Analysis
Undercapacity in CLIA-waived molecular assay production across Texas and Florida manufacturing clusters is compressing supplier margins while amplifying pricing power for instrument-leasing incumbents with captive consumable streams. FDA clearance backlogs and cold-chain infrastructure gaps are forcing buyers into premium service tiers that bundle reagent stability guarantees with hardware placement.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared platforms and economy-grade research-use-only devices, with CLIA waiver status commanding 40-60% price premiums in urgent care procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by connectivity integration and enterprise LIS compatibility, with Epic and Cerner pre-built modules anchoring the top tier. Cost compression in standard-tier immunoassay consumables is intensifying because of Medicare fee schedule compression and group purchasing organization consolidation. Hospital point-of-care programs exhibit lowest price sensitivity due to bundled contractual purchasing, while independent urgent care chains in Arizona and Nevada face acute margin pressure from reagent spoilage costs.
Supply Chain Analysis
Export control restrictions on miniaturized thermal cycler components and isothermal amplification enzymes are constraining cross-border flows from EU and Japanese specialty chemical suppliers into North American cartridge manufacturing. Geographic supply concentration centers on Massachusetts and California for microfluidic chip fabrication, with reagent formulation anchored in North Carolina and Illinois chemical processing corridors. Raw material dependencies include photolithography-grade silicon wafers, stabilized polymerase enzymes, and fluorescence detection dyes. Single-source vulnerability in PCR enzyme supply creates chokepoint exposure during pandemic demand surges. Distribution runs through Cardinal Health and McKesson medical-surgical divisions into hospital-affiliated urgent care networks, with direct-to-site cold chain logistics increasingly bundled into instrument lease agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA regulatory affairs specialists with CLIA waiver submission experience is constraining product launch velocity and amplifying first-mover advantages for incumbents with established 510(k) pathways. Firms that capture this talent pool or automate submission workflows will outpace competitors in molecular assay commercialization.
For Market Incumbents: Build switching-cost moats through pre-integrated HL7 connectivity modules that embed point-of-care results directly into Cerner and Epic workflows, raising replacement costs for hospital systems. Expand consumable-only contract structures that decouple instrument pricing from reagent revenue, defending against emerging entrants with asset-light leasing models. Threat of miniaturized isothermal amplification platforms from specialized molecular diagnostics firms demands accelerated R&D in sample-to-answer automation. Channel control through exclusive urgent care network partnerships in Texas and Florida represents the priority defensive lever. For New Entrants and Emerging Players: Pursue white-space opportunity in Ontario provincial procurement, where decentralized health authority structures create entry points outside US competitive intensity with lower incumbent saturation. Target home care connectivity integration for smartphone-linked glucose meters and pregnancy tests, bypassing hospital purchasing committees entirely. Employer wellness programs in California and Illinois present the most penetrable segment for CLIA-waived cholesterol testing panels. Go-to-market angle should emphasize EPA pre-validated waste management protocols that satisfy Health Canada environmental compliance gates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across molecular diagnostics miniaturization as cartridge manufacturing scales and semiconductor fabrication partnerships reduce in-house capex requirements. Long-term viability over the next decade hinges on recurring consumable revenue streams rather than instrument placement economics, favoring targets with locked-in hospital system contracts. Acquisition target archetype: mid-cap firms with FDA-cleared respiratory panels and established urgent care network density in seasonal demand markets. Signal to watch is CMS reimbursement determination velocity for waived test categories, which dictates sustainable volume penetration outside central laboratory economics.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Acceleration | FDA streamlined clearances compress time-to-market for PCR-miniaturized platforms entering urgent care environments. |
| Enterprise LIS Integration Partnership | Pre-built HL7 modules for Cerner and Epic systems raise switching costs and embed instruments into hospital workflows. |
| Multi-Site Instrument Leasing Expansion | Asset-light models in Ontario and British Columbia exploit decentralized provincial procurement outside US competitive intensity. |
| Home Care Connectivity Development | Smartphone-linked glucose meters open direct-to-patient revenue streams bypassing traditional hospital purchasing channels. |
| EPA Compliance Pre-Validation | Pre-validated waste management protocols satisfy Health Canada environmental gates for distributed testing location contracts. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS Medicare fee schedules, and Health Canada medical device licensing records preceded structured interviews with hospital point-of-care program directors, urgent care network operations managers, GPO contracts specialists, and biomedical engineers at instrument manufacturers. Primary fieldwork with clinical laboratory scientists and provincial procurement officers in Ontario and British Columbia validated secondary findings on competitive dynamics. Bottom-up instrument placement counts across Texas, Florida, and Ontario urgent care networks were triangulated against top-down revenue estimates from SEC filings and trade association data.
Forecast assumptions held FDA CLIA waiver pathway velocity and CMS reimbursement determination timelines constant while varying molecular diagnostics adoption curves and seasonal infectious disease testing demand across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user category, and application workflow, with regulatory pathway tier as an industry-specific cross-cutting variable. CAGRs were derived from logistic diffusion curves fitted to historical instrument placement data and consumable revenue per installed base. Industry-specific forecast inputs incorporated PCR-miniaturization cost decline trajectories and isothermal amplification chemistry maturation timelines.
Sensitivities concentrate around FDA clearance backlog duration, CMS fee schedule compression magnitude, and cold chain infrastructure investment rates in distributed ambulatory settings. Forecasts reflect documented assumptions regarding CLIA personnel certification availability and enterprise LIS integration complexity. Material shifts in FDA oversight stringency for molecular assay waived status or provincial procurement decentralization in Canada would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
D-Dimer Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Bilirubin Blood Test Market