
 Sperm Count Test Market | 2026-2036
Sperm Count Test Market Size, Share, and Industry Trends Forecast 2026-2036
Sperm Count Test Market Analytics
Multi-source procurement for semen analysis consumables is repositioning how fertility networks secure reagent supplies. Medical Electronic Systems leverages its installed base of automated analyzers to sustain recurring revenue across European fertility clinics. Hamilton Thorne anchors North American laboratory demand through computer-assisted sperm analysis platforms with embedded software ecosystems. SwimCount competes in the direct-to-consumer channel with disposable cartridge formats that bypass clinic infrastructure entirely.
A sperm count test quantifies spermatozoa concentration per milliliter of semen, typically employing hemocytometer grids or flow cytometric counting, to assess male factor infertility in clinical and research settings. The analysis measures motility percentage, morphology classification, and total motile count to inform treatment pathways ranging from lifestyle intervention to assisted reproductive technology. Home Testing Kits capture widening consumer interest as privacy preferences and telehealth reimbursement expand, though Laboratory Testing Kits retain higher diagnostic fidelity for clinical decision-making. Computer-Assisted Sperm Analysis dominates technology revenue due to standardized motility scoring and reduced inter-technician variability, while Mobile Testing Devices represent the fastest-growing category as smartphone-integrated optics improve.
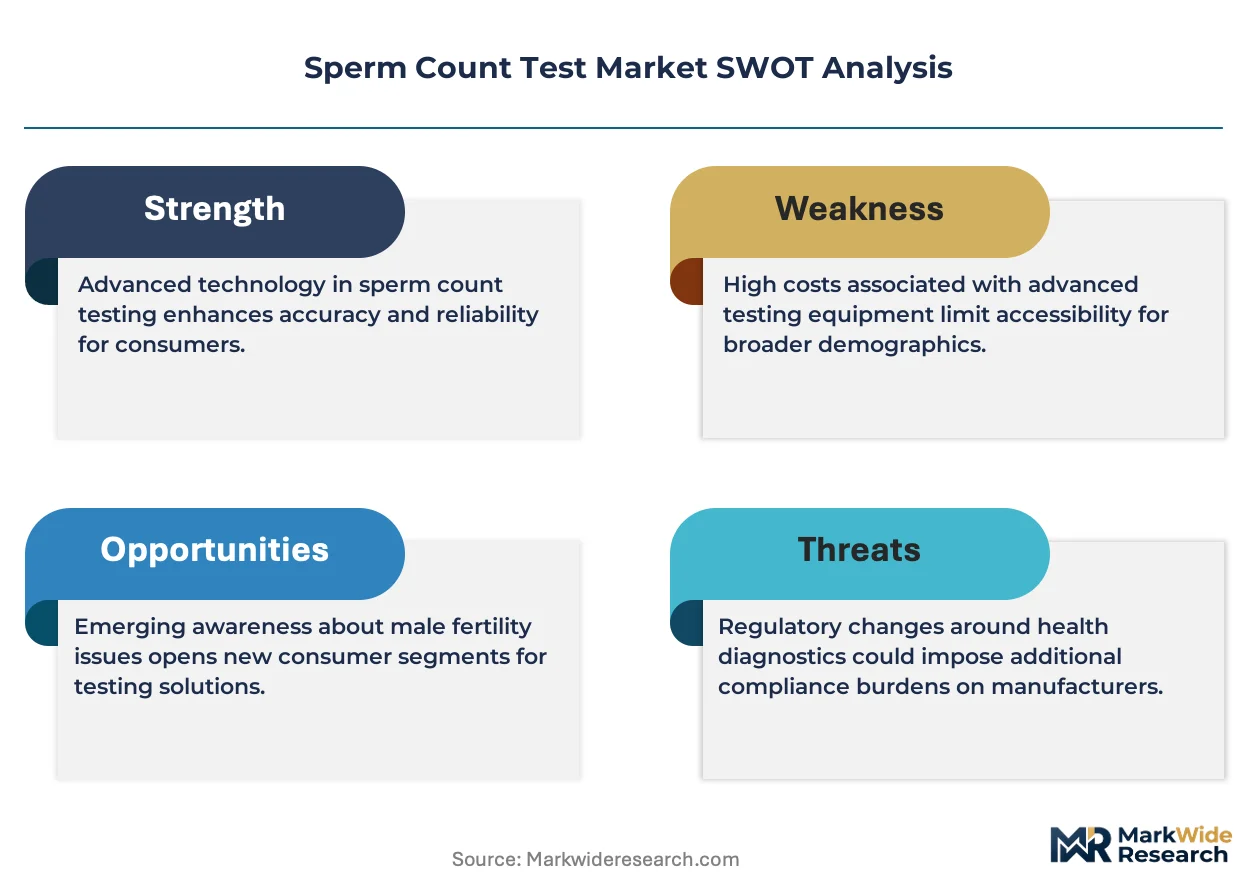
The FDA regulates sperm count tests marketed for clinical use as Class II medical devices requiring 510(k) premarket notification, while the European Medical Device Regulation imposes stricter clinical evidence standards for in vitro diagnostic devices including semen analysis systems. The EPA's Good Laboratory Practice standards shape research institution procurement criteria for reproductive toxicology studies. Stakeholders must monitor evolving home-use labeling requirements and telehealth reimbursement policies that will determine channel economics between clinical and consumer segments.
Market Dynamics
Telehealth reimbursement expansion and employer-sponsored fertility benefits in the United States are compressing diagnostic timelines and pulling testing volume toward at-home formats, forcing manufacturers to split R&D budgets between clinical-grade precision and consumer-accessible design.
Growth Catalysts
- Delayed Parenthood Patterns:Couples across developed economies are pursuing diagnostic clarity earlier in family planning, expanding fertility clinic throughput and downstream testing demand.
- FDA 510(k) Pathway Clarity:The agency's evolving guidance on direct-to-consumer reproductive health devices is reducing regulatory uncertainty for manufacturers entering home-use segments.
- Smartphone-Integrated Optics:Mobile Testing Devices leverage improved CMOS sensors and AI-assisted image analysis to deliver laboratory-comparable motility scoring without capital equipment.
Market Restraints
- Reagent Supply Concentration:European fertility networks face vulnerability from single-source dependencies for hemocytometer consumables and specialized staining media.
- Clinical Validation Burden:The European Medical Device Regulation imposes extended clinical evidence timelines for in vitro diagnostic devices, delaying product launches by 18-36 months.
- Substitute Diagnostic Pathways:Direct hormone assays and genetic screening for male factor infertility capture budget share from traditional semen analysis in premium clinic segments.
Strategic Opportunities
- Underpenetrated Rural Diagnostics:India and Southeast Asian markets lack distributed andrology infrastructure, creating white space for portable analyzer deployment through public health networks.
- Telehealth Integration Mandates:US state-level reimbursement parity laws for remote reproductive health services are accelerating channel partnerships between test manufacturers and virtual clinic platforms.
- AI-Cloud Convergence:Machine learning algorithms trained on multi-site motility datasets enable centralized quality control across distributed testing locations, reducing technician training requirements.
Industry Challenges
- Embryologist Training Pipeline:Shortages of certified andrologists capable of manual morphology assessment create bottlenecks for high-complexity laboratory operations.
- Legacy LIS Integration:Computer-Assisted Sperm Analysis platforms require costly middleware development to interface with established fertility clinic electronic medical record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sperm Count Test Market |
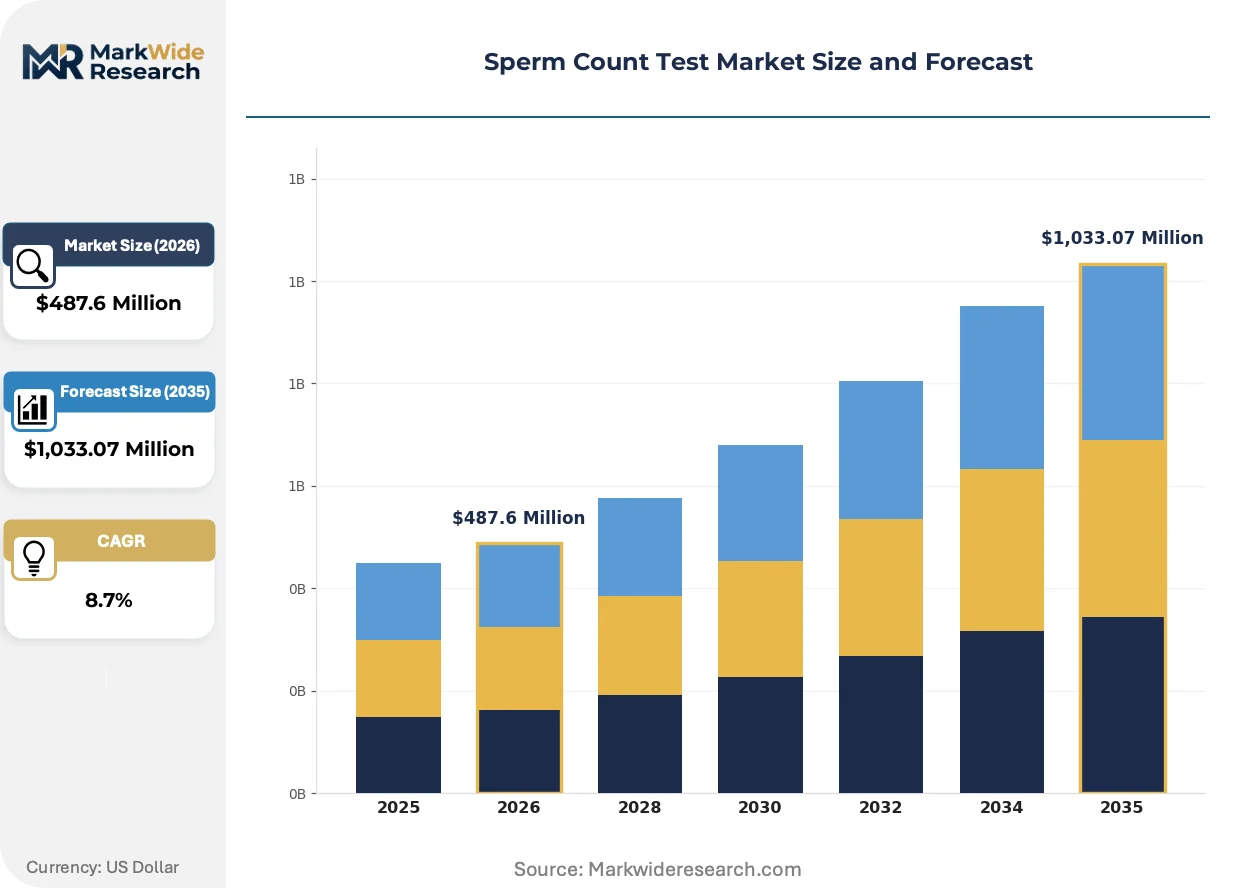
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Testing Kits, Laboratory Testing Kits, Semen Analysis Systems, Mobile Testing Devices Technology: Colorimetric Method, Computer-Assisted Sperm Analysis, Flow Cytometry, Microscopic Analysis End User: Hospitals, Fertility Clinics, Diagnostic Laboratories, Research Institutions Distribution Channel: Online Retail, Pharmacies, Direct Sales, Medical Supply Distributors |
| Companies Covered | Medical Electronic Systems, ExSeed Health, Hamilton Thorne, Artron Laboratories, AB ANALITICA, SwimCount, Olympus Corporation, Microptic, Sandstone Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sperm Count Test Market Evolving Landscape
Diagnostic workflows are fragmenting across physical sites as remote sample collection, centralized image analysis, and distributed result delivery recombine into hybrid service models. This reconfiguration demands new technical architectures and commercial partnerships.
Computer-Assisted Sperm Analysis is consolidating market position as fertility clinics prioritize standardized motility scoring and inter-laboratory reproducibility. Large network providers in the United States and Germany are mandating CASA platform standardization across satellite locations. This technology is compressing demand for manual hemocytometer methods and technician-dependent morphology classification.
The European Medical Device Regulation's 2021 implementation timeline continues to reshape competitive access, as stricter clinical evidence requirements for in vitro diagnostic devices filter out smaller manufacturers lacking trial infrastructure. Medium-scale European fertility networks are extending equipment replacement cycles rather than navigating new certification burdens. The directive is accelerating consolidation among IVD suppliers serving the andrology segment.
Consumer privacy preferences are redirecting initial diagnostic contact away from clinic-based encounters toward direct-to-consumer channels where sample collection occurs at home. Telehealth platforms in the United States are unbundling the traditional fertility consultation, with sperm testing now frequently ordered before first in-person specialist visits. This pattern concentrates volume growth in disposable cartridge formats and smartphone-integrated devices.
Sperm Count Test Market Segmentation
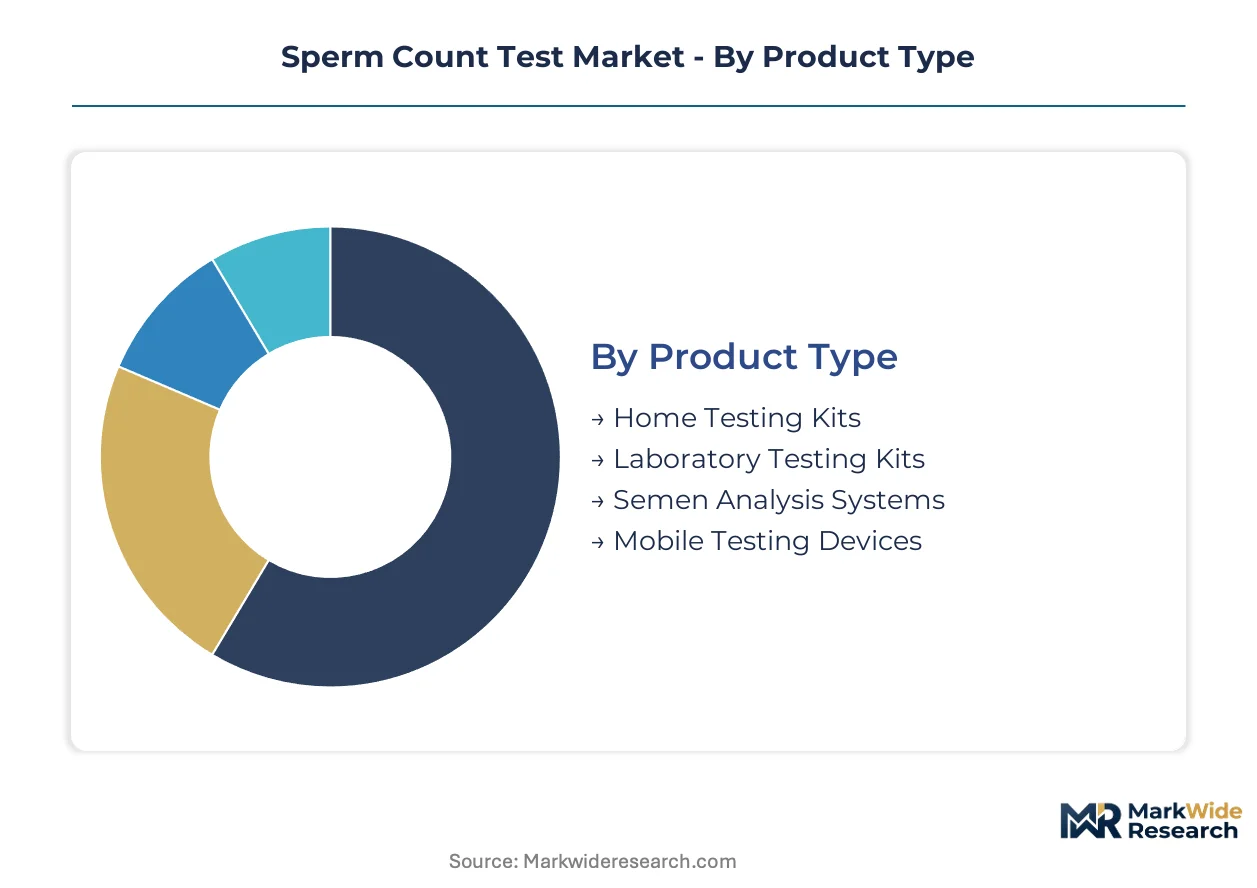
Segmentation in the sperm count test market reveals how regulatory pathways, clinical workflows, and consumer privacy preferences split demand across divergent product formats and channel structures. Manufacturers must navigate distinct validation requirements and reimbursement logics for each segment cluster.
Product Type:
FDA 510(k) clearance applies to Laboratory Testing Kits and Semen Analysis Systems marketed for clinical diagnostic use, while Home Testing Kits face evolving direct-to-consumer oversight that delays market entry for new entrants.
- Laboratory Testing Kits:Comprehensive reagent panels calibrated for hemocytometer grids and specialized staining protocols deliver diagnostic-grade precision. Demand concentrates in United States fertility networks where employer-sponsored benefits normalize pre-treatment screening. FDA 510(k) premarket notification requirements extend development timelines by 12-18 months for novel assay formats.
- Home Testing Kits:Disposable cartridge formats integrate sample collection chambers with lateral flow or colorimetric readouts for privacy-conscious consumers. United States telehealth platforms drive volume as state-level reimbursement parity laws expand remote reproductive health access. Regulatory uncertainty around home-use labeling continues to reshape competitive access.
- Semen Analysis Systems:Automated platforms with embedded software ecosystems serve high-throughput fertility clinic networks.
- Mobile Testing Devices:Smartphone-integrated optics with AI-assisted image analysis bypass capital equipment requirements.
Laboratory Testing Kits sit at the top of the volume ranking, with Mobile Testing Devices climbing the fastest.
Technology:
Cost tier stratification separates capital-intensive platforms from consumable-heavy methods, with reimbursement rates determining clinical adoption patterns across healthcare systems.
- Computer-Assisted Sperm Analysis:Standardized motility scoring algorithms reduce inter-technician variability below 5% for progressive motility classification. Large United States network providers mandate CASA standardization across satellite locations to ensure inter-laboratory reproducibility. Platform costs exceed $75,000 per installation, restricting deployment to high-volume fertility centers.
- Flow Cytometry:Fluorescence-activated cell sorting enables simultaneous DNA fragmentation index and viability assessment. Research Institutions in Germany and the United Kingdom drive procurement for reproductive toxicology studies under OECD test guideline compliance. Instrument maintenance contracts and specialized operator training create recurring cost burdens.
- Colorimetric Method:Lateral flow immunoassays provide rapid qualitative results for initial screening applications.
- Microscopic Analysis:Manual hemocytometer counting retains utility in resource-constrained settings with limited capital budgets.
Computer-Assisted Sperm Analysis dominates current revenue, with Flow Cytometry gaining share fastest in premium laboratory segments.
End User:
Customer type determines sensitivity to turnaround time, with fertility clinics prioritizing rapid results and research institutions accepting extended protocols for methodological rigor.
- Fertility Clinics:Integrated andrology laboratories require same-day result delivery to maintain treatment cycle coordination. United States clinic networks expand throughput as couples delay parenthood and seek diagnostic clarity earlier. Embryologist training shortages create operational bottlenecks for manual morphology assessment.
- Diagnostic Laboratories:Centralized processing facilities achieve economies of scale through batch analysis of referred specimens. Reference laboratories in India and Southeast Asia lack distributed andrology infrastructure, creating white space for portable analyzer deployment. Quality control standardization across multiple collection sites demands AI-cloud convergence for centralized oversight.
- Hospitals:General pathology departments handle sporadic male infertility referrals within broader diagnostic portfolios.
- Research Institutions:Reproductive toxicology studies require GLP-compliant documentation under EPA standards.
Fertility Clinics sit at the top of the volume ranking, with Diagnostic Laboratories climbing the fastest in emerging markets.
Distribution Channel:
Geography shapes channel viability, with online retail penetration varying sharply by national postal infrastructure and cold chain reliability for biological specimens.
- Direct Sales:Manufacturer field forces negotiate multi-year service contracts for Semen Analysis Systems with large fertility network providers. United States group purchasing organizations consolidate procurement for independent clinic chains. Relationship-based selling sustains pricing power against distributor intermediation.
- Online Retail:Direct-to-consumer platforms capture privacy-sensitive demand for Home Testing Kits with discreet packaging and telehealth integration. United States employer-sponsored fertility benefits increasingly reimburse at-home testing through specialized digital health marketplaces. Logistics complexity limits expansion to markets with unreliable specimen transport infrastructure.
- Pharmacies:Retail pharmacy chains stock entry-level screening products for walk-in male health consultations.
- Medical Supply Distributors:Regional wholesalers serve mid-sized fertility clinics with reagent replenishment and emergency equipment support.
Direct Sales sits at the top of the volume ranking, with Online Retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge fertility technology cluster anchors North American sperm count test demand, with employer-sponsored benefits and telehealth reimbursement creating concentrated procurement pull. United States fertility networks drive volume for both clinical-grade analyzers and direct-to-consumer formats. Germany's precision manufacturing base supplies automated platform components to European fertility clinics.
United States
Employer-sponsored fertility benefits at Fortune 500 companies normalize pre-treatment screening, expanding fertility clinic throughput. The FDA's evolving 510(k) guidance for direct-to-consumer reproductive health devices reduces regulatory uncertainty for home-use entrants. The Boston-Cambridge corridor concentrates venture-backed mobile testing device developers.
Germany
Large fertility network providers mandate Computer-Assisted Sperm Analysis standardization across satellite locations for inter-laboratory reproducibility. The European Medical Device Regulation imposes stricter clinical evidence standards for in vitro diagnostic devices, filtering out smaller manufacturers. The Munich-Stuttgart axis hosts precision optics suppliers serving automated analyzer OEMs.
United Kingdom
Research institutions drive procurement for reproductive toxicology studies under OECD test guideline compliance. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit device registration requirements for semen analysis systems. London's academic medical centers anchor GLP-compliant toxicology service demand.
India
Diagnostic laboratories in metropolitan areas lack distributed andrology infrastructure, creating white space for portable analyzer deployment through public health networks. The Central Drugs Standard Control Organization regulates in vitro diagnostic device import and distribution. Maharashtra's hospital networks expand fertility service capacity in Mumbai and Pune corridors.
Japan
Delayed parenthood patterns among urban professionals expand fertility clinic consultation volumes and downstream testing demand. The Pharmaceuticals and Medical Devices Agency maintains stringent quality management system requirements for automated semen analyzers. Tokyo-Osaka fertility network consolidation drives platform standardization mandates.
Sperm Count Test Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and channel access. The vendor base organizes into three tiers: automated platform specialists with embedded software ecosystems, disposable cartridge manufacturers targeting direct-to-consumer channels, and precision optics suppliers serving OEM assembly. Consolidation pressures intensify as the European Medical Device Regulation's clinical evidence requirements favor trial-capable incumbents. Geographic expansion and strategic partnerships represent dominant competitive moves as manufacturers navigate divergent FDA and EMA pathways.
Within the automated platform tier, Medical Electronic Systems and Hamilton Thorne occupy positions sustained by installed base recurring revenue and laboratory relationship depth. SwimCount exemplifies the direct-to-consumer archetype with cartridge formats that bypass clinic infrastructure entirely. Olympus Corporation anchors the precision optics supply position for microscope-integrated analysis systems.
| Leading Market Players |
|---|
| Medical Electronic Systems |
| ExSeed Health |
| Hamilton Thorne |
| Artron Laboratories |
| AB ANALITICA |
| SwimCount |
| Olympus Corporation |
| Microptic |
| Sandstone Diagnostics |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up fertility laboratory networks in the United States and Germany exercise concentrated procurement power over semen analysis consumables, compressing reagent margins while simultaneously locking in multi-year service contracts for automated analyzer platforms that insulate capital equipment pricing from spot-market volatility.
Pricing Analysis
Input-cost pass-through for specialized staining media and CMOS sensor modules determines tiered pricing across analyzer platforms, with FDA 510(k) certification tier and inter-laboratory reproducibility guarantees serving as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates CASA platforms with embedded AI from manual hemocytometer kits and disposable smartphone cartridges. Pricing pressure stems from employer-sponsored fertility benefits normalizing at-home testing reimbursement, forcing clinical-grade manufacturers to defend volume through service bundling. Diagnostic laboratories in emerging markets exhibit highest price sensitivity, while United States fertility network providers prioritize standardization over unit cost.
Supply Chain Analysis
Specialized optical component supply rests on precision manufacturing clusters in Germany, Japan, and the United States, with Munich-Stuttgart axis suppliers feeding automated analyzer OEMs and Tokyo-based CMOS foundries anchoring smartphone-integrated device production. Hemocytometer glassware, fluorescence staining reagents, and AI training datasets constitute critical input dependencies. Single-source vulnerability concentrates in European hemocytometer consumables, where single-source dependencies expose fertility networks to disruption. Distribution runs through direct sales forces for capital equipment, medical supply distributors for reagent replenishment, and online retail platforms for direct-to-consumer cartridge formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sperm count test market functions as a stable compounder, with delayed parenthood patterns across developed economies generating durable diagnostic demand that transcends cyclical healthcare spending fluctuations.
For Market Incumbents: Acquire AI-cloud convergence capabilities to centralize quality control across distributed testing locations, defending against smartphone-integrated device entrants that bypass clinic infrastructure entirely. Pursue backward integration into precision optics manufacturing to secure component supply and capture margin from German and Japanese specialty suppliers. Investment in FDA 510(k) premarket notification infrastructure creates regulatory moats against smaller competitors lacking trial capabilities. For New Entrants and Emerging Players: Capture underpenetrated rural diagnostics in India and Southeast Asia through portable analyzer deployment partnerships with public health networks, where distributed andrology infrastructure remains absent. Target United States telehealth platform integration as the most penetrable channel, leveraging state-level reimbursement parity laws for remote reproductive health services. Position disposable cartridge formats with smartphone connectivity to bypass capital equipment barriers and clinic relationship requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European IVD suppliers facing extended MDR clinical evidence timelines, creating distressed acquisition opportunities for trial-capable consolidators. Long-term viability rests on telehealth reimbursement permanence and employer benefit expansion rather than discretionary fertility spending. Watch FDA guidance evolution on direct-to-consumer reproductive health devices as the inflection signal determining channel economics between clinical and consumer segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Secures clinical diagnostic claims required for United States fertility network procurement contracts. |
| CE Marking Under MDR | Enables European market access amid stricter clinical evidence standards filtering smaller competitors. |
| Telehealth Platform Partnership | Captures volume growth from reimbursement parity laws expanding remote reproductive health access. |
| AI-Cloud Quality Control Development | Reduces technician training requirements across distributed laboratory networks through centralized oversight. |
| Disposable Cartridge Manufacturing Scale-Up | Meets privacy-driven demand for home testing formats that bypass clinic infrastructure entirely. |
Research Methodology
Bottom-up fertility clinic throughput modeling reconciled against top-down automated analyzer installation tracking forms the analytical core, combining primary interviews with andrologists, embryologists, GPO contracts managers, and telehealth platform executives with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and employer benefits plan disclosures. Triangulation across end-user demand signals and manufacturer supply-side data ensures coverage of both clinical-grade and direct-to-consumer channel dynamics.
Input-output matrix framing connects semen analysis test volumes to underlying population demographics, fertility treatment initiation rates, and technology substitution patterns across the projection horizon. Segmentation dimensions span product type, technology platform, end-user setting, and distribution channel, with CAGRs derived from trend extrapolation of clinic network expansion, telehealth reimbursement policy trajectories, and smartphone-integrated device adoption curves. Forecast inputs incorporate regulatory pathway timelines, embryologist training pipeline constraints, and reagent supply concentration metrics.
Regulatory guidance revisions, telehealth reimbursement policy reversals, and single-source supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding FDA and EMA pathway stability, employer benefit expansion continuity, and optical component supply reliability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
UAE in Vitro Diagnostics Market