
 Global STD Diagnostics Market | 2026-2036
Global STD Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global STD Diagnostics Market Foresight
The EU Green Deal is shifting procurement criteria across European healthcare systems toward sustainable diagnostic supply chains. Abbott Laboratories leverages its point-of-care manufacturing scale to dominate decentralized testing networks in emerging markets. F. Hoffmann-La Roche AG anchors its position through sustained R&D intensity in nucleic acid amplification platforms. Becton Dickinson and Company competes through specialized specimen collection systems that integrate with automated laboratory workflows.
STD diagnostics encompasses laboratory and point-of-care technologies that detect bacterial, viral, and parasitic sexually transmitted infections through nucleic acid amplification, immunoassay, or culture-based methods, typically requiring specimen collection within 72 hours of exposure for optimal sensitivity. These systems serve clinical decision-making, epidemiological surveillance, and public health reporting functions across healthcare settings. Nucleic acid amplification tests capture the highest-margin segment due to multiplexing capabilities and superior sensitivity for asymptomatic screening. Rapid test kits extend access to resource-limited settings where laboratory infrastructure remains sparse. Immunoassays retain substantial volume in blood bank and prenatal screening protocols where cost efficiency outweighs turnaround time requirements.
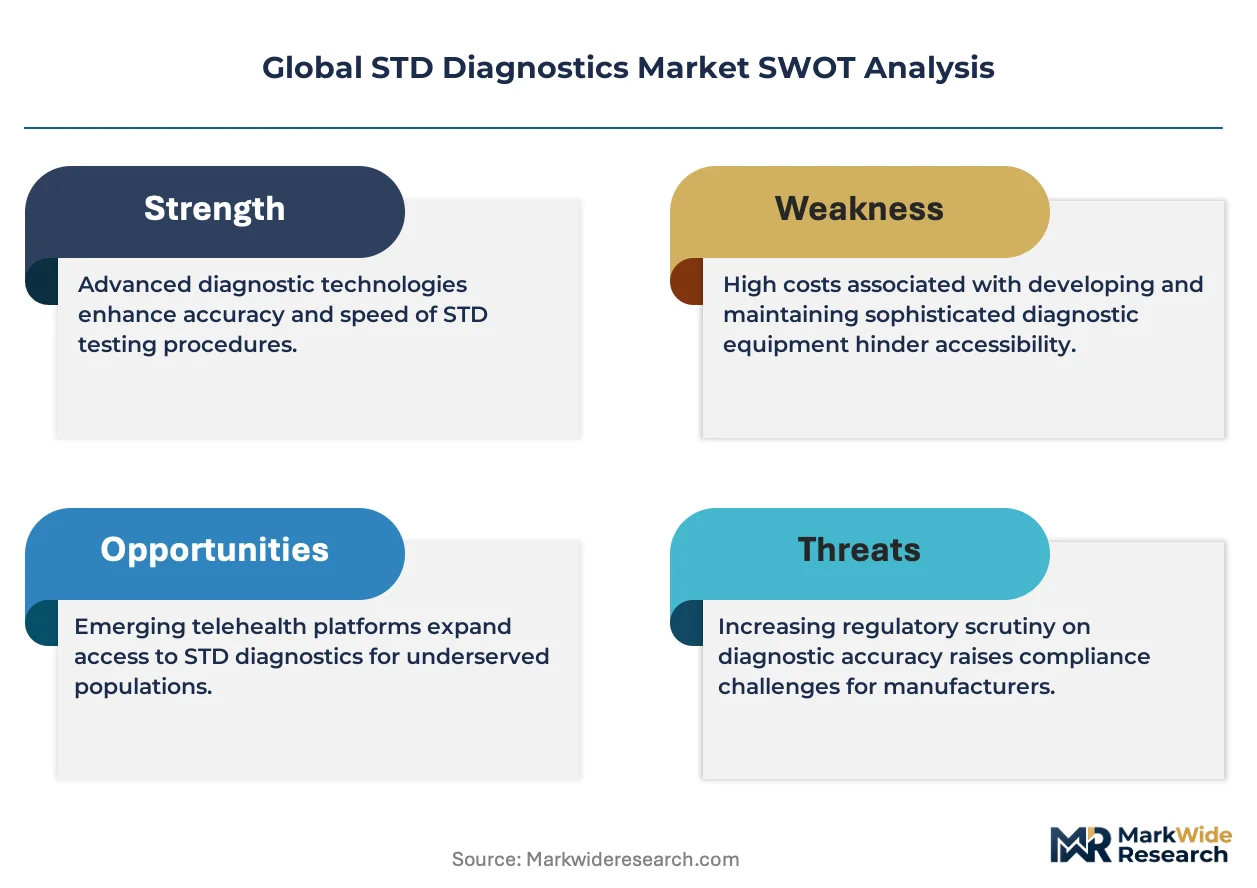
The FDA governs premarket authorization and clinical trial design for novel STD diagnostic platforms, while the WHO issues target product profiles that shape procurement criteria in low- and middle-income countries. REACH and RoHS frameworks in Europe restrict hazardous substances in diagnostic device manufacturing, compelling suppliers to reformulate reagent chemistries and electronic components. Stakeholders must monitor evolving CE marking requirements under the EU Medical Device Regulation as notified bodies apply stricter clinical evidence standards to infectious disease assays. The central strategic question involves balancing multiplex test menu expansion against regulatory complexity and reimbursement uncertainty in fragmented national healthcare systems.
Market Dynamics
Decentralized diagnostic networks are compressing laboratory infrastructure requirements while nucleic acid amplification platforms extend multiplexing capabilities into point-of-care settings. The tension between centralized high-throughput systems and distributed rapid testing reshapes capital allocation across public health procurement frameworks.
Growth Catalysts
- National AIDS Control Programme:India's government scales decentralized diagnostic networks across rural districts, expanding screening access beyond urban hospital laboratories.
- WHO Target Product Profiles:Updated guidelines for STI testing streamline procurement criteria in low- and middle-income countries, accelerating assay validation pathways.
- Multiplexing Technology:Nucleic acid amplification platforms now detect multiple pathogens per specimen, reducing per-test costs for sexual health clinics.
Market Restraints
- Reagent Supply Concentration:Polymerase and enzyme manufacturing clusters in Germany and the United States create single-source dependencies for amplification chemistries.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for infectious disease assays extend CE marking timelines by 18-24 months.
- Specimen Stability Windows:Nucleic acid degradation within 72 hours of collection limits rural deployment without cold chain infrastructure.
Strategic Opportunities
- Sub-Saharan Africa Laboratory Gap:Underpenetrated diagnostic infrastructure creates demand for heat-stable rapid test kits requiring no refrigeration.
- Self-Collection Channel:Mail-in specimen kits bypass clinic visits entirely, capturing privacy-sensitive demographics in urban Brazil and South Africa.
- EU Green Deal Procurement:Sustainable supply chain criteria favor manufacturers with reformulated reagent chemistries and reduced hazardous substance profiles.
Industry Challenges
- ISO 15189 Accreditation Timeline:Laboratory quality management certification for molecular diagnostics requires 12-18 months of documented proficiency testing.
- Legacy LIS Integration:Automated laboratory information systems in older hospital networks resist API connectivity with newer cloud-based result platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global STD Diagnostics Market |
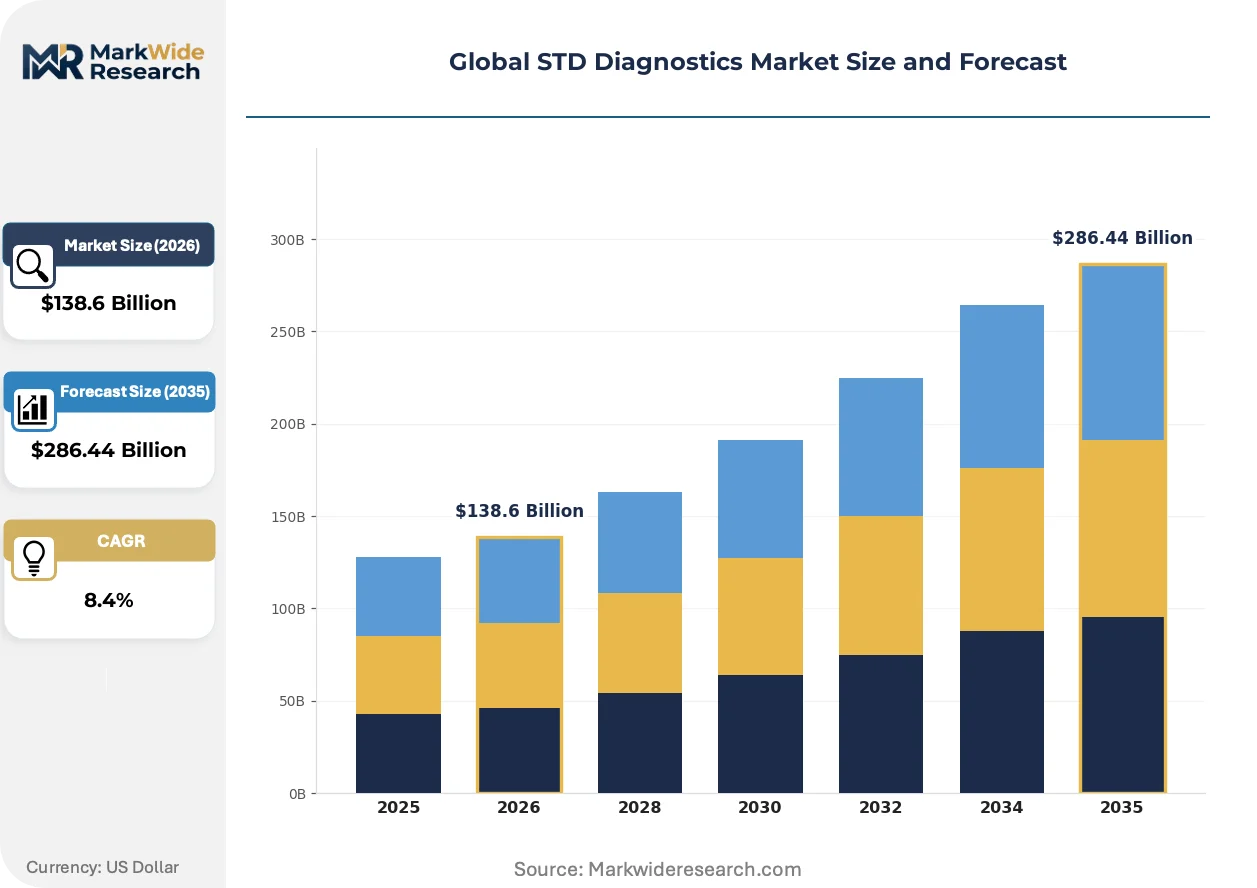
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $286.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, Nucleic Acid Amplification Tests, Immunoassays, Culture Tests, Microscopy Application: Chlamydia Detection, Syphilis Screening, Gonorrhea Identification, Herpes Testing, HIV Diagnosis End User: Diagnostic Laboratories, Sexual Health Clinics, Primary Care Centers, Public Health Agencies, Mobile Testing Units Deployment: Point-of-Care, Hospital Labs, Standalone Testing Facilities, Telemedicine Platforms, Community Health Programs |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Becton Dickinson and Company, Hologic Inc., bioMérieux SA, Siemens Healthineers, Bio-Rad Laboratories Inc., Danaher Corporation, Qiagen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global STD Diagnostics Market Shifts & Advancements
Digital connectivity and miniaturized molecular platforms are collapsing the distance between specimen collection and diagnostic result. These shifts reconfigure where testing occurs, who performs it, and how reimbursement flows follow.
Isothermal amplification chemistries bypass thermal cycling hardware entirely, enabling battery-operated devices for field deployment. Community health workers in Kenya and Nigeria adopt these platforms for same-result counseling sessions. Benchtop PCR systems is overtaking central laboratory workflows as the default configuration for district-level hospitals.
REACH and RoHS frameworks compel reformulation of electronic components and reagent stabilizers across European manufacturing. Suppliers face substance restriction deadlines for cadmium, lead, and certain phthalates in diagnostic device production. Multiplex cartridge manufacturers in the Netherlands and Switzerland accelerate green chemistry partnerships to maintain CE marking eligibility.
Self-pay testing models proliferate where public reimbursement excludes asymptomatic screening. Direct-to-consumer channels in the United Kingdom and Australia capture young adults avoiding primary care registration. Sexual health clinics respond with hybrid offerings: free clinician-collected specimens alongside paid expedited result services.
Global STD Diagnostics Market Segmentation
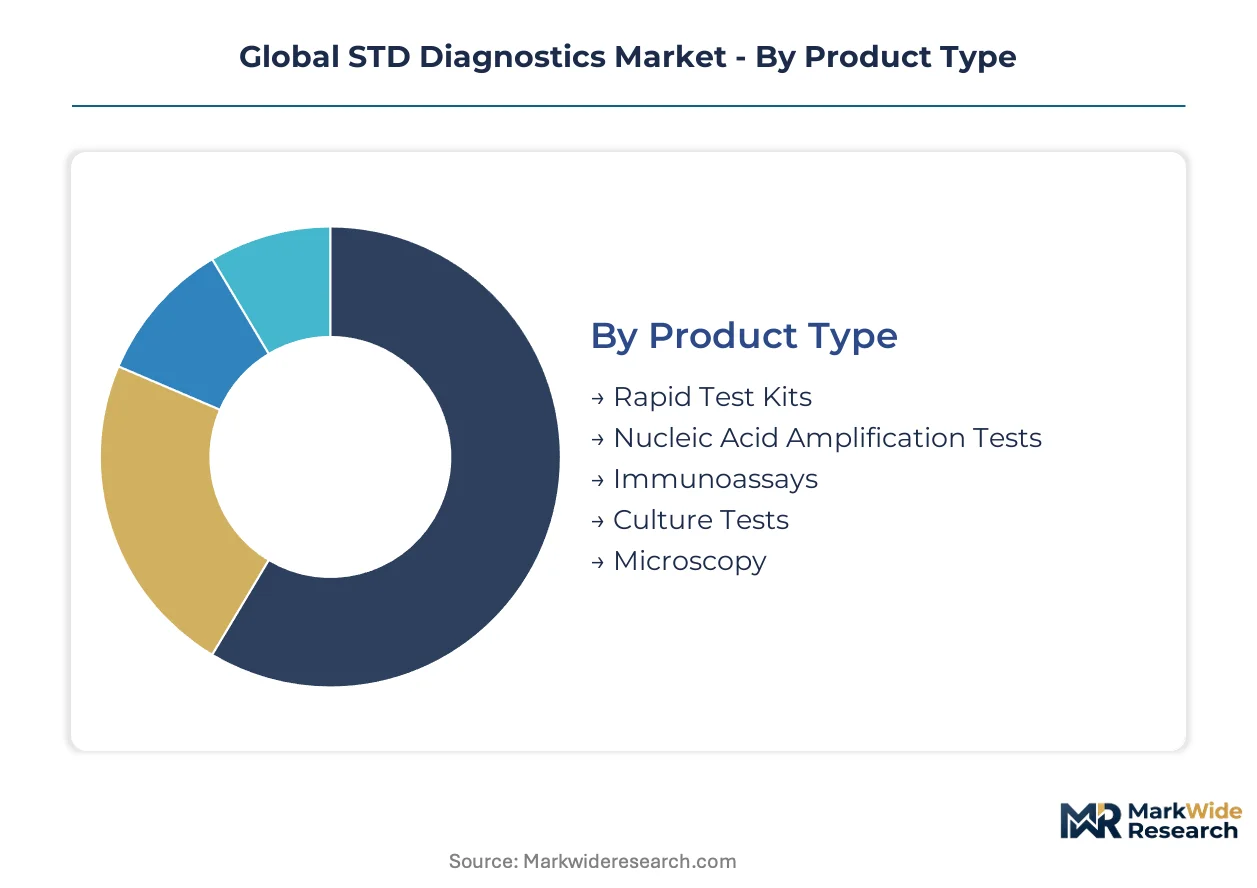
Technology selection in STD diagnostics tracks directly to infrastructure availability and turnaround requirements. Procurement patterns diverge sharply between centralized laboratory networks and decentralized screening programs.
Product Type:
Cost tier separates buyers seeking multiplex precision from those prioritizing field deployment speed.
- Nucleic Acid Amplification Tests:These platforms employ polymerase chain reaction and transcription-mediated amplification to detect pathogen-specific genetic material with sensitivity exceeding 95% for asymptomatic screening. Demand concentrates in urban hospital laboratories across Germany and Japan where high-throughput automation justifies capital investment and trained technologist staffing.
- Rapid Test Kits:Lateral flow immunoassays and dipstick formats deliver visual results within 20 minutes without instrumentation. Volume clusters in India's National AIDS Control Programme rural districts and Kenya's community health worker networks where cold chain absence and electricity intermittency exclude molecular alternatives.
- Immunoassays:Enzyme-linked immunosorbent assays and chemiluminescent platforms dominate blood bank screening protocols in Brazil and South Africa.
- Culture Tests:Traditional bacterial cultivation retains regulatory acceptance for antimicrobial susceptibility testing in tertiary care centers.
- Microscopy:Dark-field and fluorescent microscopy persists for syphilis confirmation in resource-constrained settings lacking molecular access.
Volume sits with Immunoassays; growth tilts toward Nucleic Acid Amplification Tests.
Application:
Screening intensity varies by disease burden visibility and public health prioritization in national control programs.
- HIV Diagnosis:Fourth-generation antigen-antibody combination assays and viral load quantification anchor the largest testing volume globally. Procurement concentrates through PEPFAR-funded programs in Nigeria and Tanzania alongside India's NACP centralized laboratory network.
- Chlamydia Detection:Nucleic acid amplification dominates asymptomatic screening in sexual health clinics across the United Kingdom and Australia where opportunistic testing captures young adult demographics.
- Gonorrhea Identification:Multiplex platforms combining Neisseria gonorrhoeae with Chlamydia trachomatis detection reduce per-test costs in urban United States public health laboratories.
- Syphilis Screening:Dual non-treponemal and treponemal algorithm testing persists in prenatal protocols across Latin America.
- Herpes Testing:Type-specific serologic assays serve symptomatic patient management in private clinic settings.
Procurement scale favors HIV Diagnosis; technology upgrade spending flows fastest into Chlamydia Detection.
End User:
Specimen handling capability and result turnaround requirements segment institutional buyers.
- Diagnostic Laboratories:Automated high-throughput systems process thousands of specimens daily with integrated laboratory information systems. These facilities anchor national reference networks in South Korea and Saudi Arabia where accreditation to ISO 15189 standards governs eligibility for insurance reimbursement.
- Sexual Health Clinics:Same-visit testing with rapid result disclosure supports partner notification and immediate treatment initiation. Australia's publicly funded clinic network and Brazil's Sistema Único de Saúde prioritize these settings for young adult access.
- Primary Care Centers:General practitioner offices in France and Spain adopt benchtop molecular platforms for opportunistic screening.
- Public Health Agencies:Surveillance and outbreak response drives centralized procurement in the United States CDC and Nigeria's disease control centers.
- Mobile Testing Units:Van-based and temporary outreach serves transient populations and rural access gaps in South Africa and Indonesia.
Test throughput concentrates in Diagnostic Laboratories; expansion investment targets Sexual Health Clinics.
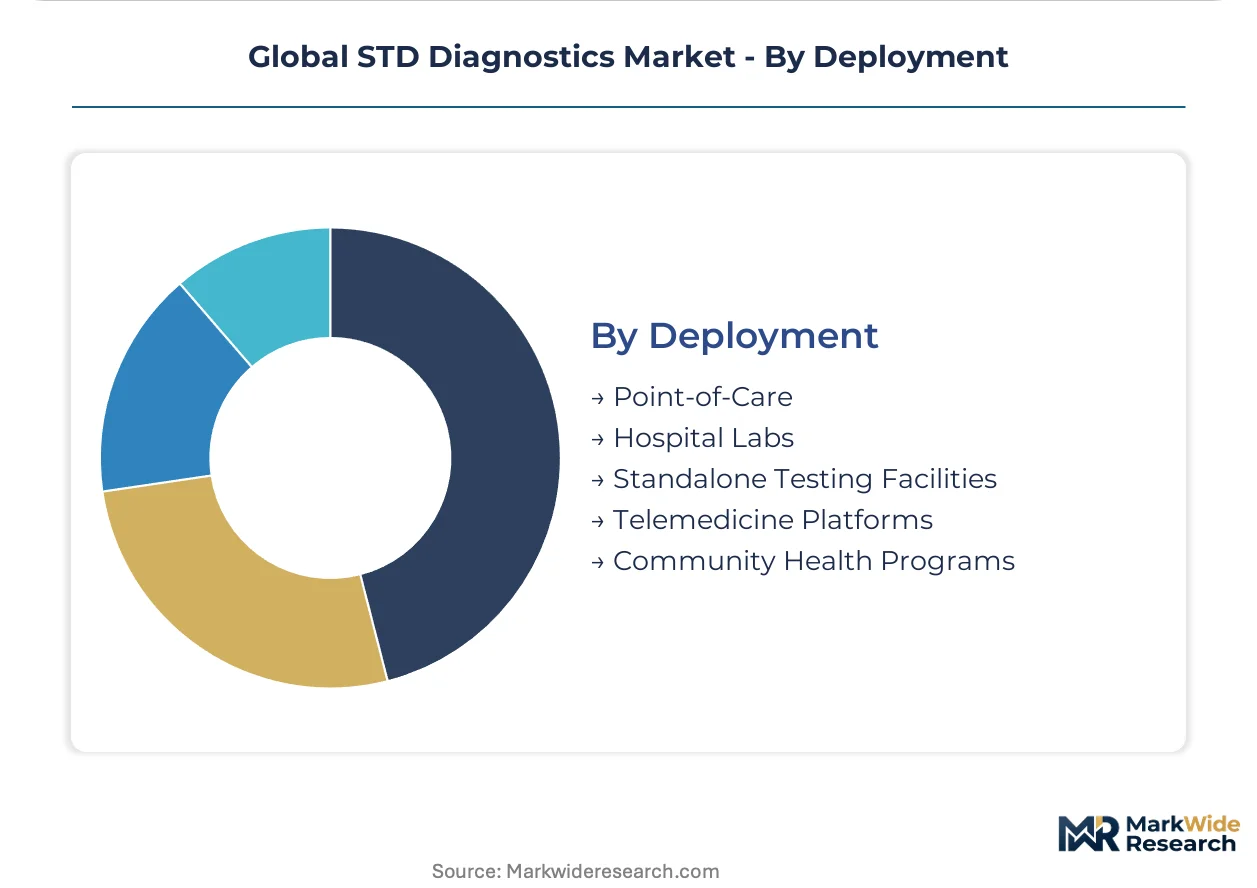
Deployment:
Physical infrastructure requirements and regulatory oversight intensity shape channel selection.
- Point-of-Care:CLIA-waived and CE-marked devices permit non-laboratory personnel operation in pharmacies, correctional facilities, and community venues. Kenya's community health strategy and the United Kingdom's pharmacy-based testing pilots demonstrate scale potential.
- Hospital Labs:Integrated health systems in the United States and Germany consolidate infectious disease diagnostics within centralized laboratory medicine departments.
- Standalone Testing Facilities:Dedicated sexual health laboratories in the Netherlands and Denmark optimize workflow for high-volume anonymous screening.
- Telemedicine Platforms:Mail-in self-collection kits with remote result delivery bypass geographic and stigma barriers in Australia and urban Brazil.
- Community Health Programs:Government-funded outreach in India and Ethiopia deploys rapid testing through trained lay workers.
Institutional volume flows through Hospital Labs; channel innovation accelerates fastest in Telemedicine Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American molecular diagnostics R&D, hosting contract research organizations that validate nucleic acid amplification platforms for FDA premarket authorization. The corridor feeds technology transfer into manufacturing networks across multiple continents.
United States
Sexual health clinics in New York and Los Angeles expand same-day testing menus as CDC surveillance data drives municipal procurement priorities. FDA premarket authorization pathways for multiplex STI panels compress validation timelines for manufacturers with breakthrough device designation. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing for amplification reagents serving domestic hospital networks.
Germany
University hospital laboratories in Berlin and Munich anchor reference testing volumes for antimicrobial susceptibility confirmation in gonorrhea cases. ECHA enforcement of REACH substance restrictions compels reagent manufacturers in the Rhine-Ruhr industrial belt to reformulate stabilizer chemistries ahead of 2026 deadlines. The Baden-Württemberg precision engineering corridor supplies thermal cycling hardware components to Asian point-of-care device assemblers.
India
The National AIDS Control Programme deploys decentralized testing to 600+ district hospitals as viral load monitoring scales beyond metropolitan reference centers. CDSCO streamlined diagnostic kit registration under the 2017 Medical Devices Rules accelerates import substitution for rapid HIV test kits. The Hyderabad-Genome Valley cluster manufactures indigenous nucleic acid extraction cartridges for government procurement tenders.
Brazil
Sistema Único de Saúde sexual health clinics in São Paulo and Rio de Janeiro integrate rapid syphilis screening into prenatal protocols as congenital case notification rises. ANVISA post-market surveillance requirements for in-vitro diagnostics strengthen quality enforcement across the São Paulo state industrial corridor. The Campinas biotechnology park hosts technology transfer partnerships for heat-stable rapid test manufacturing.
South Africa
PEPFAR-funded mobile testing units in KwaZulu-Natal and Gauteng provinces deploy community health workers with rapid result disclosure authority. The national health laboratory service ISO 15189 accreditation program extends molecular testing capability to 50+ district hospitals. The Cape Town biomedical research cluster validates point-of-care platforms for WHO prequalification submission.
Global STD Diagnostics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across multiplexing capability and regulatory certification density. The vendor base stratifies between diversified conglomerates with full diagnostic portfolios and specialized molecular testing houses with narrow assay menus. Three archetypes dominate: integrated life science conglomerates with vertical control over reagent supply, mid-scale platform specialists licensing amplification chemistries, and regional rapid test assemblers competing on distribution reach. Capacity expansion in point-of-care manufacturing and strategic partnerships for cold-chain-free specimen stabilization represent the dominant competitive moves.
Among diversified diagnostic conglomerates, Abbott Laboratories, F. Hoffmann-La Roche AG, and Danaher Corporation occupy positions spanning centralized laboratory automation through decentralized rapid testing networks. Abbott exemplifies the point-of-care scale archetype with manufacturing footprints calibrated to emerging market procurement volumes. Roche represents sustained R&D intensity in nucleic acid amplification platforms. Danaher sits within the life science tools-to-diagnostics integration model, leveraging subsidiary networks across specimen preparation and molecular detection workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Becton Dickinson and Company |
| Hologic Inc. |
| bioMérieux SA |
| Siemens Healthineers |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Qiagen N.V. |
| Others |
Supply & Pricing Matrix
Government procurement programs in India and Brazil anchor volume pricing for rapid test kits, compressing margins for manufacturers while nucleic acid amplification platforms command outcome-based premiums in German and Japanese hospital networks. The divergence between public tender pricing and private laboratory reimbursement creates tiered purchasing power across end-user segments.
Pricing Analysis
Outcome-based pricing tied to diagnostic sensitivity thresholds anchors contract negotiations for nucleic acid amplification platforms in sexual health clinics. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD certified multiplex systems from research-use-only reagents and unregulated rapid immunoassays. Pricing pressure stems from India's National AIDS Control Programme consolidated procurement, which aggregates district-level demand into single-source tenders. Public health agencies exhibit highest price sensitivity; tertiary care reference laboratories demonstrate lowest sensitivity due to bundled service contracts.
Supply Chain Analysis
Polymerase and reverse transcriptase enzyme manufacturing rests on specialty chemical producers in Germany, the United States, and Japan, creating concentrated input dependencies for amplification chemistry production. Lyophilized reagent stabilizers, precision-molded cartridge plastics, and thermal cycling hardware components feed into final assembly operations. Single-source vulnerability persists for heat-stable enzyme formulations protected by process trade secrets. Distribution runs through authorized distributor networks serving government procurement channels in emerging markets alongside direct sales teams for hospital laboratory accounts in OECD countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The STD diagnostics market functions as a vertical-integration race where control over reagent supply and specimen stabilization chemistry determines margin capture. Players are pursuing backward integration into polymerase manufacturing to escape single-source dependencies.
For Market Incumbents: Anchor market position through captive supply of amplification enzymes and strategic capacity addition in Hyderabad and Campinas manufacturing clusters. Consolidate against emerging point-of-care specialists by acquiring heat-stable chemistry platforms. ISO 15189 accreditation investments in district-level reference laboratories lock out non-compliant competitors from reimbursement-eligible networks. For New Entrants and Emerging Players: Telemedicine-enabled self-collection channels offer the lowest customer acquisition cost entry path into privacy-sensitive urban demographics in Brazil and Australia. White-space concentration sits with mail-in specimen logistics for asymptomatic screening populations avoiding clinic stigma. Partner with existing CLIA-waived device manufacturers for private-label rapid test distribution rather than building manufacturing de novo. For Investors and Strategic Acquirers: The window for entry favors point-of-care platform specialists with WHO prequalification dossiers in active review. Long-term viability hinges on regulatory certification density rather than manufacturing scale alone. Watch for CDSCO and ANVISA accelerated approval pathways for indigenous diagnostic kits as inflection signals for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks PEPFAR and Global Fund procurement eligibility for African and Asian government tenders. |
| CE Marking under EU MDR | Mandatory for European market access as notified bodies apply stricter clinical evidence standards. |
| Reagent Supply Integration | Captures margin from polymerase manufacturing currently concentrated in German and US suppliers. |
| Self-Collection Kit Development | Captures privacy-sensitive demographics in Australia's direct-to-consumer channel and Brazil's urban clinics. |
| Heat-Stable Chemistry Partnership | Enables cold-chain-free deployment for Sub-Saharan Africa laboratory gap and rural India outreach. |
Research Methodology
Independent corroboration across diagnostic platform manufacturers, public health procurement officers, and clinical laboratory directors underwrites the qualitative findings presented in this study. Primary interviews with biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies were cross-referenced against secondary validation from FDA 510(k) filings, WHO target product profiles, CDSCO registration databases, and ANVISA post-market surveillance reports. Bottom-up triangulation across instrument placement data and top-down reconciliation against national control program budgets produced convergent market sizing estimates.
Comparable-period anchoring to historical reference data across the projection horizon enabled calibration of technology adoption curves and procurement cycle timing. Segmentation modeling incorporated product type, application disease target, end-user facility category, and deployment channel dimensions alongside regional regulatory cluster variations. CAGRs were derived from logistic diffusion curves fitted to nucleic acid amplification platform penetration rates and rapid test kit volume expansion in government programs. Industry-specific inputs included viral load monitoring scale-up targets under India's NACP and syphilis screening integration timelines in Brazil's SUS prenatal protocols.
Inputs from procurement databases and regulatory filing repositories were available through the study window; gaps in real-time distributor inventory data introduce uncertainty bands around point-of-care device placement estimates. Forecasts reflect assumptions regarding WHO guideline adoption timelines and national reimbursement expansion for asymptomatic screening. A small set of triggers—including EU MDR implementation delays, reagent supply disruptions, and prequalification pathway accelerations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Antibody Testing Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market