
 Global Neurodiagnostics Market | 2026-2036
Global Neurodiagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurodiagnostics Market Foresight
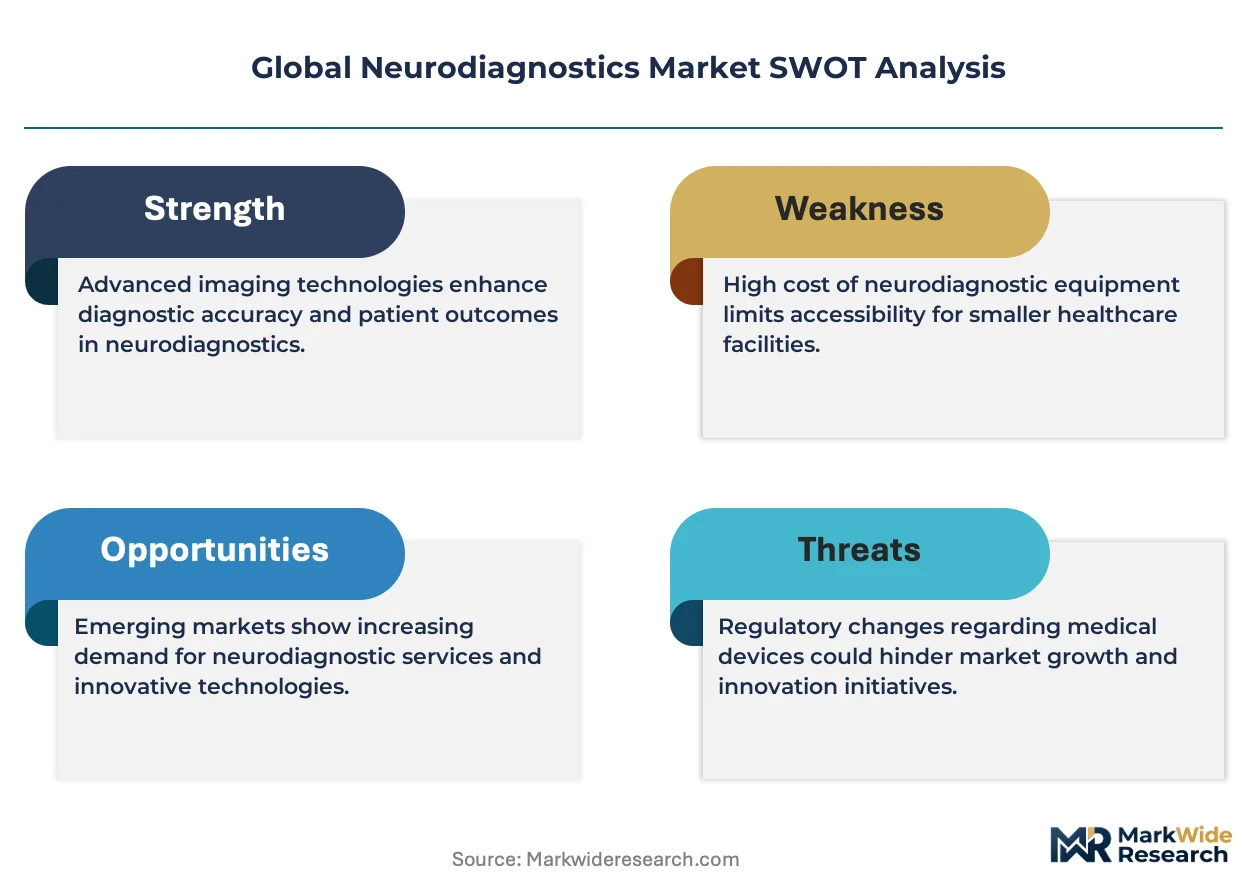
The EU Medical Device Regulation is expanding pre-market clinical obligations for neurodiagnostic manufacturers, raising compliance costs and favoring incumbents with established notified body relationships. Siemens Healthineers leverages its integrated imaging portfolio to bundle CT, MRI, and EEG workflows for hospital systems. GE Healthcare sustains R&D intensity in deep-learning reconstruction algorithms for faster neuroimaging protocols. Natus Medical specializes in long-term epilepsy monitoring systems that anchor its position in the sleep and seizure diagnostics segment.
Neurodiagnostics encompasses technologies that measure, image, and record electrical, magnetic, and metabolic activity of the central and peripheral nervous systems, typically operating at spatial resolutions from single-neuron microelectrodes to whole-brain functional MRI at 1.5–7 Tesla field strengths, with the primary purpose of detecting structural lesions, functional abnormalities, and disease biomarkers to guide neurological treatment decisions. Neuroimaging commands the largest revenue share among product types due to the capital intensity of MRI and PET systems and their irreplaceable role in stroke and tumor diagnosis. Cloud-based technology deployment is gaining fastest adoption as hospital networks seek centralized data architectures for multi-site neurology departments. Wireless and portable modalities are penetrating outpatient clinics and ambulatory epilepsy monitoring, though reimbursement frameworks lag behind hardware innovation.
The FDA enforces 510(k) and PMA pathways for neurodiagnostic devices, with escalating scrutiny of software-as-a-medical-device algorithms in AI-enhanced neuroimaging. Japan's PMDA maintains distinct pharmacovigilance reporting for implanted neurodiagnostic electrodes, while China's NMPA accelerates review timelines for domestically manufactured EEG and EMG systems under updated innovation channel policies. Stakeholders must monitor divergent regulatory timelines for AI diagnostic algorithms across the FDA, EMA, and NMPA, as asynchronous approvals will fragment product launch strategies and channel investments.
Market Dynamics
Hospital neurology departments are consolidating diagnostic workflows around cloud-based data architectures, forcing equipment vendors to abandon standalone hardware sales in favor of integrated platform subscriptions that bundle imaging, monitoring, and AI-enhanced analysis tools.
Growth Catalysts
- EU Medical Device Regulation (MDR):Tightened clinical evidence requirements for neuroimaging equipment favor established manufacturers with notified body relationships, accelerating hospital consolidation toward trusted vendor partnerships.
- Centralized stroke networks:The United States, Germany, and Japan are expanding dedicated stroke centers that require continuous EEG monitoring and rapid-access CT/MRI protocols, driving replacement cycles for aging neurodiagnostic fleets.
- Deep-learning reconstruction:AI-enhanced image processing is compressing scan times by 40-60% without resolution loss, enabling higher patient throughput in saturated radiology departments.
Market Restraints
- Capital intensity of MRI systems:Superconducting magnet and helium cooling supply chains concentrate in a handful of specialized vendors, exposing purchasers to price volatility and extended lead times.
- Reimbursement lag for wireless modalities:Ambulatory EEG and portable monitoring devices face fragmented payer codes across US Medicare, German statutory insurance, and Japanese health ministry frameworks, delaying outpatient adoption.
- Helium dependency:MRI systems require liquid helium for superconducting magnet cooling, and global helium supply disruptions threaten operational continuity for hospital radiology departments.
Strategic Opportunities
- India's underserved epilepsy monitoring:The country's 12 million epilepsy patients access fewer than 500 dedicated monitoring beds nationwide, creating white space for portable long-term video-EEG systems.
- Software-as-a-medical-device (SaMD) pathways:FDA's evolving 510(k) guidance for AI diagnostic algorithms creates regulatory clarity for cloud-native neuroimaging analysis platforms that decouple software from hardware sales.
- Convergence of sleep and seizure diagnostics:Combined polysomnography-EEG systems address comorbid sleep disorders in epilepsy patients, opening reimbursement pathways through cardiology and pulmonology budgets.
Industry Challenges
- Electrophysiology technologist shortage:Skilled professionals capable of interpreting complex EEG and EMG waveforms are scarce in rural US markets and emerging European health systems, constraining service expansion.
- Legacy PACS integration:Hospital IT departments struggle to embed cloud-native neurodiagnostic platforms into entrenched picture archiving systems without disrupting radiologist workflow continuity.
- Asynchronous AI approvals:Divergent FDA, EMA, and NMPA timelines for algorithm validation fragment product launch strategies and force redundant clinical trials across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurodiagnostics Market |
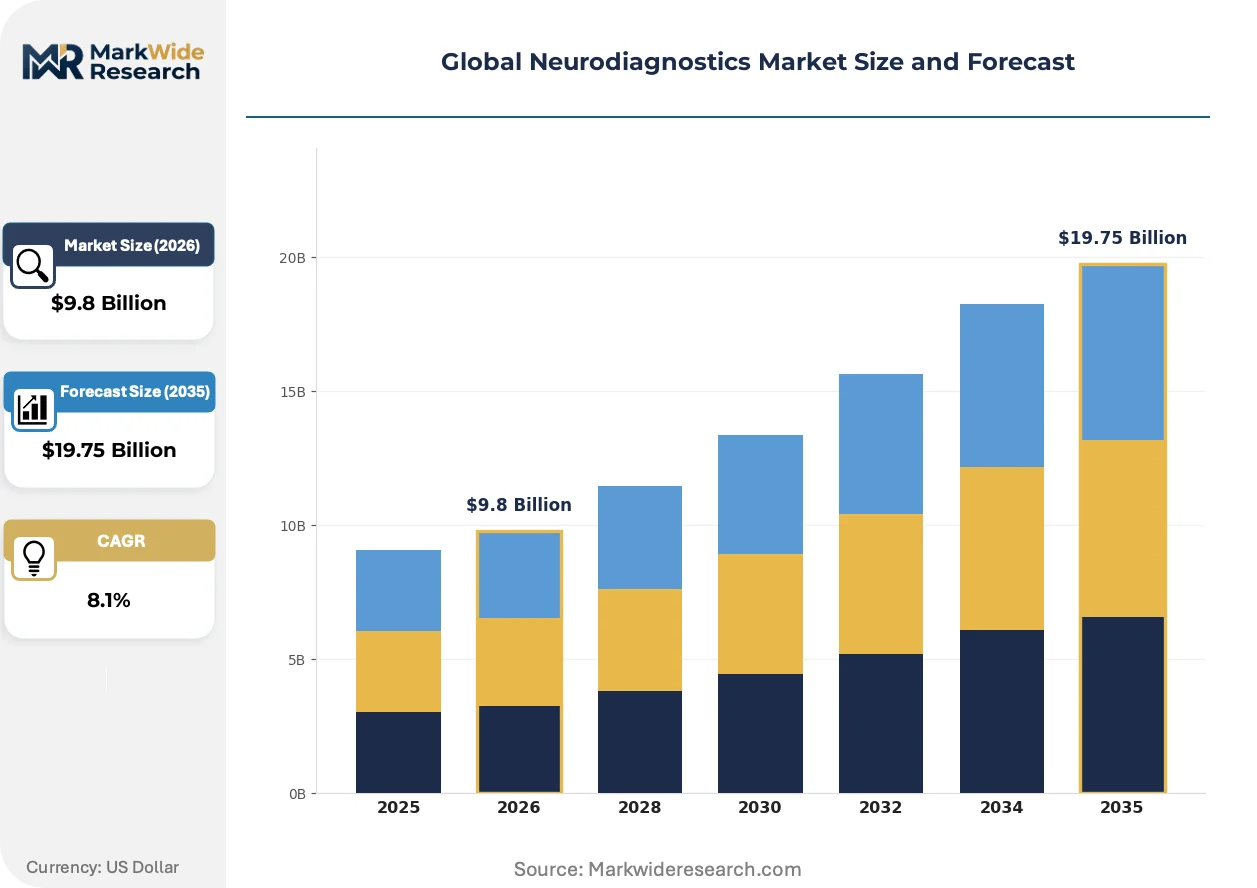
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $19.75 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography, Magnetoencephalography, Electromyography, Neuroimaging End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Technology: Wireless, Portable, Stationary, Cloud-Based Application: Sleep Disorders, Epilepsy, Stroke, Neurodegenerative Diseases |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Thermo Fisher Scientific, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, F. Hoffmann-La Roche Ltd, Natus Medical Incorporated, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurodiagnostics Market Shifts & Advancements
Neurodiagnostic technology is pivoting from hardware-centric sales toward software-enabled service models, with artificial intelligence, regulatory harmonization pressures, and buyer consolidation collectively redefining vendor-customer relationships.
Deep-learning reconstruction algorithms are automating image acquisition protocols in CT and MRI systems, allowing Siemens Healthineers and GE Healthcare to sell throughput guarantees rather than equipment specifications. Academic medical centers in the United States and university hospitals in Germany are piloting these tools to compress emergency stroke imaging from 15 minutes to under 5 minutes. The structural consequence is automating radiologist workflow prioritization and reducing reliance on on-site specialist availability for time-critical diagnoses.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on AI-enhanced neuroimaging software that exceeds traditional medical device requirements. Manufacturers must now maintain post-market performance monitoring systems and algorithm change control protocols that add 12-18 months to European commercialization timelines. High-risk diagnostic AI modules face the strictest scrutiny, pushing vendors to segregate European product configurations from faster-moving US and Asian releases.
Hospital procurement departments are consolidating neurodiagnostic purchasing through centralized capital committees that bundle imaging, monitoring, and informatics spend across multi-site networks. This behavior is displacing decentralized department-level purchasing authority and favoring vendors with comprehensive platform portfolios. The shift is most visible in US integrated delivery networks and German hospital federations, where single-vendor contracts now span 5-7 year terms with embedded technology refresh clauses.
Global Neurodiagnostics Market Segmentation
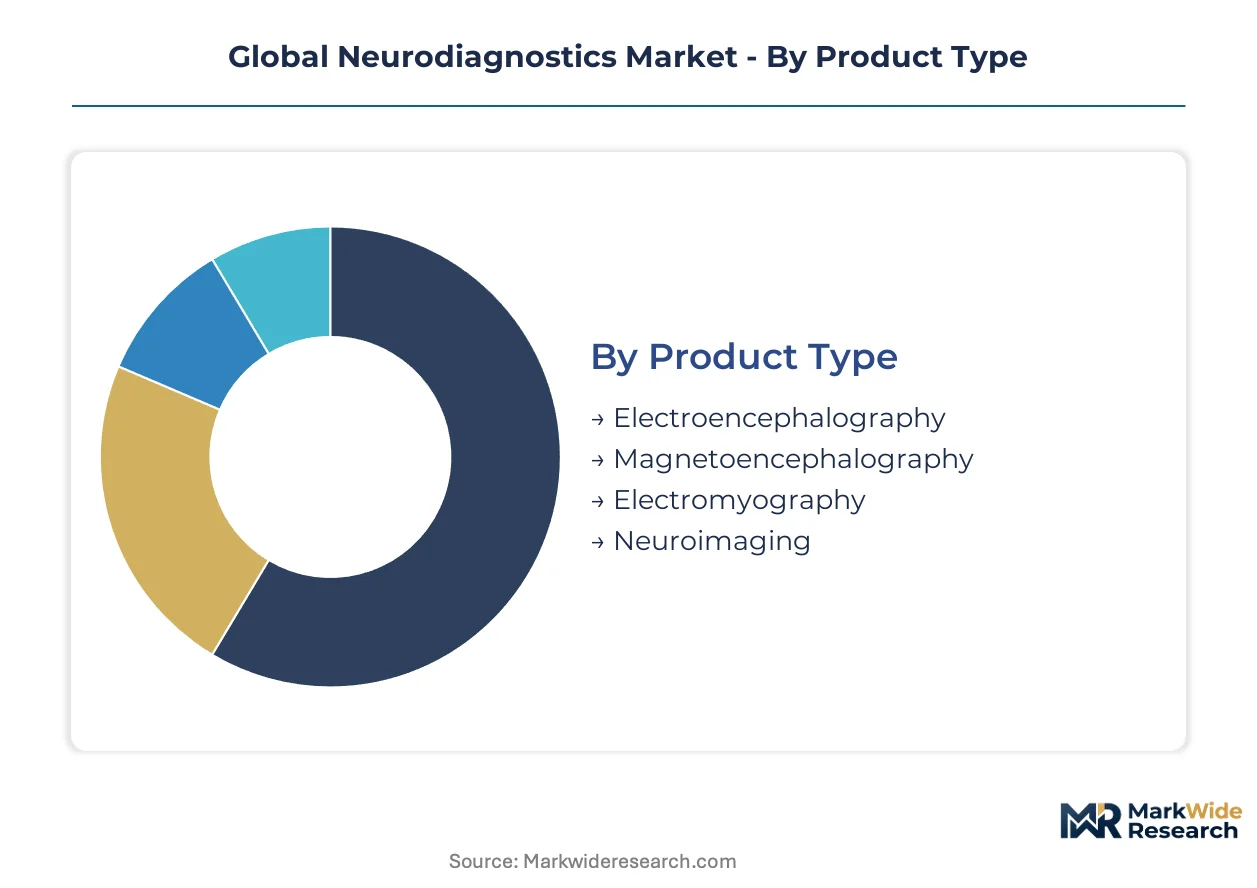
Neurodiagnostic purchasing decisions hinge on capital intensity, clinical workflow integration, and reimbursement pathway clarity. Equipment replacement cycles vary dramatically across product categories, with imaging systems commanding decade-long investment horizons while monitoring technologies refresh every 3-5 years.
Product Type:
Upgrade cycles differ sharply between capital-intensive imaging platforms and electrophysiology systems, with hospital procurement committees timing replacements to regulatory compliance deadlines and technology refresh clauses.
- Neuroimaging:MRI and CT systems operate at 1.5-7 Tesla field strengths with superconducting magnet architectures requiring liquid helium cooling. Demand concentrates in United States and German stroke centers where rapid-access protocols drive fleet modernization; helium supply volatility extends replacement timelines and favors vendors with captive magnet servicing capabilities.
- Electroencephalography:Multi-channel recording systems measure electrical brain activity through scalp electrodes at microvolt sensitivity. Hospital neurology departments in Japan prioritize high-density arrays for epilepsy surgical planning; reimbursement compression for routine diagnostic EEGs shifts volume toward ambulatory monitoring configurations.
- Electromyography:Needle and surface electrode systems assess peripheral nerve and muscle function through evoked potential measurement.
- Magnetoencephalography:Superconducting quantum interference device arrays detect femtotesla-scale magnetic fields from neuronal currents, restricted to academic medical centers with specialized shielding infrastructure.
Volume placements concentrate in Neuroimaging; the faster expansion belongs to Electroencephalography as ambulatory and wireless configurations penetrate outpatient settings.
End User:
Procurement authority is migrating from department-level decision-making toward centralized capital committees that bundle multi-site contracts across integrated delivery networks.
- Hospitals:Comprehensive neurology departments require continuous EEG monitoring, rapid-access CT/MRI for stroke protocols, and integrated PACS infrastructure. United States integrated delivery networks and German hospital federations now execute 5-7 year single-vendor agreements spanning imaging, monitoring, and informatics.
- Diagnostic Laboratories:Independent testing facilities focus on high-volume EMG and routine EEG interpretation with streamlined technician staffing models.
- Outpatient Clinics:Ambulatory settings demand portable and wireless modalities for epilepsy monitoring and sleep disorder assessment; fragmented payer codes across US Medicare and German statutory insurance delay hardware deployment despite clinical utility.
- Research Institutes:Academic medical centers pilot deep-learning reconstruction algorithms and high-density MEG systems for neurosurgical planning applications.
Capital commitment intensity peaks in Hospitals; Research Institutes are climbing the fastest as NIH and DFG funding expands for AI-enhanced neuroimaging validation studies.
Technology:
Hardware-software decoupling is accelerating as cloud-native platforms separate data analysis from acquisition device sales, enabling subscription-based revenue models.
- Cloud-Based:Centralized data architectures enable multi-site neurology departments to standardize protocols and deploy AI-enhanced analysis tools across distributed networks. United States hospital systems lead adoption, driven by cybersecurity insurance requirements and radiologist workforce consolidation.
- Wireless:Bluetooth and proprietary radio-frequency systems eliminate tethered connections for ambulatory EEG and sleep monitoring, though battery life and artifact rejection limit clinical acceptance.
- Portable:Battery-powered devices with reduced channel counts serve point-of-care stroke assessment and emergency department triage in rural United States markets.
- Stationary:Fixed-installation systems with highest channel density and signal fidelity remain the default for epilepsy monitoring units and intraoperative neurophysiology.
Installed base dominance remains with Stationary configurations; Cloud-Based deployment is gaining share fastest as EU AI Act conformity requirements favor centralized algorithm monitoring infrastructure.
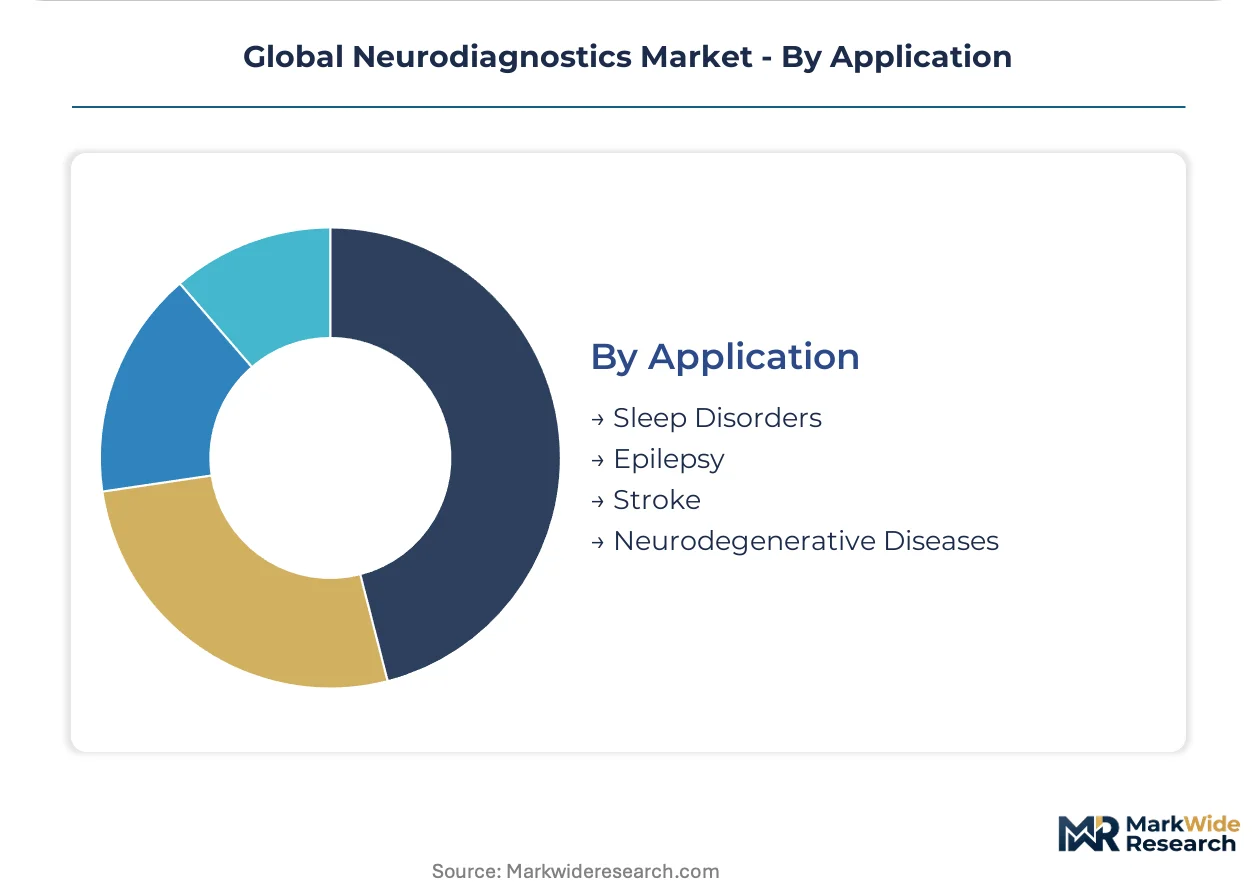
Application:
Reimbursement pathway maturity determines technology adoption velocity, with well-established codes accelerating hardware placement and fragmented coverage delaying penetration.
- Stroke:Time-critical imaging protocols require sub-5-minute CT acquisition and immediate EEG for seizure detection in large vessel occlusion cases. Centralized stroke networks in the United States, Germany, and Japan drive replacement demand for aging CT fleets and establish continuous monitoring standards.
- Epilepsy:Long-term video-EEG monitoring for surgical candidacy evaluation commands dedicated bed capacity and specialized electrophysiology technologist staffing; India's 12 million patients access fewer than 500 monitoring beds nationwide, creating white space for portable systems.
- Sleep Disorders:Polysomnography-EEG convergence addresses comorbid sleep architecture disruption in epilepsy patients, opening cardiology and pulmonology budget lines for combined diagnostic systems.
- Neurodegenerative Diseases:PET amyloid imaging and quantitative EEG biomarker development for Alzheimer's disease progression monitoring remain concentrated in academic research protocols pending regulatory qualification.
Procedure volume concentrates in Stroke emergency protocols; Sleep Disorders are expanding most quickly as combined diagnostic systems capture reimbursement from multiple clinical service lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan are driving replacement demand for aging neurodiagnostic fleets as these countries expand centralized stroke networks and epilepsy monitoring centers.
United States
Integrated delivery networks consolidate neurodiagnostic purchasing through centralized capital committees spanning imaging, monitoring, and informatics. FDA 510(k) pathways for AI-enhanced neuroimaging software create regulatory clarity for cloud-native analysis platforms. The Greater Boston cluster anchors academic medical center pilots of deep-learning reconstruction algorithms for emergency stroke protocols.
Germany
Hospital federations execute single-vendor contracts with embedded technology refresh clauses covering multi-site neurology departments. EU Medical Device Regulation conformity assessment obligations extend commercialization timelines for AI-enhanced diagnostic software. The Bavaria region concentrates university hospital networks piloting combined polysomnography-EEG systems for comorbid sleep disorder assessment.
Japan
PMDA pharmacovigilance reporting requirements for implanted neurodiagnostic electrodes shape product development priorities for domestic manufacturers. METI funding expands high-density EEG array deployment for epilepsy surgical planning. The Kanto region around Tokyo hosts specialized shielding infrastructure for magnetoencephalography systems at academic medical centers.
China
NMPA innovation channel policies accelerate review timelines for domestically manufactured EEG and EMG systems. Provincial health commissions expand centralized stroke center networks requiring rapid-access CT and continuous monitoring capabilities. The Yangtze River Delta cluster concentrates manufacturing capacity for portable neurodiagnostic devices serving underserved rural markets.
India
Twelve million epilepsy patients access fewer than five hundred dedicated monitoring beds nationwide, creating white space for portable long-term video-EEG systems. CDSCO medical device registration pathways for wireless ambulatory modalities remain under development. Maharashtra's Mumbai-Pune corridor anchors private hospital chain investments in cloud-based data architectures for multi-site neurology departments.
Global Neurodiagnostics Market Competitive Landscape
United States and German producers anchor the premium imaging tier; Japanese specialists hold differentiated positions in electrophysiology monitoring. The vendor base stratifies across comprehensive platform providers, electrophysiology-focused specialists, and emerging software-native entrants. Three archetypes dominate: integrated imaging portfolios bundling CT, MRI, and EEG workflows; dedicated epilepsy and sleep monitoring system providers; and cloud-native algorithm developers decoupling analysis from hardware sales. Competitive moves concentrate on strategic partnerships for AI development and portfolio diversification into adjacent diagnostic modalities.
Within the integrated platform tier, Siemens Healthineers and GE Healthcare exemplify vendors leveraging comprehensive imaging portfolios to capture multi-year hospital system contracts. Natus Medical occupies a specialist position exemplifying focused electrophysiology providers targeting long-term monitoring segments. These three anchors represent distinct strategic postures: scale-driven platform breadth, technology-led algorithm development, and clinical-application depth in seizure diagnostics.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Thermo Fisher Scientific |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| F. Hoffmann-La Roche Ltd |
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Superconducting magnet grade divergence separates premium MRI systems from portable EEG configurations, with helium-cooled 7 Tesla field strength units commanding captive servicing contracts while battery-powered ambulatory devices compete on unit economics and distributor margins. This bifurcation concentrates procurement authority in United States integrated delivery networks for imaging platforms while fragmenting purchasing across outpatient clinics for wireless modalities, with EU MDR conformity costs embedding directly into premium tier pricing and Chinese manufacturing scale driving economy segment affordability.
Pricing Analysis
Volume placements in portable EEG and EMG systems trade at compressed margins against low-single-digit unit profitability, while premium MRI and MEG platforms sustain value-based pricing through throughput guarantees and embedded AI reconstruction subscriptions. Price differentiation rests on FDA 510(k) clearance tier and notified body relationship depth for EU MDR compliance, with cloud-native software companions capturing recurring revenue streams that hardware vendors increasingly bundle. Pricing pressure stems from helium supply volatility extending superconducting magnet lead times and forcing purchasers toward extended service contracts. Hospital procurement committees exhibit highest price sensitivity for standalone monitoring hardware, while stroke network administrators prioritize rapid-access protocol reliability over capital expenditure minimization.
Supply Chain Analysis
Freight costs for liquid helium transport from United States and Qatar extraction facilities concentrate superconducting magnet servicing capabilities in Germany, Japan, and the United States, with cryogenic container leasing rates embedding directly into MRI total cost of ownership. Superconducting wire, rare-earth magnet alloys, and specialized shielding materials draw from Japanese and German precision manufacturing, while semiconductor components for EEG acquisition systems source from Taiwan and South Korea. Single-source vulnerability concentrates in helium liquefaction capacity, with geopolitical disruption threatening operational continuity for hospital radiology departments. Distribution runs through authorized service organizations with captive engineering teams rather than third-party logistics, reflecting installation complexity and regulatory servicing obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR tightened clinical evidence requirements function as a cost-of-compliance moat, with notified body relationship scarcity and post-market surveillance infrastructure investments filtering subscale competitors from premium neuroimaging segments.
For Market Incumbents: Deepen vertical integration into helium recycling and captive magnet servicing capabilities to offset supply volatility exposure, while consolidating AI algorithm development partnerships to defend subscription revenue streams against software-native entrants. Lock in 5-7 year single-vendor contracts with United States integrated delivery networks before hospital procurement committee consolidation completes, using embedded technology refresh clauses to capture replacement cycle timing. For New Entrants and Emerging Players: The premium-to-economy price-point gap in long-term epilepsy monitoring creates white-space entry through portable video-EEG systems targeting India's 12 million underserved patients and rural United States markets lacking electrophysiology technologist density. Bypass capital-intensive MRI competition by anchoring on cloud-native analysis platforms with FDA 510(k) SaMD pathways, selling software subscriptions that decouple from hardware procurement cycles and capture recurring revenue without manufacturing scale requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where comprehensive imaging portfolios absorb specialized electrophysiology monitoring capabilities to satisfy hospital federation bundling demands. Five-to-ten year viability favors vendors with established notified body relationships and captive AI development infrastructure over pure-play hardware manufacturers facing software margin compression. Watch FDA-EMA-NMPA asynchronous AI approval timelines as the critical signal for which algorithm developers can achieve multi-jurisdictional scale without redundant clinical trial burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Investment | EU MDR conformity assessment scarcity accelerates commercialization timelines for prepared manufacturers. |
| Helium Recycling Infrastructure | Captive liquefaction capacity insulates MRI servicing margins from supply disruption volatility. |
| Cloud-Native Platform Development | Software-as-a-medical-device pathways decouple analysis revenue from hardware replacement cycles. |
| Hospital System Partnership | Integrated delivery network consolidation favors vendors with multi-site standardization capabilities. |
| AI Algorithm Validation | FDA 510(k) clearance for deep-learning reconstruction enables throughput guarantee pricing models. |
Research Methodology
Multi-period observation of hospital procurement contract structures, regulatory submission timelines, and helium spot price volatility anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, biomedical engineering managers, electrophysiology technologists, and GPO contracts specialists. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body certificates, CMS Medicare reimbursement code updates, and hospital capital expenditure disclosures. Bottom-up equipment placement tracking across United States, German, and Japanese stroke centers triangulated against top-down manufacturer revenue segmentation to constrain forecast variance.
Segment-weighting approaches distributed total market value across neuroimaging, electroencephalography, electromyography, and magnetoencephalography product types, with technology deployment mode and end-user facility type as secondary stratification dimensions. CAGRs derived from logistic growth curve fitting to historical placement data, adjusted for replacement cycle timing and regulatory compliance deadline clustering. Forecast inputs incorporated NIH and DFG funding trajectories for AI-enhanced neuroimaging validation, alongside METI high-density EEG array deployment commitments and NMPA innovation channel throughput assumptions.
Underlying measurement precision varies by segment; cloud-based technology adoption rates and wireless modality placement carry tighter precision than magnetoencephalography system counts given academic medical center concentration and specialized shielding infrastructure scarcity. Forecasts reflect modeling assumptions regarding helium supply stabilization, reimbursement code harmonization timelines, and electrophysiology workforce expansion rates that could revise trajectory if material conditions diverge. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Europe Blood Screening Market
Diagnostics
LDL Test Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market