
 Global Predictive Genetic Testing and Consumer/Wellness Genomics Market | 2026-2036
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market Intelligence
China's expanding life sciences and genomics laboratory infrastructure is reconfiguring the competitive landscape for genetic testing services. Established players like 23andMe, Inc. leverage a massive proprietary database to refine trait prediction algorithms. Ancestry.com LLC differentiates through its deep integration with genealogical records, while MyHeritage Ltd. competes on a broad international presence and localized product offerings.
Predictive genetic testing and consumer genomics involve the analysis of an individual's DNA to forecast susceptibility to diseases, identify carrier status, or reveal ancestral origins. This process primarily utilizes technologies like Next-Generation Sequencing to scan for specific genetic markers and variations across the genome. While Whole Genome Sequencing represents a high-value test type, the Direct-to-Consumer Platforms end-user segment drives the majority of market volume. Next-Generation Sequencing technology continues to displace older microarray analysis methods due to its superior data resolution.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and compliance with data privacy laws such as Europe's GDPR are critical for market access. These frameworks govern the clinical validity claims of tests and the secure handling of highly sensitive personal health information. Providers must continuously navigate the evolving ethical guidelines and data security expectations to maintain consumer trust and operational legitimacy.
Market Dynamics
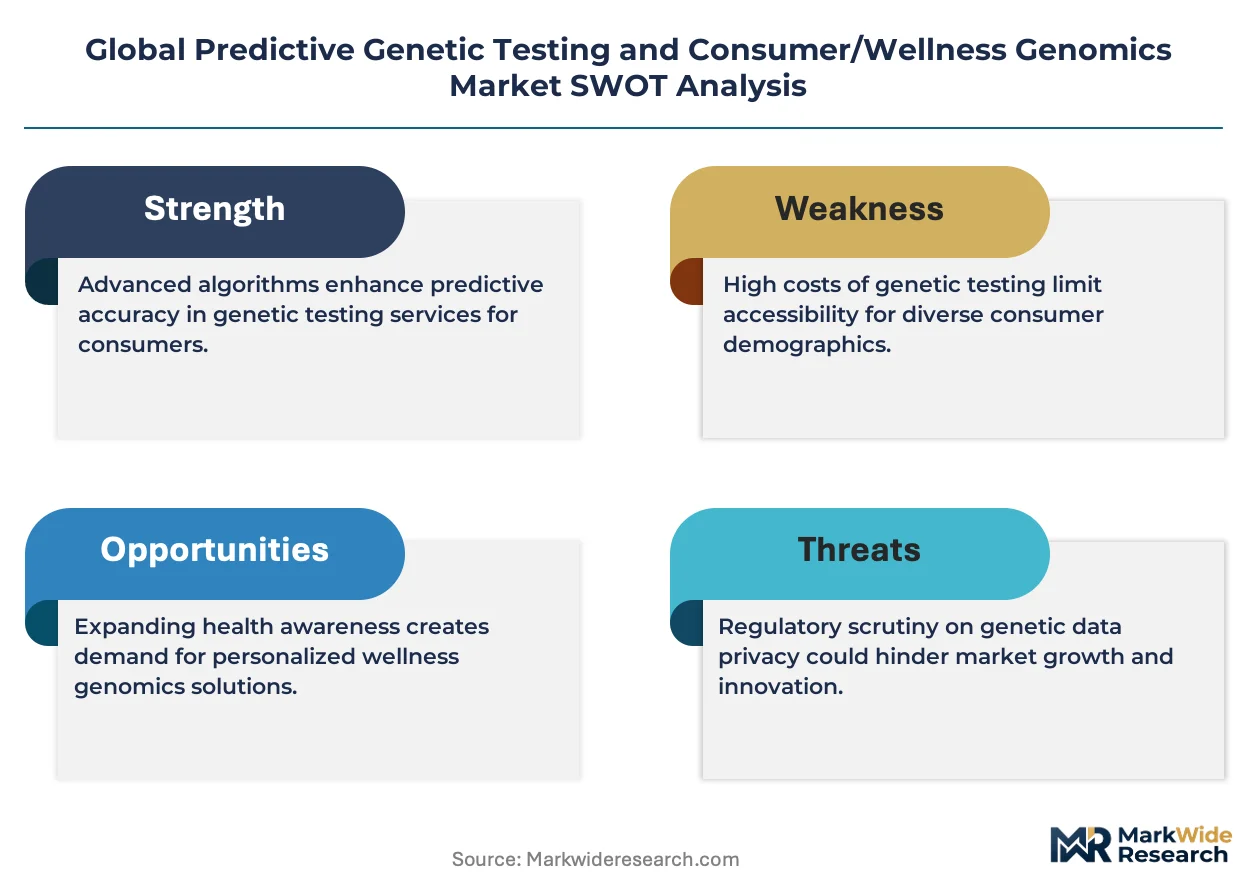
The central dynamic shaping the market is the tension between the explosive growth of consumer-generated genomic data via Direct-to-Consumer platforms and the simultaneous tightening of global data privacy and security mandates, exemplified by Europe's GDPR and the U.S. HIPAA framework.
Growth Catalysts
- Next-Generation Sequencing Cost Decline:Continuous reductions in the cost of Next-Generation Sequencing (NGS) technology are making genetic tests more affordable and accessible, expanding the consumer base beyond early adopters to the mass market.
- Personalized Health Demand:A strong cultural focus on proactive health management and personal ancestry discovery, particularly concentrated in the United States, drives high-volume demand for consumer-facing wellness and genealogical testing services.
- National Genomics Initiatives:Government-backed programs, such as those expanding laboratory infrastructure in China, create a fertile ground for market development by building technical capacity and fostering domestic scientific expertise.
Market Restraints
- Stringent Clinical Validation:Regulatory bodies like the U.S. FDA impose rigorous requirements for demonstrating the clinical validity of predictive health tests, creating high barriers to entry and long development timelines for new products.
- Data Interpretation Complexity:The sheer volume and complexity of data from Whole Genome Sequencing present significant analytical and interpretive hurdles, limiting its routine use and creating a bottleneck for actionable insights.
- Ethical and Privacy Concerns:Public apprehension regarding the potential for genetic discrimination by insurers or employers, coupled with concerns over data security breaches, acts as a significant deterrent for a segment of potential consumers.
Strategic Opportunities
- Pharmacogenomic Integration:The integration of pharmacogenomic testing into standard clinical practice offers a major growth vector, enabling physicians to use genetic data to optimize drug selection and dosage for individual patients.
- Emerging Market Penetration:Untapped markets in regions like Southeast Asia and Latin America, characterized by a rising middle class and increasing healthcare spending, present substantial opportunities for geographic expansion.
- Polygenic Risk Score Development:Advances in machine learning algorithms create an opportunity to develop and commercialize more accurate polygenic risk scores (PRS) for complex conditions like heart disease and diabetes, enhancing clinical utility.
Industry Challenges
- Bioinformatics Talent Scarcity:A persistent shortage of qualified bioinformaticians and genetic counselors capable of accurately interpreting genomic data and communicating findings to patients constrains the ability of providers to scale their services.
- Lack of Data Standardization:The absence of universally accepted standards for genomic data formatting and analysis across laboratories hinders data interoperability, complicating large-scale research and the portability of consumer genetic information.
- Navigating Global Regulations:Companies face significant operational complexity and compliance costs in navigating the fragmented landscape of data privacy laws, which vary substantially between jurisdictions like the EU, the U.S., and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Predictive Genetic Testing and Consumer/Wellness Genomics Market |
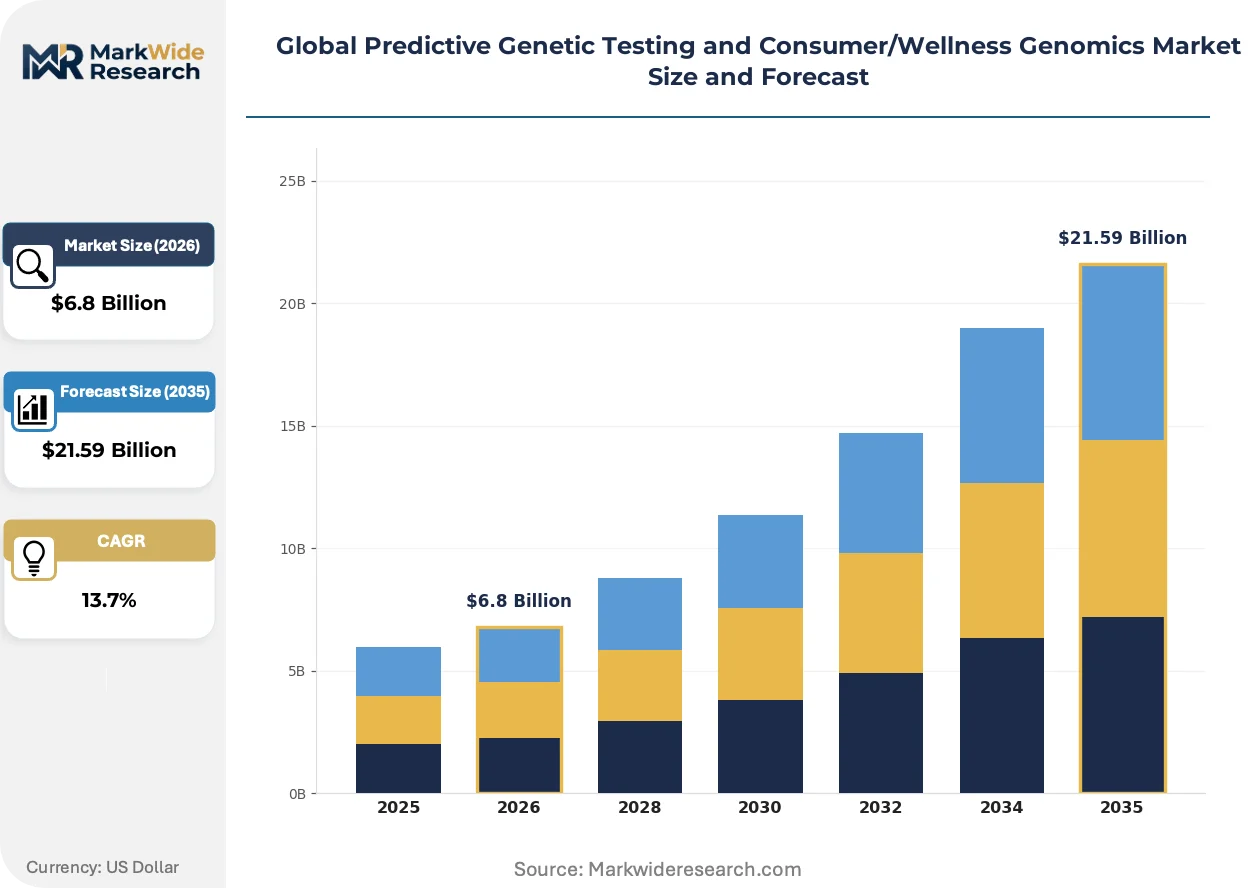
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Carrier Screening, Pharmacogenomics, Whole Genome Sequencing, Ancestry Analysis, Nutrigenomics Technology: Next-Generation Sequencing, Microarray Analysis, PCR-Based Testing, CRISPR-based Assays, DNA Microfluidics End User: Research Laboratories, Direct-to-Consumer Platforms, Wellness Providers, Genetic Counseling Centers, Biotechnology Firms Application: Disease Risk Assessment, Trait Prediction, Drug Response Optimization, Lifestyle Management, Ancestral Insights |
| Companies Covered | Nebula Genomics, Inc., Gene by Gene, Ltd., 23andMe, Inc., Orig3n, Inc., Living DNA Ltd., Ancestry.com LLC, Prenetics Ltd., Dante Labs S.p.A., MyHeritage Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market Strategic Shifts & Innovations
The market's focus is shifting from broad, exploratory genetic analysis toward the delivery of targeted, actionable insights. This evolution is driven by technological maturation and a regulatory push for greater clinical relevance, moving genomics from a novelty to an integrated component of healthcare.
Long-read sequencing technology provides a more complete and accurate resolution of complex genomic regions that are challenging for traditional short-read methods. Clinical research laboratories are increasingly adopting this technology to investigate structural variations linked to rare diseases and cancer. As a result, the market's analytical power is migrating from simply identifying single-point mutations toward resolving large-scale genomic rearrangements and previously uncharacterizable DNA segments.
Europe's General Data Protection Regulation (GDPR) continues to set a global precedent for handling sensitive personal information, including genetic data. The regulation mandates explicit consent and grants consumers rights over their data, forcing companies to re-architect their data governance and security protocols. The Direct-to-Consumer segment is most affected, with providers investing heavily in compliance infrastructure to maintain access to the European market.
Consumer purchasing behavior is evolving from a one-time transaction for a static report to a preference for subscription-based engagement models. This trend disrupts the traditional test-and-report sales cycle, replacing it with platforms that offer ongoing updates, new trait reports, and evolving ancestry insights. This model is most visible in the North American market, where users value continuous discovery and long-term interaction with their genomic data.
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market Segmentation
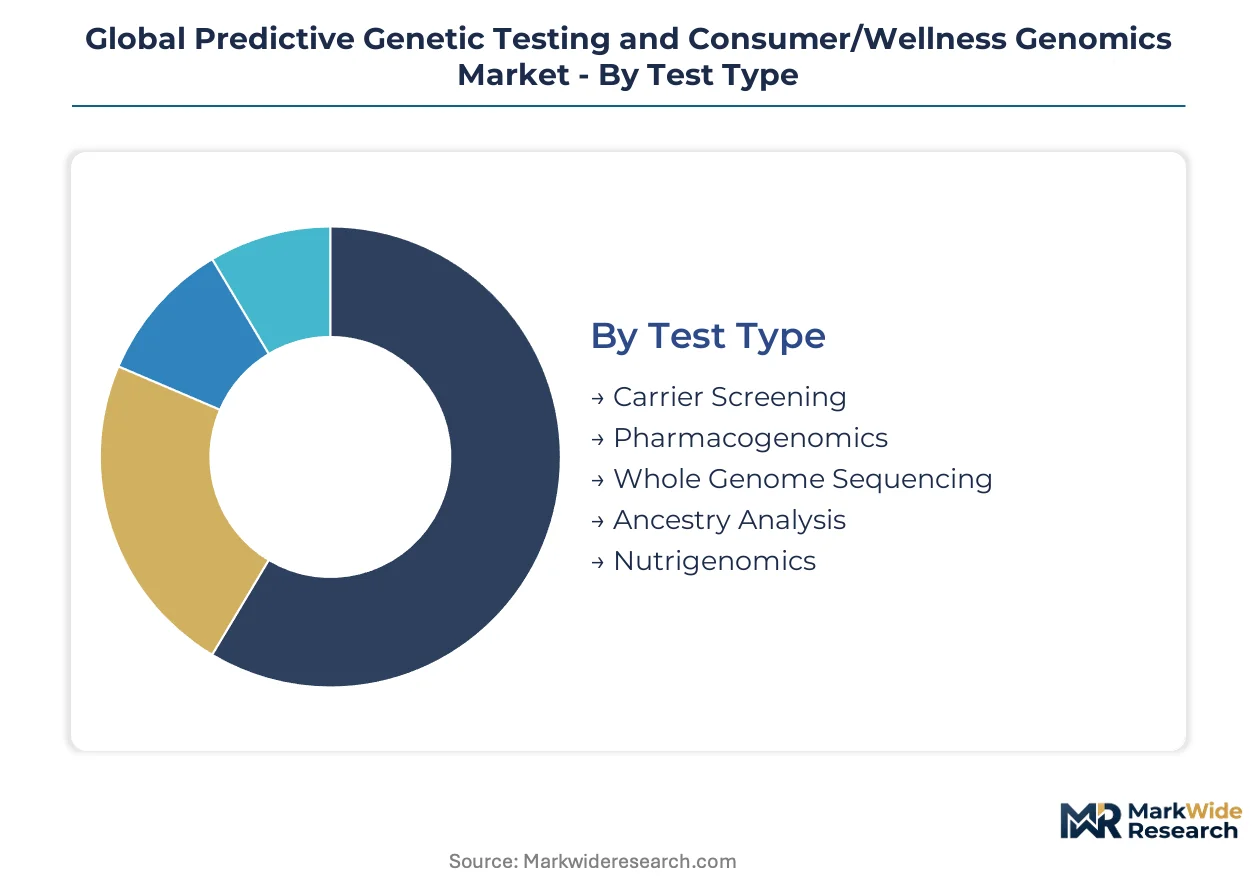
The Global Predictive Genetic Testing and Consumer/Wellness Genomics Market is analyzed through distinct segments, reflecting varied technological approaches and end-user demands. This detailed breakdown illuminates the specific drivers influencing adoption across different testing modalities and service delivery models. Understanding these categories is essential for identifying areas of concentrated growth and evolving consumer preferences.
Test Type:
The spectrum of genetic tests spans from medical diagnostics to personal wellness and ancestral discovery, addressing diverse consumer and clinical needs.
- Whole Genome Sequencing:This comprehensive analysis of an individual's entire genome identifies variations across all chromosomes, providing vast genetic information. It is crucial for rare disease diagnosis in clinical settings, especially in countries like the United States, driving demand for high-resolution data.
- Ancestry Analysis:This method utilizes genetic markers to trace an individual's ethnic origins and genealogical connections across populations. High consumer interest in personal heritage, particularly in North America, fuels widespread adoption of these accessible platforms.
- Carrier Screening:This test identifies genetic variants that could cause inherited conditions in offspring, guiding reproductive planning for prospective parents.
- Pharmacogenomics:This analysis examines genetic variations influencing individual drug responses, optimizing medication efficacy and minimizing adverse effects.
- Nutrigenomics:This field explores the interaction between genes and diet, offering personalized dietary recommendations for health and wellness.
Established volume favors Ancestry Analysis; emerging adoption favors Pharmacogenomics.
Technology:
Technological advancements continue to drive down costs and increase data resolution, influencing accessibility and application across various price points.
- Next-Generation Sequencing:This high-throughput DNA sequencing technology processes millions of DNA fragments in parallel, providing vast genomic data. It is displacing older methods due to superior data resolution and declining costs, expanding its use in research laboratories and clinical diagnostics globally.
- CRISPR-based Assays:This gene-editing technology is adapted for precise and rapid detection of specific genetic sequences or pathogens, offering high sensitivity. It represents an emerging diagnostic tool with significant potential for point-of-care testing and advanced research applications in biotechnology firms.
- Microarray Analysis:This technology simultaneously measures the expression levels of thousands of genes or detects specific genetic variations on a chip.
- PCR-Based Testing:This method amplifies specific DNA segments for detection, widely used for targeted genetic screening and infectious disease diagnostics.
- DNA Microfluidics:This approach integrates laboratory functions onto a micro-chip for automated, high-throughput genetic analysis with minimal sample volumes.
Next-Generation Sequencing serves as the dominant platform, while CRISPR-based Assays offer specialized, highly targeted capabilities.
End User:
End-user segments reflect distinct application focuses, ranging from fundamental scientific inquiry to personalized health management and direct consumer engagement.
- Direct-to-Consumer Platforms:These platforms provide genetic testing services directly to individuals without requiring a healthcare provider's order, often via online channels. This segment drives the majority of market volume, particularly in the United States, fueled by consumer interest in personal health and ancestry insights.
- Research Laboratories:These entities conduct fundamental and applied genomic studies, developing new diagnostic methods and understanding disease mechanisms. They form the bedrock of innovation and validation for new genetic tests, with government-backed initiatives, such as those in China, expanding their infrastructure.
- Wellness Providers:These professionals integrate genetic insights into broader health and lifestyle programs, offering personalized recommendations to clients.
- Genetic Counseling Centers:These centers offer expert interpretation of genetic test results and guidance on implications for patients and their families.
- Biotechnology Firms:These companies develop and commercialize novel genomic technologies and therapeutic applications based on genetic insights.
Volume is concentrated in Direct-to-Consumer Platforms, while Biotechnology Firms represent a key growth area for innovation.
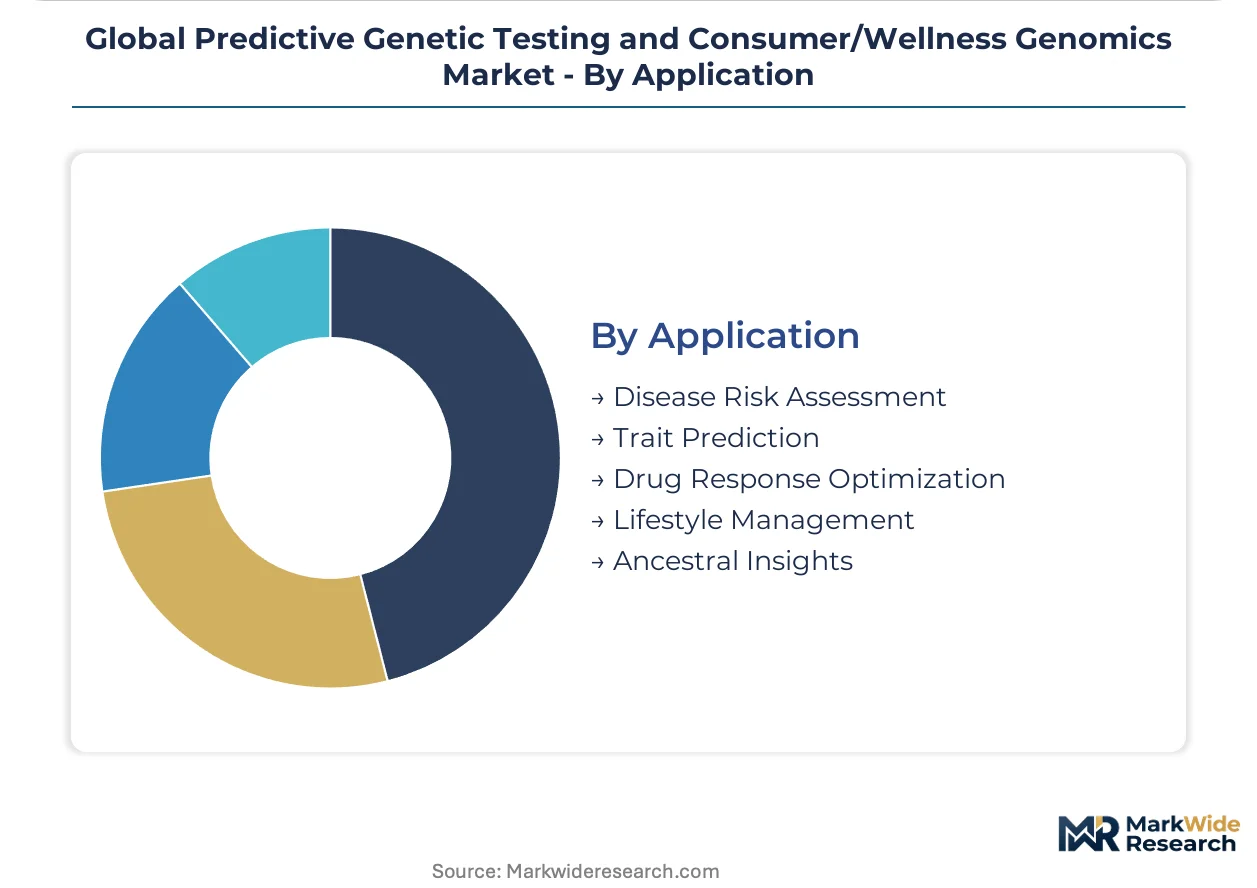
Application:
Applications differentiate based on their core value proposition, from informing medical decisions to enhancing personal understanding and optimizing lifestyle choices.
- Disease Risk Assessment:This application utilizes genetic markers to estimate an individual's predisposition to developing specific diseases, informing preventive strategies. It is crucial for proactive health management, especially in regions with high healthcare awareness like the United States, driving clinical utility.
- Ancestral Insights:This application provides information about an individual's ethnic origins, migration patterns, and genetic connections to historical populations. High consumer engagement, particularly in North America, where curiosity about heritage fuels the popularity of direct-to-consumer genetic services.
- Trait Prediction:This identifies genetic markers associated with various physical or behavioral characteristics, such as hair color or athletic potential.
- Drug Response Optimization:This uses pharmacogenomic data to tailor medication choices and dosages for individual patients, improving treatment outcomes.
- Lifestyle Management:This offers personalized recommendations for diet, exercise, and wellness based on an individual's genetic predispositions.
The primary driver for consumer engagement is Ancestral Insights, while clinical utility is increasingly found in Drug Response Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market for predictive genetic testing exhibits supply-side concentration, driven by advanced genomic research and consumer demand. Key regions are expanding their infrastructure and regulatory frameworks to support this specialized industry. These areas foster both technological innovation and widespread adoption of genetic services.
United States
Demand in the United States for genetic testing is concentrated, driven by significant consumer interest in personal health and ancestry discovery. The U.S. FDA imposes rigorous validation for health tests, while HIPAA governs data privacy. The Boston-Cambridge biotech hub fosters innovation in genomic technologies and clinical applications.
China
China's expanding life sciences infrastructure and national genomics initiatives stimulate domestic market development. Government-backed programs promote technical capacity and scientific expertise, overseen by national health regulators. The Yangtze River Delta region is a growing center for genomics laboratories and research.
Germany
Germany demonstrates strong demand for pharmacogenomics and disease risk assessment, supported by its advanced healthcare system. GDPR sets a strict precedent for genetic data handling, ensuring patient privacy across the nation. Munich and Bavaria are significant hubs for biotech research and development in personalized medicine.
United Kingdom
The United Kingdom pursues large-scale genomic projects, fostering demand for advanced genetic analysis in healthcare. The MHRA ensures clinical validity, while UK GDPR mandates strict data privacy protocols for genetic information. London and Cambridge form a vital cluster for genomic research and clinical trial development.
Japan
Japan's aging population and focus on preventive healthcare stimulate demand for predictive genetic testing applications. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates genetic tests, ensuring safety and efficacy. Tokyo and Osaka represent key centers for advanced genomics research and biotechnology firms.
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market Key Industry Players
Consumer-focused platforms and specialized clinical providers split the market for predictive genetic testing. The industry structure features a mix of established large-scale players and numerous smaller, agile biotechnology firms. Strategic archetypes include direct-to-consumer services emphasizing ancestry and wellness, and clinical laboratories focusing on disease risk assessment and pharmacogenomics. Companies pursue portfolio diversification and strategic partnerships to expand service offerings and penetrate new geographic markets.
Within the consumer-facing segment, 23andMe, Inc. represents a player leveraging extensive proprietary databases for refining trait prediction algorithms. Ancestry.com LLC exemplifies a strategy focused on deep integration with genealogical records, differentiating its ancestry insights. MyHeritage Ltd. occupies a position characterized by a broad international presence and localized product offerings, catering to diverse global consumers. These firms collectively anchor the direct-to-consumer market, driving volume through accessible genetic insights and continuous engagement models.
| Leading Market Players |
|---|
| Nebula Genomics, Inc. |
| Gene by Gene, Ltd. |
| 23andMe, Inc. |
| Orig3n, Inc. |
| Living DNA Ltd. |
| Ancestry.com LLC |
| Prenetics Ltd. |
| Dante Labs S.p.A. |
| MyHeritage Ltd. |
| Others |
Cost & Logistics Intelligence
The transatlantic freight corridor's cost dynamics influence the pricing of specialized genetic testing reagents, reflecting supply concentration in key manufacturing hubs and affecting downstream consumer test differentiation.
Pricing Analysis
Europe's GDPR dictates the pricing tier structure for genetic data services, emphasizing explicit consent and data rights for consumers. Subscription-based engagement models are prevalent, particularly for continuous ancestry updates and wellness insights. Price differentiation stems from the level of clinical validation, such as U.S. FDA approval, and the degree of customization in genomic reports. Pricing softness reflects intense competition in the direct-to-consumer segment, especially for basic ancestry kits. Direct-to-consumer platforms exhibit high price sensitivity, while clinical diagnostic labs are less sensitive due to medical necessity and reimbursement structures.
Supply Chain Analysis
Specialized contract research organizations and reagent manufacturers hold significant capacity within the genetic testing supply chain. Geographic supply concentration includes China for laboratory infrastructure and reagent production, alongside the United States for Next-Generation Sequencing technology development. Raw material dependencies encompass NGS reagents, bioinformatics software licenses, and specialized microfluidics components. Regulatory restrictions on cross-border data transfer pose a significant structural risk. Distribution runs through direct-to-consumer online channels and established clinical laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The predictive genetic testing market requires a strong substitution defense as advancements in non-invasive diagnostics threaten to displace traditional genomic screening methods.
For Market Incumbents:
Pre-empt emerging competition by strengthening proprietary data assets and diversifying service portfolios. Invest in advanced bioinformatics for polygenic risk score development, enhancing clinical utility against rapid advancements in AI-driven diagnostic tools. Pursue strategic partnerships with healthcare providers to integrate genetic insights into routine medical practice. Leverage R&D in long-read sequencing technology to maintain a technological edge.
For New Entrants and Emerging Players:
Southeast Asian markets represent a significant geographic underpenetration for personalized genetic testing services. Focus on localized nutrigenomics offerings and pharmacogenomic integration to address specific regional health needs. The direct-to-consumer wellness segment in regions with a rising middle class offers the most penetrable entry point. Partner with local wellness clinics for distribution and consumer trust building.
For Investors and Strategic Acquirers:
Specialized bioinformatics firms with robust data interpretation capabilities offer attractive acquisition targets. The market demonstrates long-term growth potential over the next decade due to increasing integration into clinical care pathways. Companies developing advanced polygenic risk score algorithms represent a key archetype. Increasing regulatory approvals for clinical utility claims by the U.S. FDA is a signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Pharmacogenomic Integration | Optimizes drug selection and dosage for individual patients, enhancing clinical outcomes. |
| Develop Advanced Polygenic Risk Scores | Offers more accurate risk assessment for complex conditions like diabetes, improving preventive care strategies. |
| Strengthen Data Privacy Infrastructure | Ensures compliance with global regulations like GDPR, maintaining consumer trust in genetic services. |
| Penetrate Emerging Markets | Captures new consumer segments in Latin America with rising healthcare spending and interest. |
| Invest in Long-Read Sequencing | Provides superior resolution for complex genomic regions, improving rare disease diagnosis in research labs. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence reports anchors the qualitative findings. Genetic counselors, bioinformatics specialists, R&D directors at biotechnology firms, and regulatory affairs managers provided expert insights. Secondary data sources included ClinicalTrials.gov, U.S. FDA regulatory filings, academic genomics journals, and national health statistics. Bottom-up data from company reports and top-down market sizing estimates were triangulated for accuracy.
Quantitative models were calibrated using a multi-factor approach, integrating historical market performance with future growth drivers. The analytical framework projects market trajectories across the analysis window. Segmentation dimensions included test type, technology, end user, application, and regional regulatory frameworks. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth projections. Declining Next-Generation Sequencing costs and evolving data privacy regulations were key forecast inputs.
Practitioners should monitor evolving regulatory landscapes and technological breakthroughs for early signals that could revise market forecasts. Forecasts reflect assumptions regarding consumer adoption rates and clinical integration pathways. Unforeseen data breaches or significant shifts in public perception represent specific risk factors. Quarterly review of U.S. FDA approvals and GDPR enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fertility Testing Devices Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Melioidosis Diagnostic Market