
 Immuno-Oncology Clinical Trials Market | 2026-2036
Immuno-Oncology Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Immuno-Oncology Clinical Trials Market Intelligence
The EU Green Deal is shifting oncology trial sustainability standards toward carbon-accountable site selection and patient travel minimization. Merck & Co. leverages its Keytruda franchise to dominate Phase III checkpoint inhibitor trials across multiple tumor types. Novartis anchors its position through CAR-T cell therapy development, sustaining leadership in personalized immuno-oncology protocols.
Immuno-oncology clinical trials evaluate therapeutic agents that harness or modulate the immune system to recognize and eliminate malignant cells, typically involving biologics such as monoclonal antibodies, cell therapies, and therapeutic vaccines that require cold-chain distribution and specialized bioanalytical endpoints. The primary purpose is to generate regulatory-grade evidence of safety and efficacy for immune-mediated cancer treatments. Phase III trials command the largest operational budgets due to expanded enrollment and long-term survival endpoints, while combination therapy investigations represent the fastest-expanding intervention category as sponsors seek to overcome resistance mechanisms. Melanoma indication studies remain structurally mature with established surrogate endpoints, whereas lung cancer trials attract the deepest investment pools driven by front-line approval opportunities.
FDA accelerated approval and breakthrough therapy designation frameworks compress development timelines and reshape trial design priorities for immuno-oncology sponsors. EMA's PRIME scheme and the EU Clinical Trials Regulation harmonize assessment standards while mandating enhanced pharmacovigilance for novel immune modulators. Stakeholders must monitor evolving FDA guidance on confirmatory trial requirements, as the agency tightens evidentiary standards for accelerated approvals in checkpoint inhibitor classes.
Market Dynamics
FDA accelerated approval pathways compress development timelines for checkpoint inhibitors, while EU Clinical Trials Regulation harmonization reduces multi-country activation delays. Sponsors now prioritize adaptive trial designs that integrate real-world evidence generation alongside traditional randomized controls.
Growth Catalysts
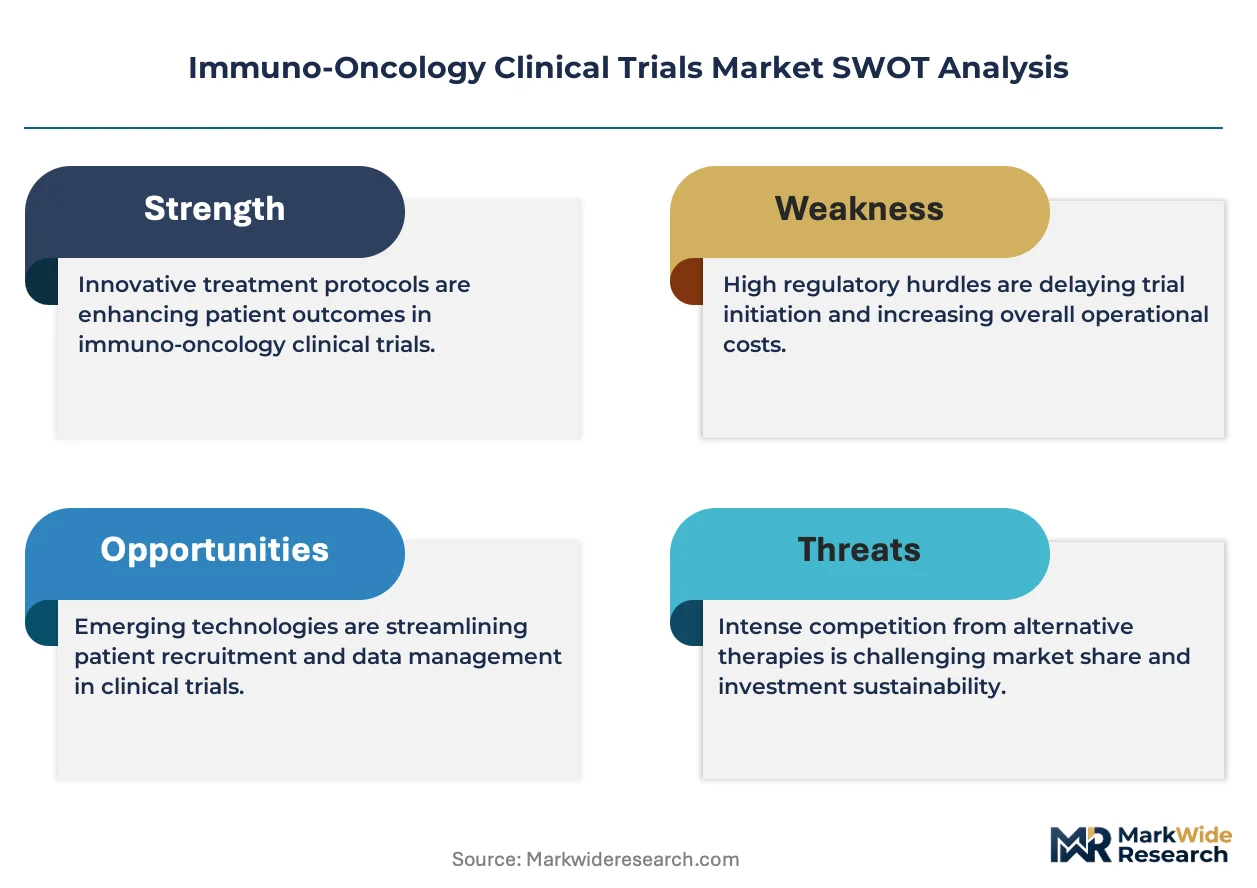
- Breakthrough Therapy Designation:FDA's expedited review framework compresses Phase II-to-approval intervals for novel immune modulators, compressing competitive windows for first-in-class entrants.
- CAR-T manufacturing scale-up:Automated cell processing platforms reduce per-patient production costs, expanding addressable patient populations beyond academic medical centers.
- Biomarker-driven enrollment:PD-L1 expression and tumor mutational burden stratification improves response rates, reducing required sample sizes for powered studies.
Market Restraints
- Cold-chain distribution costs:Cell therapies require liquid nitrogen logistics and cryogenic storage, constraining site activation to tertiary oncology centers with specialized infrastructure.
- Confirmatory trial mandates:FDA's tightened evidentiary standards for accelerated approvals demand larger post-marketing studies, extending capital lock-up periods for sponsors.
- Patient travel burden:Centralized manufacturing and infusion requirements limit rural and ex-urban participation, skewing trial demographics toward metropolitan clusters.
Strategic Opportunities
- Decentralized trial models:Home nursing and local lab partnerships expand geographic reach beyond traditional academic sites, capturing underrepresented populations.
- Combination therapy protocols:Pairing checkpoint inhibitors with radiotherapy or targeted agents addresses resistance mechanisms, opening new indication expansion pathways.
- EU Green Deal compliance:Carbon-accountable site selection and virtual monitoring reduce trial environmental footprint while accelerating EMA approval timelines.
Industry Challenges
- Immuno-oncology biostatistician scarcity:Complex survival analysis and competing-risk modeling require specialized expertise that outpaces academic training pipeline output.
- Legacy EDC integration:Electronic data capture platforms designed for chemotherapy trials require costly reconfiguration to handle immune-related adverse event complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immuno-Oncology Clinical Trials Market |
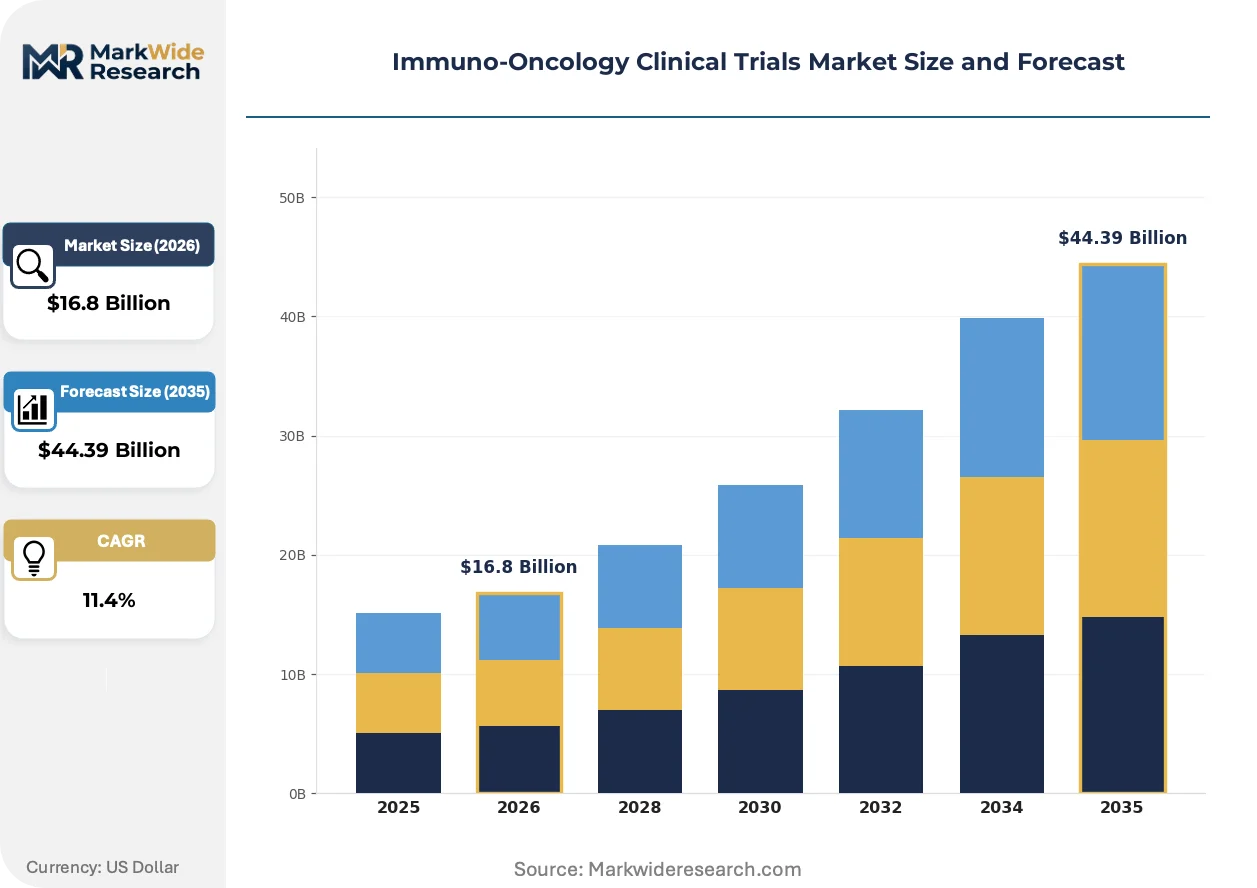
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $44.39 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV Indication: Lung Cancer, Melanoma, Colorectal Cancer, Breast Cancer Intervention Type: Monotherapy, Combination Therapy, Vaccine, Antibody End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Research Organizations |
| Companies Covered | Merck & Co., Novartis, AstraZeneca, IQVIA Holdings, ICON Plc, Syneos Health, Medpace, BeiGene, Kite Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immuno-Oncology Clinical Trials Market Strategic Shifts & Innovations
Digital biomarker acquisition and decentralized patient monitoring are compressing traditional site-centric trial models. These shifts reduce geographic barriers to enrollment while generating continuous efficacy signals.
Decentralized clinical trial platforms is decentralizing patient data collection through wearable devices and telemedicine check-ins. Community oncology practices now enroll patients previously excluded by travel constraints. This technology is decentralizing trial execution authority from academic medical centers to distributed care networks, accelerating recruitment velocity.
EMA's PRIME scheme prioritizes novel immuno-oncology agents for accelerated assessment and enhanced scientific dialogue. The framework compresses regulatory feedback loops for cell therapies and bispecific antibodies. European sponsors now front-load manufacturing readiness to meet compressed approval timelines.
Site selection criteria now weight carbon footprint alongside enrollment capacity. Virtual monitoring and local laboratory partnerships displace centralized site visits. This recalibration is most visible in Germany and France, where EU Green Deal compliance has become a contractual requirement for major pharmaceutical sponsors.
Immuno-Oncology Clinical Trials Market Segmentation
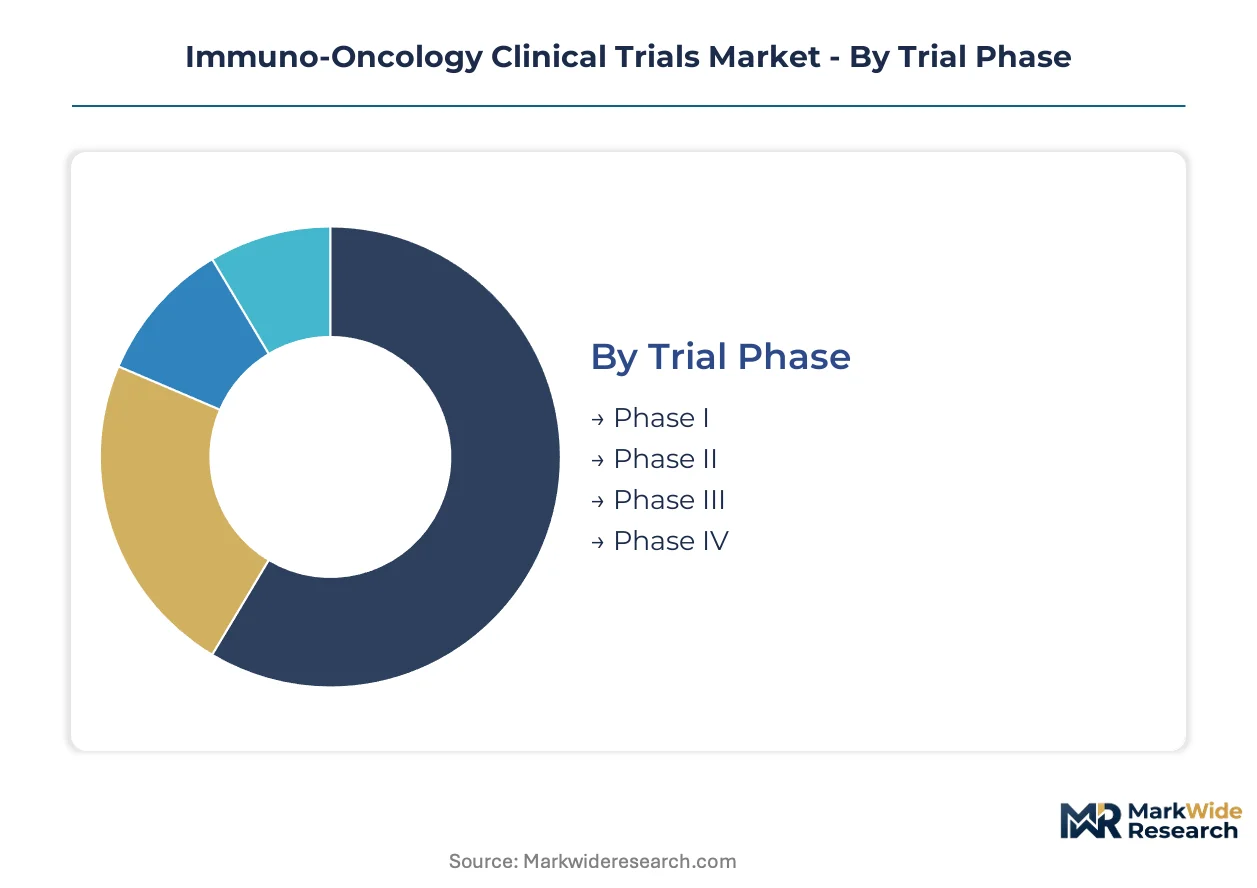
Immuno-oncology trial sponsors allocate budgets across distinct operational layers. Phase complexity, tumor biology, therapeutic modality, and sponsor type each reshape protocol design, patient recruitment strategy, and regulatory submission pathways.
Trial Phase:
Sponsor investment intensity escalates with phase progression as patient enrollment scales and survival endpoints lengthen.
- Phase I:First-in-human studies establish safety profiles and maximum tolerated doses for novel immune modulators. Demand concentrates in the United States where FDA's exploratory IND guidance permits streamlined dose-escalation designs, though limited patient numbers constrain per-trial revenue contribution.
- Phase III:Pivotal registration trials generate regulatory-grade evidence through randomized controlled designs with overall survival or progression-free survival primary endpoints. Pharmaceutical companies in Germany and France allocate the deepest budgets here, driven by EMA's centralized marketing authorization requirements and confirmatory evidence mandates.
- Phase II:Efficacy signals in defined tumor cohorts support breakthrough therapy designation applications. Academic medical centers in Boston and San Francisco dominate enrollment for single-arm expansion cohorts.
- Phase IV:Post-marketing surveillance captures long-term safety and real-world effectiveness data. Regulatory pressure from FDA's tightened accelerated approval confirmatory requirements is expanding commitment volumes.
Volume sits with Phase III; growth tilts toward Phase I as bispecific antibodies and cell therapies multiply first-in-human programs.
Indication:
Tumor type dictates biomarker infrastructure requirements and competitive positioning against approved standards of care.
- Lung Cancer:Non-small cell lung cancer trials leverage PD-L1 expression stratification and tumor mutational burden thresholds for patient selection. Sponsors in the United Kingdom and Japan prioritize this indication for front-line checkpoint inhibitor combinations given large addressable populations and established reimbursement pathways.
- Melanoma:Cutaneous melanoma maintains the most mature immuno-oncology trial infrastructure with validated surrogate endpoints and centralized pathology review networks. Australian and Italian sites contribute disproportionate enrollment due to high incidence rates and specialized surgical oncology integration.
- Colorectal Cancer:Microsatellite instability-high subpopulations drive targeted enrollment strategies. Deficient mismatch repair biomarker testing requirements limit site activation to centers with integrated molecular diagnostics.
- Breast Cancer:Triple-negative and HER2-positive subtypes attract checkpoint inhibitor and antibody-drug conjugate combinations. Patient advocacy networks in Canada and Spain accelerate recruitment for these historically chemotherapy-dependent populations.
Revenue concentrates in lung cancer; expansion tilts toward colorectal cancer as MSI-high prevalence mapping improves screening integration.
Intervention Type:
Manufacturing complexity and mechanism of action determine site infrastructure requirements and supply chain risk profiles.
- Combination Therapy:Pairing checkpoint inhibitors with chemotherapy, radiotherapy, or targeted agents dominates current protocol development. Sponsors in Switzerland and the Netherlands prioritize these designs to address primary and acquired resistance mechanisms.
- Monotherapy:Single-agent checkpoint inhibitors retain utility in biomarker-selected populations and maintenance settings. Post-approval trials in South Korea and Sweden focus on sequencing optimization and treatment duration minimization.
- Antibody:Bispecific and trispecific antibody constructs require specialized bioanalytical endpoints for cytokine release monitoring. CMC development timelines constrain program initiation velocity.
- Vaccine:Personalized neoantigen vaccines demand patient-specific manufacturing with extended production windows. Academic consortiums in Germany and Denmark anchor this modality's clinical translation.
Protocol volume sits with combination therapy; innovation tilts toward bispecific antibodies as manufacturing platforms mature.
End User:
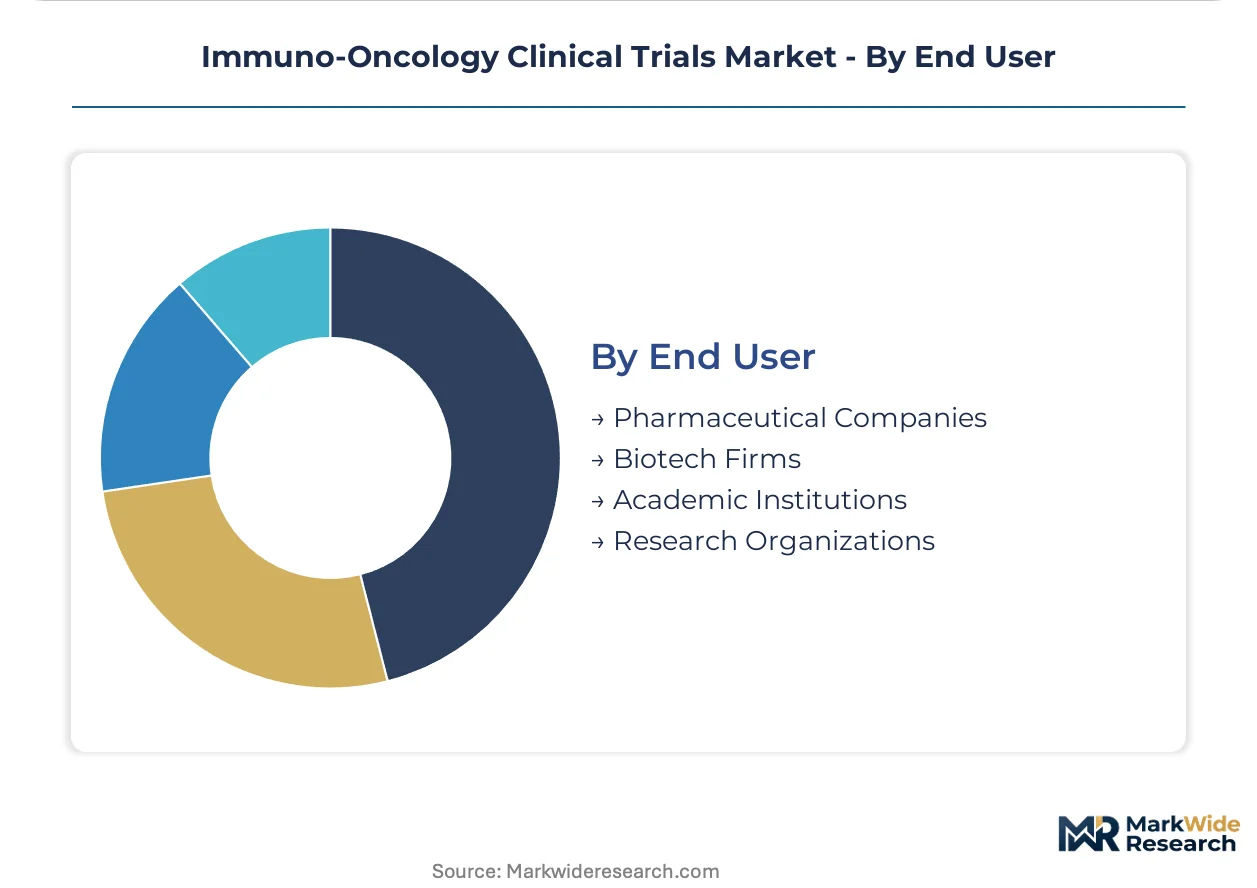
Sponsor organizational structure shapes decision-making speed, outsourcing preferences, and portfolio risk tolerance.
- Pharmaceutical Companies:Large-cap sponsors maintain integrated development functions with internal biostatistics and regulatory affairs capabilities. Merck & Co. and Bristol Myers Squibb anchor the deepest Phase III investment pools across multiple tumor types.
- Biotech Firms:Venture-backed developers rely on contract research organizations for operational execution while retaining medical and scientific leadership in-house. Boston and San Francisco clusters concentrate pre-IPO financing activity.
- Academic Institutions:University medical centers contribute investigator-initiated trials and early-phase translational science. NCI-designated cancer centers in the United States provide foundational evidence for subsequent industry-sponsored registration programs.
- Research Organizations:Non-profit and government-funded entities conduct comparative effectiveness and health services research. EORTC and SWOG networks generate practice-changing data independent of commercial sponsorship.
Trial volume sits with pharmaceutical companies; growth tilts toward biotech firms as cell therapy and bispecific antibody platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the densest concentration of immuno-oncology trial activity worldwide, with the Longwood Medical Area and Kendall Square hosting overlapping academic and commercial research operations. Trial demand distributes across five national markets where regulatory frameworks and manufacturing infrastructure create distinct competitive conditions.
United States
FDA's Breakthrough Therapy Designation and exploratory IND guidance compress Phase I initiation timelines for novel immune modulators. The National Cancer Institute funds investigator-initiated trials through its designated cancer center network. Boston, San Francisco, and Houston medical clusters generate the deepest enrollment pools for checkpoint inhibitor and CAR-T protocols.
Germany
EMA's centralized marketing authorization procedure and PRIME scheme for accelerated assessment attract Phase III investment from multinational sponsors. The EU Clinical Trials Regulation harmonizes protocol submissions across member states, reducing multi-country activation delays. Heidelberg and Munich academic medical centers anchor CAR-T manufacturing and first-in-human cell therapy investigations.
United Kingdom
NHS England's Cancer Drugs Fund and early access to medicines scheme create reimbursement certainty for novel immuno-oncology agents. MHRA's post-Brexit regulatory autonomy permits streamlined trial approvals for innovative biologics. London and Manchester oncology networks concentrate lung cancer and melanoma trial enrollment through integrated molecular diagnostics.
China
NMPA's priority review pathway for innovative biologics accelerates domestic PD-1/PD-L1 inhibitor development. The country's dual carbon goals pressure sponsors toward virtual monitoring and reduced patient travel in trial design. Shanghai and Beijing biotech clusters host the fastest-expanding Phase I programs for bispecific antibodies and cell therapies.
Switzerland
Swissmedic's rapid authorization procedures and alignment with EMA standards position the country as a launchpad for European immuno-oncology trials. Basel and Zurich pharmaceutical corridors concentrate combination therapy protocol development. Academic-industry partnerships at University Hospital Zurich drive biomarker-driven enrollment strategies for personalized cancer vaccines.
Immuno-Oncology Clinical Trials Market Key Industry Players
The competitive structure tilts toward large-cap pharmaceutical sponsors with integrated development functions and established checkpoint inhibitor franchises. Mid-tier contract research organizations capture operational execution from venture-backed biotech developers lacking internal infrastructure. Three archetypes dominate: integrated pharma sponsors with proprietary pipeline assets, full-service CROs with immuno-oncology therapeutic area expertise, and specialized cell therapy manufacturers with captive production platforms. Competitive moves concentrate on adaptive trial design capabilities and decentralized patient monitoring technologies.
Among integrated pharmaceutical developers, Merck & Co. and Novartis exemplify the archetype of sponsors leveraging established immuno-oncology franchises to anchor Phase III investment pools. BeiGene occupies a position within the emerging biotech tier, representing sponsors that rely on external CRO partnerships for operational execution while retaining scientific and medical leadership internally. These three entities collectively illustrate the spectrum from fully integrated development to hybrid outsourcing models that characterize sponsor-side competitive positioning.
| Leading Market Players |
|---|
| Merck & Co. |
| Novartis |
| AstraZeneca |
| IQVIA Holdings |
| ICON Plc |
| Syneos Health |
| Medpace |
| BeiGene |
| Kite Pharma |
| Others |
Cost & Logistics Intelligence
The EU Green Deal carbon-accountability mandates gate both qualified supply and premium-tier pricing access for immuno-oncology trials, as sponsors must demonstrate sustainable site selection and minimized patient travel to secure EMA approval pathways and command differentiated pricing from environmentally conscious pharmaceutical buyers.
Pricing Analysis
Value-based pricing anchored to progression-free survival and overall survival endpoints dominates Phase III immuno-oncology trials, with premium tiers reserved for protocols demonstrating biomarker-driven patient stratification and accelerated regulatory pathways. Price differentiation rests on manufacturing complexity—CAR-T cell therapies command standard-economy spreads against monoclonal antibodies—while cold-chain logistics costs intensify pricing pressure on decentralized trial models. Academic medical centers exhibit highest price sensitivity due to fixed grant funding, whereas large-cap pharmaceutical sponsors absorb premium pricing for integrated development capabilities.
Supply Chain Analysis
Good Manufacturing Practice certification and EMA PRIME scheme qualification gate supplier participation in European immuno-oncology trial supply chains, constraining qualified vendors to specialized logistics providers. Manufacturing concentrates in the United States, Germany, and Switzerland for cell therapy processing equipment and cryogenic storage systems. Raw material dependencies span patient-derived leukapheresis collections, viral vector production media, and synthetic mRNA manufacturing inputs. Single-source vulnerability permeates automated cell processing platforms. Distribution runs through temperature-controlled specialty couriers with real-time chain-of-custody tracking to NCI-designated cancer centers and academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immuno-oncology clinical trials market has become a vertical-integration race, with sponsors pursuing captive CAR-T manufacturing capabilities to control per-patient production costs and compress approval timelines.
For Market Incumbents: Anchor defensive positioning through backward integration into automated cell processing platform manufacturing, eliminating single-source dependencies that threaten trial continuity. Expand capacity additions in Germany and Switzerland to secure EMA PRIME scheme eligibility and EU Green Deal compliance certification. Consolidate investigator-initiated trial networks through exclusive site partnerships that preempt emerging biotech access to high-enrollment academic medical centers.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in decentralized trial execution services creates white-space opportunity for technology-native platforms offering virtual monitoring and home nursing capabilities. Target community oncology practices in ex-urban United States markets currently excluded by centralized manufacturing requirements. Pursue biomarker-driven enrollment specialization in colorectal cancer MSI-high subpopulations where diagnostic infrastructure constraints limit incumbent penetration.
For Investors and Strategic Acquirers: FDA confirmatory trial mandate withdrawals for accelerated approvals is the leading indicator that capital efficiency in post-marketing surveillance capabilities will separate viable platforms from distressed assets. Frame long-term viability around adaptive trial design technology stacks and real-world evidence generation infrastructure. Monitor contract research organizations with immuno-oncology therapeutic area certification expansion as acquisition targets. A model refresh is warranted upon material change in FDA accelerated approval evidentiary standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Implementation | IQVIA and ICON deploy Bayesian protocols that compress enrollment timelines for checkpoint inhibitor studies. |
| CAR-T Manufacturing Scale-Up | Novartis and Kite Pharma anchor automated cell processing platforms that reduce per-patient production costs. |
| EU Green Deal Compliance Certification | Merck & Co. and AstraZeneca integrate carbon-accountable site selection to accelerate EMA approval pathways. |
| Biomarker-Driven Enrollment Expansion | BeiGene leverages PD-L1 expression stratification to power smaller, higher-response-rate pivotal trials. |
| Decentralized Patient Monitoring Technology | Medpace and Syneos Health deploy wearable devices and telemedicine to capture underrepresented rural populations. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov protocol registries formed the secondary backbone of this analysis, supplemented by customs data on cold-chain logistics equipment and SEC 10-K disclosures from contract research organizations. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated secondary findings and informed segmentation assumptions. Bottom-up and top-down triangulation reconciled patient enrollment velocity data with sponsor budget allocation patterns across trial phases.
Bottom-up modeling anchored forecasts to site activation rates, per-patient costs by therapeutic modality, and biomarker testing penetration curves, while top-down validation checked aggregate spend against pharmaceutical R&D line-item disclosures. Segmentation dimensions spanned trial phase, tumor indication, intervention type, and sponsor organizational structure across the projection horizon. CAGRs derived from historical enrollment growth rates and regulatory pathway compression trends, with scenario weighting for FDA accelerated approval policy evolution and EU Clinical Trials Regulation harmonization implementation.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time site activation cost reporting introduce uncertainty bands around decentralized trial model adoption forecasts. Forecasts reflect documented assumptions regarding biomarker infrastructure expansion and cold-chain logistics cost trajectories. A model refresh is warranted upon material change in FDA confirmatory trial requirements or EU Green Deal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
North America Proton Therapy Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Ustekinumab Market
Oncology
Laser Cancer Therapy Market
Oncology
Immuno-Oncology Market
Oncology
AI in Oncology Market
Oncology
Cancer Supportive Care Products Market
Oncology
Cancer Cachexia Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Liposarcoma Treatment Market
Oncology
Solid Tumor Market
Oncology
Global Interventional Oncology Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Intratumoral Cancer Therapies Market