
 PD1 Resistant Head and Neck Cancer Market | 2026-2036
PD1 Resistant Head and Neck Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
PD1 Resistant Head and Neck Cancer Market Analytics
The FDA's accelerated approval framework is broadening the cost-of-entry calculus for developers of next-generation checkpoint inhibitors. Bristol-Myers Squibb Company leverages its established immuno-oncology infrastructure to sustain commercial traction in refractory settings. Merck & Co., Inc. anchors its position through deep clinical trial investment across combination regimens. AstraZeneca plc differentiates via bispecific antibody platforms targeting alternative immune escape mechanisms.
PD1 resistant head and neck cancer denotes squamous cell carcinomas of the oral cavity, pharynx, and larynx that progress despite prior anti-PD1 therapy, typically characterized by upregulated alternative checkpoint pathways, altered antigen presentation, or tumor microenvironment immunosuppression. These malignancies require therapeutic interventions that circumvent exhausted T-cell signaling through novel receptor targeting, adoptive cell transfer, or tumor-infiltrating lymphocyte engineering. Immunotherapy segments command premium development investment as combination strategies displace monotherapy standards of care. Targeted therapy segments occupy narrower but defensible niches where actionable mutations such as EGFR amplification or PIK3CA alterations permit precision approaches. Biomarker stratification segments are concentrating demand around PD-L1 expression and tumor mutational burden assays that determine trial eligibility and reimbursement pathways.
The FDA, EMA, and WHO collectively shape market access through divergent evidentiary standards for overall survival endpoints and quality-of-life metrics in recurrent disease. FDA breakthrough therapy designation compresses development timelines, while EMA conditional marketing authorization demands more mature European patient data, fragmenting launch sequencing across jurisdictions. Stakeholders must monitor biomarker assay harmonization efforts, as discordant testing platforms between academic centers and community oncology practices threaten to segment addressable populations unpredictably.
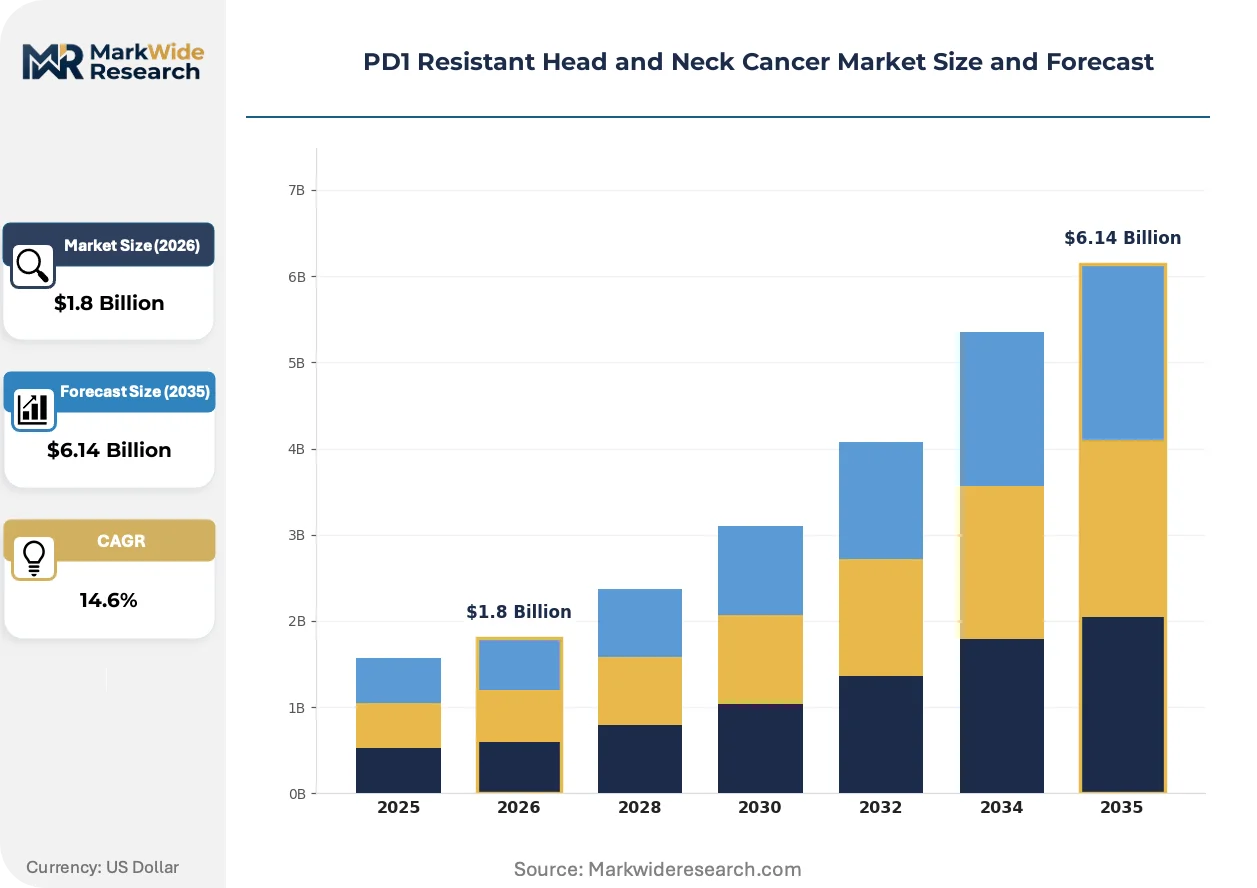
Market Dynamics
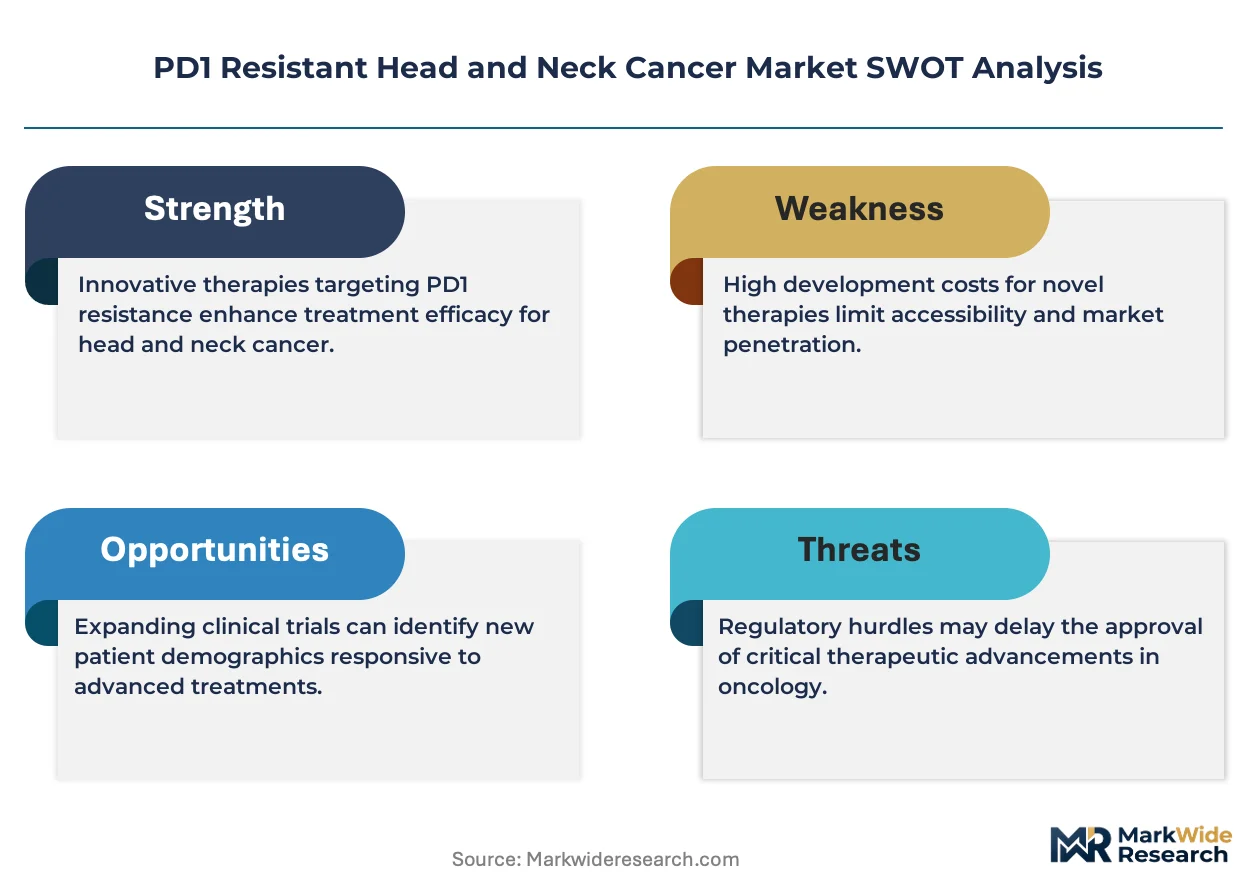
FDA breakthrough therapy designation compresses development timelines for novel checkpoint inhibitors, forcing developers to accelerate biomarker stratification and adaptive trial designs. This regulatory pressure is restructuring capital allocation across immuno-oncology pipelines.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation shortens commercialization timelines for combination immunotherapy protocols, incentivizing investment in bispecific antibody platforms.
- Academic Medical Center Expansion:Oncology departments at leading US academic centers are scaling adoption of tumor-infiltrating lymphocyte engineering and adoptive cell transfer protocols.
- Biomarker Assay Harmonization:PD-L1 expression and tumor mutational burden testing standardization is streamlining trial eligibility and reimbursement pathways across community oncology practices.
Market Restraints
- Clinical Trial Cost Structure:Combination regimen development requires substantially larger patient cohorts and longer follow-up periods than monotherapy studies.
- Regulatory Fragmentation:EMA conditional marketing authorization demands more mature European patient data than FDA accelerated approval, fragmenting launch sequencing.
- Technical Efficacy Limitations:Alternative checkpoint pathway upregulation and tumor microenvironment immunosuppression limit response durability in refractory populations.
Strategic Opportunities
- Underpenetrated Community Oncology:US community oncology practices outside major metropolitan referral networks present expansion potential for biomarker-driven patient identification.
- Technology Convergence:Integration of bispecific antibody platforms with adoptive cell engineering is opening novel mechanism-of-action combinations.
- Precision Medicine Mandates:Payer pressure for actionable mutation identification is accelerating EGFR amplification and PIK3CA alteration testing infrastructure.
Industry Challenges
- Biomarker Interpretation Skill Gap:Pathologists and community oncologists require specialized training in discordant PD-L1 assay platform interpretation.
- Manufacturing Capex Intensity:Tumor-infiltrating lymphocyte engineering and personalized cell therapy production require substantial GMP facility investment.
- Cross-Jurisdictional Compliance Complexity:WHO, FDA, and EMA divergent evidentiary standards for quality-of-life endpoints create protocol design friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PD1 Resistant Head and Neck Cancer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Radiation Therapy, Chemotherapy, Immunotherapy, Targeted Therapy End User: Hospitals, Clinics, Research Institutes, Outpatient Facilities Therapy Area: Oral Cancer, Laryngeal Cancer, Nasopharyngeal Cancer, Oropharyngeal Cancer Biomarker Status: PD-L1 Positive, TMB High, Microsatellite Instable, Others |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., Inc., AstraZeneca plc, Amgen Inc., Boehringer Ingelheim GmbH, Novartis AG, Incyte Corporation, GSK plc, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PD1 Resistant Head and Neck Cancer Market Evolving Landscape
Checkpoint inhibitor development is pivoting from monotherapy optimization toward mechanism-of-action stacking. This shift is compressing traditional development paradigms and restructuring competitive differentiation around combination science rather than single-agent efficacy.
Bispecific antibody platforms targeting alternative immune escape mechanisms are absorbing substantial R&D investment from large-cap developers. Academic medical centers are piloting these constructs in early-phase trials at accelerating enrollment rates. The technology is absorbing market attention previously directed toward next-generation PD1 variants, compressing the addressable window for incremental checkpoint improvements.
EMA conditional marketing authorization requirements are tightening evidentiary standards for European patient-reported outcomes in recurrent disease. This policy divergence is forcing developers to maintain parallel trial cohorts with region-specific endpoints. Combination immunotherapy segments face the most pronounced compliance burden, as overall survival data maturity expectations differ substantially across Atlantic regulatory frameworks.
Referral networks for recurrent and metastatic cases are consolidating around high-volume academic centers with integrated biomarker laboratories. Community oncology practices are losing complex case volume to these centralized hubs, particularly in the southeastern and midwestern United States. This geographic demand rotation is compressing the viable addressable market for developers lacking established academic partnerships.
PD1 Resistant Head and Neck Cancer Market Segmentation
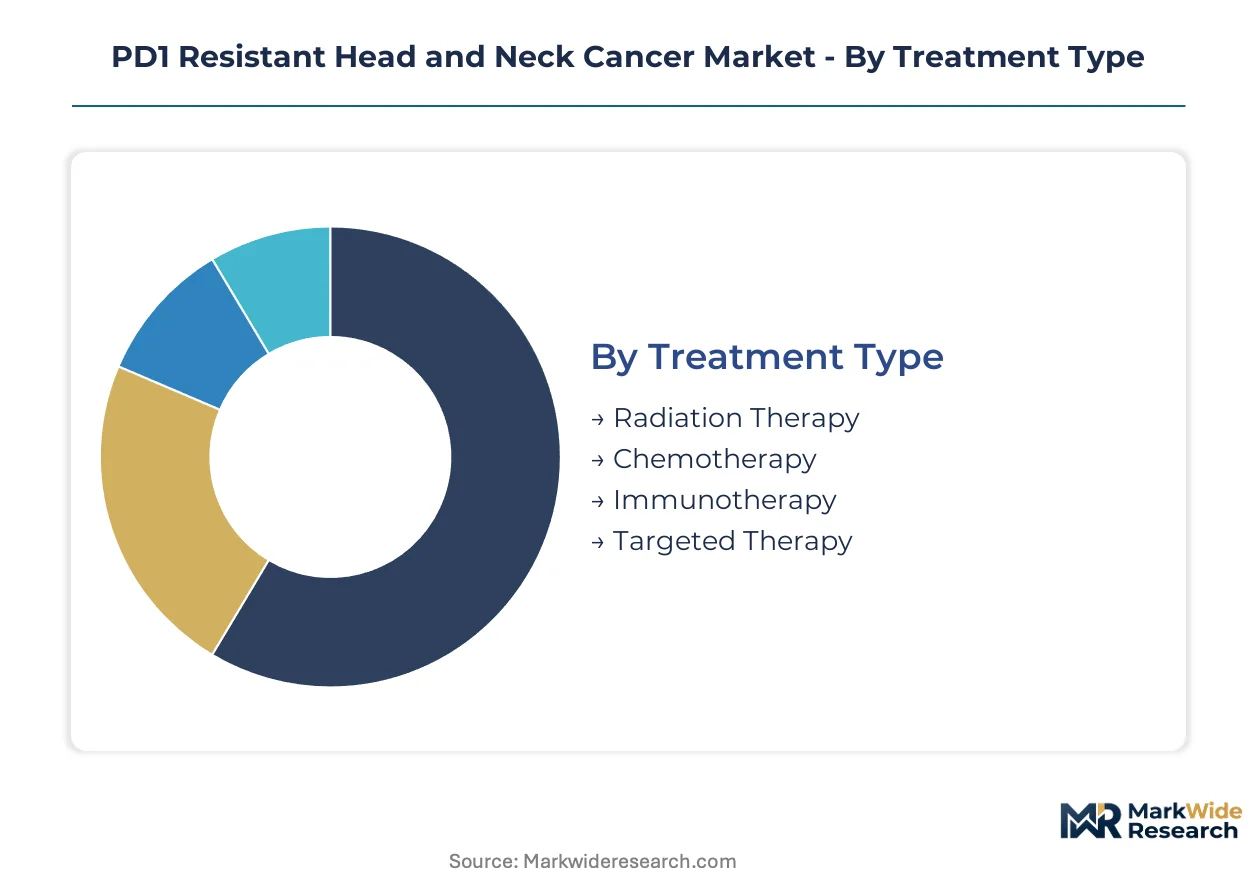
Therapeutic stratification in PD1 resistant head and neck cancer determines clinical trial eligibility, reimbursement pathways, and manufacturing investment priorities. Biomarker-driven patient selection is compressing addressable populations while concentrating value in precision-matched segments.
Treatment Type:
Technology platforms differentiate by mechanism-of-action complexity and capital intensity requirements.
- Immunotherapy:Bispecific antibody platforms and adoptive cell transfer protocols dominate development pipelines. Demand concentrates at academic medical centers in the United States with integrated GMP manufacturing capabilities, driven by FDA breakthrough therapy designation timelines.
- Targeted Therapy:EGFR inhibitors and PIK3CA pathway antagonists serve mutation-defined subpopulations. Commercial traction clusters around community oncology practices with expanded molecular testing infrastructure, constrained by actionable alteration prevalence rates.
- Chemotherapy:Platinum-taxane combinations retain utility in rapid progression settings.
- Radiation Therapy:Re-irradiation protocols apply to locoregional recurrence with limited systemic options.
Mature deployment sits with Chemotherapy. Newer deployment is concentrated in Immunotherapy.
End User:
Site-of-care economics and patient complexity determine referral patterns and protocol adoption rates.
- Hospitals:Comprehensive cancer centers manage combination immunotherapy administration and adverse event monitoring. Volume aggregates at tertiary institutions with embedded phase I trial units, shaped by prior authorization requirements for novel agents.
- Research Institutes:Early-phase trial execution and biomarker assay development occur at NCI-designated centers. Enrollment concentrates in the southeastern and midwestern United States where patient access programs are most developed.
- Clinics:Community-based medical oncology practices handle stable disease monitoring.
- Outpatient Facilities:Infusion centers support recurring administration schedules.
Established infrastructure sits with Hospitals. Expanding capacity is concentrated in Research Institutes.
Therapy Area:
Anatomic subsites vary in molecular profile, prior treatment exposure, and surgical salvage potential.
- Oropharyngeal Cancer:HPV-positive and HPV-negative subtypes exhibit divergent immune microenvironment characteristics. Clinical development prioritizes this segment at US academic centers, propelled by high anti-PD1 first-line exposure rates generating resistant populations.
- Oral Cancer:Surgical resection followed by adjuvant therapy defines standard care. Recurrence management concentrates in high-volume head and neck surgery programs, limited by locoregional pattern complexity.
- Laryngeal Cancer:Organ preservation protocols influence progression patterns.
- Nasopharyngeal Cancer:EBV association shapes immunotherapy response profiles.
Prior therapeutic intensity sits with Oropharyngeal Cancer. Emerging protocol development is concentrated in Oral Cancer.
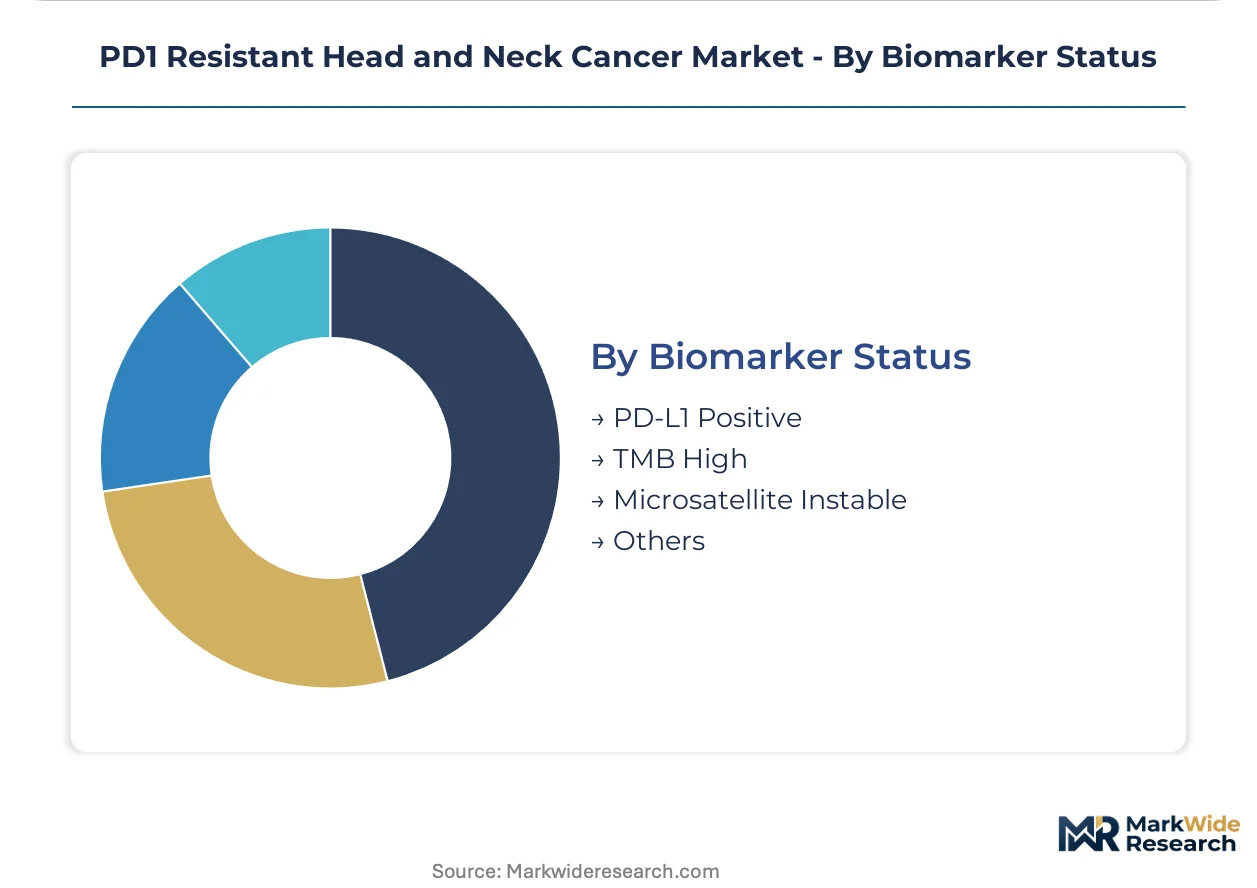
Biomarker Status:
Molecular stratification dictates trial eligibility and payer coverage decisions.
- PD-L1 Positive:Expression thresholds determine combination regimen access. Testing standardization efforts at US community oncology practices are streamlining patient identification, though platform discordance creates interpretation friction.
- TMB High:Tumor mutational burden cutoffs select for neoantigen-rich phenotypes. Assay harmonization between academic centers and commercial laboratories is expanding addressable cohorts, constrained by tissue adequacy requirements.
- Microsatellite Instable:Deficient mismatch repair status enables checkpoint inhibitor rechallenge.
- Others:Emerging signatures include STK11 and KEAP1 alterations.
Established reimbursement sits with PD-L1 Positive. Fastest assay adoption is concentrated in TMB High.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Opportunity Zones and Orphan Drug Tax Credits concentrate pharmaceutical development investment in designated metropolitan clusters. Academic medical centers in these zones access accelerated depreciation schedules for GMP manufacturing facilities. State-level bioscience incentives in Massachusetts, California, and Maryland amplify federal advantages.
United States
FDA breakthrough therapy designation shortens commercialization timelines for combination immunotherapy protocols. The Orphan Drug Act provides seven-year market exclusivity for developers addressing refractory patient populations. MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor the highest-volume early-phase trial enrollment.
Germany
EMA conditional marketing authorization demands mature European patient-reported outcome data, extending development timelines relative to FDA pathways. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on quality-of-life endpoint harmonization. Heidelberg and Munich academic hospital networks concentrate phase I/II trial execution for bispecific antibody platforms.
United Kingdom
NHS England's Cancer Drugs Fund provides conditional reimbursement for promising therapies prior to full NICE appraisal. MHRA post-Brexit regulatory autonomy permits accelerated assessment pathways analogous to FDA breakthrough designation. The Royal Marsden NHS Foundation Trust in London and Christie NHS Foundation Trust in Manchester lead tumor-infiltrating lymphocyte protocol adoption.
Japan
PMDA sakigake designation system compresses review timelines for innovative oncology therapies addressing unmet need. METI funding for regenerative medicine infrastructure supports adoptive cell therapy manufacturing scale-up. National Cancer Center Hospital in Tokyo and Osaka International Cancer Institute concentrate refractory head and neck cancer specialist referral volume.
China
NMPA priority review pathways for breakthrough therapies are converging toward FDA timeline standards. Hainan Boao Lecheng International Medical Tourism Pilot Zone permits early access to non-approved immunotherapy combinations. Beijing Cancer Hospital and Fudan University Shanghai Cancer Center anchor domestic phase I trial capacity expansion.
PD1 Resistant Head and Neck Cancer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanism-of-action categories. Large-cap pharmaceutical developers leverage established immuno-oncology infrastructure to sustain commercial traction in refractory settings. Mid-cap biotechnology firms concentrate R&D investment on bispecific antibody platforms and adoptive cell engineering. Competitive dynamics center on strategic partnerships for GMP manufacturing capacity and biomarker assay co-development.
Within the large-cap diversified tier, Bristol-Myers Squibb Company and Merck & Co., Inc. exemplify players anchoring positions through deep clinical trial investment across combination regimens. AstraZeneca plc occupies a differentiated position via alternative immune escape mechanism targeting. These three entities represent the dominant competitive archetypes: infrastructure-leveraged incumbents, trial-scale investors, and platform-differentiated challengers.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Amgen Inc. |
| Boehringer Ingelheim GmbH |
| Novartis AG |
| Incyte Corporation |
| GSK plc |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Payer consolidation around value-based oncology contracts in the United States is forcing developers to absorb manufacturing complexity and compress margins on combination immunotherapy protocols. This procurement shift rewards sponsors with captive GMP capacity and punishes those dependent on contract manufacturing organizations.
Pricing Analysis
Short lead-time premiums for personalized cell therapy manufacturing command substantial markups over standard biologics production schedules. Pricing stratifies across premium, standard, and economy tiers based on manufacturing modality complexity and biomarker stratification requirements. Cost compression in the chemotherapy backbone segment is intensifying because of generic erosion and biosimilar entry. Community oncology practices exhibit highest price sensitivity due to prior authorization burden and reimbursement lag, while academic medical centers demonstrate lowest sensitivity given trial infrastructure subsidies.
Supply Chain Analysis
Freight costs for temperature-controlled cellular therapy logistics absorb disproportionate share of delivered cost, particularly for autologous products requiring cryogenic chain maintenance. Manufacturing concentration centers on the United States, Germany, and Japan where GMP facility density supports personalized production at scale. Raw material dependencies include recombinant cytokines, viral vector stocks, and synthetic peptide reagents. Single-source vulnerability for lentiviral vector supply creates structural risk exposure. Distribution runs through specialized courier networks with validated cold-chain documentation rather than standard pharmaceutical wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as sponsors pursue backward integration into GMP manufacturing capacity to secure supply certainty and capture margin. Control over lentiviral vector production and cell processing infrastructure represents the decisive upstream lever.
For Market Incumbents: Acquire GMP manufacturing facilities in designated US Opportunity Zones to exploit accelerated depreciation schedules and Orphan Drug Tax Credit advantages. Consolidate positions by locking exclusive supply agreements with academic medical center cell processing laboratories. The threat of mid-cap bispecific antibody specialists securing breakthrough therapy designation ahead of combination data readouts demands preemptive trial enrollment acceleration.
For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for mechanism-of-action stacking strategies that leapfrog monotherapy incumbents. White-space targets include community oncology practices with underdeveloped biomarker testing infrastructure and European markets where EMA conditional marketing authorization timelines lag FDA pathways. The most penetrable segment is tumor-infiltrating lymphocyte engineering for oropharyngeal cancer, where referral network consolidation has not yet completed. A go-to-market angle anchored in platform technology licensing to large-cap partners reduces capital intensity.
For Investors and Strategic Acquirers: The window for entry favors mid-cap biotechnology firms with validated bispecific antibody platforms and established academic medical center partnerships. Long-term viability hinges on demonstrating durable response data in refractory populations and securing reimbursement in at least two major regulatory jurisdictions. The acquisition target archetype combines novel checkpoint mechanism intellectual property with integrated manufacturing capabilities. The signal to watch is biomarker assay harmonization progress, as standardization completion would abruptly expand addressable patient populations and revalue platform assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated enrollment at MD Anderson and Memorial Sloan Kettering compresses FDA breakthrough therapy timelines. |
| Manufacturing Scale-Up | GMP facility investment in Massachusetts and Maryland Opportunity Zones exploits Orphan Drug Tax Credit advantages. |
| Regulatory Approval Pathway | Parallel FDA and EMA submission strategies address divergent quality-of-life endpoint requirements. |
| Strategic Partnership | Biomarker assay co-development with community oncology networks streamlines patient identification infrastructure. |
| Pipeline Diversification | Adoptive cell therapy expansion beyond TIL engineering into CAR-T modalities hedges mechanism-of-action risk. |
Research Methodology
FDA filings, ClinicalTrials.gov, and EMA assessment reports formed the secondary backbone of data collection. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated quantitative assumptions. Bottom-up and top-down triangulation reconciled patient population estimates with revenue projections across treatment modalities.
Bottom-up modeling anchored forecasts in addressable patient cohorts by biomarker status and prior therapy exposure, while top-down analysis cross-checked against immuno-oncology market evolution patterns. Segmentation dimensions included treatment line, administration route, and regional regulatory cluster. CAGRs were derived from patient flow modeling and pricing trajectory assumptions. Forecast inputs incorporated biomarker assay adoption curves and academic medical center capacity expansion plans.
The model assumes a particular technology adoption path; alternative pathways for bispecific antibody platforms would alter the outlook if mechanism-of-action stacking demonstrates superior durability. Forecasts reflect assumptions about FDA breakthrough therapy designation velocity and EMA conditional marketing authorization convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Gynecological Cancer Drugs Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Testicular Cancer Treatment Market
Oncology
Glioblastoma Market
Oncology
Solid Tumor Market
Oncology
Germany Radiotherapy Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Radiation Oncology Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Global Veterinary Oncology Market
Oncology
Precision Oncology Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Single-Room Proton Therapy Systems Market