
 Breast Cancer Brachytherapy Market | 2026-2036
Breast Cancer Brachytherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Cancer Brachytherapy Market Intelligence
Afterloader service contracts is rewriting margin economics across the installed base, pulling recurring revenue from capital equipment vendors toward technical service networks. Elekta AB leverages its Nordic manufacturing footprint to sustain premium positioning in remote afterloader systems. Varian Medical Systems, Inc. anchors North American hospital relationships through integrated software-to-hardware oncology workflows. Hologic, Inc. differentiates in balloon catheter platforms with proprietary strut-based applicator designs.
Breast cancer brachytherapy delivers radioactive sources directly to tumor beds via interstitial needles, intracavitary balloons, or surface applicators, typically using iridium-192 or iodine-125 isotopes with dose rates calibrated in gray per hour for precise tissue sparing. The technique serves primarily as adjuvant radiation following lumpectomy, reducing treatment courses from six weeks to five days in select patients. High-dose-rate afterloaders dominate capital expenditure budgets while balloon catheters capture accelerated procedure volumes in ambulatory settings. Low-dose-rate seed implants retain stable demand in permanent prostate crossover applications, though breast-specific adoption plateaus.
FDA 21 CFR Part 820, NRC 10 CFR Part 35, and ISO 13485 collectively govern device design controls, radioactive materials handling, and quality management system certification for market access. These frameworks elevate compliance costs for entrants while rewarding incumbents with established regulatory infrastructure. Stakeholders must monitor reimbursement parity between hypofractionated external beam and brachytherapy fractions as payers consolidate oncology pathways.
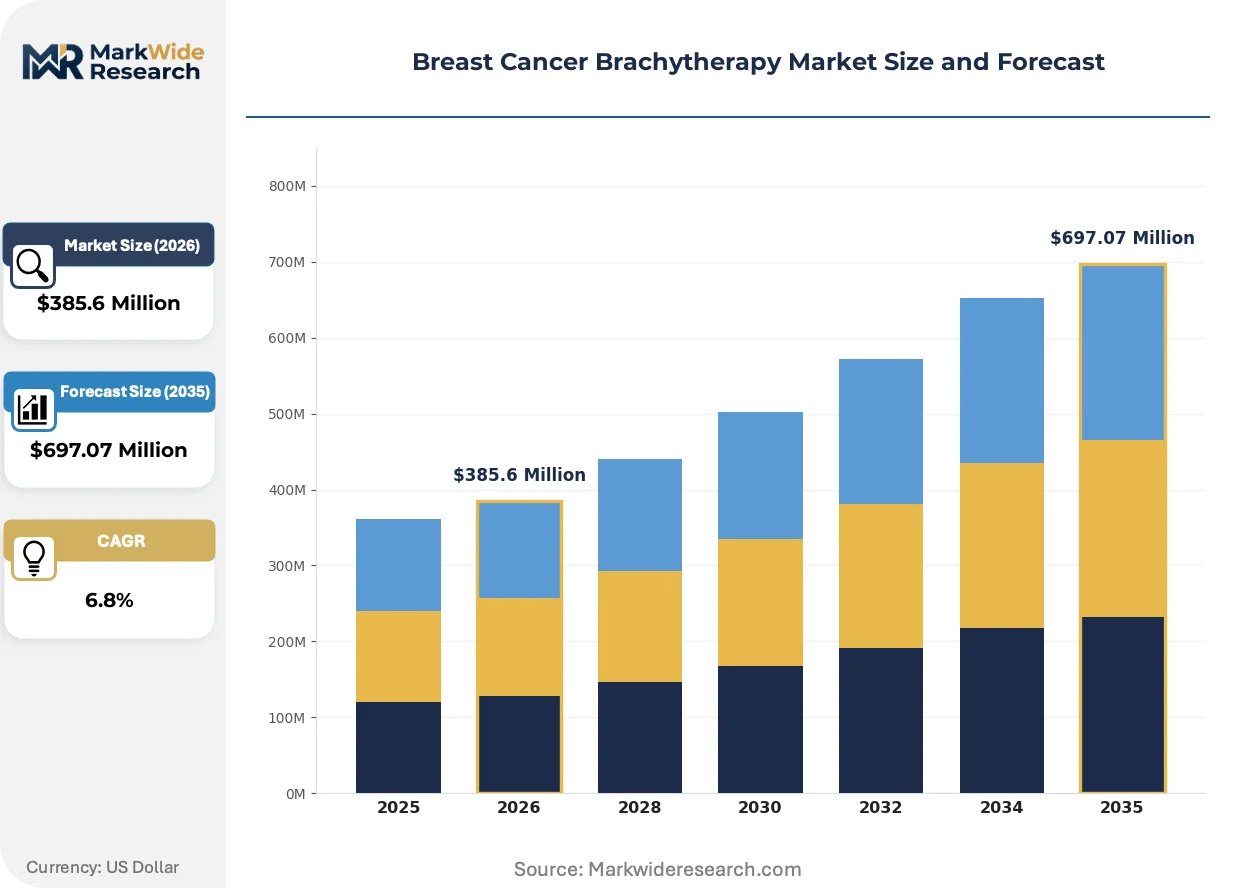
Market Dynamics
Afterloader service contracts are consolidating technical expertise around independent service organizations, diverting recurring revenue streams from original equipment manufacturers toward specialized repair networks. This structural shift compresses vendor margins while elevating clinical uptime guarantees as a competitive differentiator.
Growth Catalysts
- Hypofractionated protocols:Five-day treatment regimens approved by the FDA for select early-stage patients compress care delivery timelines and expand ambulatory surgical center eligibility.
- Iridium-192 source optimization:Miniaturized high-activity sources enable more precise dwell-time modulation, improving dose conformity to irregular tumor beds.
- United States:Medicare reimbursement parity between external beam and brachytherapy fractions sustains procedure economics in hospital outpatient departments.
Market Restraints
- Isotope supply concentration:Molybdenum-99 decay chain dependencies and limited commercial irradiation reactors create source availability volatility.
- Capital intensity:High-dose-rate afterloader systems require shielded vault construction and remote handling infrastructure, elevating facility entry costs.
- Technical workforce scarcity:Board-certified medical physicists with brachytherapy specialization remain concentrated in academic medical centers, constraining community expansion.
Strategic Opportunities
- Surface applicator expansion:Electronic brachytherapy platforms using miniature X-ray sources enable intraoperative radiation delivery without radioactive isotope handling.
- India:CDSCO streamlined medical device registration pathways and rising breast cancer incidence create first-mover potential in tier-one oncology centers.
- Integrated software workflows:DICOM-RT connectivity between treatment planning systems and afterloader control units reduces manual transcription errors and accelerates quality assurance.
Industry Challenges
- Legacy system interoperability:Proprietary communication protocols between decade-old afterloaders and modern oncology information systems demand costly middleware development.
- Quality management system maintenance:FDA 21 CFR Part 820 and ISO 13485 surveillance audits require dedicated regulatory affairs personnel, burdening mid-sized device vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Cancer Brachytherapy Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Implants, Balloon Catheters, Applicators, Afterloaders Delivery Mode: Interstitial, Intracavitary, Surface, Permanent End User: Hospitals, Oncology Clinics, Research Institutes, Home Care Technique: Low Dose Rate, High Dose Rate, Pulsed Dose Rate, Intraoperative |
| Companies Covered | Eckert & Ziegler BEBIG, Elekta AB, Varian Medical Systems, Inc., Hologic, Inc., iCAD, Inc., Merit Medical Systems, Becton Dickinson and Company, IsoAid LLC, Cianna Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Cancer Brachytherapy Market Strategic Shifts & Innovations
Three distinct vectors are restructuring competitive advantage in breast cancer brachytherapy: source technology miniaturization, regulatory data requirements for software-enabled devices, and the unbundling of equipment ownership from clinical service delivery.
High-dose-rate afterloader technology is migrating from cobalt-60-based gamma sources toward miniature X-ray generators and electronic brachytherapy platforms. Academic medical centers in the United States and Germany are piloting these systems for intraoperative partial breast irradiation. This migration is compressing the radioactive materials licensing burden while shifting capital expenditure toward disposable applicator consumables.
Europe's Medical Device Regulation (MDR) is imposing enhanced clinical evidence requirements for software-as-a-medical-device components embedded in treatment planning systems. Manufacturers must now submit post-market surveillance data and periodic safety update reports for algorithm-driven dose optimization modules. Small and mid-sized vendors with limited notified body relationships face extended certification timelines, advantaging incumbents with established European regulatory infrastructure.
Ambulatory surgical centers are unbundling equipment ownership from procedure delivery through managed service arrangements with third-party radiation oncology management companies. These entities assume capital risk, regulatory compliance, and physicist staffing responsibilities while facilities retain patient volume and billing rights. Texas, Florida, and Arizona exhibit the highest concentration of these arrangements, driven by certificate-of-need deregulation and freestanding surgery center proliferation.
Breast Cancer Brachytherapy Market Segmentation
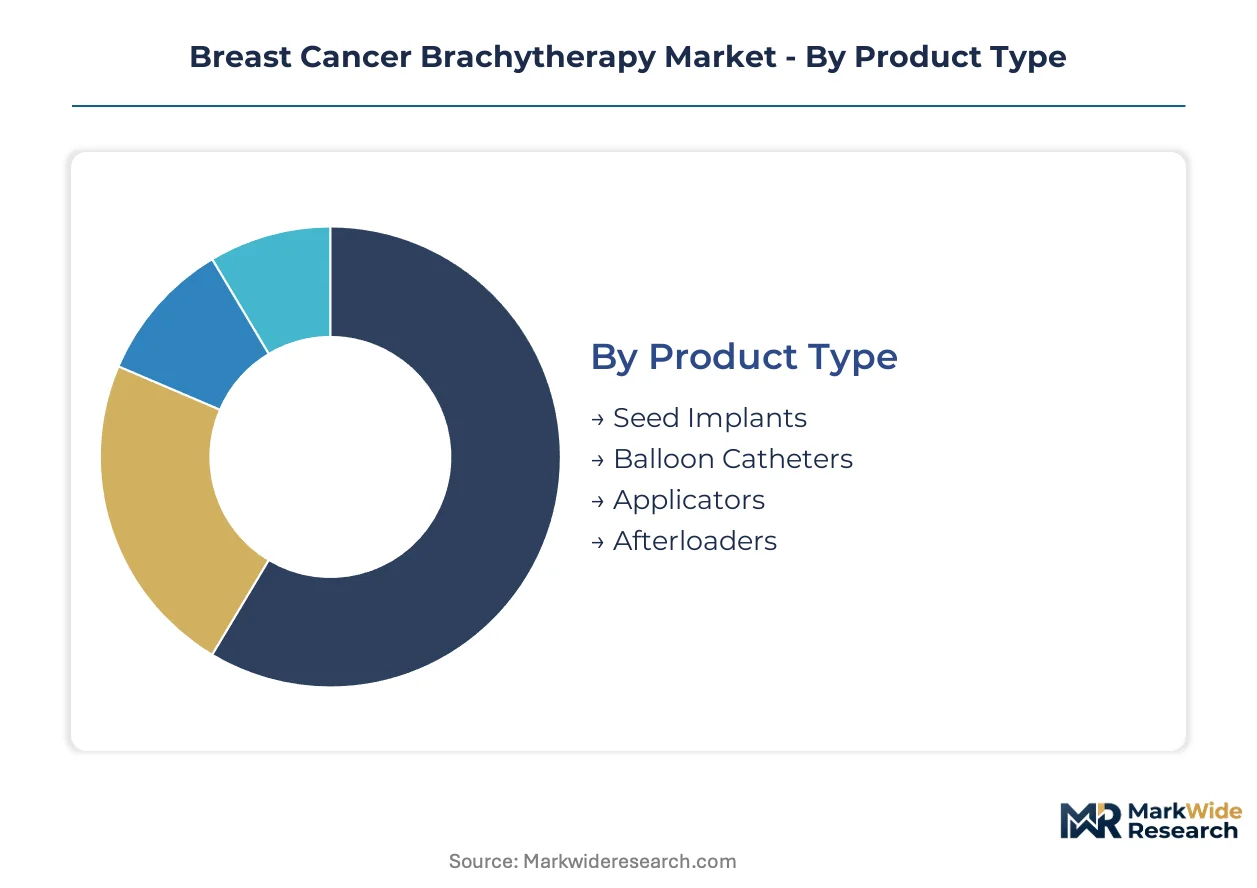
Brachytherapy equipment generates substantial recurring revenue through source replacement cycles, physicist staffing contracts, and shielding maintenance obligations. Segment boundaries in this market reflect capital intensity gradients, regulatory licensing tiers, and procedure volume concentration patterns across care delivery settings.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with afterloader systems demanding 15-20% annual contract value for source logistics and vault compliance versus disposable applicators with minimal post-sale engagement.
- Afterloaders:Remote HDR systems with motorized source delivery mechanisms require NRC-licensed physicists for weekly quality assurance checks. United States hospital outpatient departments concentrate procurement of these systems where Medicare reimbursement parity sustains capital recovery timelines.
- Balloon Catheters:Strut-based and multi-lumen designs enable dose modulation through dwell-time programming. Ambulatory surgical centers in Texas and Florida drive volume acceleration as certificate-of-need deregulation permits freestanding radiation oncology service lines.
- Seed Implants:Permanent LDR iodine-125 pellets for prostate crossover applications carry stable demand but plateauing breast-specific adoption.
- Applicators:Interstitial needle templates and surface molds vary in complexity from standardized kits to patient-specific 3D-printed guides.
By volume, balloon catheters lead. By growth pace, afterloader service contracts are expanding most quickly.
Delivery Mode:
Procedure reimbursement structures favor modalities completing treatment courses within single calendar weeks, compressing demand toward accelerated delivery mechanisms.
- Intracavitary:Balloon-based luminal insertion following lumpectomy enables five-day fractionation protocols FDA-cleared for select early-stage patients. Oncology clinics prioritize this modality for throughput efficiency in limited vault capacity environments.
- Interstitial:Multi-catheter implantation with template guidance delivers superior dose conformity for irregular tumor beds. Academic medical centers concentrate adoption where medical physicist specialization supports complex dwell-time optimization.
- Surface:Electronic brachytherapy platforms using miniature X-ray sources eliminate radioactive materials licensing burdens for intraoperative partial breast irradiation.
- Permanent:LDR seed placement retains stable prostate application demand with minimal breast-specific utilization.
By procedure volume, intracavitary dominates. By regulatory simplification appeal, surface delivery gains share fastest.
End User:
Capital deployment patterns diverge between integrated health systems absorbing shielding construction costs and ambulatory operators leasing turnkey radiation oncology management arrangements.
- Hospitals:Academic medical centers anchor HDR afterloader installed base with captive medical physicist staffing and comprehensive quality management systems for FDA 21 CFR Part 820 compliance.
- Oncology Clinics:Freestanding facilities concentrate balloon catheter procedure volumes through managed service partnerships assuming capital risk and regulatory liability.
- Research Institutes:Pilot sites for electronic brachytherapy and intraoperative radiation platforms generate clinical evidence for expanded indication applications.
- Home Care:Minimal penetration limited by radioactive materials handling restrictions and NRC licensing requirements for patient discharge protocols.
By installed equipment value, hospitals lead. By volume expansion trajectory, oncology clinics climb the fastest.
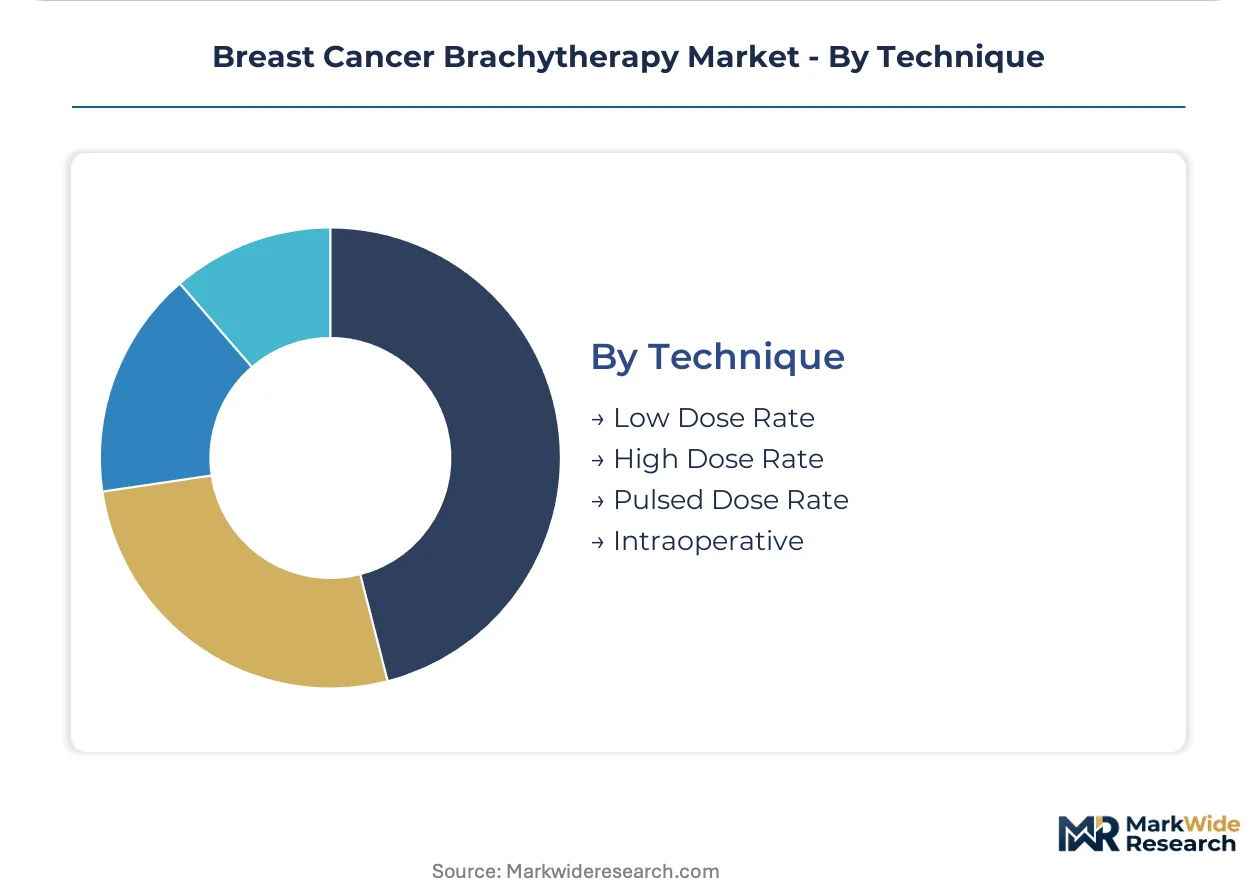
Technique:
Dose rate selection determines source logistics complexity, with high-activity iridium-192 requiring weekly exchange versus permanent implants with zero ongoing supply chain exposure.
- High Dose Rate:Iridium-192 sources with remote afterloader delivery enable outpatient fractionation completing treatment in five days. United States facilities concentrate adoption where Medicare reimbursement sustains procedure economics against hypofractionated external beam alternatives.
- Intraoperative:Single-fraction delivery during lumpectomy using electronic brachytherapy or mobile HDR systems eliminates postoperative radiation courses. German and United States academic centers pilot these platforms for patient convenience and cost compression.
- Low Dose Rate:Permanent seed implants retain prostate crossover demand with declining breast-specific utilization.
- Pulsed Dose Rate:Intermediate kinetics offering theoretical tissue repair advantages with limited commercial system availability.
By procedure volume, high dose rate dominates. By clinical protocol innovation, intraoperative techniques show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for integrated software-to-hardware workflows, while Indian procurement prioritizes cost-efficient balloon catheter platforms. European facilities navigate MDR compliance costs that compress vendor margins.
United States
Medicare reimbursement parity between external beam and brachytherapy fractions sustains procedure economics in hospital outpatient departments. FDA 21 CFR Part 820 quality system regulations govern device commercialization timelines, elevating compliance costs for entrants. Texas and Florida ambulatory surgical centers concentrate managed service arrangements with third-party radiation oncology management companies.
Germany
Academic medical centers pilot electronic brachytherapy platforms for intraoperative partial breast irradiation, compressing radioactive materials licensing burdens. EMA and national regulators enforce MDR clinical evidence requirements for software-enabled treatment planning systems. Berlin and Munich anchor HDR afterloader installed base with captive medical physicist staffing.
India
Rising breast cancer incidence and CDSCO streamlined medical device registration pathways create first-mover potential in tier-one oncology centers. The country's national pharmaceutical regulator accelerates approval timelines for balloon catheter platforms. Maharashtra and Karnataka concentrate oncology infrastructure expansion in Mumbai and Bengaluru metro corridors.
Japan
PMDA oversees quality management system certification for market access, rewarding incumbents with established regulatory infrastructure. METI industrial policy supports domestic medical device manufacturing competitiveness. Tokyo and Osaka academic centers concentrate adoption of complex interstitial techniques requiring specialized dwell-time optimization.
United Kingdom
NHS reimbursement frameworks favor hypofractionated protocols completing treatment courses within single calendar weeks. MHRA post-Brexit regulatory autonomy maintains alignment with MDR standards while streamlining national approval pathways. London and Manchester hospital networks concentrate HDR afterloader procurement with integrated software workflows.
Breast Cancer Brachytherapy Market Key Industry Players
Integrated oncology workflow vendors and specialized applicator manufacturers split the market along capital intensity gradients. The vendor base concentrates around three strategic archetypes: Nordic-based remote afterloader system builders, North American integrated software-to-hardware providers, and balloon catheter platform specialists. Dominant competitive moves include managed service partnerships assuming capital risk and regulatory liability, plus DICOM-RT connectivity investments reducing manual transcription errors.
Within the integrated systems tier, Elekta AB and Varian Medical Systems, Inc. exemplify contrasting geographic anchoring strategies for oncology workflow dominance. Elekta leverages its Nordic manufacturing footprint to sustain premium positioning in remote afterloader systems, while Varian anchors North American hospital relationships through software-to-hardware integration. Hologic, Inc. occupies a position within the specialized applicator archetype, differentiating through proprietary strut-based designs that enable dose modulation in ambulatory settings.
| Leading Market Players |
|---|
| Eckert & Ziegler BEBIG |
| Elekta AB |
| Varian Medical Systems, Inc. |
| Hologic, Inc. |
| iCAD, Inc. |
| Merit Medical Systems |
| Becton Dickinson and Company |
| IsoAid LLC |
| Cianna Medical |
| Others |
Cost & Logistics Intelligence
Antwerp-Rotterdam-Amsterdam freight corridors govern iridium-192 source logistics costs, concentrating pricing power with NRC-licensed distributors while forcing ambulatory surgical centers toward bundled service contracts that absorb volatility.
Pricing Analysis
After-sales service contracts capture lifetime value across the installed base, with annual maintenance agreements running 15-20% of capital cost for HDR afterloader systems. Pricing stratifies across premium remote afterloader platforms, standard balloon catheter kits, and economy-grade applicator disposables based on software integration depth and physicist staffing bundling. Cost compression in disposable applicators intensifies as independent service organizations undercut OEM service networks. Community oncology clinics exhibit highest price sensitivity versus academic medical centers absorbing premium positioning for integrated workflow systems.
Supply Chain Analysis
Isotope supply concentration between Belgian commercial irradiation reactors and South African molybdenum-99 processing facilities dominates downstream availability risk for iridium-192 sources. The chain draws from specialized stainless steel shielding fabrication in Germany, precision motor assemblies in Japan, and disposable polymer applicator molding in Malaysia. Single-source vulnerability runs through the limited global fleet of high-flux research reactors generating medical radioisotopes. Distribution runs through NRC-licensed radiopharmaceutical networks with mandatory chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breast cancer brachytherapy sits in early-cycle expansion as five-day hypofractionated protocols displace six-week external beam courses, compressing treatment timelines and unlocking ambulatory surgical center penetration.
For Market Incumbents: Insulate installed base relationships by deepening physicist staffing contracts and DICOM-RT software integration investments that elevate switching costs. Electronic brachytherapy platforms threaten radioactive materials licensing advantages, demanding preemptive pilot partnerships with academic centers to capture clinical evidence generation.
For New Entrants and Emerging Players: Tier-one oncology centers in Maharashtra and Karnataka offer underpenetrated white-space as CDSCO streamlines balloon catheter registration pathways. Surface applicator segments for intraoperative radiation delivery present the most penetrable entry point, with managed service partnerships offering capital-light go-to-market positioning.
For Investors and Strategic Acquirers: Specialized applicator manufacturers with proprietary 3D-printed guide capabilities and established GPO contracts represent priority acquisition targets. Long-term viability hinges on reimbursement parity maintenance between brachytherapy and hypofractionated external beam fractions. Watch Medicare coding decisions for intraoperative techniques as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare coding alignment for five-day hypofractionated protocols sustains procedure economics. |
| Hospital System Partnership | Integrated software-to-hardware contracts with GPOs lock in multi-year afterloader placements. |
| CE Marking Pathway | MDR clinical evidence requirements for software-enabled planning systems advantage incumbents. |
| Software Companion Development | DICOM-RT connectivity modules reduce manual transcription errors and accelerate quality assurance. |
| FDA Submission | Electronic brachytherapy platforms for intraoperative partial breast irradiation expand indication scope. |
Research Approach
Cross-validation between hospital procurement databases and CMS Medicare reimbursement data anchors the qualitative findings in this study. Primary interviews with radiation oncologists, medical physicists, GPO contracts managers, and biomedical engineers combined with secondary validation against FDA 510(k) filings, NRC licensing records, and hospital capital expenditure disclosures. Bottom-up equipment unit economics and top-down oncology service line revenue triangulation ensure segmentation consistency.
Calibration against historical procedure volume trajectories and reimbursement policy shifts shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, technique, and dose rate classification. CAGRs derive from fitted growth curves applied to equipment replacement cycles and procedure volume elasticity. Forecast inputs incorporate physicist workforce supply constraints and isotope reactor maintenance schedules.
Practitioners should monitor reimbursement coding decisions, isotope reactor outages, and MDR certification timelines for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Europe Proton Therapy Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Cancer Supportive Care Products Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
South Korea Radiotherapy Market
Oncology
Tumor Ablation Market
Oncology
Glottic Cancer Treatment Market
Oncology
Colorectal Cancer Treatment Market
Oncology
North America Proton Therapy Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Cancer API Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Osteosarcoma Market
Oncology
Radiotherapy Market