
 Buruli Ulcer Treatment Market | 2026-2036
Buruli Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Buruli Ulcer Treatment Market Outlook
Multi-source procurement of rifampicin-clarithromycin combination therapies is expanding as endemic-country health ministries diversify antibiotic suppliers to mitigate stockout risks. GlaxoSmithKline leverages its established anti-infectives manufacturing footprint to sustain preferential pricing agreements with WHO prequalification programs. Cipla anchors generic production capacity for clarithromycin formulations, competing on cost in African tender markets. Novartis differentiates through its infectious disease R&D pipeline, occupying a technology leadership position in novel mycolactone-targeting compounds.
Buruli ulcer treatment encompasses pharmacological and surgical interventions targeting Mycobacterium ulcerans infection, with standard-of-care combining eight-week rifampicin-clarithromycin oral regimens and debridement procedures for necrotic lesions. The primary purpose is limb preservation and disability prevention in predominantly rural tropical populations where delayed diagnosis advances tissue destruction. Antibiotics dominate product type value pools due to sustained demand for combination oral therapy, while wound care products represent the fastest-growing segment as negative-pressure wound therapy gains adoption in referral hospitals. Hospital treatment anchors application volume, though community health programs show structural expansion as mass drug administration models integrate Buruli ulcer screening into existing NTD platforms.
WHO prequalification standards, FDA antibacterial drug development guidance, and national medicines regulatory authorities in Ghana and Côte d'Ivoire shape product registration pathways and quality benchmarks for antibiotic suppliers. EMA orphan drug incentives influence European-headquartered firms' R&D allocation toward neglected tropical disease indications. Stakeholders must monitor clarithromycin supply chain resilience and emerging mycolactone virulence factor inhibitors to inform portfolio decisions.
Market Dynamics
The Buruli Ulcer Treatment Market pivots on WHO's mass drug administration infrastructure expansion, which is reconfiguring how rifampicin-clarithromycin regimens reach endemic rural populations through integrated neglected tropical disease platforms rather than standalone vertical programs.
Growth Catalysts
- WHO Prequalification Program:Streamlined antibiotic quality benchmarks accelerate supplier onboarding for endemic-country tenders. Ghana's national medicines regulatory authority leverages these standards to fast-track registration of combination therapies.
- Community Health Worker Networks:Trained village health teams in Benin and Côte d'Ivoire extend screening reach into remote cocoa-growing regions where clinic access remains limited.
- Mycolactone Pathway Research:Academic consortia mapping bacterial virulence mechanisms generate targets for adjunctive therapeutics that could shorten treatment duration.
Market Restraints
- Clarithromycin Supply Concentration:Active pharmaceutical ingredient production clusters in South Asia create vulnerability to export restriction shocks and quality inconsistency.
- Cold Chain Requirements:Rifampicin stability demands complicate last-mile distribution in tropical climates lacking reliable refrigeration infrastructure.
- Diagnostic Delay:Polymerase chain reaction confirmation requires laboratory capacity absent in most district hospitals, permitting disease progression to irreversible tissue destruction.
Strategic Opportunities
- Point-of-Care Diagnostics:Loop-mediated isothermal amplification tests under field validation in Ghana could decentralize confirmation to village level.
- Negative-Pressure Wound Therapy:Referral hospitals in Côte d'Ivoire pilot device-based wound management for extensive lesions previously requiring prolonged hospitalization.
- EMA Orphan Drug Incentives:European developers access protocol assistance and fee waivers for novel mycolactone inhibitors targeting the cytotoxin directly.
Industry Challenges
- Antimicrobial Resistance Surveillance:Mycobacterium ulcerans strain monitoring demands molecular laboratory capacity that national health systems struggle to sustain.
- Health Worker Training:Surgical debridement competency for necrotic lesions requires supervised practice hours that overstretched district surgical officers cannot complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buruli Ulcer Treatment Market |
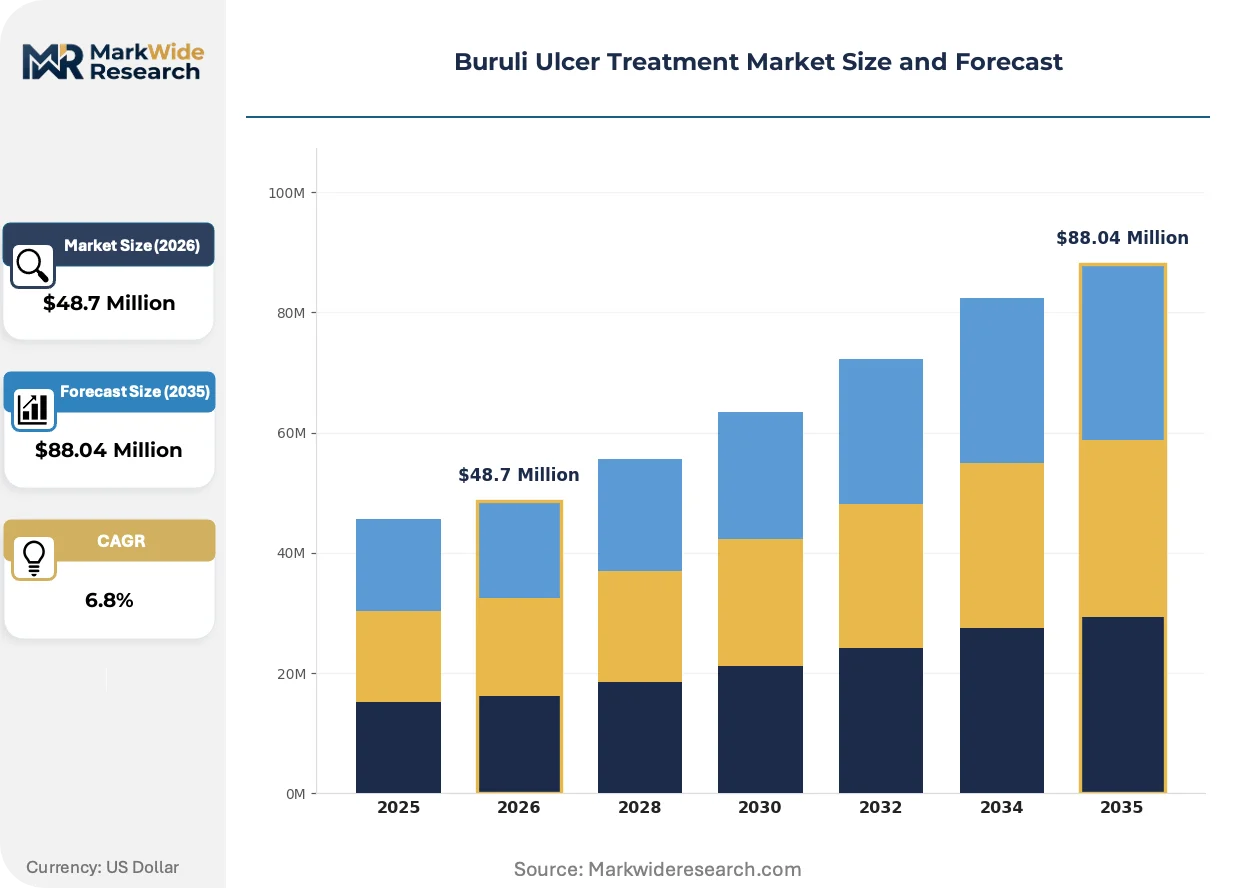
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Procedures, Wound Care Products, Supportive Treatments End User: Hospitals, Clinics, Home Care, Research Institutions Delivery Mode: Oral, Injectable, Topical, Intravenous Application: Hospital Treatment, Community Health Programs, Research Studies, Preventive Care |
| Companies Covered | B. Braun Melsungen, Teva Pharmaceutical Industries, GlaxoSmithKline, Bayer, AbbVie, Pfizer, Cipla, Lupin Laboratories, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buruli Ulcer Treatment Market Strategic Shifts
Antibiotic stewardship imperatives and wound care technology maturation are converging to reshape therapeutic protocols, with emphasis shifting from prolonged hospitalization toward ambulatory management supported by community-based adherence monitoring.
Negative-pressure wound therapy is integrating into referral hospital protocols for extensive Buruli ulcer lesions, replacing conventional moist dressings in cases where surgical debridement alone proves insufficient. Plastic surgery units in Ghana's teaching hospitals adopt these systems to accelerate granulation tissue formation and reduce graft failure rates. The technology is compressing average length of stay for complicated cases while transferring wound monitoring burden to outpatient nursing services.
EMA's orphan drug framework now explicitly includes neglected tropical disease indications, lowering regulatory barriers for European-headquartered developers pursuing mycolactone-targeting small molecules. The industrial consequence is redirected R&D allocation toward host-directed therapies that could reduce antibiotic exposure duration. Early-phase candidates face preclinical toxicology requirements shaped by EMA's pediatric investigation plan obligations, given the disease's childhood prevalence.
Health ministries in endemic countries consolidate antibiotic procurement through pooled purchasing mechanisms coordinated by WHO's Global Drug Facility, displacing fragmented national tender processes that previously generated price volatility and stockout cycles. The pooled model aggregates demand from Ghana, Benin, and Côte d'Ivoire into single-supplier contracts with volume guarantees. This concentration is most visible in West African franc zone countries where currency harmonization simplifies cross-border procurement administration.
Buruli Ulcer Treatment Market Segmentation
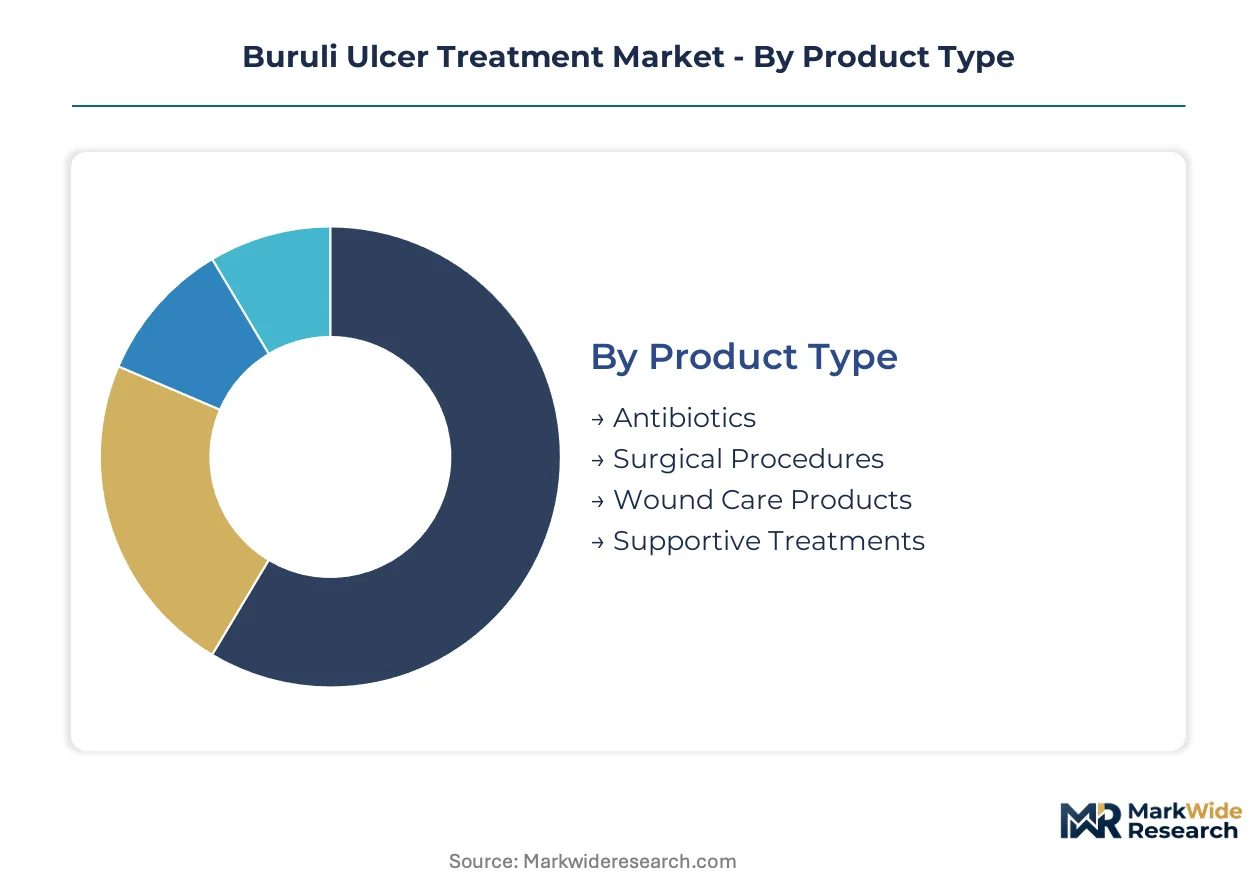
Segmentation in the Buruli ulcer treatment market reveals how regulatory pathways, procurement channels, and care settings fragment demand across distinct product and service categories. Each segment carries specific certification requirements that shape supplier eligibility and pricing power in endemic-country tenders.
Product Type:
WHO prequalification status and national medicines regulatory authority registration requirements create divergent market access conditions across product categories, with antibiotics facing the most stringent quality benchmarks.
- Antibiotics:Rifampicin-clarithromycin combination regimens constitute the pharmacological backbone of standard care, requiring WHO prequalification or stringent review by Ghana's Food and Drugs Authority and Côte d'Ivoire's national pharmaceutical regulator for tender eligibility. Demand concentrates in West African public health programs where eight-week oral protocols dominate first-line management.
- Wound Care Products:Negative-pressure wound therapy devices and advanced dressings are gaining adoption in Ghana's teaching hospitals and Côte d'Ivoire's regional referral centers, driven by surgical units seeking to reduce graft failure rates and compress length of stay for extensive lesions.
- Surgical Procedures:Debridement and skin grafting interventions require sterile equipment procurement through hospital supply chains.
- Supportive Treatments:Pain management and nutritional supplementation support adherence to prolonged antibiotic regimens.
Antibiotics sit at the top of the volume ranking, with wound care products climbing the fastest.
End User:
Procurement authority and reimbursement pathways determine how treatment flows reach patients, with public sector institutions commanding preferential pricing through pooled purchasing mechanisms.
- Hospitals:Regional referral and teaching hospitals in Ghana, Benin, and Côte d'Ivoire anchor surgical capacity for complicated lesions, managing procurement through national health insurance schemes and ministerial budget lines.
- Clinics:District health facilities serve as diagnostic and treatment initiation points, with staffing constraints limiting surgical intervention capability.
- Home Care:Village health workers extend adherence monitoring and wound dressing changes into remote cocoa-growing regions.
- Research Institutions:Academic medical centers in Abidjan and Accra host clinical trials for novel mycolactone inhibitors and point-of-care diagnostics.
Hospitals capture the largest procurement volumes, though home care is expanding most quickly as community health worker networks mature.
Delivery Mode:
Stability requirements and cold chain infrastructure shape which delivery modes reach rural populations, with oral formulations dominating decentralized care.
- Oral:Fixed-dose rifampicin-clarithromycin tablets enable ambulatory management without refrigeration dependency, making this the default for community-based treatment programs across West Africa's tropical climates.
- Injectable:Intravenous and intramuscular routes serve hospitalized patients with severe complications or surgical needs.
- Topical:Wound care applications include antimicrobial dressings and topical analgesics.
- Intravenous:Reserved for severe sepsis or surgical preparation in tertiary facilities.
Oral delivery commands the highest treatment volumes, while topical applications are gaining share fastest through advanced wound care adoption.
Application:
Program architecture determines funding flows and procurement scale, with integrated neglected tropical disease platforms displacing standalone vertical programs.
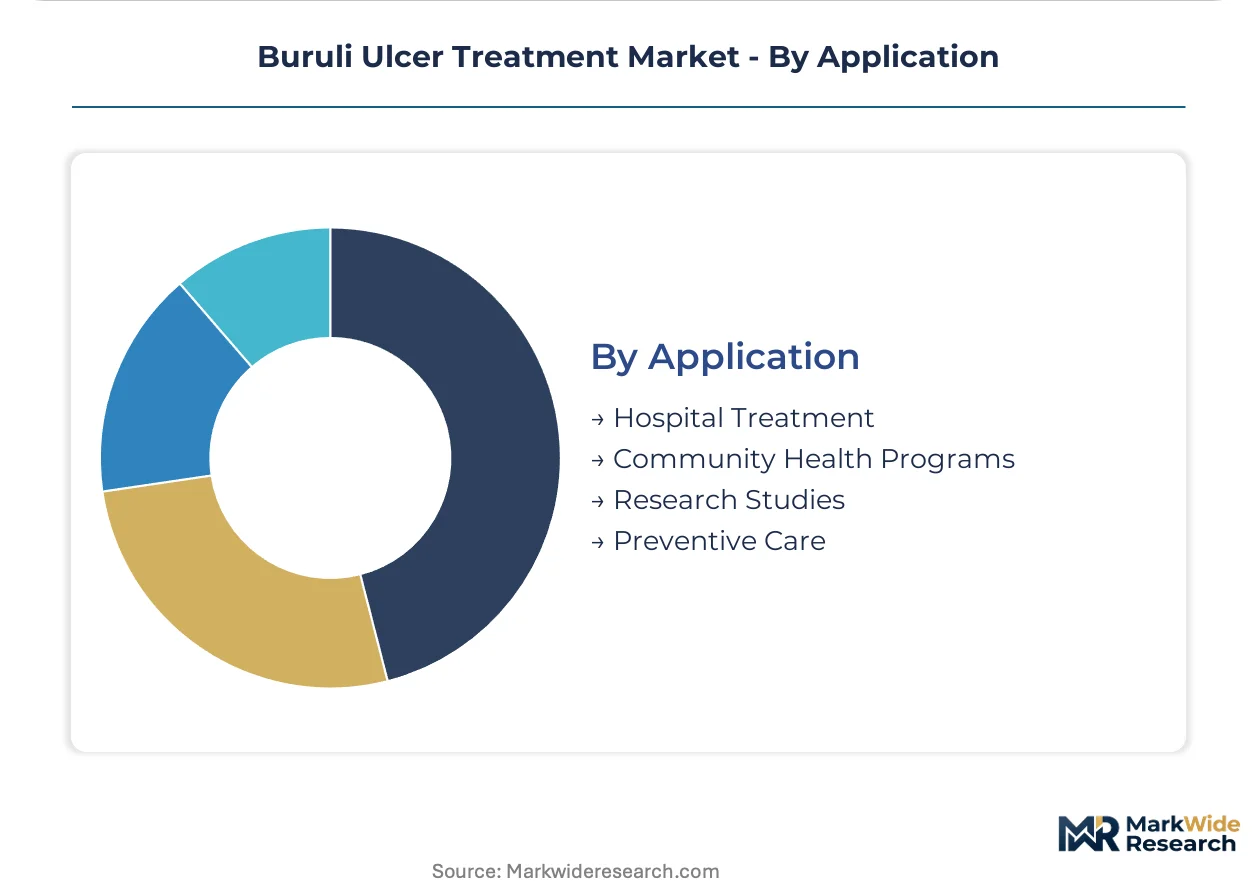
- Hospital Treatment:Tertiary and secondary facilities manage complicated lesions requiring surgical debridement, skin grafting, or negative-pressure wound therapy, funded through national health insurance and ministerial budget allocations.
- Community Health Programs:Mass drug administration infrastructure in Benin and Côte d'Ivoire integrates Buruli ulcer screening and treatment adherence monitoring into existing onchocerciasis and lymphatic filariasis platforms.
- Research Studies:Academic consortia and pharmaceutical sponsors fund investigator-initiated trials of shortened antibiotic regimens and host-directed therapies.
- Preventive Care:Early detection campaigns and vector control measures operate through district health management teams.
Hospital treatment retains the largest patient volume, with community health programs showing the steepest expansion trajectory as WHO integration policies take hold.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibiotic production for Buruli ulcer treatment migrates toward jurisdictions with streamlined active pharmaceutical ingredient registration pathways, creating compliance-cost arbitrage between established European manufacturers and emerging South Asian suppliers.
Ghana
The Ghana Health Service operates Africa's most extensive Buruli ulcer surveillance network, with Korle Bu Teaching Hospital in Accra managing surgical referrals for necrotic lesions. The country's Food and Drugs Authority applies WHO prequalification standards to fast-track rifampicin-clarithromycin registrations. Manufacturing partnerships with Indian generic producers secure preferential pricing for eight-week combination regimens distributed through district health facilities.
Benin
Community health worker networks in the Ouémé and Atlantique departments extend screening into remote cocoa-growing regions where clinic access remains limited. The national neglected tropical disease program integrates Buruli ulcer treatment into existing onchocerciasis mass drug administration platforms. Cotonou's central pharmacy coordinates pooled procurement with neighboring franc zone countries to stabilize antibiotic supply chains.
Côte d'Ivoire
Treicheville University Hospital in Abidjan anchors surgical capacity for extensive lesions requiring skin grafting or negative-pressure wound therapy. The national pharmaceutical regulator enforces WHO quality benchmarks for clarithromycin imports while supporting local production feasibility studies. Research collaborations with European academic consortia test point-of-care diagnostics in the Comoé district.
Australia
Victoria's Department of Health maintains passive surveillance for imported cases among returned travelers from endemic regions. The Therapeutic Goods Administration recognizes WHO prequalification for antibiotic registrations used in compassionate access protocols. Melbourne's Burnet Institute conducts molecular epidemiology research on Mycobacterium ulcerans strain evolution in Pacific Island settings.
France
ANSM oversees orphan drug applications for novel mycolactone inhibitors developed by Paris-based research consortia targeting shortened treatment durations. The national reference center for mycobacterial infections at Hôpital Saint-Louis manages imported case consultations. Lyon-based pharmaceutical clusters contribute to EMA-funded neglected tropical disease research initiatives.
Buruli Ulcer Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mycolactone-targeting therapeutics and point-of-care diagnostic platforms. The antibiotic supply segment consolidates around WHO-prequalified generic manufacturers with proven cold chain distribution capabilities into West Africa. Three archetypes dominate: multinational pharmaceutical conglomerates with infectious disease portfolios, specialized generic producers focused on African tender markets, and research-stage biopharmaceutical developers advancing host-directed therapies. Competitive dynamics center on strategic partnerships with endemic-country health ministries and technology licensing for novel virulence factor inhibitors.
Within the multinational tier, GlaxoSmithKline and Novartis exemplify divergent strategic positions—GlaxoSmithKline leveraging established anti-infectives manufacturing for preferential WHO pricing agreements, while Novartis occupies a technology leadership position in R&D-stage mycolactone-targeting compounds. Cipla anchors the generic production archetype, competing on cost in African tender markets for clarithromycin formulations. These three companies collectively represent the spectrum from volume-driven antibiotic supply to innovation-focused pipeline development.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| Teva Pharmaceutical Industries |
| GlaxoSmithKline |
| Bayer |
| AbbVie |
| Pfizer |
| Cipla |
| Lupin Laboratories |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification tiering separates premium-grade rifampicin-clarithromycin suppliers from commodity generic entrants, concentrating pricing power with manufacturers holding validated cold chain capabilities into West Africa while marginalizing unqualified producers to spot-market distress sales. This certification ladder shapes procurement patterns across Ghana's Food and Drugs Authority tenders and Côte d'Ivoire's national pharmaceutical regulator contracts, where quality-assured products command sustainable margins against price-pressured alternatives.
Pricing Analysis
Distributor margins for Buruli ulcer antibiotics compress as Ghana's pooled procurement mechanisms displace fragmented national tenders, with volume aggregation shifting margin capture upstream to manufacturers holding WHO prequalification. Three-tier pricing structure across prequalified, nationally registered, and unregistered suppliers reflects certification grade and cold chain reliability rather than active pharmaceutical ingredient quality alone. Pricing pressure stems from Indian generic producers expanding clarithromycin capacity into African markets. District health facilities exhibit highest price sensitivity, while teaching hospitals prioritize graft success rates over per-unit antibiotic cost.
Supply Chain Analysis
Air freight costs for temperature-sensitive rifampicin formulations consume disproportionate share of landed cost in Benin's Ouémé department, where road infrastructure gaps force reliance on Abidjan-Cotonou air corridors. Active pharmaceutical ingredient production clusters in India and China, with secondary formulation capacity in South Africa. Clarithromycin supply rests on macrolide fermentation capacity concentrated in Gujarat and Zhejiang provinces. Single-source vulnerability manifests in South Asian export restriction exposure. Distribution runs through WHO's Global Drug Facility coordinating pooled orders from Ghana, Benin, and Côte d'Ivoire.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in wound care device tiers, where negative-pressure therapy adoption in Ghana's teaching hospitals creates premium pricing headroom against commoditized antibiotic supply. Cost compression in standard-of-care regimens frees procurement budget for advanced surgical adjuncts.
For Market Incumbents: Anticipate clarithromycin supply disruption from Indian export policy shifts by diversifying active pharmaceutical ingredient sourcing to South African and Nigerian secondary manufacturers. Anchor defensive positioning through exclusive distributor arrangements with Côte d'Ivoire's central pharmacy and Ghana's Korle Bu Teaching Hospital surgical units, locking out generic entrants from referral hospital procurement channels. Prioritize WHO prequalification maintenance investment over volume expansion into unqualified tenders. For New Entrants and Emerging Players: Community health worker networks in Benin's cocoa-growing regions offer lowest competitive density for adherence monitoring technology and point-of-care diagnostic platforms. Target district health facilities lacking PCR confirmation capacity with loop-mediated isothermal amplification field validation partnerships. Pursue go-to-market positioning through integration into existing onchocerciasis mass drug administration infrastructure rather than standalone Buruli ulcer vertical programs. For Investors and Strategic Acquirers: Consolidation pressure builds where mycolactone-targeting R&D pipelines face EMA orphan drug funding gaps and preclinical toxicology cost barriers. Long-term viability favors developers with pediatric investigation plan exemptions and established African field trial relationships. Acquisition target archetype: European biopharmaceutical firms with Phase I host-directed therapy candidates and existing WHO partnership frameworks. Signal to watch: EMA protocol assistance award announcements for neglected tropical disease indications.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Orphan Drug Pathway Advancement | Protocol assistance unlocks fee waivers for mycolactone inhibitor developers targeting shortened treatment durations. |
| WHO Prequalification Maintenance | Continuous quality certification preserves tender eligibility in Ghana's Food and Drugs Authority procurement cycles. |
| Point-of-Care Diagnostic Field Validation | Loop-mediated isothermal amplification deployment in Comoé district decentralizes confirmation from centralized laboratories. |
| Negative-Pressure Wound Therapy Integration | Device adoption in Treicheville University Hospital reduces graft failure rates for extensive lesion cases. |
| Community Health Worker Network Expansion | Village health team training in Atlantique department extends screening reach beyond clinic-accessible populations. |
Study Parameters
Coverage spans West African endemic countries, European R&D hubs, and South Asian manufacturing centers, with primary inputs from each region informing demand and supply assessments. Drug development executives at antibiotic manufacturers, regulatory affairs leads at Ghana's Food and Drugs Authority, formulary directors at Côte d'Ivoire's national health insurance, and hospital procurement managers at Korle Bu Teaching Hospital provided structured interviews. Secondary validation drew from WHO prequalification listings, EMA orphan drug designations, FDA antibacterial guidance documents, and ClinicalTrials.gov mycolactone inhibitor entries. Bottom-up patient volume estimates from Ghana Health Service surveillance data triangulated against top-down antibiotic procurement records from WHO's Global Drug Facility.
Granularity-level modeling disaggregated volume and value across product type, end user, delivery mode, and application dimensions, with regional regulatory cluster and WHO prequalification status as cross-cutting stratifiers. CAGRs derived from trend extrapolation of historical procurement volumes adjusted for projected mass drug administration platform expansion. Forecast inputs incorporated clarithromycin supply chain resilience indices and mycolactone pathway research advancement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antimicrobial resistance surveillance capacity buildout and EMA pediatric investigation plan enforcement. Forecasts reflect documented assumptions regarding WHO integration policy continuity and South Asian export regulation stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Idiopathic Short Stature Market