
 China Radiotherapy Market | 2026-2036
China Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
China Radiotherapy Market Insights
Public hospital procurement dominance is collapsing as private oncology chains and specialty clinics gain purchasing authority. Varian Medical Systems leverages its installed base of linear accelerators to sustain service revenue streams across provincial capitals. Elekta anchors proton therapy development through research institution partnerships in eastern China. Siemens Healthineers competes on integrated imaging-radiotherapy workflows that reduce treatment planning cycles.
Radiotherapy encompasses the clinical use of ionizing radiation—delivered via photon, electron, or proton beams with energies typically ranging from 4 to 25 MV—to destroy malignant cells while sparing surrounding healthy tissue through precise beam modulation and image guidance. Its primary purpose is curative and palliative cancer treatment delivered in fractionated dose schedules over multiple sessions. Linear accelerators occupy the dominant hardware position due to their versatility across treatment modalities, while proton therapy represents the fastest-growing technology segment despite capital intensity driven by superior dose conformity for pediatric and skull-base indications. Brachytherapy maintains stable demand in cervical and prostate applications where intracavitary or interstitial source placement offers organ-sparing advantages.
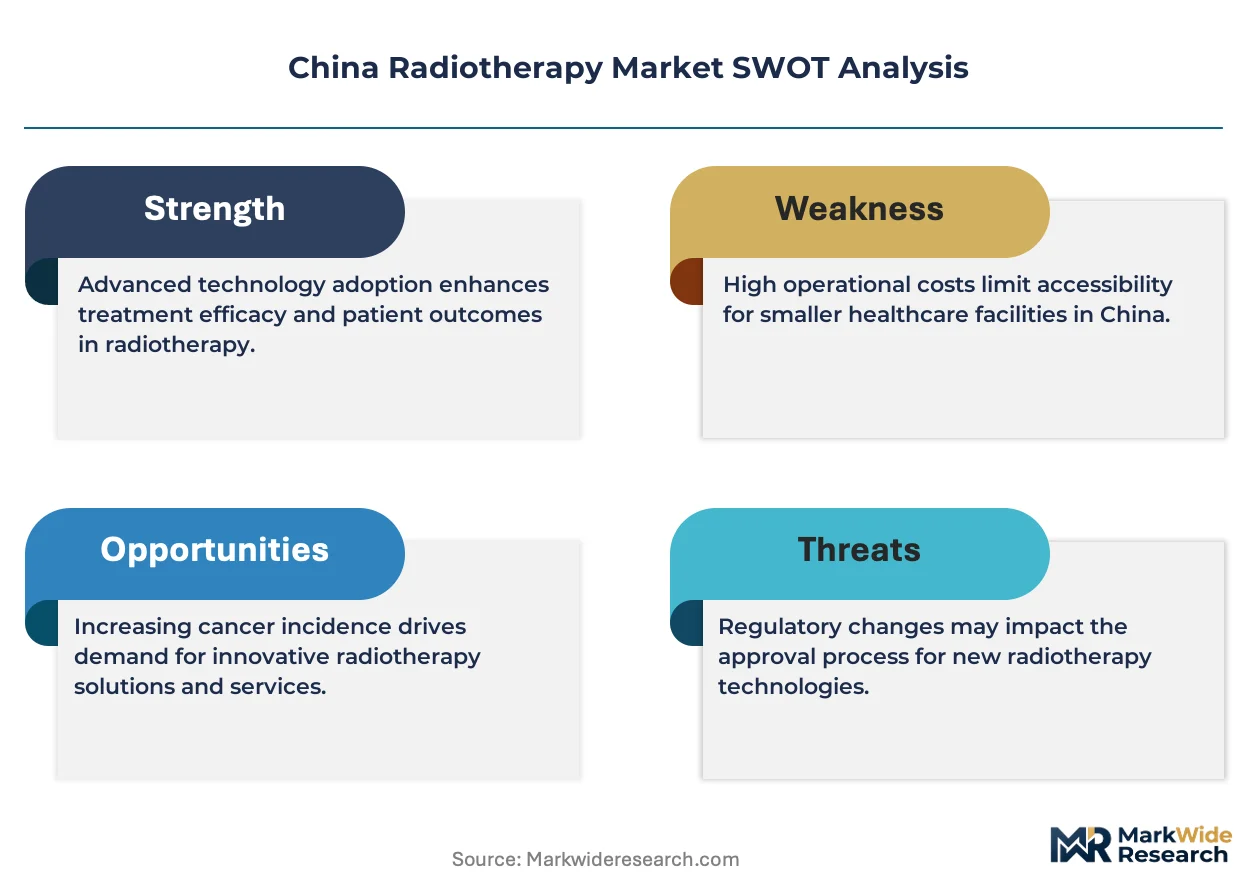
NMPA device registration requirements and GB standards for medical electrical safety shape product entry timelines and localization obligations for imported radiotherapy systems. The National Healthcare Security Administration's reimbursement catalog revisions directly influence hospital procurement priorities and technology upgrade cycles. Stakeholders must monitor NMPA's evolving clinical trial requirements for AI-enabled treatment planning software as algorithmic dose optimization becomes embedded in next-generation radiotherapy platforms.
Market Dynamics
China's radiotherapy sector is restructuring around the NMPA's accelerated novel device approval pathway, which compresses registration timelines for AI-integrated treatment planning systems and proton therapy platforms while forcing domestic localization commitments upon foreign equipment suppliers.
Growth Catalysts
- Reimbursement catalog expansion:The National Healthcare Security Administration's periodic revisions to radiotherapy procedure codes are unlocking hospital budget allocations for advanced modalities including stereotactic body radiotherapy and adaptive planning workflows.
- Proton therapy infrastructure buildout:Eastern China's research hospital clusters are commissioning particle therapy centers with government-backed capital subsidies, creating anchor demand for heavy-ion and proton beam systems.
- AI-enabled dose optimization:Algorithmic treatment planning software embedded in next-generation linear accelerators is reducing planning cycles from hours to minutes, accelerating patient throughput in congested oncology departments.
Market Restraints
- Capital intensity barriers:Proton therapy installations require RMB 300-500 million in dedicated facility construction, shielding, and cyclotron equipment, restricting deployment to top-tier medical centers with direct ministry funding.
- Localization mandates:NMPA device registration rules impose domestic manufacturing or joint venture requirements on imported radiotherapy systems, extending product entry timelines for foreign suppliers without established China-based production.
- Specialized workforce scarcity:Medical physicist and radiation oncologist training programs produce insufficient graduates to staff expanding provincial radiotherapy centers, creating operational bottlenecks in tier-two and tier-three cities.
Strategic Opportunities
- Private oncology chain penetration:Specialty clinic networks in Chengdu, Wuhan, and Xi'an are gaining independent procurement authority, creating alternative sales channels beyond saturated Beijing-Shanghai-Guangzhou hospital clusters.
- Integrated imaging-radiotherapy convergence:MRI-guided linear accelerators combining real-time soft-tissue visualization with beam delivery are opening organ-motion management applications previously excluded from radiotherapy protocols.
- Brachytherapy service unbundling:After-sales source handling, applicator sterilization, and treatment planning are separating from hardware sales into recurring revenue streams for equipment vendors with trained field service teams.
Industry Challenges
- Legacy LINAC upgrade complexity:Provincial hospitals with decade-old linear accelerator installations face difficult integration paths for AI planning modules and image-guidance retrofits without full system replacement.
- GB standards compliance friction:Medical electrical safety testing and electromagnetic compatibility certification for software-heavy radiotherapy platforms create unpredictable NMPA submission timelines that disrupt product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Radiotherapy Market |
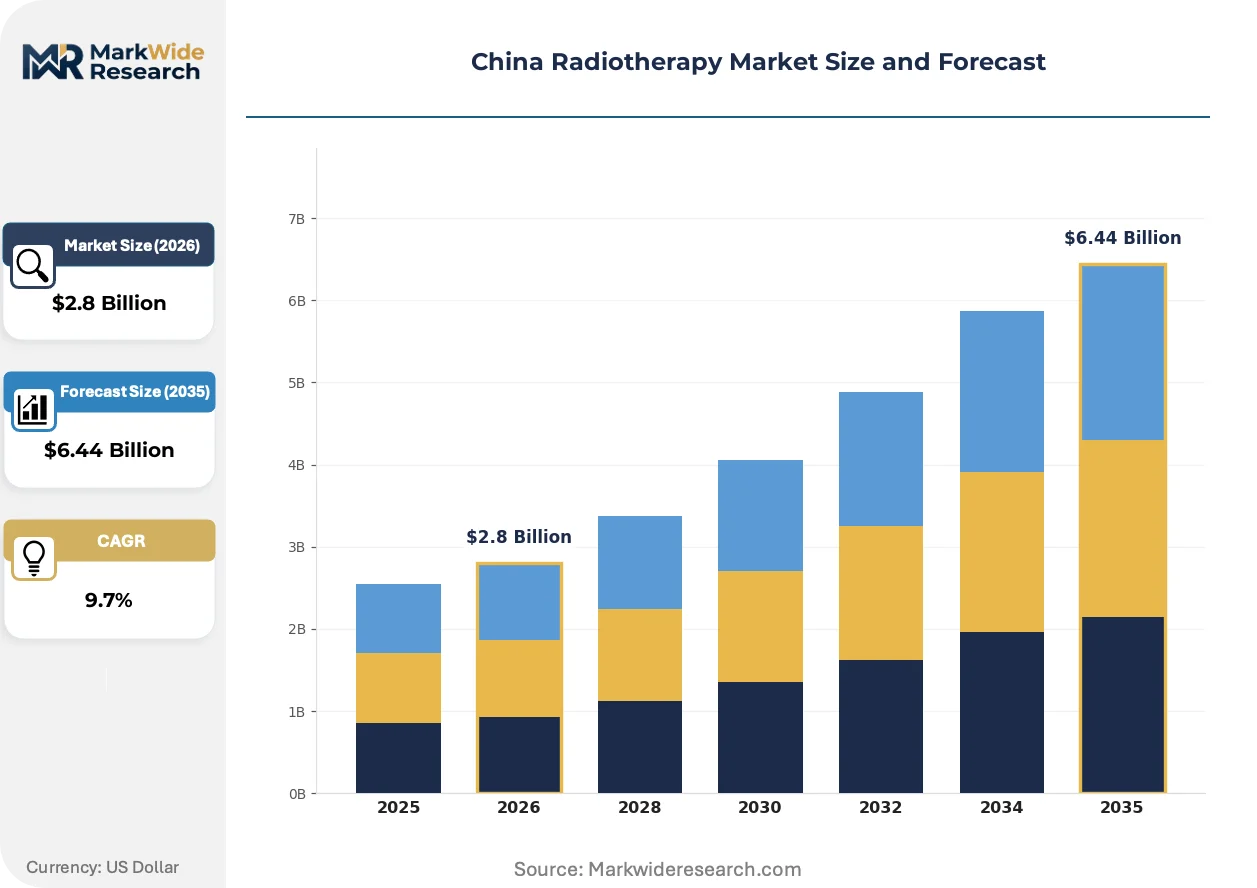
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Radiation Therapy Systems, Radiosurgery Systems End User: Hospitals, Oncology Centers, Research Institutions, Specialty Clinics Technology: 3D Conformal Radiation Therapy, Intensity-Modulated Radiation Therapy, Stereotactic Radiosurgery, Proton Therapy Application: Cancer Treatment, Palliative Care, Pediatric Therapy, Neurosurgical Procedures |
| Companies Covered | Accuray, ViewRay, Varian Medical Systems, Nordion, Curium Pharma, Elekta, IBA RadioPharma Solutions, MeVis Medical Solutions, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Radiotherapy Market Trends and Innovations
Hardware-software convergence is compressing treatment delivery windows while regulatory pressure on AI clinical validation is reshaping vendor R&D priorities across China's radiotherapy value chain.
Compact single-room proton therapy systems are miniaturizing footprint requirements from football-field-scale facilities to conventional radiotherapy vault dimensions. Community oncology centers in Hangzhou and Nanjing are evaluating these downsized platforms for pediatric and head-neck specialty programs. This format reduction is miniaturizing the addressable market for proton therapy from national flagship centers to regional hospital networks.
NMPA's evolving clinical trial requirements for AI-enabled treatment planning software are mandating prospective validation studies against physician-approved plans before algorithmic dose optimization receives device registration. This regulatory stringency is extending development timelines for domestic startups and forcing foreign vendors to establish China-specific training datasets. The AI-software segment bears the heaviest compliance burden, with submissions now requiring real-world performance tracking post-approval.
Hospital procurement committees are fragmenting purchasing authority between radiotherapy departments and centralized medical equipment bureaus, complicating vendor sales cycles. Equipment suppliers now navigate dual stakeholder sets: clinical champions advocating for technical specifications and administrative gatekeepers enforcing budget discipline and localization quotas. This bifurcation is most pronounced in Jiangsu and Zhejiang province health systems undergoing public hospital reform pilots.
China Radiotherapy Market Segmentation
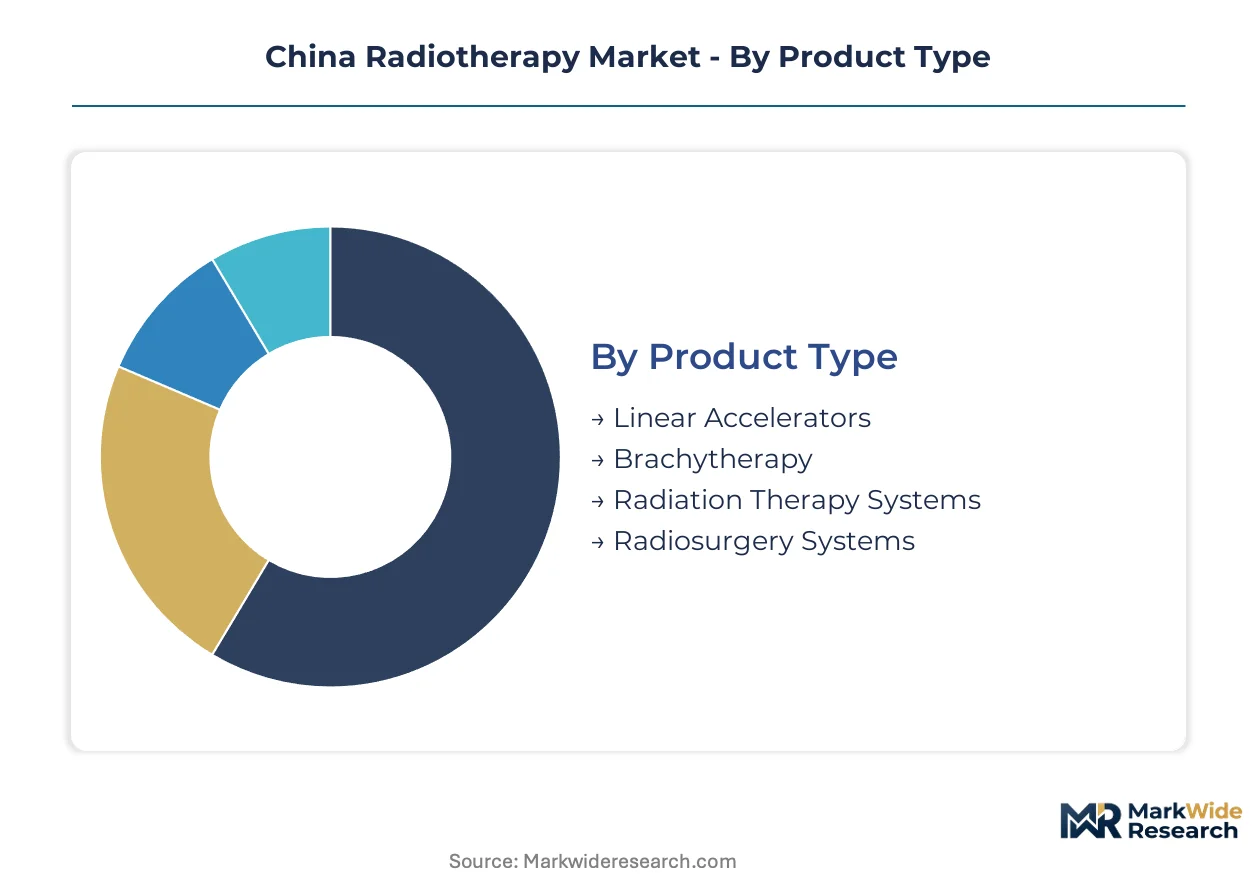
Segmentation in China's radiotherapy market reveals distinct procurement patterns across product categories, with channel dynamics shifting as private oncology chains gain purchasing autonomy. Understanding these segment boundaries clarifies where NMPA regulatory pressure concentrates and where localization mandates reshape competitive entry.
Product Type:
Channel distribution varies sharply by product complexity, with high-value systems flowing through centralized provincial procurement platforms while specialized modalities reach end-users via direct manufacturer relationships.
- Linear Accelerators:Photon and electron beam systems operating at 4-25 MV dominate hardware installations across tier-one hospital clusters in Beijing, Shanghai, and Guangzhou. Provincial procurement bureaus in Jiangsu and Zhejiang are consolidating LINAC purchases into multi-year framework agreements, compressing vendor margins while locking in service revenue streams.
- Brachytherapy:Intracavitary and interstitial radioactive source delivery systems maintain stable demand through cervical and prostate specialty programs. Oncology centers in Chengdu and Wuhan are unbundling after-sales source handling from hardware sales, creating recurring revenue opportunities for vendors with trained field service teams.
- Radiation Therapy Systems:Integrated treatment planning and delivery platforms with embedded AI dose optimization modules.
- Radiosurgery Systems:Stereotactic platforms for cranial and extracranial precision ablation procedures.
By volume, Linear Accelerators lead. By growth pace, Radiation Therapy Systems with embedded AI modules are climbing the fastest.
End User:
Customer-type concentration determines pricing leverage, with public hospital networks extracting volume discounts while private chains prioritize technology differentiation over procurement cost.
- Hospitals:Tertiary public institutions with radiation oncology departments accredited by the National Health Commission. Beijing's Peking Union Medical College Hospital and Shanghai's Fudan University Cancer Center anchor demand for proton therapy platforms, though capital intensity restricts these acquisitions to ministry-funded flagship sites.
- Oncology Centers:Dedicated cancer treatment facilities with consolidated radiotherapy and medical oncology services. Specialty chains in Xi'an and Hangzhou are gaining independent procurement authority outside traditional hospital procurement committees, opening alternative sales channels for mid-tier LINAC suppliers.
- Research Institutions:University-affiliated hospitals and national laboratories conducting clinical trials for novel radiation modalities.
- Specialty Clinics:Focused practices in pediatric radiation or neuro-oncology with narrow indication scopes.
By patient throughput, Hospitals dominate. By technology upgrade frequency, Oncology Centers are gaining share fastest.
Technology:
Technology maturity curves shape margin profiles, with established modalities facing price compression while emerging platforms command premium positioning pending NMPA registration completion.
- 3D Conformal Radiation Therapy:Geometric beam shaping using multileaf collimators to approximate tumor contours. Legacy installations in tier-two provincial hospitals face difficult upgrade paths for adaptive planning integration without full system replacement.
- Intensity-Modulated Radiation Therapy:Inverse-planned dose modulation with dynamic leaf motion. IMRT-equipped LINACs constitute the installed base majority across Guangdong and Shandong provinces, though reimbursement catalog revisions are accelerating replacement cycles toward more advanced modalities.
- Stereotactic Radiosurgery:High-dose fractionated or single-session ablation with sub-millimeter targeting precision.
- Proton Therapy:Particle beam delivery with superior dose conformity for pediatric and skull-base indications.
By installed base, Intensity-Modulated Radiation Therapy leads. By capital commitment growth, Proton Therapy shows the steepest expansion trajectory.
Application:
Indication-specific demand patterns reveal where clinical evidence requirements from NMPA create regulatory moats versus where standardized protocols enable rapid deployment.
- Cancer Treatment:Curative-intent radiotherapy for solid tumors across lung, breast, prostate, and colorectal indications. NMPA's evolving clinical trial requirements for AI-enabled planning software are mandating prospective validation against physician-approved plans before algorithmic dose optimization receives device registration.
- Palliative Care:Symptom-directed radiation for pain, obstruction, or bleeding control in advanced disease. Community oncology networks in Nanjing and Suzhou are expanding palliative radiotherapy capacity as hospice-integrated care models gain policy support under regional health reform pilots.
- Pediatric Therapy:Organ-sparing protocols requiring superior dose conformity to limit developmental toxicity.
- Neurosurgical Procedures:Stereotactic radiosurgery for arteriovenous malformations and functional disorders.
By procedure volume, Cancer Treatment leads. By reimbursement rate expansion, Palliative Care is advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in eastern coastal provinces where NMPA registration expertise and hospital procurement networks overlap. Provincial health reform pilots are redistributing radiotherapy capacity from saturated megacities to emerging regional hubs.
Beijing-Tianjin-Hebei
Peking Union Medical College Hospital and Cancer Hospital Chinese Academy of Medical Sciences anchor proton therapy demand through ministry-funded capital budgets. NMPA's accelerated approval pathway for AI-integrated treatment planning systems prioritizes submissions from institutions within this cluster. Beijing's Haidian District hosts concentrated medical device registration consultancies serving foreign equipment suppliers navigating GB standards compliance.
Yangtze River Delta
Fudan University Cancer Center and Shanghai Proton and Heavy Ion Center drive particle therapy infrastructure investment with municipal government backing. The National Healthcare Security Administration's Shanghai office pilots reimbursement catalog expansions for stereotactic body radiotherapy procedures. Hangzhou's Binjiang District attracts compact proton therapy system evaluations from community oncology networks seeking pediatric specialty capacity.
Pearl River Delta
Sun Yat-sen University Cancer Center maintains Guangdong Province's highest linear accelerator density through centralized provincial procurement frameworks. MIIT medical device manufacturing incentives support domestic LINAC component production in Shenzhen's Pingshan District. Dongguan specialty clinics are gaining independent procurement authority outside traditional hospital committees.
Sichuan-Chongqing
West China Hospital of Sichuan University anchors western China's radiotherapy training capacity for medical physicists and radiation oncologists. NMPA's clinical trial requirements for AI-enabled planning software mandate prospective validation studies at tier-one institutions before algorithmic registration. Chengdu's private oncology chains are establishing independent LINAC procurement channels distinct from public hospital networks.
Shandong Peninsula
Shandong Cancer Hospital and Institute drives IMRT-equipped LINAC replacement cycles through provincial reimbursement catalog revisions. GB standards for medical electrical safety testing create compliance friction for software-heavy radiotherapy platforms seeking NMPA device registration. Jinan's medical equipment distribution networks serve tier-two city hospitals upgrading decade-old linear accelerator installations.
China Radiotherapy Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized radiation therapy equipment manufacturers. The vendor base separates into three strategic tiers: integrated imaging-radiotherapy workflow providers, proton therapy platform specialists, and linear accelerator service revenue optimizers. M&A activity targets AI-enabled treatment planning software capabilities while strategic partnerships anchor proton therapy research institution collaborations.
Among diversified health technology groups, Siemens Healthineers and Varian Medical Systems occupy positions exemplifying integrated imaging-radiotherapy convergence. Elekta represents the proton therapy development archetype through research institution anchoring in eastern China. These three entities illustrate competitive positioning around NMPA registration timelines, service revenue capture, and AI-software integration pathways.
| Leading Market Players |
|---|
| Accuray |
| ViewRay |
| Varian Medical Systems |
| Nordion |
| Curium Pharma |
| Elekta |
| IBA RadioPharma Solutions |
| MeVis Medical Solutions |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
NMPA device registration requirements gate both supply qualification and price differentiation simultaneously for radiotherapy systems entering China, compressing margins for foreign vendors without established domestic production while enabling premium positioning for AI-integrated platforms that clear accelerated approval pathways.
Pricing Analysis
NMPA's localization mandates dictate the pricing tier structure across China's radiotherapy market. Premium-mid-economy pricing differentiation separates AI-enabled treatment planning systems from legacy LINAC configurations, with certification grade and after-sales service bundling as primary price drivers. Cost compression in standard linear accelerator tiers is intensifying because provincial procurement bureaus consolidate multi-year framework agreements. Public hospital networks exhibit highest price sensitivity, while private oncology chains prioritize technology differentiation over procurement cost.
Supply Chain Analysis
Shanghai Port customs clearance chokepoints underwrite extended lead times for imported linear accelerator components and proton therapy cyclotron systems. Manufacturing concentration centers on Germany, Sweden, and the United States for precision accelerator hardware, while China-based joint ventures feed domestic assembly requirements. Supply chains draw from specialized magnet suppliers, radiation shielding fabricators, and software development centers. Single-source vulnerability persists for superconducting magnet components. Distribution runs through provincial medical equipment bureaus and direct manufacturer relationships with flagship cancer centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's radiotherapy sector is approaching a platform-economics inflection where AI-enabled treatment planning software interoperability determines hardware purchasing decisions, shifting vendor competition from device specifications to ecosystem integration depth.
For Market Incumbents: Secure service revenue streams across provincial capitals by embedding AI planning modules into existing LINAC installed bases before domestic startups complete NMPA clinical validation studies. Deepen backward integration into domestic software development centers to satisfy localization quotas without surrendering core intellectual property. Counter emerging entrant pressure from compact proton therapy specialists by accelerating MRI-LINAC convergence timelines.
For New Entrants and Emerging Players: Differentiate on pediatric and neuro-oncology specialization where proton therapy dose conformity commands clinical premium and reimbursement expansion. Target private oncology chains in Chengdu, Wuhan, and Xi'an where procurement authority fragmentation creates white-space access outside saturated Beijing-Shanghai-Guangzhou clusters. Pursue research institution partnerships as anchor reference sites before scaling to community hospital networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact single-room proton therapy systems, compressing facility construction requirements from ministry-funded flagship scale to regional hospital network accessibility. Long-term viability favors vendors with software-hardware integration capabilities rather than pure hardware manufacturers. Monitor NMPA's evolving AI clinical trial requirements as the signal for when algorithmic dose optimization platforms achieve registration velocity enabling portfolio-scale deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Accelerated Approval Pathway Navigation | Compresses registration timelines for AI-integrated treatment planning systems from foreign and domestic vendors. |
| Domestic Joint Venture Establishment | Satisfies localization mandates for imported linear accelerator systems while preserving service revenue capture. |
| Research Institution Partnership Anchoring | Creates clinical validation pathways for proton therapy platforms at Fudan University Cancer Center and comparable sites. |
| AI Software Companion Development | Enables algorithmic dose optimization modules that reduce treatment planning cycles from hours to minutes. |
| Provincial Procurement Bureau Engagement | Secures multi-year framework agreements within Jiangsu and Zhejiang health system reform pilots. |
Research Methodology
Desk research of NMPA device registration databases, hospital procurement records, and GB standards documentation preceded structured interviews with radiation oncology department heads, medical physicists, hospital purchasing committee members, and biomedical engineers. Secondary validation drew from provincial health commission reports, medical equipment distribution records, and research institution clinical trial disclosures. Bottom-up installation data triangulated against top-down market sizing from reimbursement catalog analysis.
Variance decomposition across product type, end user category, technology modality, and application indication shaped the analytical framework throughout the projection horizon. CAGRs derived from segmented demand modeling incorporating NMPA approval velocity, reimbursement expansion trajectories, and provincial hospital capital budget cycles. Forecast inputs included linear accelerator replacement rates, proton therapy infrastructure buildout pipelines, and AI software adoption curves across tier-one and tier-two hospital clusters.
The analysis sits within stated boundaries; outcomes outside NMPA regulatory timelines, reimbursement catalog revision schedules, or provincial procurement reform trajectories would require recalibration. Forecasts reflect assumptions regarding medical physicist training program expansion and domestic manufacturing joint venture completion. Practitioners should keep alternative scenarios live as NMPA clinical trial requirements for AI-enabled systems evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
ECG Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Cell Washer Market
Medical Equipment
Hospital Stretchers Market