
 Liposarcoma Treatment Market | 2026-2036
Liposarcoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Liposarcoma Treatment Market Outlook
Multi-source clinical supply networks for investigational liposarcoma agents is repositioning how Phase II and III trials secure comparator drugs and radiolabeled compounds. Pfizer Inc. leverages its established oncology manufacturing footprint to maintain consistent supply of doxorubicin formulations across North American and European trial sites. Eli Lilly and Company anchors its sarcoma portfolio through targeted therapy pipelines directed at MDM2-amplified dedifferentiated subtypes. Novartis AG competes on radioligand therapy infrastructure, extending its nuclear medicine platform into rare solid tumor indications.
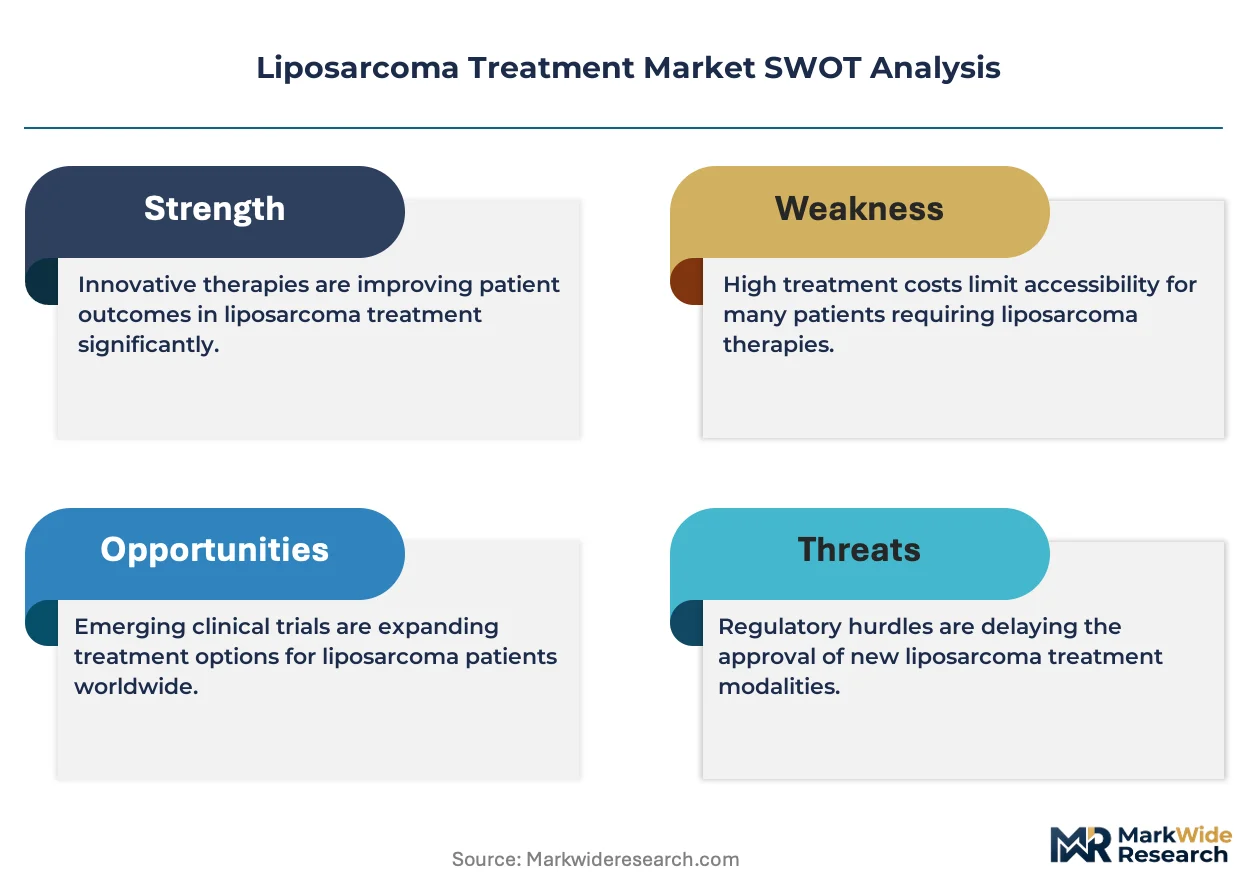
Liposarcoma treatment encompasses multimodal management of malignant adipocytic neoplasms spanning well-differentiated, dedifferentiated, myxoid, and pleomorphic histologic subtypes, with therapeutic selection hinging on anatomic site, grade, and genomic alterations such as FUS-DDIT3 translocations or MDM2 amplification. The primary purpose centers on achieving complete local control while addressing systemic micrometastatic disease in retroperitoneal and extremity presentations. Surgery and radiation therapy retain dominant positions in localized disease, though margin-negative resection rates in retroperitoneal cases remain structurally constrained by anatomic complexity. Targeted therapy represents the fastest-expanding segment, with pazopanib and emerging MDM2 inhibitors capturing concentrated margin pools in relapsed or metastatic settings where chemotherapy response durations are limited.
FDA orphan drug designations and EMA priority medicine pathways accelerate liposarcoma therapy development, compressing regulatory review timelines and mandating pediatric investigation plans for relevant molecular targets. The EPA governs radiopharmaceutical manufacturing emissions, while ISO 13485 standards constrain quality systems for companion diagnostic devices used in patient stratification. Stakeholders must monitor how CD19 and GD2-targeted platform migrations from hematology into solid tumors reshape competitive resource allocation across sarcoma programs.
Market Dynamics
FDA orphan drug incentives and EMA priority medicine designations are compressing clinical trial timelines while reshaping how sarcoma-specific protocols secure comparator drugs and radiolabeled compounds across academic medical centers.
Growth Catalysts
- Orphan Drug Designation:FDA incentives compress regulatory review timelines and mandate pediatric investigation plans for MDM2-amplified targets. Academic medical centers in the United States leverage these pathways to accelerate Phase II enrollment.
- Radioligand Infrastructure:Nuclear medicine platform extensions into rare solid tumors enable companion diagnostic stratification. ISO 13485 standards constrain quality systems while expanding patient eligibility for targeted radiopharmaceutical trials.
- Retroperitoneal Referral Networks:Specialized sarcoma centers in Germany and Japan concentrate surgical expertise for margin-negative resection. These networks funnel complex cases away from general oncology practices.
Market Restraints
- Comparator Drug Scarcity:Doxorubicin supply volatility constrains Phase III trial design. Pfizer's manufacturing footprint dominates North American and European comparator sourcing.
- Anatomic Complexity:Retroperitoneal site presentations structurally limit margin-negative resection rates regardless of surgical technique. Vascular involvement precludes complete local control in a substantial subset.
- EPA Radiopharmaceutical Emissions:Manufacturing facility compliance costs restrict radiolabeled compound production to a limited supplier base. Site licensing timelines extend 18-24 months.
Strategic Opportunities
- MDM2 Inhibitor Pipeline:Dedifferentiated subtype targeting represents unmet need in relapsed settings. Eli Lilly anchors development through amplified-specific therapeutic candidates.
- GD2 Platform Migration:Hematology-derived cell therapy infrastructure transfers into solid tumor sarcoma programs. CAR-T manufacturing partnerships with academic centers reduce capital requirements.
- Pediatric Investigation Mandates:EMA priority medicine pathways require early-age enrollment for relevant molecular targets. This creates trial design differentiation against adult-only competitors.
Industry Challenges
- Sarcoma-Specific Pathology Talent:Diagnostic expertise concentration at referral centers creates bottlenecks for community hospital specimen review. FUS-DDIT3 translocation identification requires specialized molecular testing.
- Radiopharmaceutical Cold Chain:Short half-life isotopes demand same-day manufacturing-to-administration logistics. Distribution infrastructure gaps outside major metropolitan clusters limit site activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposarcoma Treatment Market |
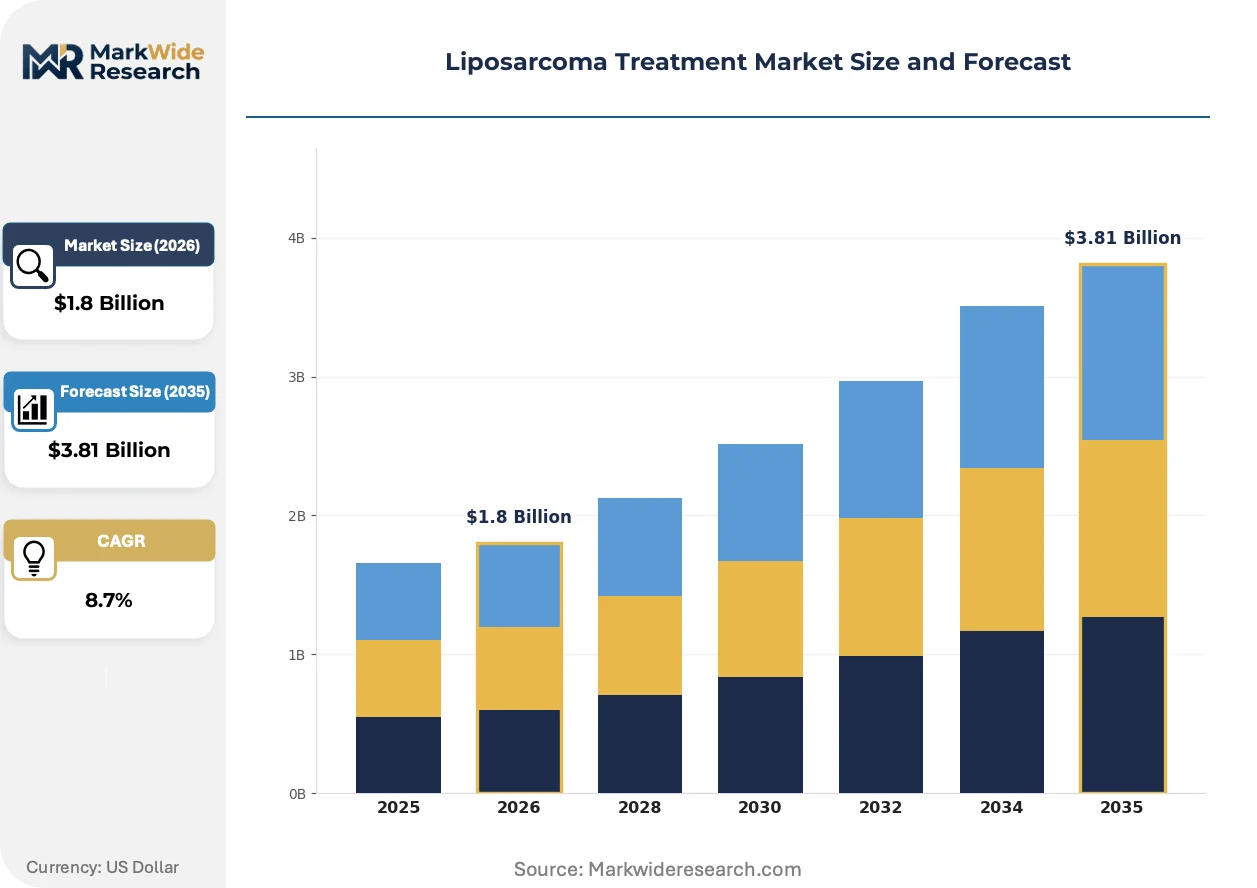
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy Drug Type: Doxorubicin, Ifosfamide, Gemcitabine, Pazopanib Care Setting: Hospital, Outpatient Clinic, Specialty Cancer Center, Home Care Patient Demographics: Adult, Elderly, Pediatric, Male |
| Companies Covered | Pfizer Inc., Intensity Therapeutics, Johnson & Johnson Services, Inc., Sotio, Ascentage Pharma, Eli Lilly and Company, Sanofi SA, Adaptimmune, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposarcoma Treatment Market Strategic Shifts
Multimodal management protocols are converging genomic stratification with surgical planning algorithms, reshaping how well-differentiated and dedifferentiated subtypes route through academic versus community care settings.
Artificial intelligence pathology platforms are automating FUS-DDIT3 translocation detection and MDM2 amplification scoring in diagnostic workflows. Community hospitals lacking in-house molecular pathology capabilities adopt cloud-based algorithmic review to retain specimen processing locally. This technology is automating the referral triage function that previously required centralized academic review, compressing time-to-treatment decisions.
EMA's priority medicine scheme now mandates pediatric investigation plans for agents targeting molecular alterations present in both adult and childhood sarcomas. This regulatory compression forces earlier-age enrollment into Phase I/II trials, expanding addressable populations while complicating informed consent protocols. European academic centers are responding by embedding pediatric oncology units within adult sarcoma programs.
Site-of-care migration is redirecting stable-disease monitoring from infusion centers to home-based nursing networks. Third-party logistics providers now coordinate oral targeted therapy delivery directly to patients, disintermediating traditional specialty pharmacy channels. This pattern is most visible in United States metropolitan corridors where pazopanib maintenance protocols have matured.
Liposarcoma Treatment Market Segmentation
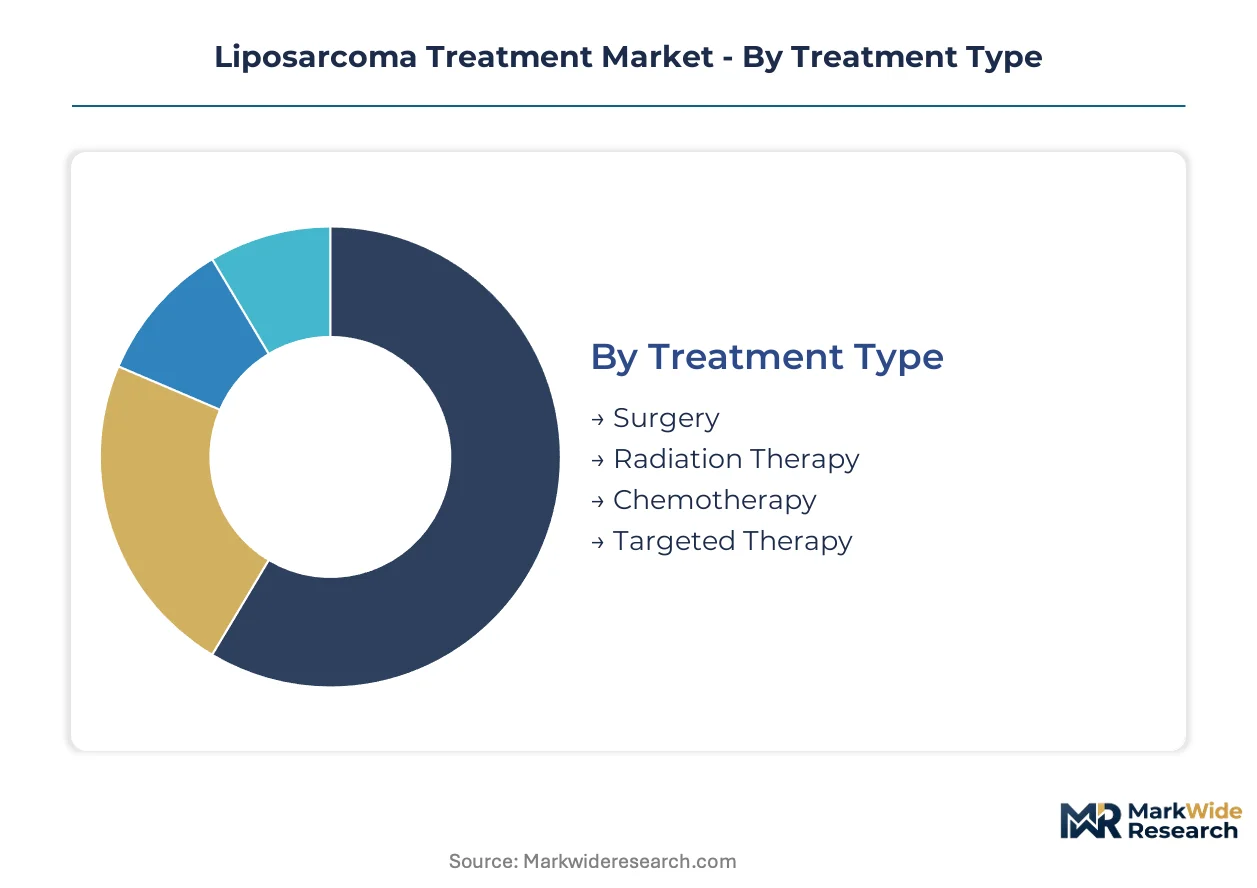
Liposarcoma management requires precise patient stratification across histologic subtypes and anatomic presentations. Treatment pathways diverge sharply between localized retroperitoneal disease requiring multimodal intervention and extremity presentations amenable to limb-sparing surgery.
Treatment Type:
Surgical resection functions as the standalone curative modality for localized presentations, while systemic approaches embed within multimodal protocols for advanced disease.
- Surgery:Margin-negative resection remains the definitive intervention for well-differentiated and myxoid subtypes confined to extremity compartments. Retroperitoneal presentations at specialized centers in Germany and Japan achieve complete local control when vascular involvement is absent. Anatomic complexity constrains resectability in approximately one-third of retroperitoneal cases regardless of surgical expertise.
- Targeted Therapy:MDM2 inhibitors and angiogenesis blockers address relapsed dedifferentiated subtypes where chemotherapy response durations prove limited. Academic medical centers in the United States concentrate Phase II enrollment for amplified-specific candidates. FDA orphan drug incentives compress development timelines for this fastest-expanding therapeutic category.
- Radiation Therapy:Preoperative and adjuvant protocols reduce local recurrence in extremity presentations. Proton beam facilities at select United States academic centers optimize dosing for anatomically constrained sites.
- Chemotherapy:Doxorubicin-based regimens retain utility in metastatic pleomorphic subtypes. Supply volatility constrains comparator drug availability for ongoing trials.
Surgery leads volumes today; targeted therapy is gaining share fastest.
Drug Type:
Agent selection tracks histologic subtype molecular profiles and line-of-therapy positioning, with cost tiers separating branded targeted agents from generic cytotoxics.
- Pazopanib:Multi-kinase inhibitor approved for advanced soft-tissue sarcoma maintenance following progression on anthracycline therapy. Oral administration enables home-based delivery through third-party logistics networks in United States metropolitan corridors. Site-of-care migration away from infusion centers accelerates patient convenience.
- Doxorubicin:Anthracycline backbone for first-line systemic treatment across pleomorphic and dedifferentiated subtypes. Pfizer's manufacturing footprint dominates North American and European clinical supply. EPA emissions compliance restricts radiolabeled analog production to limited supplier bases.
- Ifosfamide:Alkylating agent combined with doxorubicin in combination regimens for high-grade presentations. Hospital inpatient administration requirements concentrate utilization at academic medical centers.
- Gemcitabine:Nucleoside analog employed in salvage protocols and combination with docetaxel. Generic availability produces pricing compression favorable to outpatient clinic budgets.
Doxorubicin anchors first-line volumes; pazopanib demonstrates steepest expansion trajectory in maintenance settings.
Care Setting:
Patient acuity and treatment modality determine site selection, with high-complexity resections concentrating at referral networks and stable disease monitoring decentralizing to community access points.
- Specialty Cancer Center:Retroperitoneal sarcoma surgery and novel agent trials require concentrated pathology expertise and nuclear medicine infrastructure. FUS-DDIT3 translocation identification and MDM2 amplification scoring depend on specialized molecular testing capabilities. Germany's national sarcoma network and Japan's designated cancer hospitals centralize these functions.
- Hospital:Inpatient chemotherapy administration and complex resections with anticipated vascular reconstruction. Margin-negative outcomes in retroperitoneal disease correlate with annual case volume at these facilities.
- Outpatient Clinic:Routine surveillance imaging and oral targeted therapy monitoring. Community hospitals lacking in-house molecular pathology adopt cloud-based AI platforms to retain specimen processing locally.
- Home Care:Oral pazopanib maintenance and supportive care delivery. Third-party logistics coordination bypasses traditional specialty pharmacy channels in mature United States protocols.
Specialty cancer centers capture the highest-acuity cases; home care is expanding most quickly for stable-disease populations.
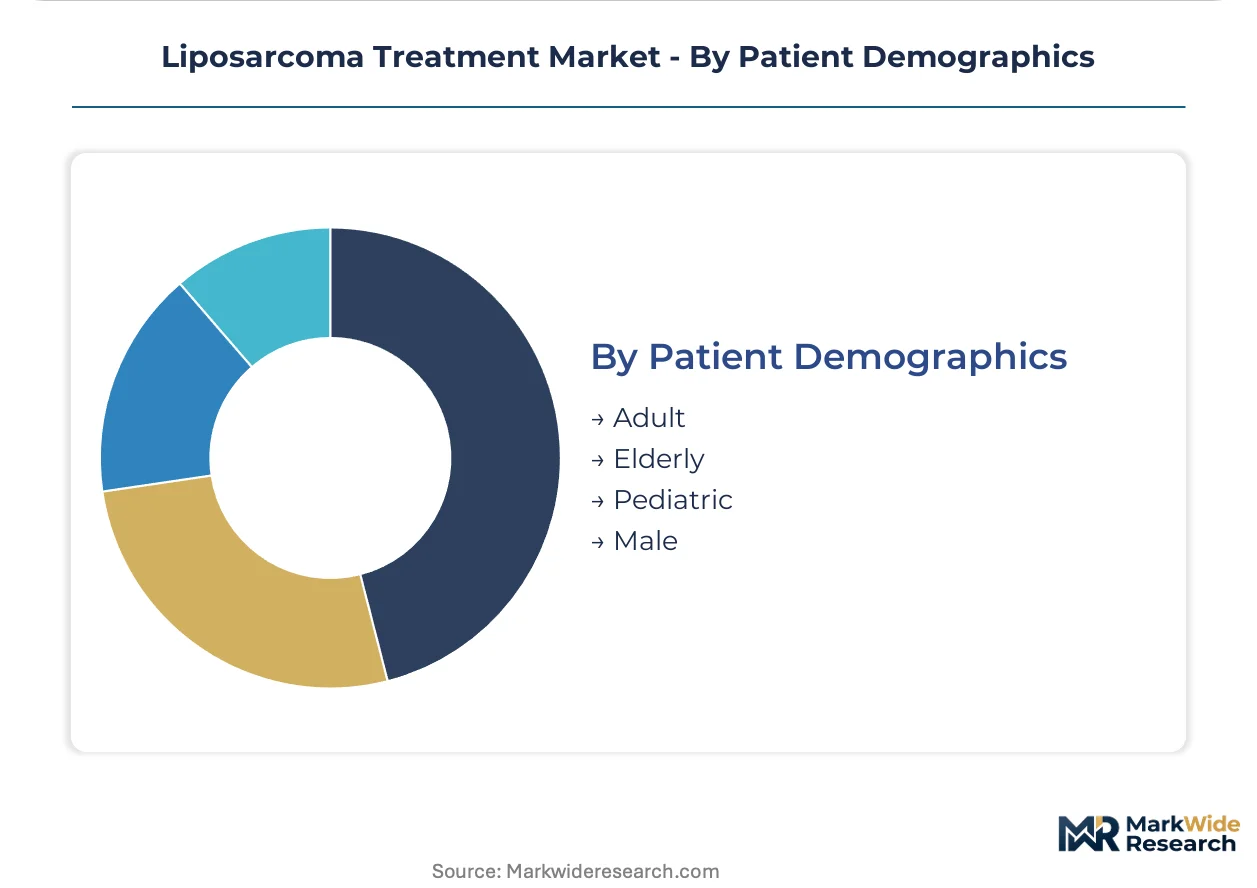
Patient Demographics:
Disease biology and regulatory mandates shape enrollment patterns across age and sex distributions, with pediatric investigation plans now compulsory for molecular targets present in childhood sarcomas.
- Adult:Peak incidence occurs in fifth and sixth decades across all histologic subtypes. Well-differentiated and dedifferentiated presentations predominate in this cohort. Clinical trial enrollment concentrates at academic medical centers with dedicated sarcoma programs.
- Elderly:Comorbidity burden influences surgical candidacy and chemotherapy tolerance. Radiation therapy and de-escalated systemic approaches feature prominently in this population. Outpatient clinic utilization exceeds hospital-based care for monitoring functions.
- Pediatric:Myxoid liposarcoma with FUS-DDIT3 translocation represents the primary presentation in this group. EMA priority medicine mandates require early-age enrollment for relevant molecular targets. European centers embed pediatric oncology units within adult sarcoma programs to comply.
- Male:Slight predomination in epidemiologic studies, particularly for retroperitoneal presentations. Sex-specific outcomes data inform surgical risk stratification algorithms.
Adult patients constitute the predominant treated population; pediatric segments are climbing the fastest due to regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate sarcoma-specific surgical expertise and novel agent trial enrollment. FDA orphan drug incentives and EMA priority medicine designations are compressing development timelines across North American and European sites. Nuclear medicine infrastructure in Japan and Germany enables radioligand therapy expansion into rare solid tumor indications.
United States
Retroperitoneal referral networks at MD Anderson and Memorial Sloan Kettering funnel complex cases from community oncology practices. FDA orphan drug designation mandates pediatric investigation plans for MDM2-amplified targets, accelerating Phase II enrollment timelines. Boston and New York metropolitan clusters host proton beam facilities optimizing dosing for anatomically constrained sites.
Germany
The national sarcoma network centralizes margin-negative resection expertise for well-differentiated and dedifferentiated subtypes. EMA priority medicine pathways require early-age enrollment for molecular targets present in childhood sarcomas, embedding pediatric units within adult programs. Heidelberg and Berlin academic centers coordinate FUS-DDIT3 translocation identification through specialized molecular testing.
Japan
Designated cancer hospitals concentrate pathology expertise for pleomorphic subtype diagnosis and treatment planning. PMDA streamlined review pathways align with EMA priority medicine schemes for rare malignancy indications. Tokyo and Osaka metropolitan areas maintain radiopharmaceutical manufacturing infrastructure despite EPA-equivalent emissions compliance costs.
United Kingdom
Royal Marsden and Christie Hospital anchor limb-sparing surgery protocols for extremity presentations. NHS England specialized commissioning routes sarcoma cases away from general hospitals toward designated centers. London and Manchester academic clusters integrate artificial intelligence pathology platforms for community hospital specimen triage.
France
ANSM regulates radiolabeled compound production for academic trial sites across the Paris-Saclay cluster. Sarcoma reference networks in Lyon and Toulouse coordinate MDM2 amplification scoring for dedifferentiated subtype stratification. EMA pediatric investigation mandates drive enrollment into Phase I/II trials at earlier ages than adult-only protocols.
Liposarcoma Treatment Market Competitive Environment
Global majors compete with regional champions across clinical supply networks and nuclear medicine infrastructure. The vendor base stratifies into three tiers: established oncology manufacturers with radioligand capabilities, mid-cap targeted therapy developers, and emerging cell therapy platforms migrating from hematology. Dominant competitive moves include strategic partnerships for radiopharmaceutical distribution and portfolio diversification into companion diagnostic devices.
Within the established oncology tier, Pfizer Inc. and Eli Lilly and Company anchor North American manufacturing and development footprints. Novartis AG occupies a position in radioligand therapy infrastructure, extending nuclear medicine platforms into rare solid tumor indications. These three exemplify how FDA orphan drug incentives and EMA priority medicine designations reshape resource allocation across sarcoma programs.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Intensity Therapeutics |
| Johnson & Johnson Services, Inc. |
| Sotio |
| Ascentage Pharma |
| Eli Lilly and Company |
| Sanofi SA |
| Adaptimmune |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Academic medical center procurement committees concentrate demand for liposarcoma therapies, anchoring contract-based pricing for doxorubicin formulations and targeted agents across North American and European trial networks. This buyer concentration enables volume-negotiated supply agreements while constraining margin flexibility for manufacturers serving fragmented community oncology settings.
Pricing Analysis
Input-cost pass-through from radiolabeled isotope production and EPA emissions compliance fees shapes pricing for nuclear medicine platforms, while generic doxorubicin availability compresses anthracycline-tier margins. Pricing stratifies across branded targeted therapy, standard cytotoxic, and economy generic tiers based on molecular specificity and administration setting. Cost compression in the cytotoxic segment intensifies as Pfizer's manufacturing dominance constrains comparator sourcing alternatives. Community hospitals exhibit highest price sensitivity due to formulary budget caps, whereas academic centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Reverse-logistics for short-half-life radiopharmaceuticals demands same-day manufacturing-to-administration workflows, constraining distribution to metropolitan clusters with nuclear medicine infrastructure. Active pharmaceutical ingredient production concentrates in the United States, Germany, and Switzerland for quality-assured oncology inputs. Doxorubicin supply draws from specialized fermentation capacity, while MDM2 inhibitor candidates source from contract manufacturing organizations with potent compound handling certifications. Single-source vulnerability pervades radiolabeled compound production due to EPA licensing bottlenecks. Distribution runs through specialty pharmacy and third-party logistics networks for oral targeted agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation functions as a regulatory compounder, compressing development timelines and mandating pediatric investigation plans that expand addressable populations for molecularly targeted agents.
For Market Incumbents: Lock in radioligand therapy infrastructure through nuclear medicine platform extensions, securing manufacturing site licenses before EPA emissions compliance costs escalate further. Deepen backward integration into companion diagnostic development to capture stratification value in MDM2-amplified subtypes. Eli Lilly's anchored position in dedifferentiated pipelines and Novartis's radiopharmaceutical footprint exemplify defensive consolidation against emerging cell therapy migration from hematology. For New Entrants and Emerging Players: EMA priority medicine pathways in Europe open a window for pediatric-enrollment differentiation, embedding early-age protocols within adult sarcoma programs at academic centers. Target home-based oral therapy delivery networks in United States metropolitan corridors where pazopanib maintenance has matured site-of-care migration. Partner with third-party logistics providers to bypass traditional specialty pharmacy channels and capture stable-disease monitoring volumes. For Investors and Strategic Acquirers: Large-cap oncology manufacturers with radioligand capabilities are the most active acquirer in this space, seeking pipeline diversification into rare solid tumor indications. Acquisition target archetypes include mid-cap MDM2 inhibitor developers and AI pathology platforms automating FUS-DDIT3 translocation detection. Monitor FDA pediatric investigation plan enforcement patterns as inflection indicator for regulatory-driven enrollment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II enrollment compression through orphan drug incentives accelerates MDM2-amplified candidate timelines at academic centers. |
| Regulatory Approval Pathway | EMA priority medicine schemes mandate pediatric investigation plans, expanding addressable populations for molecular targets. |
| Manufacturing Scale-Up | Radiopharmaceutical production expansion requires EPA emissions compliance investment and 18-24 month site licensing. |
| Pipeline Diversification | GD2-targeted cell therapy migration from hematology into sarcoma programs reshapes competitive resource allocation. |
| Strategic Partnership | Academic medical center alliances for companion diagnostic stratification secure patient access in retroperitoneal referral networks. |
Study Parameters
Multiple input streams — regulatory filing databases, clinical trial registries, and hospital procurement records — were reconciled with primary interviews across the analysis window. Conversations with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed pipeline prioritization and access dynamics. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Cross-referencing historical approval patterns against expert panel input anchored the forecast framework across the projection horizon. Segmentation dimensions modeled include treatment line, histologic subtype, administration route, and regional regulatory cluster. CAGRs were derived from patient incidence trajectories, therapy penetration curves, and pricing evolution assumptions. Forecast inputs incorporated orphan drug designation timelines, radiopharmaceutical manufacturing capacity expansion, and AI pathology adoption rates in community hospital settings.
Revisions become necessary when pediatric investigation mandate enforcement intensifies, radiolabeled isotope supply disruptions materialize, or AI pathology platforms displace centralized molecular testing. Forecasts reflect documented assumptions regarding regulatory pathway compression and referral network concentration. Practitioners should monitor EPA licensing timelines, EMA pediatric enrollment requirements, and GD2 platform clinical readouts for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Radiation Oncology Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Sterile Oncology Injectable Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Angiosarcomas Treatment Market
Oncology
Metastatic Melanoma Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Bone Metastasis Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Global Veterinary Oncology Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market