
 North America Proton Therapy Market | 2026-2036
North America Proton Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Proton Therapy Market Insights
Service contracts for cyclotron maintenance and beam-line calibration is consolidating as a recurring revenue layer that shifts vendor economics from one-time hardware sales to long-term partnerships. Varian Medical Systems leverages its installed base across major academic medical centers to secure multi-year service agreements. Mevion Medical Systems anchors its competitive stance through compact single-room system designs that reduce facility construction costs. IBA Worldwide differentiates by offering proton therapy systems with integrated spot scanning technology.
Proton therapy employs accelerated proton beams with Bragg peak energy deposition to target tumors with sub-millimeter precision while sparing adjacent healthy tissue. Beam delivery systems operate at energies between 70 and 250 MeV, requiring superconducting cyclotrons or synchrotrons housed in specialized vaults with multi-foot concrete shielding. Multi-room systems capture the largest capital expenditure share due to their throughput advantages for high-volume cancer centers, while spot scanning technology represents the fastest-growing beam delivery modality as clinics seek intensity-modulated proton therapy capabilities. Pediatric oncology applications command premium positioning within the application mix given proton therapy's tissue-sparing benefits for developing bodies.
The FDA Center for Devices and Radiological Health enforces stringent premarket approval requirements for proton therapy systems, extending commercialization timelines but ensuring clinical safety benchmarks. State-level certificate-of-need regulations in Texas, Florida, and New York govern hospital capital expansion for proton facilities, directly constraining regional supply growth. Stakeholders must monitor Medicare reimbursement rate determinations for proton therapy procedures, as coverage decisions by the Centers for Medicare and Medicaid Services will shape patient access and capital return timelines for new center developments.
Market Dynamics
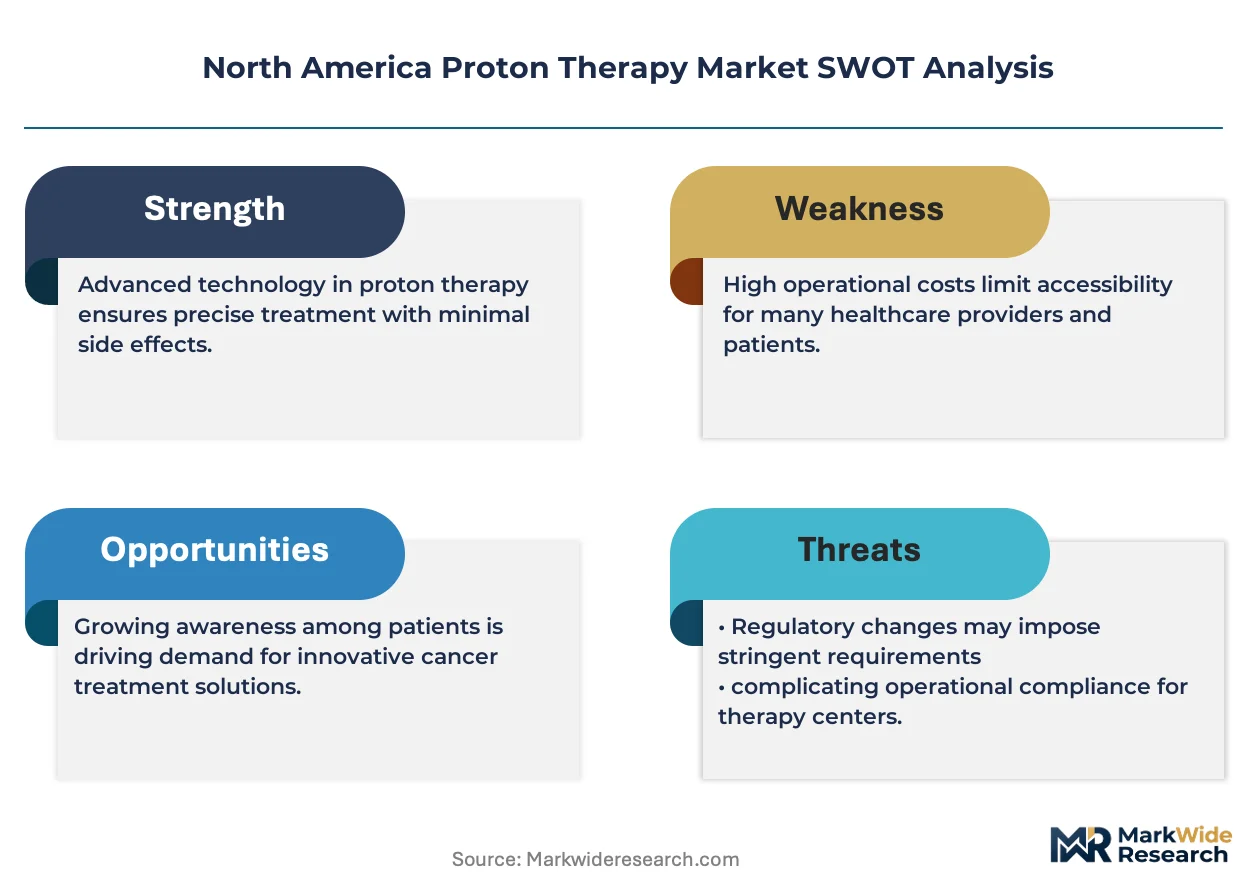
Certificate-of-need regulations in Texas, Florida, and New York constrain proton center expansion while spot scanning technology compresses treatment delivery times, forcing vendors to compete on throughput economics rather than capital equipment sales alone.
Growth Catalysts
- Pediatric oncology protocols:Children's hospitals across the United States prioritize proton therapy for craniospinal and solid tumor treatments where tissue-sparing precision protects developing organs. State Medicaid programs in California and Massachusetts now cover proton procedures for pediatric indications.
- Spot scanning beam delivery:Intensity-modulated proton therapy enables dose painting to complex tumor geometries previously unreachable with passive scattering. Academic medical centers in Houston and Boston lead clinical adoption.
- Medicare reimbursement expansion:The Centers for Medicare and Medicaid Services issued favorable national coverage determinations for proton therapy in lung and liver cancer, expanding addressable patient populations beyond prostate and pediatric cases.
Market Restraints
- Superconducting magnet supply concentration:High-field cyclotron magnets rely on a limited supplier base in Germany and Japan, creating procurement bottlenecks for North American system integrators.
- Concrete shielding cost inflation:Multi-foot radiation vault construction requires specialized contractors and steel-reinforced concrete, with material costs fluctuating with regional construction demand.
- Certificate-of-need friction:New York and Florida regulators deny hospital capital expansion applications where existing proton capacity sits underutilized, freezing greenfield development in saturated metropolitan markets.
Strategic Opportunities
- Single-room compact systems:Community cancer centers in secondary Texas markets like San Antonio and Austin seek lower-capital proton alternatives to multi-room academic configurations.
- Carbon ion convergence:Research institutions in Dallas and Miami explore dual-modality centers combining proton and carbon ion capabilities for radioresistant tumors.
- Canadian provincial expansion:Ontario and Alberta health authorities evaluate proton facility investments to retain pediatric patients currently referred to United States centers.
Industry Challenges
- Medical physicist scarcity:Beam commissioning and daily quality assurance require specialized personnel with proton-specific training; academic programs at University of Pennsylvania and MD Anderson cannot graduate sufficient talent.
- FDA premarket approval timelines:Novel beam delivery technologies face extended clinical trial requirements, delaying commercial deployment by 18-24 months beyond European regulatory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Proton Therapy Market |
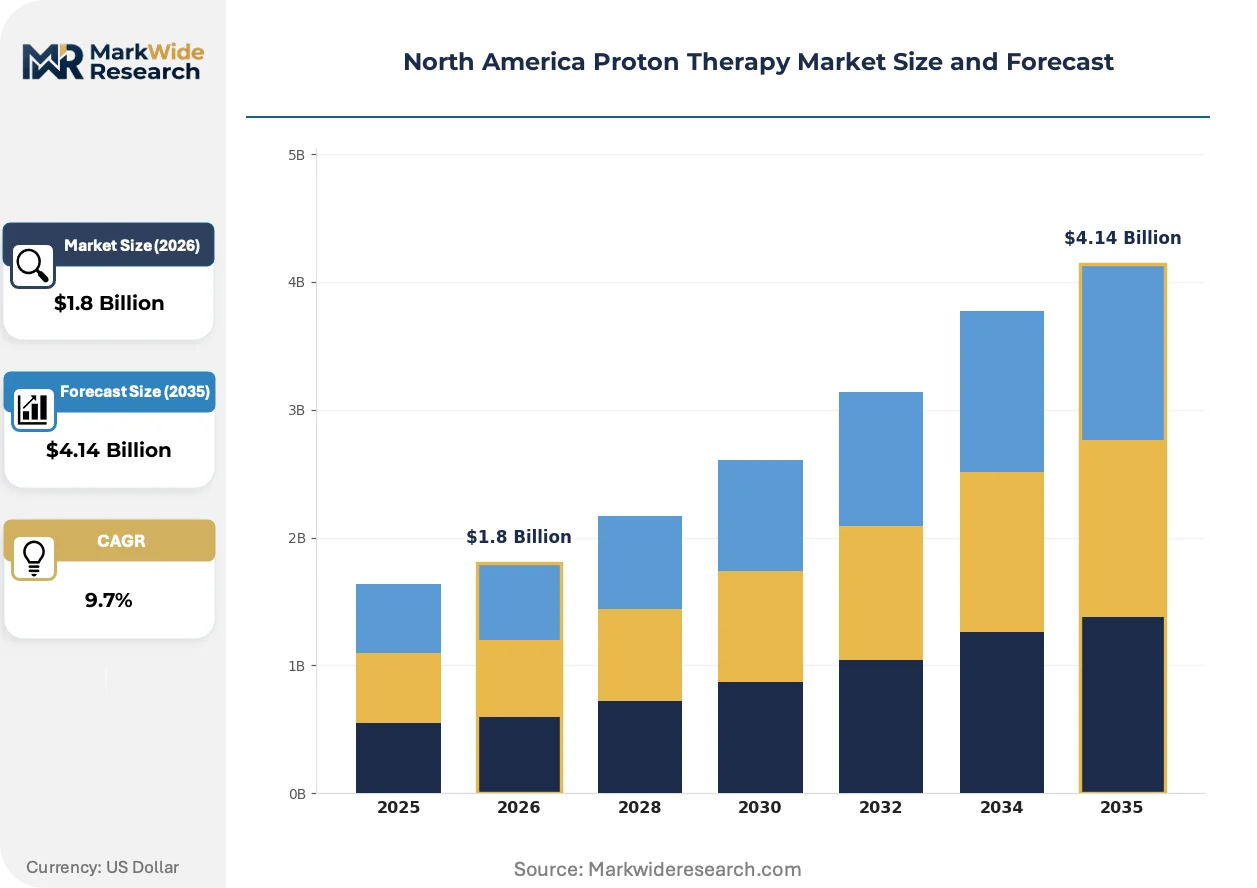
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Room Systems, Multi-Room Systems, Service Contracts, Accessories End User: Hospitals, Cancer Treatment Centers, Research Institutions, Academic Medical Centers Technology: Passive Angle Scattering, Active Scattering, Spot Scanning, Hybrid Systems Application: Pediatric Oncology, Adult Oncology, Neurological Conditions, Cardiac Conditions |
| Companies Covered | Varian Medical Systems, Mevion Medical Systems, ProNova Solutions, Optivus Proton Therapy, ProTom International, IBA Worldwide, Hitachi, Sumitomo Heavy Industries, Advanced Oncotherapy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Proton Therapy Market Trends and Innovations
Proton therapy systems are converging with adaptive planning software and real-time imaging, compressing the gap between simulation and treatment while enabling same-day plan adjustments for mobile tumors.
Spot scanning technology is integrating pencil beam scanning with respiratory gating to track lung and liver tumors during beam delivery. Major cancer centers in Dallas and Jacksonville deploy these systems for thoracic malignancies. The technology is integrating motion management with dose reconstruction, enabling hypofractionated regimens that compress treatment courses from 30 sessions to 5.
The FDA Center for Devices and Radiological Health tightened software validation requirements for proton therapy planning systems in 2023, mandating independent dose calculation verification. Vendors now submit extensive beam model documentation. Pediatric treatment protocols face heightened scrutiny, with FDA reviewers requiring longitudinal toxicity data for growing tissue exposure.
Hospital procurement teams unbundle service contracts from initial equipment purchases, negotiating multi-year maintenance separately after competitive bidding. Academic medical centers in California and Texas lead this shift, pressuring Varian and IBA to disclose hourly labor rates and parts markup. The practice spreads to community hospital joint ventures in Florida, where capital constraints force operational expenditure scrutiny.
North America Proton Therapy Market Segmentation
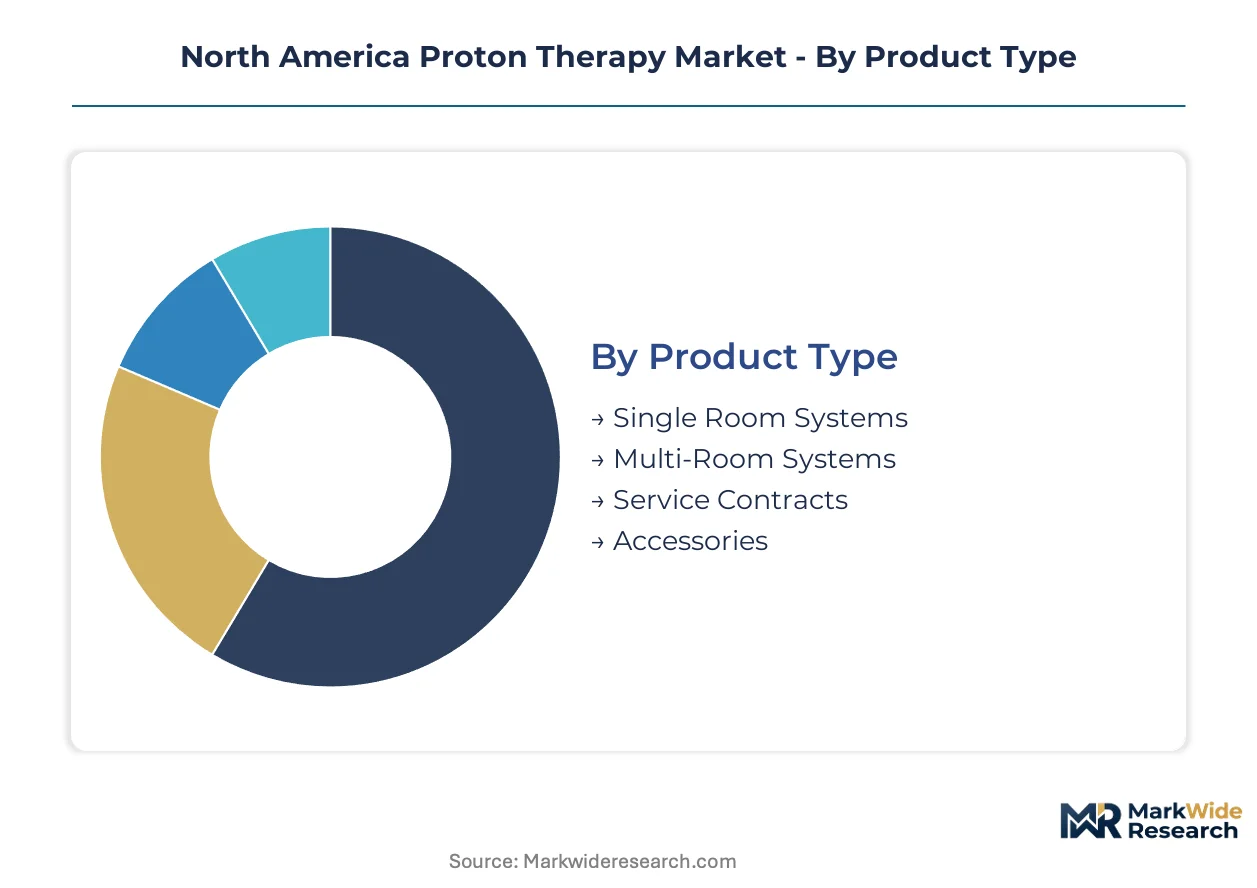
Proton therapy segmentation reveals how capital intensity, clinical workflow integration, and reimbursement pathways shape purchasing decisions across North American healthcare systems. Equipment configurations range from compact single-room installations to sprawling multi-room academic complexes, each serving distinct patient throughput and research missions.
Product Type:
Standalone proton systems dominate capital budgets, while embedded service layers now generate recurring revenue streams that extend vendor relationships across decades.
- Single Room Systems:Compact cyclotron or synchrotron configurations housed in shielded vaults requiring roughly one-third the footprint of multi-room alternatives. Community cancer centers in Texas secondary markets like San Antonio and Austin deploy these systems to offer proton capabilities without academic medical center overhead. Mevion Medical Systems anchors this segment with its superconducting synchrocyclotron design.
- Multi-Room Systems:Central beamline architectures feeding three to five treatment rooms from a single particle accelerator, maximizing patient throughput for high-volume centers. Major metropolitan hospital clusters in Houston, Dallas, and Jacksonville favor these configurations where certificate-of-need regulations protect capital returns through controlled regional supply. Varian Medical Systems and IBA Worldwide compete primarily in this tier.
- Service Contracts:Cyclotron maintenance, beam-line calibration, and software support agreements that shift vendor economics toward long-term partnerships. Procurement teams increasingly unbundle these contracts from initial equipment purchases, negotiating multi-year terms separately after competitive bidding.
- Accessories:Patient positioning systems, immobilization devices, and respiratory gating hardware that integrate with base beam delivery platforms.
Multi-room systems lead volumes today; single-room configurations are gaining share fastest as community hospitals seek lower-capital proton alternatives.
End User:
Customer concentration varies sharply by capital access, with academic institutions commanding technology leadership while community hospitals drive volume expansion.
- Hospitals:Integrated health systems with diversified service lines that add proton therapy as a specialty cancer service. Major systems in Florida and California construct proton centers as destination medicine anchors to capture out-of-market referrals.
- Cancer Treatment Centers:Dedicated oncology facilities where proton therapy represents core clinical identity rather than ancillary service. These centers achieve higher beam utilization rates through focused patient scheduling and disease-specific protocols.
- Research Institutions:National laboratories and university-affiliated facilities exploring next-generation beam delivery, biological effectiveness modeling, and radio-resistant tumor applications. MD Anderson Cancer Center and University of Pennsylvania anchor this segment with active proton research programs.
- Academic Medical Centers:Teaching hospitals combining clinical service with residency training and clinical trial infrastructure. These institutions lead adoption of spot scanning technology and adaptive planning software, setting protocols that diffuse to community settings.
Academic medical centers anchor technology adoption; cancer treatment centers are expanding capacity most aggressively.
Technology:
Beam delivery sophistication determines clinical applicability, with precision-modulated systems displacing legacy scattering approaches in new installations.
- Passive Angle Scattering:First-generation beam broadening using compensators and collimators to shape dose distributions around tumor contours. Legacy installations in early-adopter proton centers retain these systems, though new procurement favors modulated alternatives.
- Active Scattering:Magnetically controlled beam spreading that reduces neutron contamination and improves dose conformity compared with passive methods. Mid-tier academic centers in the Midwest deployed this technology during proton expansion phases.
- Spot Scanning:Pencil beam scanning enabling intensity-modulated proton therapy with dose painting to complex tumor geometries previously unreachable. Academic medical centers in Houston and Boston lead clinical adoption, with respiratory gating integration tracking lung and liver tumors during delivery. This modality enables hypofractionated regimens compressing treatment courses from thirty sessions to five.
- Hybrid Systems:Platforms combining passive and active scanning capabilities to accommodate diverse clinical protocols within single installations.
Passive scattering retains installed base dominance; spot scanning commands all new capital deployment.
Application:
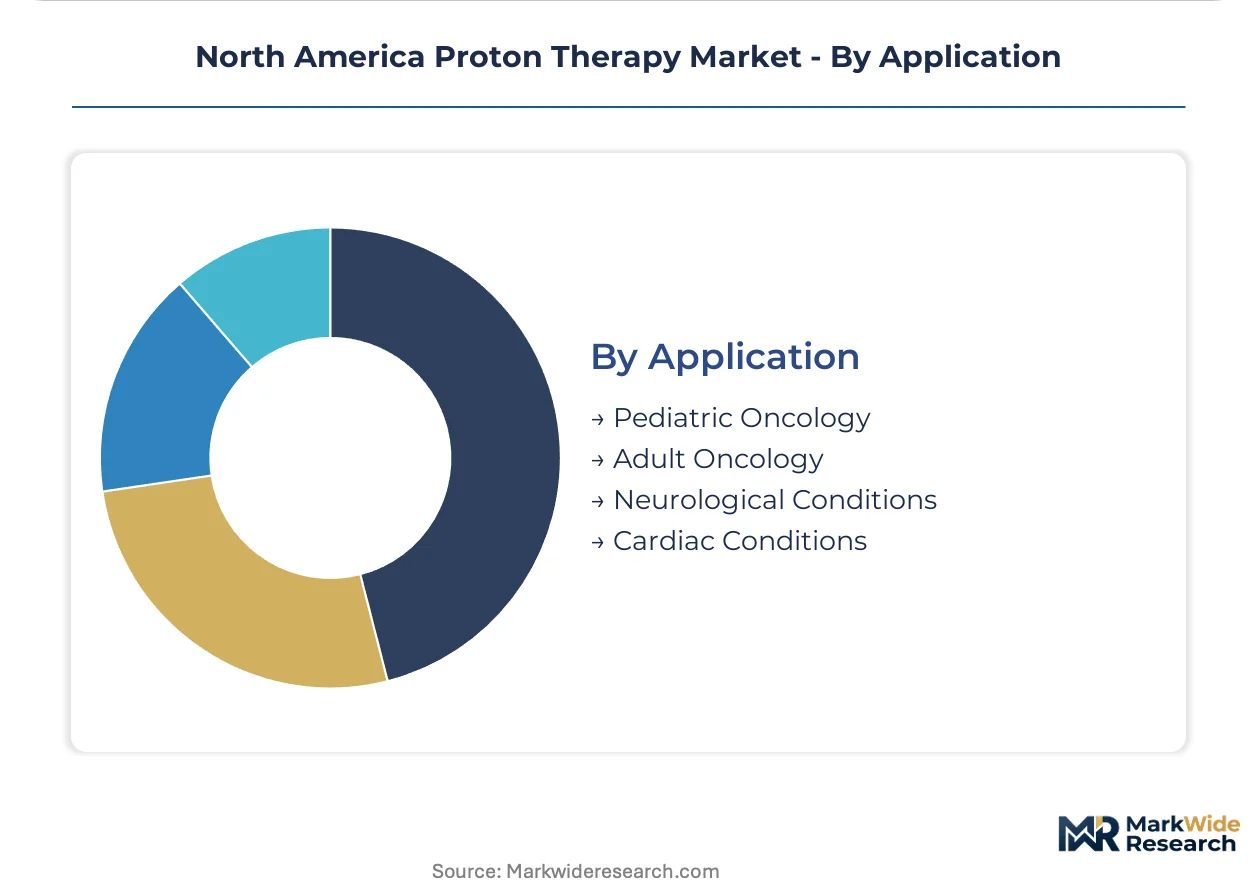
Clinical indication mix shapes reimbursement economics and capital planning, with pediatric cases commanding premium positioning despite smaller volume shares.
- Pediatric Oncology:Craniospinal irradiation and solid tumor treatments where tissue-sparing precision protects developing organs from radiation-induced growth impairment and secondary malignancies. State Medicaid programs in California and Massachusetts now cover proton procedures for pediatric indications, expanding access beyond commercially insured populations.
- Adult Oncology:Prostate, lung, liver, and head-and-neck malignancies where proton dosimetry advantages translate to reduced toxicity profiles. Medicare national coverage determinations for lung and liver applications expanded addressable patient populations substantially.
- Neurological Conditions:Arteriovenous malformations and benign brain tumors requiring sub-millimeter precision adjacent to critical neural structures.
- Cardiac Conditions:Emerging applications in cardiac radioablation for arrhythmia management, still investigational at major research institutions.
Adult oncology generates procedure volume leadership; pediatric applications command the steepest reimbursement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands proton therapy infrastructure concentration unmatched by Canada, where provincial health authorities deliberate facility investments while pediatric patients cross the border for treatment.
United States
Texas, Florida, and California anchor proton center construction activity, with metropolitan hospital clusters in Houston, Dallas, and Jacksonville favoring multi-room configurations for throughput advantages. The FDA Center for Devices and Radiological Health enforces stringent premarket approval requirements that extend commercialization timelines. Academic medical centers in Boston and Philadelphia lead spot scanning adoption, setting clinical protocols that diffuse to community settings.
Canada
Ontario and Alberta health authorities evaluate proton facility investments to retain pediatric oncology patients currently referred to United States centers, driven by tissue-sparing precision requirements for craniospinal treatments. Health Canada regulates particle beam systems through its medical device licensing framework. Toronto's University Health Network and Edmonton's Cross Cancer Institute anchor research collaborations with American proton centers.
Mexico
Private hospital groups in Mexico City and Monterrey explore proton therapy partnerships with United States academic medical centers to capture regional medical tourism demand for oncology services. The Federal Commission for the Protection against Sanitary Risk (COFEPRIS) governs radiation therapy device registration. Guadalajara's Hospital Civil and Tijuana's medical corridor represent emerging collaboration nodes for cross-border patient referral networks.
North America Proton Therapy Market Competitive Landscape
Top-tier vendors anchor multi-room system deployments at academic medical centers, while compact single-room specialists target community hospital joint ventures. The vendor landscape concentrates around cyclotron manufacturers and beam delivery integrators with established service infrastructures. Three archetypes dominate: full-stack system integrators, compact system specialists, and service-contract consolidators. Competitive moves center on unbundling maintenance agreements from hardware sales and securing multi-year operational partnerships.
Within the full-stack integrator tier, Varian Medical Systems and IBA Worldwide occupy positions defined by installed base scale and beamline architecture breadth. Mevion Medical Systems exemplifies the compact system archetype through superconducting synchrocyclotron designs that reduce facility footprints. Among Asia-Pacific headquartered conglomerates with radiation therapy divisions, Hitachi and Sumitomo Heavy Industries represent diversified industrial players leveraging accelerator physics expertise across medical and non-medical applications.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Mevion Medical Systems |
| ProNova Solutions |
| Optivus Proton Therapy |
| ProTom International |
| IBA Worldwide |
| Hitachi |
| Sumitomo Heavy Industries |
| Advanced Oncotherapy |
| Others |
Pricing and Supply Chain Analysis
FDA radiation safety mandates gate both qualified superconducting magnet suppliers and premium-tier system pricing access, compressing vendor margins for non-compliant configurations while elevating certified equipment premiums. Proton therapy capital economics hinge on this regulatory filter, with beam-line calibration certification becoming the decisive cost threshold separating viable from marginal suppliers.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for multi-room installations as certificate-of-need protections erode in saturated metropolitan markets. Three-tier pricing structure across academic medical center, community hospital, and research consortium levels reflects customization depth and service bundling intensity. Cost compression in single-room configurations is intensifying because Mevion's compact synchrocyclotron designs force legacy vendors to unbundle maintenance contracts. Community hospital joint ventures in secondary Texas markets exhibit highest price sensitivity; academic medical centers with NIH funding access show least.
Supply Chain Analysis
CE marking and FDA premarket approval timelines gate superconducting magnet procurement, with German and Japanese specialty steel suppliers commanding 18-24 month order backlogs. Beam delivery systems draw from niobium-titanium superconductor feedstock, precision-machined vacuum chambers, and radiation-hardened control electronics. Single-source vulnerability concentrates in high-field cyclotron magnet fabrication, where two suppliers serve North American integrators. Distribution runs through direct vendor-hospital contracting with embedded multi-year service partnerships, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proton therapy economics favor margin expansion through service contract unbundling and spot scanning technology premiums, with single-room system cost-down curves widening addressable hospital segments.
For Market Incumbents: Cement installed base lock-in through multi-year cyclotron maintenance agreements that extend beyond equipment depreciation cycles, countering compact system entrants. Deepen beam-line calibration certification investments to raise rival technical barriers. Prioritize respiratory-gated spot scanning R&D to maintain technology leadership against carbon ion convergence threats. For New Entrants and Emerging Players: Compact superconducting synchrocyclotron designs offer wedge positioning into community cancer center joint ventures in Austin, San Antonio, and Calgary where capital constraints exclude multi-room configurations. Target Canadian provincial health authorities evaluating proton retention strategies for pediatric oncology referrals. Pursue hospital system partnership go-to-market models with shared risk financing. For Investors and Strategic Acquirers: Roll-up economics work for regional service contract consolidators because beam-line maintenance expertise concentrates in a handful of medical physicist training programs. Five-to-ten year viability hinges on Medicare reimbursement expansion durability. Watch carbon ion dual-modality research commitments at MD Anderson and University of Miami as technology inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Novel beam delivery technologies require 18-24 month clinical trial extensions beyond European clearance timelines. |
| Hospital System Partnership | Academic medical centers in Houston and Boston set spot scanning protocols that diffuse to community settings. |
| Software Companion Development | Adaptive planning integration with real-time imaging compresses simulation-to-treatment gaps for mobile tumors. |
| Reimbursement Strategy | CMS national coverage determinations for lung and liver applications expanded addressable patient populations substantially. |
| CE Marking Pathway | Health Canada medical device licensing framework governs provincial facility investments in Ontario and Alberta. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with proton center medical physicists, hospital procurement committee members, GPO contracts managers, and cyclotron maintenance technicians with secondary validation. FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, state certificate-of-need records, and hospital capital expenditure disclosures anchored bottom-up and top-down triangulation.
Segment-weighting approaches modeled single-room versus multi-room system configurations, spot scanning versus passive scattering technology tiers, and academic medical center versus community hospital end-use categories across the projection horizon. CAGRs derived from equipment shipment trajectories, service contract renewal rates, and procedure volume scaling assumptions. Forecast inputs incorporated Medicare coverage determination timing and superconducting magnet supplier capacity constraints.
The model holds under stable FDA premarket approval timelines and CMS reimbursement continuity; deviation in certificate-of-need regulatory stringency or carbon ion clinical trial outcomes would shift capacity deployment trajectories. A model refresh is warranted upon material change in pediatric Medicaid coverage expansion or superconducting magnet supplier consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Particle Therapy Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Metastases Spinal Tumor Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Thyroid Cancer Market
Oncology
Global Cancer Profiling Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Sterile Oncology Injectable Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Particle Therapy Systems Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Global HER-2 Negative Breast Cancer Market