
 Laser Cancer Therapy Market | 2026-2036
Laser Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cancer Therapy Market Analysis
Buyer concentration among hospital networks is realigning procurement patterns across the laser cancer therapy supply base. Varian Oncology leverages its installed base of radiation platforms to cross-sell laser-guided systems. Accuray anchors its position through precision targeting technology that integrates with existing oncology workflows. Modulight competes on diode laser specialization for photodynamic applications in European treatment centers.
Laser cancer therapy employs coherent light sources—typically operating at wavelengths from 630 nm to 1064 nm—to induce selective thermal destruction or photochemical activation of malignant tissue, with power densities calibrated to spare adjacent healthy structures. Photodynamic therapy segments command premium positioning due to recurring photosensitizer drug requirements and specialized training protocols. Diode lasers lead volume deployments in ambulatory settings where compact footprint and lower capital thresholds dominate purchasing criteria. Nd:YAG systems occupy the deepest penetration in hospitals managing lung and prostate interventions through fiber-optic delivery.
FDA device classification and EMA's Medical Device Regulation impose clinical evidence thresholds that filter market entrants and extend approval timelines for novel laser oncology platforms. CE marking requirements under the EU MDR compel manufacturers to maintain post-market surveillance systems that track adverse events across European treatment sites. The EPA regulates disposal protocols for photosensitizer waste streams in US clinical facilities. Stakeholders must monitor evolving reimbursement codes for outpatient laser ablation procedures as payers recalibrate coverage policies against comparative effectiveness data.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing laser oncology suppliers to bundle service contracts with hardware sales. This buyer-side concentration favors integrated platform vendors over standalone laser manufacturers.
Growth Catalysts
- Photodynamic therapy protocols:Recurring photosensitizer drug requirements create annuity revenue streams that attract diversified pharmaceutical investment. University hospitals in Germany anchor clinical validation studies that accelerate protocol adoption.
- FDA Breakthrough Device pathway:Streamlined premarket review timelines compress commercialization cycles for novel laser ablation platforms. This regulatory efficiency particularly benefits interstitial lung applications.
- Ambulatory surgical center expansion:Diode laser compact footprint aligns with outpatient capital constraints and same-day discharge mandates. Medicare reimbursement codes for office-based tumor ablation reinforce site-of-care migration.
Market Restraints
- Photosensitizer supply concentration:Three European chemical manufacturers control precursor synthesis for FDA-approved agents, creating single-source vulnerability.
- Technical wavelength limitation:Tissue penetration depth at 630 nm restricts photodynamic efficacy to superficial or endoscopically accessible lesions.
- EMA MDR clinical evidence thresholds:Expanded post-market surveillance obligations extend approval timelines and inflate regulatory compliance costs for CE marking renewal.
Strategic Opportunities
- India tertiary hospital network expansion:Government oncology infrastructure investment creates first-mover positioning for diode laser deployment in tier-2 cities.
- Real-time thermography integration:Convergent infrared monitoring and robotic laser positioning enables sub-millimeter thermal boundary control.
- Japan PMDA regenerative medicine framework:Expedited review pathways for laser-assisted stem cell delivery applications open oncology-adjacent revenue pools.
Industry Challenges
- Interdisciplinary training deficits:Photodynamic therapy requires certified oncologists, physicists, and pharmacy staff coordination that exceeds standard radiation therapy staffing models.
- Legacy EMR integration complexity:Laser ablation procedure documentation lacks standardized HL7 FHIR templates, forcing custom interface development at each hospital system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cancer Therapy Market |
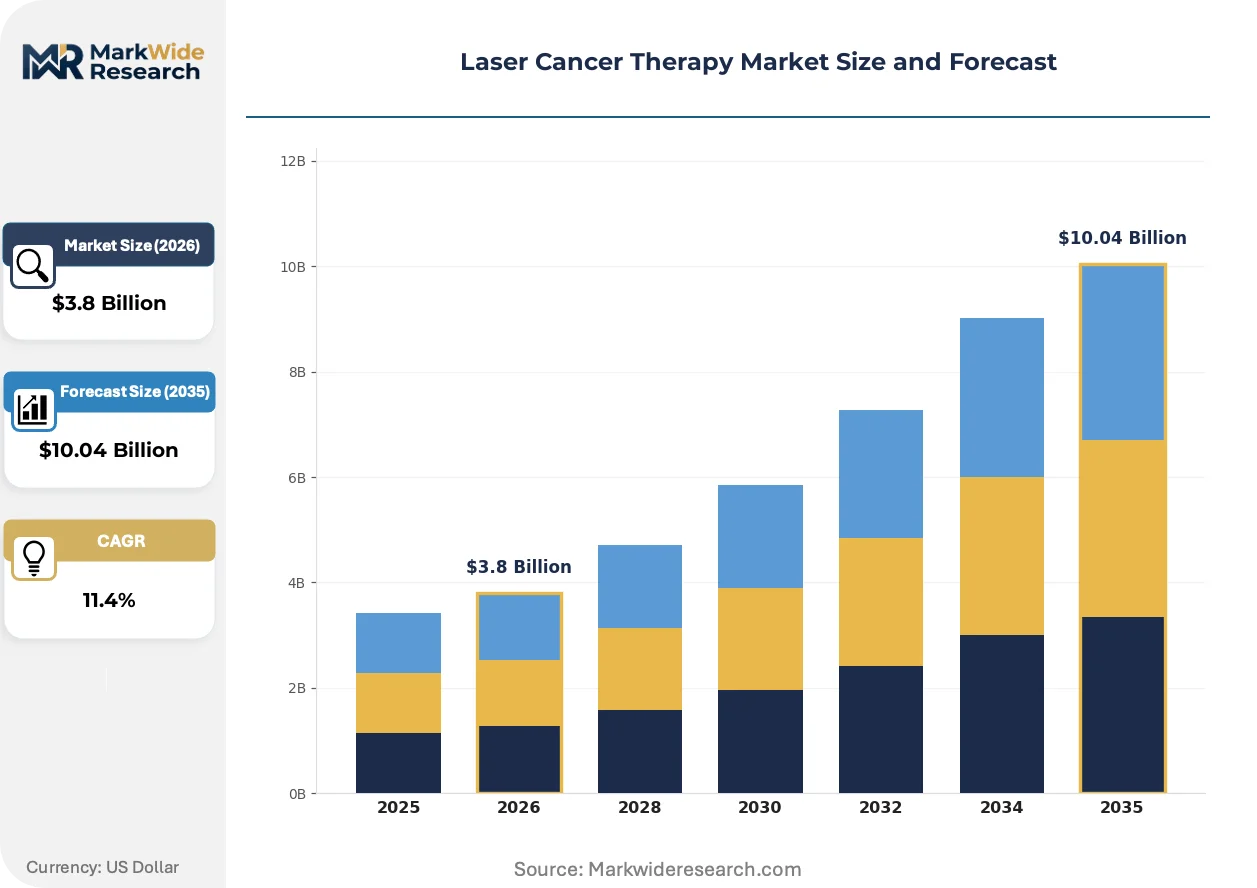
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Diode Laser, Nd:YAG Laser, Excimer Laser Technology: Photothermal Therapy, Photodynamic Therapy, Laser-Induced Thermotherapy, Laser Ablation End User: Hospitals, Ambulatory Surgical Centers, Oncology Clinics, Research Institutes Application: Skin Cancer Treatment, Lung Cancer Treatment, Prostate Cancer Treatment, Head & Neck Cancer Treatment |
| Companies Covered | Accuray, Neusoft Medical Systems, Modulight, Shinva Medical Instrument, Reflexion Medical, Varian Oncology, LAP GmbH Laser Applikationen, MN Medical, ViewRay Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cancer Therapy Market Emerging Trajectories
Robotic fiber positioning systems are eliminating manual dexterity variance in interstitial procedures. This automation wave is compressing training curves and expanding treatable patient populations beyond specialized academic centers.
Multi-wavelength tunable diode platforms are consolidating previously discrete laser modalities into single capital assets. Oncology departments at mid-size hospitals adopt these systems to avoid redundant equipment purchases. The technology is consolidating vendor relationships by displacing standalone Nd:YAG and KTP laser installations.
EPA hazardous waste rules for photosensitizer disposal are tightening containment and documentation requirements. Clinical facilities must now install dedicated pharmaceutical waste streams with chain-of-custody tracking. Outpatient centers in California and Texas face the steepest compliance cost escalation.
Hospital system value analysis committees now mandate five-year total cost of ownership modeling before laser platform approval. This procurement behavior elevates service contract transparency and consumable pricing predictability over upfront capital discounts. The shift is most pronounced in US Midwest integrated delivery networks.
Laser Cancer Therapy Market Segmentation
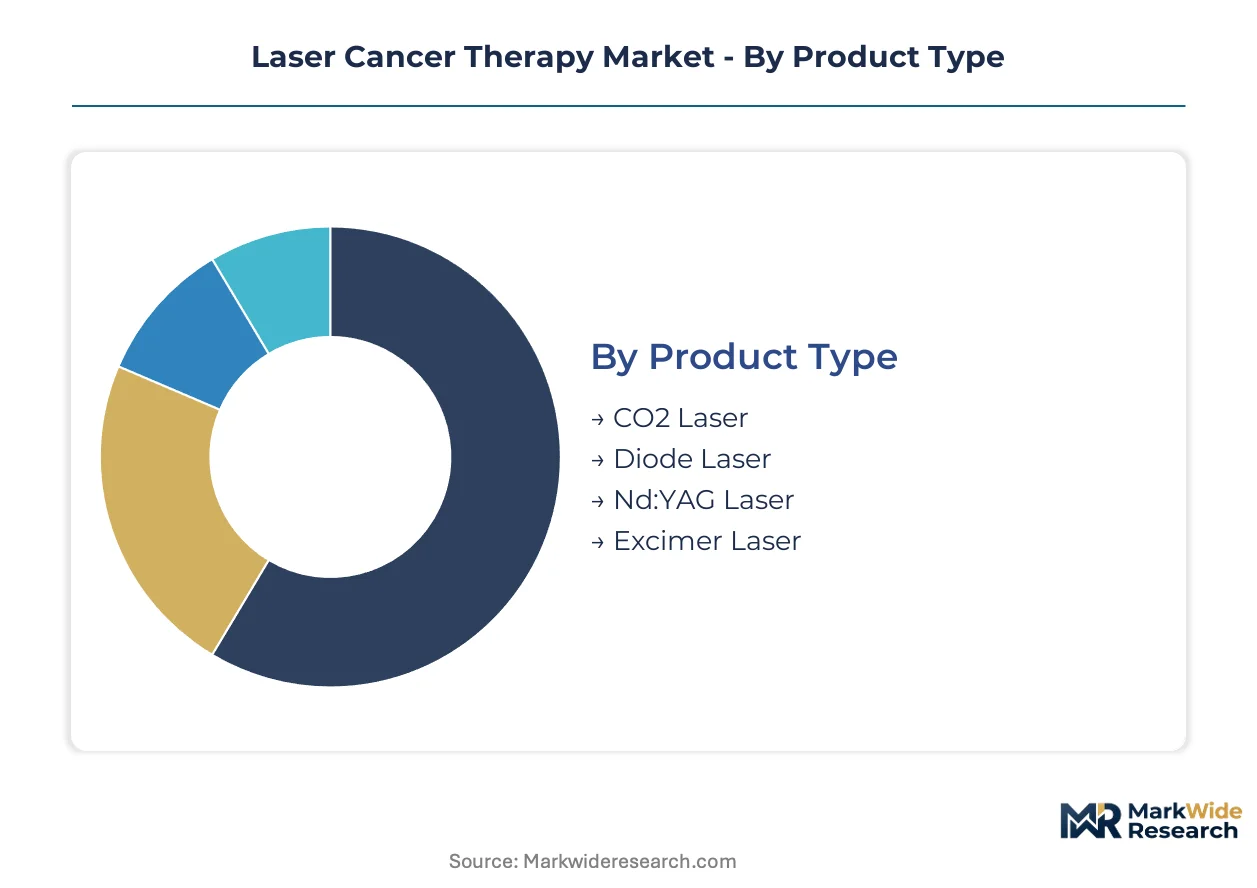
Segmentation in laser cancer therapy reveals how technology integration depth shapes procurement decisions across care settings. Standalone laser systems compete against embedded platforms that bundle diagnostics with therapeutic delivery, creating divergent margin structures and replacement cycles.
Product Type:
Integration depth varies sharply across laser modalities, with fiber-delivered systems embedding into surgical suites while free-beam units remain standalone investments.
- Diode Laser:Compact semiconductor sources operating at 630-980 nm wavelengths enable fiber-optic delivery through endoscopic channels. Demand clusters in German ambulatory centers where reimbursement favors same-day photodynamic protocols. The lower capital threshold accelerates replacement cycles compared to solid-state alternatives.
- Nd:YAG Laser:Neodymium-doped yttrium aluminum garnet crystals generate 1064 nm emission with tissue penetration exceeding 10 mm. University hospitals in Munich and Heidelberg deploy these systems for interstitial lung and prostate interventions requiring deep thermal reach. Fiber compatibility with existing surgical navigation platforms reinforces embedded positioning.
- CO2 Laser:Gas-discharge sources at 10,600 nm deliver precise superficial ablation with minimal lateral thermal spread.
- Excimer Laser:Rare gas halide systems produce ultraviolet emission for corneal and dermal applications with sub-micron tissue removal precision.
Volume placements concentrate in diode configurations; the steeper expansion trajectory belongs to Nd:YAG systems as interstitial indications broaden.
Technology:
Cost tier stratification separates capital-intensive hardware platforms from consumable-dependent protocols that generate recurring pharmaceutical revenue.
- Photodynamic Therapy:Photosensitizer drug activation at specific wavelengths creates photochemical cytotoxicity rather than thermal damage. Oncology clinics in Bavaria anchor adoption where university hospital protocols validate outcomes data for payer negotiations. The recurring drug requirement shifts vendor economics toward pharmaceutical margins.
- Photothermal Therapy:Direct light-to-heat conversion at 800-1000 nm wavelengths achieves tissue coagulation through protein denaturation. Hospital networks in North Rhine-Westphalia standardize on these protocols for cutaneous lesions, leveraging existing dermatology infrastructure. Simplified training requirements accelerate deployment compared to photosensitizer-dependent alternatives.
- Laser-Induced Thermotherapy:Magnetic nanoparticle enhancement enables targeted heating with reduced optical power requirements.
- Laser Ablation:High-power density pulses achieve immediate tissue vaporization for precise margin control in resectable tumors.
Revenue concentration sits with photodynamic protocols; photothermal applications are climbing fastest as training barriers fall.
End User:
Customer type determines capital allocation authority, with consolidated hospital systems wielding procurement leverage that fragments vendor pricing power.
- Hospitals:Integrated delivery networks manage multi-modality oncology departments with centralized capital budgeting. The Charité network in Berlin and university hospitals across Baden-Württemberg anchor high-volume deployment, bundling laser platforms with radiation and surgical robotics. Value analysis committees now mandate seven-year total cost of ownership modeling.
- Ambulatory Surgical Centers:Outpatient facilities prioritize compact diode systems aligned with same-day discharge mandates. Medicare reimbursement codes for office-based tumor ablation reinforce site-of-care migration in US markets, while German ambulatory surgery centers leverage statutory health insurance recognition.
- Oncology Clinics:Specialized cancer treatment centers concentrate photodynamic therapy expertise and patient volume.
- Research Institutes:Academic medical centers validate novel protocols and train clinical staff for broader adoption.
Hardware shipments concentrate in hospital systems; ambulatory settings are expanding most quickly as reimbursement shifts enable site-of-care migration.
Application:
Clinical indication drives wavelength selection and regulatory pathway complexity, with superficial applications facing lower evidence thresholds than interstitial indications.
- Skin Cancer Treatment:Basal cell carcinoma and melanoma interventions leverage accessible lesion geometry for straightforward optical delivery. Dermatology departments at Heidelberg University Hospital and Munich's Klinikum rechts der Isar anchor protocol development. Payer coverage for outpatient basal cell ablation reinforces volume concentration.
- Prostate Cancer Treatment:Interstitial fiber placement through transperineal approaches demands image guidance integration and specialized urology training. University hospitals in Hamburg and Cologne validate focal ablation protocols that preserve functional outcomes. The procedure complexity creates higher vendor stickiness through training investment.
- Lung Cancer Treatment:Bronchoscopic delivery targets central airway obstructions and early-stage peripheral lesions.
- Head & Neck Cancer Treatment:Laryngeal and oral cavity applications require micron-level precision to preserve speech and swallowing function.
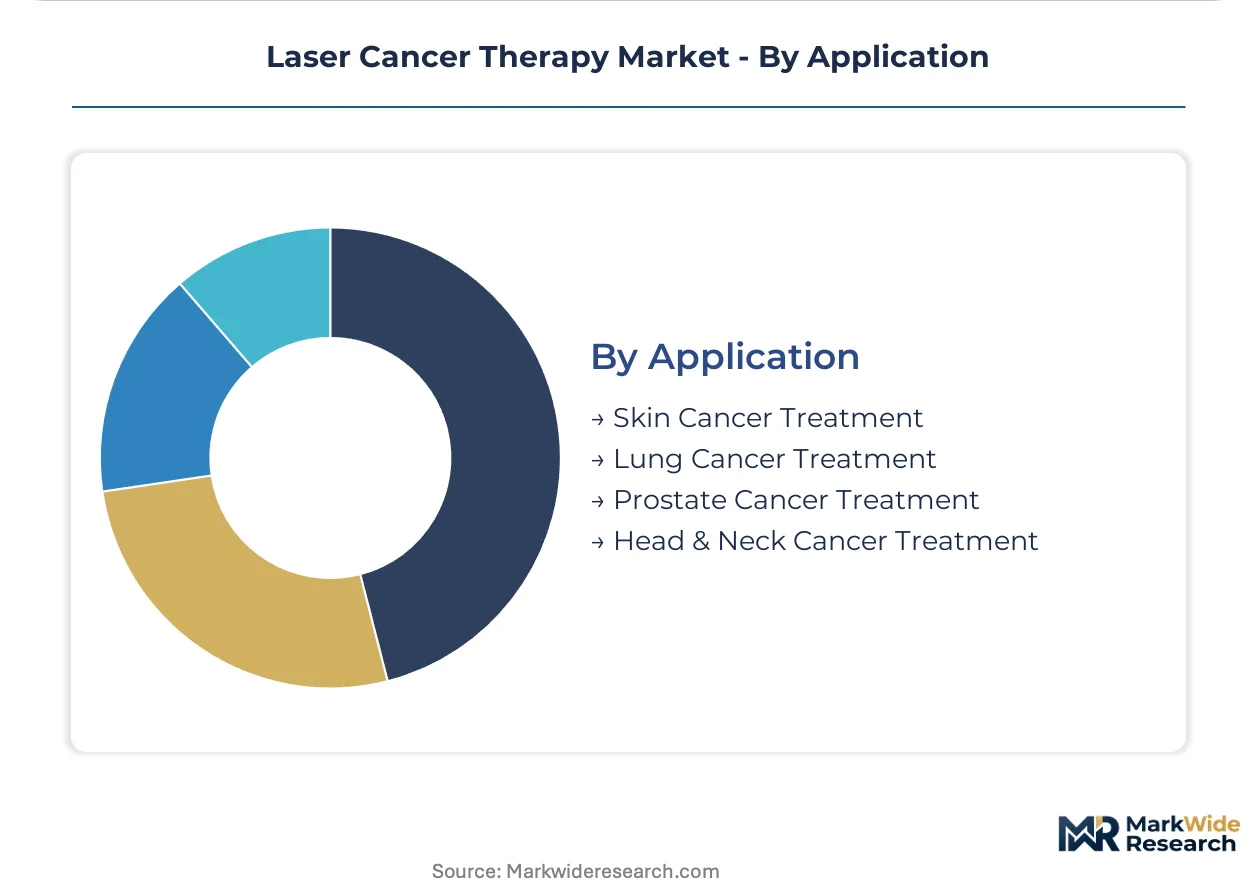
Procedure volume concentrates in dermatologic applications; urologic indications are gaining share fastest as focal therapy protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor clinical validation and reimbursement frameworks for photodynamic protocols. United States ambulatory centers drive diode laser volume through Medicare site-of-care incentives. Japanese regulators expedite novel applications under regenerative medicine pathways.
United States
FDA Breakthrough Device pathways compress premarket timelines for interstitial lung laser platforms. EPA hazardous waste rules tighten photosensitizer disposal documentation for outpatient facilities in California and Texas. The MD Anderson Cancer Center in Houston validates focal ablation protocols that diffuse into community hospital networks.
Germany
Statutory health insurance recognition of same-day photodynamic procedures concentrates demand in Bavarian ambulatory surgery centers. EMA MDR post-market surveillance obligations extend CE marking renewal cycles for laser oncology platforms. University hospitals in Munich and Heidelberg anchor interstitial Nd:YAG deployment for prostate interventions.
Japan
PMDA regenerative medicine frameworks expedite review pathways for laser-assisted stem cell delivery applications. METI funding for minimally invasive oncology infrastructure elevates hospital procurement budgets for multi-wavelength platforms. The Kansai region around Osaka concentrates manufacturing partnerships between diode laser suppliers and surgical robotics developers.
India
Government oncology infrastructure investment in tier-2 cities creates first-mover positioning for compact diode laser deployment. CDSCO medical device registration requirements filter import channels for foreign-manufactured platforms. Tertiary hospital networks in Maharashtra and Karnataka standardize on fiber-delivered systems for accessible skin and head-neck lesions.
United Kingdom
NICE technology appraisals condition NHS reimbursement for photodynamic therapy against comparative effectiveness thresholds. MHRA post-Brexit device regulations maintain alignment with EU MDR clinical evidence standards. London teaching hospitals concentrate protocol development for bronchoscopic laser delivery in central airway obstructions.
Laser Cancer Therapy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue robotic fiber positioning and real-time thermography integration. Hospital procurement consolidation compresses vendor margins and forces bundled service contracts with hardware sales. Three strategic archetypes dominate: integrated radiation-laser platform vendors, diode laser specialists for photodynamic applications, and precision targeting technology developers. Competitive moves concentrate on cross-selling through installed radiation bases and multi-wavelength platform consolidation.
Within the integrated platform tier, Varian Oncology and Accuray exemplify archetypes leveraging radiation therapy relationships to anchor laser-guided system placement. Modulight occupies a specialist position in diode laser configurations for European photodynamic centers. LAP GmbH Laser Applikationen represents German precision engineering applied to fiber-optic delivery systems.
| Leading Market Players |
|---|
| Accuray |
| Neusoft Medical Systems |
| Modulight |
| Shinva Medical Instrument |
| Reflexion Medical |
| Varian Oncology |
| LAP GmbH Laser Applikationen |
| MN Medical |
| ViewRay Incorporated |
| Others |
Supply Flow & Price Mechanics
Multi-wavelength tunable diode platforms are consolidating previously discrete laser modalities into single capital assets, simultaneously compressing per-procedure equipment costs and concentrating procurement leverage among integrated platform vendors over standalone diode specialists.
Pricing Analysis
Volume placements concentrate in diode configurations with thinner margins and faster replacement cycles, while Nd:YAG systems command premium positioning through deeper tissue penetration and longer depreciation schedules. Price differentiation separates FDA-cleared platforms for interstitial indications from CE-marked ambulatory systems with narrower clinical claims. Pricing pressure stems from hospital procurement consolidation mandating seven-year total cost of ownership modeling. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints and Medicare reimbursement ceilings.
Supply Chain Analysis
Direct-to-hospital channels handle integrated platform demand from consolidated delivery networks, while specialized distributors serve standalone diode laser procurement for European ambulatory centers. Manufacturing concentrates in Germany, Japan, and the United States for precision fiber-optic delivery systems. Precursor synthesis for photosensitizer agents draws from three European chemical manufacturers, creating single-source vulnerability for photodynamic therapy protocols. Distribution runs through GPO contracts for US hospital systems and statutory health insurance frameworks for German procurement. Tariff exposure on semiconductor laser components from East Asian foundries presents structural supply risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser cancer therapy market is becoming a vertical-integration race, with platform vendors pursuing captive photosensitizer supply and pharmaceutical margins through backward integration into drug precursor synthesis.
For Market Incumbents: Cement installed base stickiness through multi-wavelength platform consolidation that displaces standalone Nd:YAG and KTP installations. Deepen service contract transparency and consumable pricing predictability to satisfy value analysis committee mandates. Counter emerging robotic fiber positioning entrants by accelerating real-time thermography integration into existing surgical navigation workflows.
For New Entrants and Emerging Players: The premium-to-economy price gap in interstitial laser systems creates white-space positioning for mid-tier platforms with targeted prostate and lung indications. Focus initial deployment on Indian tier-2 tertiary hospitals where government oncology infrastructure investment outpaces established vendor coverage. Pursue CDSCO registration pathways ahead of domestic manufacturing scale-up to capture first-mover procurement cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where radiation therapy relationships anchor laser-guided cross-selling. Long-term viability favors vendors with integrated pharmaceutical revenue streams from recurring photosensitizer requirements. Monitor FDA Breakthrough Device designations for interstitial lung applications as inflection signals for platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Photosensitizer Backward Integration | Captive precursor supply secures pharmaceutical margins for photodynamic protocols against European chemical manufacturer concentration. |
| Multi-Wavelength Platform Consolidation | Single capital assets displace redundant Nd:YAG and KTP installations, compressing vendor relationships at mid-size hospitals. |
| Real-Time Thermography Integration | Sub-millimeter thermal boundary control enables robotic fiber positioning beyond specialized academic centers. |
| CE Marking Renewal Investment | EMA MDR post-market surveillance compliance extends market access for European photodynamic therapy deployments. |
| Indian Tier-2 Hospital Partnership | Government oncology infrastructure investment in Maharashtra and Karnataka creates first-mover positioning for compact diode deployment. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA MDR technical documentation, and CMS Medicare reimbursement code databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and photodynamic therapy protocol specialists. Secondary validation drew from hospital procurement databases, German statutory health insurance reimbursement schedules, and Japanese METI infrastructure funding disclosures. Bottom-up equipment shipment modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segment-level outputs across the projection horizon reflect technology-type splits by laser modality, integration depth by platform configuration, and end-user concentration by care setting. CAGRs were derived from procedure volume trajectories weighted by reimbursement code expansion and capital replacement cycle analysis. Forecast inputs incorporated EPA hazardous waste compliance cost escalation for photosensitizer disposal and PMDA regenerative medicine pathway timelines for laser-assisted stem cell applications.
Inputs from FDA premarket notification databases and German university hospital procurement records were available through the study window; gaps in real-time Indian tier-2 hospital installation data introduce uncertainty bands for emerging market penetration assumptions. Forecasts reflect documented assumptions regarding Medicare site-of-care migration velocity and EMA MDR renewal timeline standardization. Periodic stress-testing of base assumptions against regulatory pathway delays and photosensitizer supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer API Market
Oncology
Precision Oncology Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Breast Cancer Therapy Market
Oncology
Global Cancer Profiling Market
Oncology
Radiation Oncology Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Sterile Oncology Injectable Market
Oncology
Internal Radiation Therapy Market
Oncology
Australia Cancer Treatment Market
Oncology
Interventional Oncology Ablation Market
Oncology
South Korea Radiotherapy Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Asia-Pacific Proton Therapy Market