
 Cancer Cachexia Market | 2026-2036
Cancer Cachexia Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Cachexia Market Intelligence
A focus on novel mechanisms of action by specialized biopharmaceutical firms is realigning the development pipeline for cachexia treatments. Helsinn Group specializes in supportive cancer care products, building on its established portfolio. Actimed Therapeutics concentrates on developing drugs to combat muscle wasting. Bristol-Myers Squibb Company leverages its deep oncology expertise to investigate cachexia as part of a holistic cancer treatment approach.
Cancer cachexia is a multifactorial syndrome defined by severe body weight loss involving both fat and muscle tissue. This condition is driven by a variable combination of reduced food intake and abnormal metabolism. The market's objective is to provide interventions that preserve muscle mass and improve patient function and quality of life. Pharmacological treatments, including appetite stimulants and anti-inflammatory drugs, form the largest product segment, while therapies for pancreatic cancer patients see high utilization.
The US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) shape the development landscape through specific clinical trial endpoint requirements for cachexia therapeutics. Regulatory frameworks from bodies like Japan's PMDA also influence market access by setting standards for drug approval. Navigating these distinct regulatory pathways is critical for market participants. The ability to demonstrate a meaningful impact on patient physical function, not just weight gain, will determine future therapeutic leadership.
Market Dynamics
The imperative to demonstrate a clear impact on patient physical function, not just weight stabilization, is the central force shaping the cancer cachexia market. This pressure, originating from regulatory bodies like the FDA and EMA, is compelling a shift towards multi-modal therapeutic strategies.
Growth Catalysts
- Regulatory Frameworks:Guidance from the FDA and EMA clarifying clinical trial endpoints for lean body mass and physical function provides a clearer development pathway for new therapeutics, de-risking investment.
- Rising Cancer Incidence:An increasing prevalence of cancers with a high cachexia burden, particularly pancreatic and lung cancer, creates a sustained clinical need for effective interventions.
- Multi-Modal Treatment Adoption:The clinical validation of combining pharmacological agents with specialized nutritional support and physical therapy is expanding the therapeutic toolkit and improving patient outcomes.
Market Restraints
- Syndrome Heterogeneity:The complex and variable interplay of inflammatory cytokines, metabolic abnormalities, and reduced intake among patients makes developing a single, universally effective drug exceptionally difficult.
- Clinical Trial Hurdles:The requirement by regulators to demonstrate improvements in both weight and physical function sets a high efficacy bar that many single-agent therapies fail to meet.
- High Development Costs:The expense associated with long-term oncology trials, coupled with the inherent risks of drug development, acts as a significant financial barrier, particularly for smaller biotech firms.
Strategic Opportunities
- Emerging Geographic Markets:Expanding access to advanced cancer care in Asia-Pacific and Latin American countries presents an opportunity for market entry as healthcare infrastructure and reimbursement systems mature.
- Digital Health Integration:The convergence of pharmacological treatments with wearable technology for remote monitoring of physical activity and muscle mass offers a new frontier for personalized cachexia management.
- Indication Expansion:Leveraging research on muscle-wasting mechanisms from cancer cachexia to develop treatments for sarcopenia in other chronic conditions, such as COPD or heart failure, opens adjacent markets.
Industry Challenges
- Patient Recruitment Complexity:Enrolling and retaining patients in clinical trials is challenging due to the severe illness and frailty of the target population, often leading to delays and increased costs.
- Biomarker Standardization:A lack of universally accepted and validated biomarkers to diagnose, stage, and monitor cachexia complicates trial design and hampers the development of targeted therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Cachexia Market |
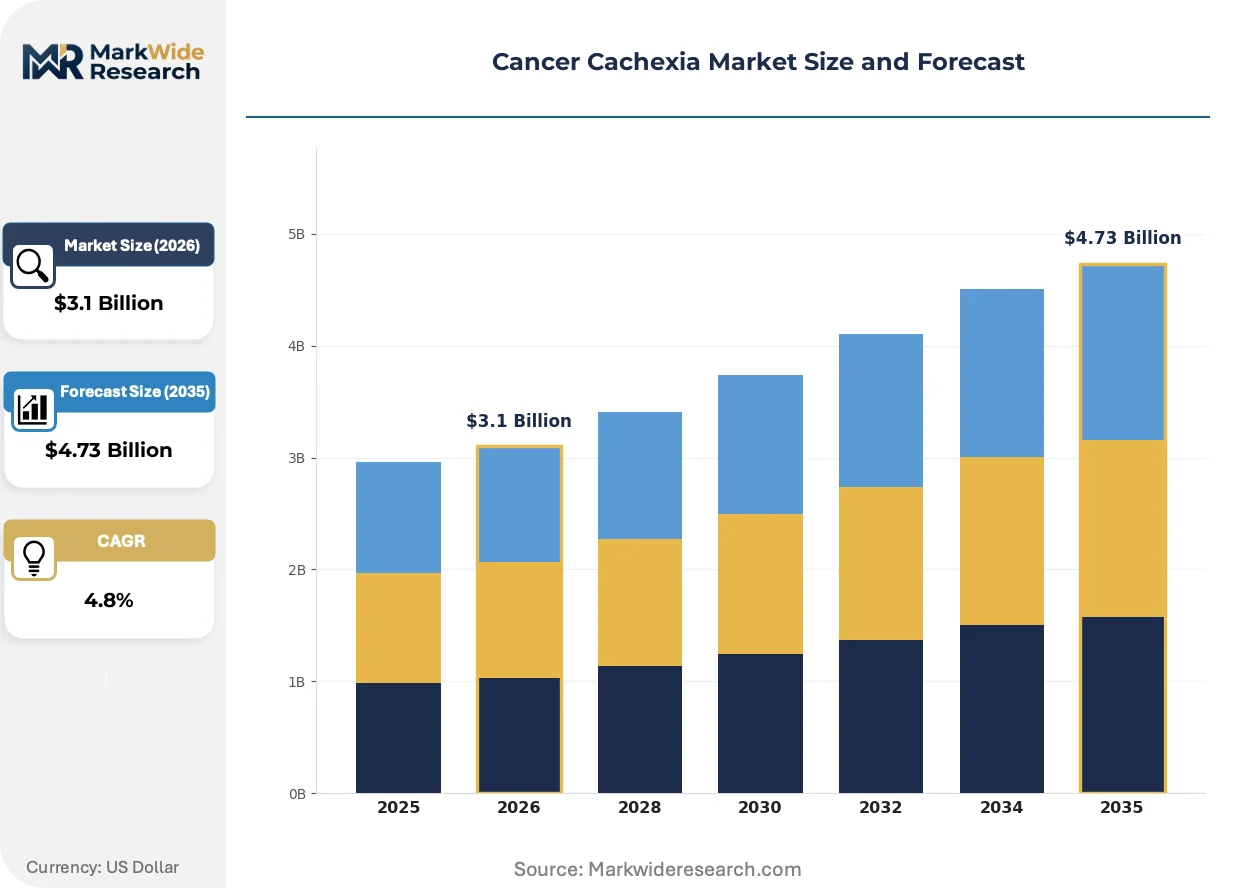
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacological Treatments, Nutritional Supplements, Biologic Agents, Appetite Stimulants, Anti-inflammatory Drugs Therapy Area: Non-Small Cell Lung Cancer, Pancreatic Cancer, Gastric Cancer, Colorectal Cancer, Head & Neck Cancer Care Setting: Hospitals, Home Care, Specialized Clinics, Hospice Facilities, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular, Transdermal |
| Companies Covered | Pfizer Inc., AbbVie Inc., Bristol-Myers Squibb Company, Helsinn Group, Merck & Co. Inc., Teva Pharmaceutical Industries Ltd., Actimed Therapeutics, Novartis, Ono Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Cachexia Market Strategic Shifts & Innovations
The market is evolving from a singular focus on appetite stimulation toward developing sophisticated interventions targeting the underlying metabolic and inflammatory drivers of muscle wasting. This pivot is redefining the therapeutic landscape and creating new standards for clinical efficacy.
Multi-target therapies that simultaneously address inflammation, metabolic dysfunction, and appetite are a key product evolution. Specialized biopharmaceutical firms are rapidly adopting this approach in their pipelines to create more effective treatments. This integrated strategy is absorbing the limitations of single-mechanism drugs, offering a more comprehensive way to manage the syndrome's complexity.
Guidance from regulatory bodies like the EMA on co-primary endpoints of body weight and physical function is a critical policy shift. This directive compels developers to prove a tangible quality-of-life benefit, moving beyond simple weight gain metrics. Consequently, companies targeting the European market are integrating patient-reported outcomes and functional tests into earlier stages of their clinical programs.
A transition toward integrated, multidisciplinary care teams is changing how cachexia is managed within oncology practices. This model distributes treatment responsibility across oncologists, dietitians, and physical therapists, disrupting traditional, single-prescriber patterns. The collaborative approach is most visible within comprehensive cancer centers in the United States and Western Europe, promoting a more holistic patient management philosophy.
Cancer Cachexia Market Segmentation
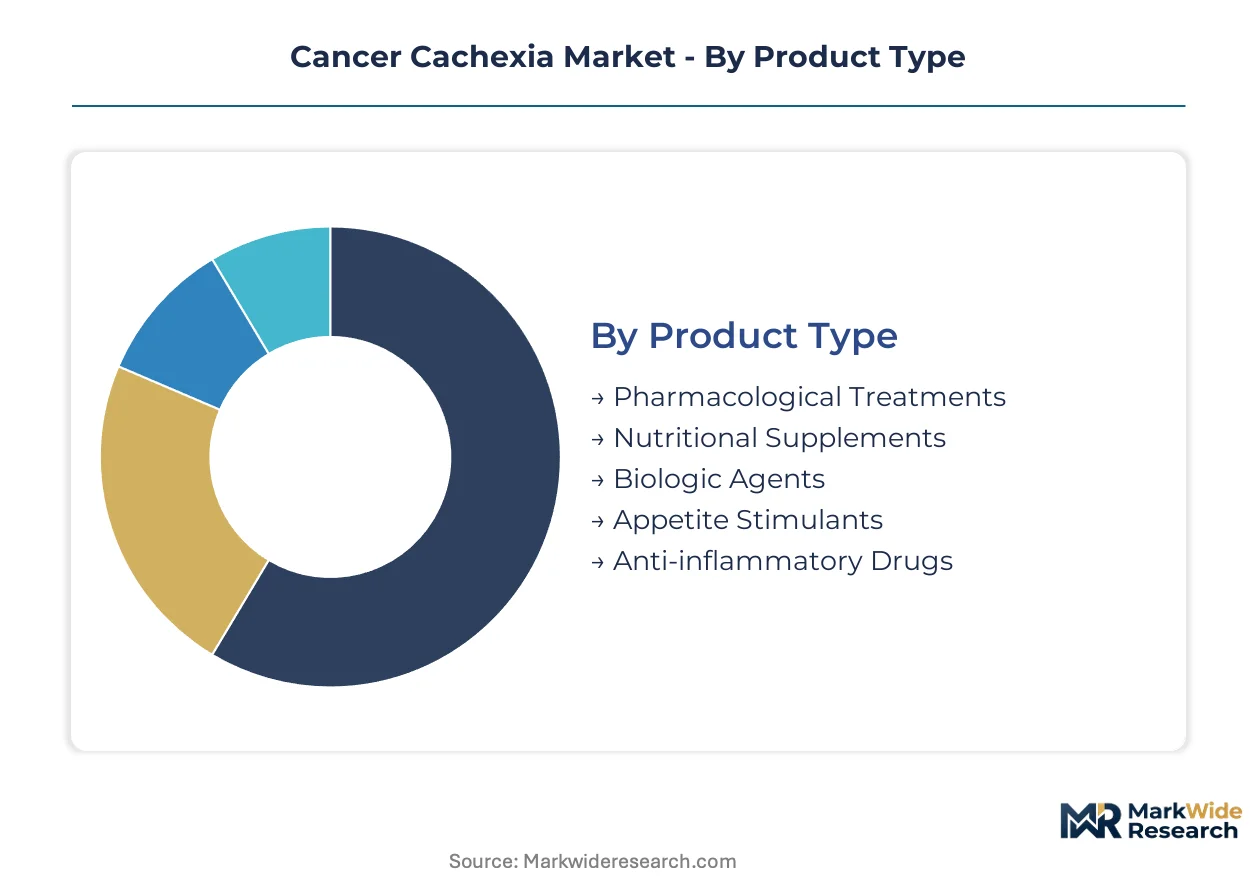
Understanding the varied approaches to managing cancer cachexia requires a detailed segmentation of the market. This breakdown reveals where development efforts are concentrating and how different interventions address the multifactorial nature of the syndrome, from specific product types to patient care settings.
Product Type:
The supply of cachexia treatments concentrates heavily on established pharmacological agents and emerging biologic therapies. These product types address distinct aspects of the syndrome's progression.
- Pharmacological Treatments:These interventions encompass a wide range of synthetic drugs designed to modulate metabolic pathways or reduce inflammation. Demand for these treatments is significant in developed markets like the United States, driven by their established efficacy and physician familiarity.
- Biologic Agents:This segment includes complex, large-molecule drugs derived from living organisms, often targeting specific inflammatory cytokines or growth factors. Investment in novel biologic agents is accelerating, particularly for patients with advanced cancer and severe muscle wasting, offering new therapeutic avenues.
- Nutritional Supplements:These products provide essential macronutrients and micronutrients to support patient energy and protein needs.
- Appetite Stimulants:Medications in this category aim to increase food intake by acting on central nervous system pathways.
- Anti-inflammatory Drugs:These agents work to reduce systemic inflammation, a key driver of cachexia progression.
Pharmacological treatments absorb the bulk of installed capacity; biologic agents are expanding most quickly.
Therapy Area:
The application of cachexia treatments varies significantly across different cancer types, reflecting unique disease pathologies and patient needs.
- Pancreatic Cancer:Patients with pancreatic cancer frequently experience severe cachexia early in their disease course, necessitating aggressive and early intervention. Therapies for this indication see high utilization across global oncology centers, particularly in regions with high incidence rates.
- Non-Small Cell Lung Cancer:Cachexia is a prevalent and debilitating complication in non-small cell lung cancer, impacting treatment tolerance and survival. Demand for effective treatments is growing as diagnostic capabilities improve and patient life expectancy extends.
- Gastric Cancer:Cachexia significantly impacts quality of life and prognosis for individuals with gastric cancer.
- Colorectal Cancer:Management of cachexia in colorectal cancer patients focuses on improving nutritional status and functional independence.
- Head & Neck Cancer:Patients with head and neck cancers often face severe eating difficulties, making cachexia a critical concern.
Pancreatic cancer treatments demonstrate significant utility, while interventions for non-small cell lung cancer are gaining traction.
Care Setting:
The patient care environment dictates the type and intensity of cachexia management, influencing the distribution of products and services.
- Hospitals:Acute care hospitals serve as primary hubs for initial diagnosis, intensive management, and intravenous therapies for cachexia. These settings provide comprehensive multidisciplinary support for severely debilitated patients, particularly in urban centers.
- Home Care:Home care services offer continuous support and monitoring for cachexia patients in their own environments, emphasizing convenience and quality of life. The increasing adoption of digital health tools enhances remote monitoring and personalized nutritional guidance in this setting.
- Specialized Clinics:These outpatient facilities focus on specific aspects of cancer care, including dedicated cachexia management programs.
- Hospice Facilities:Hospice care provides palliative support for advanced cancer patients, with cachexia management focused on comfort and symptom alleviation.
- Rehabilitation Centers:These centers offer physical therapy and nutritional support to improve functional status and muscle strength in recovering patients.
Hospitals remain central to acute care; home-based solutions are increasingly critical for continuous patient management.
Delivery Mode:
The method of drug administration impacts patient compliance, efficacy, and the overall treatment experience, driving preferences in clinical practice.
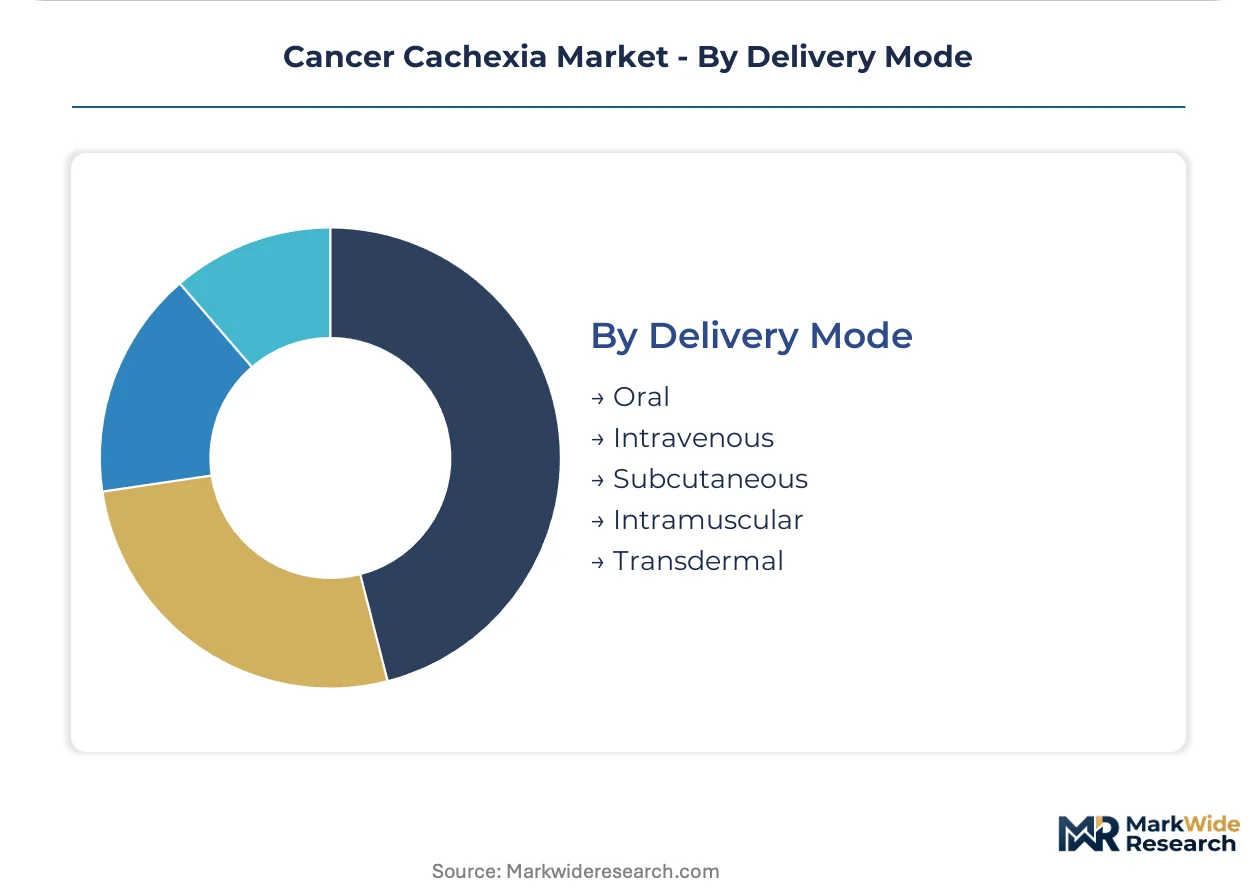
- Oral:Oral formulations offer convenience and ease of administration, making them suitable for long-term management and home-based care. This mode is preferred for many pharmacological treatments due to patient comfort and reduced need for clinical visits.
- Intravenous:Intravenous delivery ensures rapid systemic absorption and precise dosing, critical for acute symptom management or when oral intake is compromised. This mode is commonly used in hospital settings for biologic agents and certain pharmacological therapies.
- Subcutaneous:Subcutaneous injections provide a less invasive alternative to intravenous delivery, often suitable for self-administration.
- Intramuscular:Intramuscular injections are used for specific medications requiring slower absorption rates or larger volumes than subcutaneous routes.
- Transdermal:Transdermal patches offer continuous drug delivery through the skin, providing a non-invasive option for certain therapeutic agents.
Oral administration dominates for patient convenience, while intravenous delivery ensures rapid systemic effects in critical situations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its advanced healthcare infrastructure and high incidence of cancer, anchors the global demand for cancer cachexia treatments. This region drives significant research and development efforts, influencing therapeutic innovation worldwide. Other developed and emerging economies also contribute to the market, driven by specific demographic and healthcare system attributes.
United States
High cancer incidence rates and a robust oncology research ecosystem drive demand for cachexia therapies. The FDA's clear clinical trial endpoint requirements for physical function provide a defined development pathway. Biotech clusters in Boston and the San Francisco Bay Area actively pursue novel therapeutic mechanisms.
Germany
A sophisticated healthcare system and a significant patient population with cancer contribute to market growth. The European Medicines Agency (EMA) guidance on co-primary endpoints influences drug development for this region. Pharmaceutical research hubs in Munich and Berlin focus on advanced pharmacological interventions.
Japan
Japan's aging demographic and high prevalence of certain cancers necessitate effective cachexia management. The Pharmaceuticals and Medical Devices Agency (PMDA) sets rigorous standards for drug approval, impacting market access. Major pharmaceutical companies in Tokyo and Osaka invest in specialized therapeutic development.
India
Expanding healthcare infrastructure and a rising cancer burden are increasing the utilization of cachexia treatments. The Central Drugs Standard Control Organization (CDSCO) regulates the approval and distribution of pharmaceutical products. Hyderabad and Bengaluru serve as key centers for pharmaceutical manufacturing and clinical research.
Brazil
Growing access to advanced cancer care and an expanding patient base create a developing market for cachexia interventions. ANVISA, Brazil's health regulatory agency, governs drug market entry and safety. Oncology treatment centers in São Paulo and Rio de Janeiro are adopting new management protocols.
Cancer Cachexia Market Key Industry Players
Established producers occupy the standard tier, providing widely adopted pharmacological agents; emerging entrants pursue novel biologic agents and multi-modal strategies. The market structure features a mix of large pharmaceutical corporations and specialized biopharmaceutical firms. Strategic partnerships for drug development and targeted acquisitions of promising pipelines represent dominant competitive moves.
Specialists in supportive cancer care include Helsinn Group, which leverages its established portfolio to address patient needs. Actimed Therapeutics exemplifies a focused approach, concentrating on developing drugs specifically for muscle wasting. Bristol-Myers Squibb Company represents a large oncology player, integrating cachexia treatment into a holistic cancer care framework.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Helsinn Group |
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Actimed Therapeutics |
| Novartis |
| Ono Pharmaceutical |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized API manufacturing anchors both the supply position and the pricing power for complex biologic agents in the cancer cachexia market.
Pricing Analysis
Value-based pricing, often bundled with patient support programs, dominates the advanced cancer cachexia market. Price differentiation stems from demonstrated clinical efficacy in improving physical function and specific regulatory approvals like FDA or EMA. Pricing pressure stems from the high development costs of novel multi-target therapies, particularly for smaller biopharmaceutical firms. Public health systems and payers exhibit higher price sensitivity compared to private insurance or out-of-pocket payments for life-extending treatments.
Supply Chain Analysis
Active pharmaceutical ingredient (API) supply for cancer cachexia treatments primarily draws from manufacturing hubs in the United States, Germany, and India. The supply chain relies on specialized excipients and complex biologics manufacturing capacity. Single-source vulnerability for proprietary biologic agents represents a significant structural risk. Distribution runs through a network of hospital pharmacies, specialized oncology clinics, and increasingly, home care providers for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cancer cachexia market presents a consolidation play, driven by the intense regulatory scrutiny and high development costs forcing weaker players out.
For Market Incumbents:Acquire specialized early-stage pipelines targeting novel mechanisms of action to diversify product portfolios. Expand global clinical trial networks to meet evolving regulatory requirements from bodies like the FDA and EMA for physical function endpoints. Leverage existing oncology expertise to integrate cachexia treatments into comprehensive cancer care packages. This strategy helps mitigate the threat from new multi-modal therapeutic approaches.
For New Entrants and Emerging Players:A price-point gap exists for accessible, effective interventions for patients in emerging markets with less developed reimbursement structures. Target underpenetrated indications like gastric or colorectal cancer cachexia with novel, cost-effective pharmacological treatments. Focus on developing therapies with clear, measurable improvements in patient-reported outcomes for physical function. A direct-to-clinic go-to-market strategy in specialized oncology centers offers a path to initial market penetration.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquisitions by large pharmaceutical companies seeking to expand their supportive care portfolios. Invest in biopharmaceutical firms developing multi-target therapies with strong clinical data for lean body mass preservation and functional improvement. Long-term viability hinges on successful navigation of stringent regulatory pathways and clear differentiation in a competitive landscape. The signal to watch is the successful completion of Phase 3 trials demonstrating functional endpoints.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel therapeutic candidates, expanding treatment options. |
| Targeted Pipeline Acquisition | Diversifies product portfolios and strengthens market position against emerging threats. |
| Multidisciplinary Care Integration | Enhances patient outcomes by combining pharmacological, nutritional, and physical interventions. |
| Biomarker Development Investment | Improves diagnostic accuracy and enables personalized treatment strategies for patients. |
| Emerging Market Entry | Captures new patient populations and expands geographic footprint for cachexia therapies. |
Research Approach
Multi-period observation of clinical trial outcomes and regulatory guidance anchored the trend analysis, supplemented by interviews with oncology key opinion leaders, clinical researchers, and pharmaceutical R&D executives. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov databases, and specialized medical journals. The analysis triangulated insights from both bottom-up market sizing and top-down industry trend assessment.
The segment-weighting approach informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, therapy area, care setting, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates were derived using historical data extrapolation and expert consensus projections. Forecast inputs included cancer incidence rates and therapeutic approval timelines.
Inputs from regulatory bodies and clinical trial registries were available through the study window; gaps in real-world evidence for specific patient populations introduce uncertainty bands. Forecasts reflect assumptions regarding future regulatory approvals and treatment paradigm shifts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Hadron Therapy Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Vulvar Cancer Market
Oncology
AI in Oncology Market
Oncology
Bone Cancer Treatment Market
Oncology
Lung Cancer Treatment Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Tumor Embolization Market
Oncology
Pancreatic Cancer Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Europe Proton Therapy Market
Oncology
Colorectal Cancer Screening Market